
 RAN Analytics and Monitoring Market | 2026-2036
RAN Analytics and Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
RAN Analytics and Monitoring Market Analytics
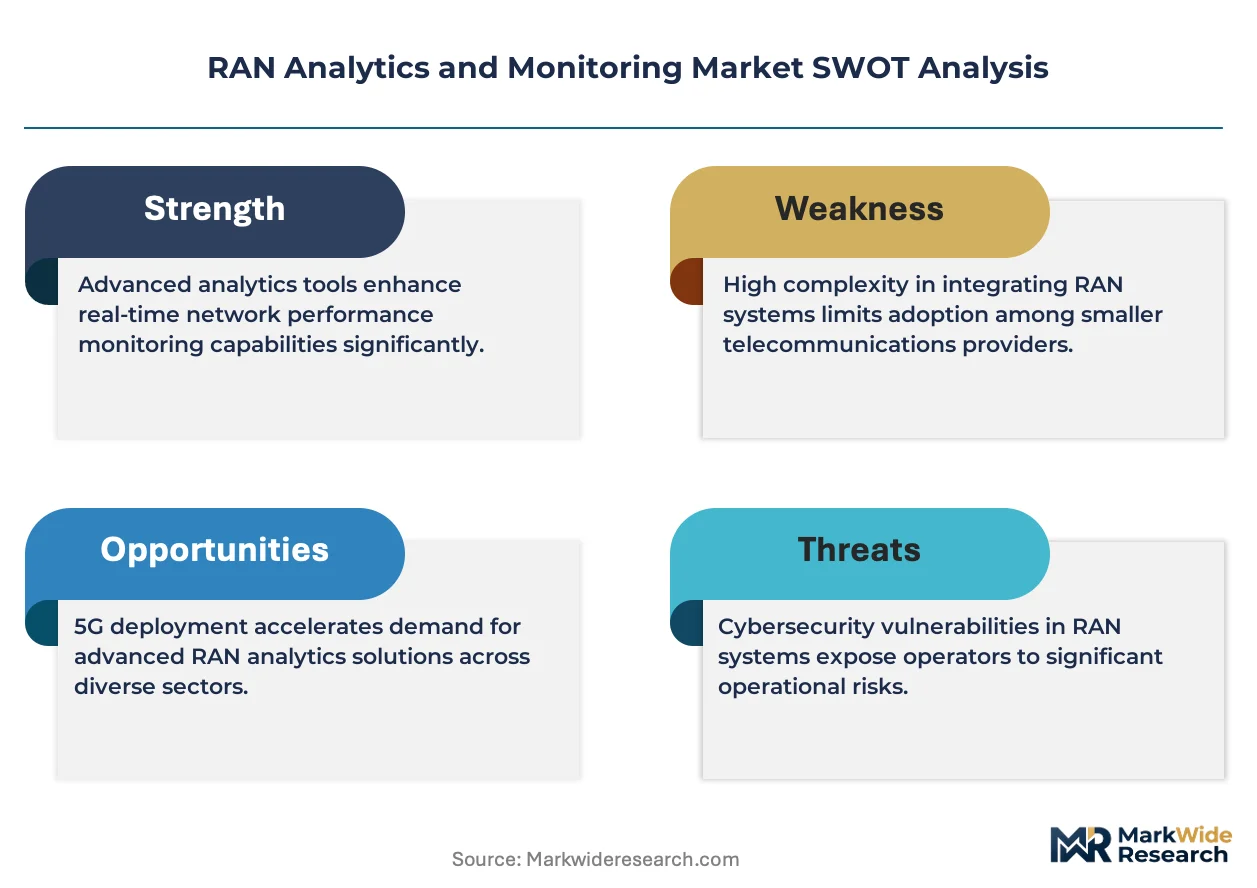
Telecom infrastructure vendors in Northern Europe are recalibrating their software-centric roadmaps to capture RAN intelligence contracts. Ericsson leverages its cloud-native orchestration stack to sustain multi-vendor interoperability leadership. Nokia anchors its position through deep partnerships with European operators pursuing Open RAN disaggregation. Huawei Technologies competes aggressively on AI inference latency for real-time radio resource management, though its geographic reach faces structural constraints.
RAN analytics and monitoring encompasses the collection, processing, and visualization of radio access network telemetry to optimize spectral efficiency, predict equipment failures, and automate capacity scaling across distributed baseband and radio units. The discipline integrates streaming data from gNodeBs, RRUs, and centralized units through protocols such as ETSI MANO and 3GPP TS 28.532, feeding machine learning pipelines that generate actionable network intelligence. Cloud-based deployment models are capturing the fastest expansion as operators seek elastic compute for sporadic traffic surges, while on-premise installations retain dominance among tier-one carriers with stringent data sovereignty requirements. Network optimization applications command the deepest margin pools because they directly correlate with capital efficiency and customer experience metrics that operators prioritize in procurement cycles.
The Federal Communications Commission in the United States mandates network reliability reporting that compels operators to maintain granular RAN observability, while the European Telecommunications Standards Institute drives Open RAN interface specifications that standardize monitoring data formats across vendors. Japan's Ministry of Economy, Trade and Industry coordinates 5G-Advanced testbeds where real-time analytics performance serves as a de facto qualification criterion for domestic supplier selection. Stakeholders must weigh the trade-off between proprietary AI model accuracy and interoperability commitments as regulatory frameworks on both sides of the Atlantic harden around vendor-neutral RAN architectures.
Market Dynamics
AI-driven automation is compressing decision cycles across radio access networks, forcing vendors to rearchitect analytics platforms for sub-millisecond inference latency while operators demand predictive capabilities that preempt congestion before subscriber experience degrades.
Growth Catalysts
- EU AI Act:Compliance mandates for automated network management systems are accelerating procurement of explainable AI frameworks that document decision logic for regulatory audits.
- 5G-Advanced spectrum efficiency:New radio interface specifications require granular telemetry collection that expands addressable monitoring infrastructure across distributed antenna systems.
- South Korea:Domestic operators deploying at-scale testbeds for real-time RAN intelligence are establishing procurement templates that neighboring markets emulate.
Market Restraints
- Specialized silicon shortages:Supply concentration for AI inference accelerators in Taiwan and South Korea creates procurement bottlenecks for edge-deployed analytics appliances.
- Data sovereignty fragmentation:Divergent national cloud localization requirements force redundant infrastructure deployment that dilutes platform economics.
- Legacy radio unit incompatibility:Pre-5G baseband hardware lacks standardized telemetry interfaces, constraining unified analytics coverage.
Strategic Opportunities
- India:TRAI spectrum efficiency directives and domestic manufacturing incentives under the PLI scheme create first-mover advantages for localized analytics platforms.
- Open RAN interface convergence:Integration of O-RAN Alliance specifications with 3GPP release timelines enables multi-vendor analytics orchestration previously locked to single-supplier stacks.
- Energy-optimized network operations:Grid stability mandates in Germany and France position AI-driven power management as a compliance-driven procurement criterion.
Industry Challenges
- RF engineering talent scarcity:The intersection of radio frequency expertise and machine learning operations remains critically undersupplied across operator engineering teams.
- Cross-vendor integration complexity:Proprietary data formats from incumbent radio suppliers resist standardization, forcing costly middleware development for unified visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RAN Analytics and Monitoring Market |
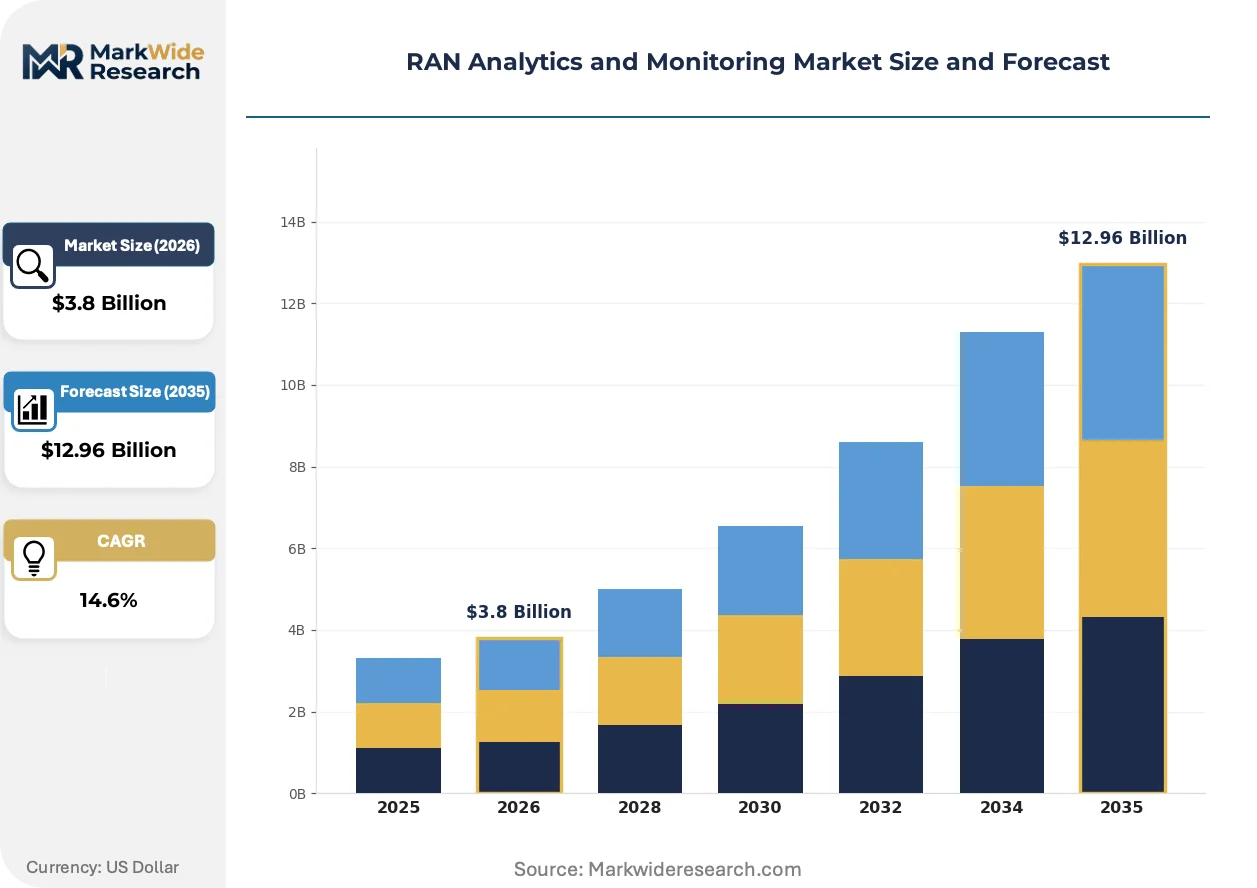
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Mobile Network Operators, Network Service Providers, Managed Service Providers, Enterprises Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: Machine Learning, Artificial Intelligence, Data Analytics, IoT Application: Network Optimization, Performance Monitoring, Fault Management, Capacity Planning |
| Companies Covered | Ericsson, Nokia, Huawei Technologies, ZTE Corporation, Samsung Electronics, Cisco Systems, VIAVI Solutions, Keysight Technologies, NetScout Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RAN Analytics and Monitoring Market Evolving Landscape
Telemetry processing architectures are migrating from centralized data lakes toward edge-native streaming pipelines that collapse latency budgets for real-time radio resource allocation decisions.
Intent-based network management is overtaking rule-based configuration systems across tier-one carrier operations. Ericsson and Nokia are embedding declarative policy engines that translate high-level service objectives into automated parameter tuning. This compression of operational abstraction layers is overtaking traditional network operations center workflows that required manual intervention for congestion response.
The EU AI Act's risk classification framework for automated decision systems imposes documentation burdens on AI-driven RAN optimization platforms. European operators must maintain algorithmic audit trails that explain automated handover decisions to national regulators. Vendors serving German and French markets are restructuring model architectures to satisfy explainability requirements that diverge from performance-optimized black-box alternatives.
Subscription-based analytics licensing is displacing perpetual software purchases among capital-constrained mobile operators. Japanese carriers under METI coordination are piloting usage-metered contracts that align vendor compensation with measured spectral efficiency gains. This consumption model rotation is most visible in South Korea, where Samsung Electronics and domestic operators structure partnerships around outcome-indexed payments rather than upfront platform fees.
RAN Analytics and Monitoring Market Segmentation
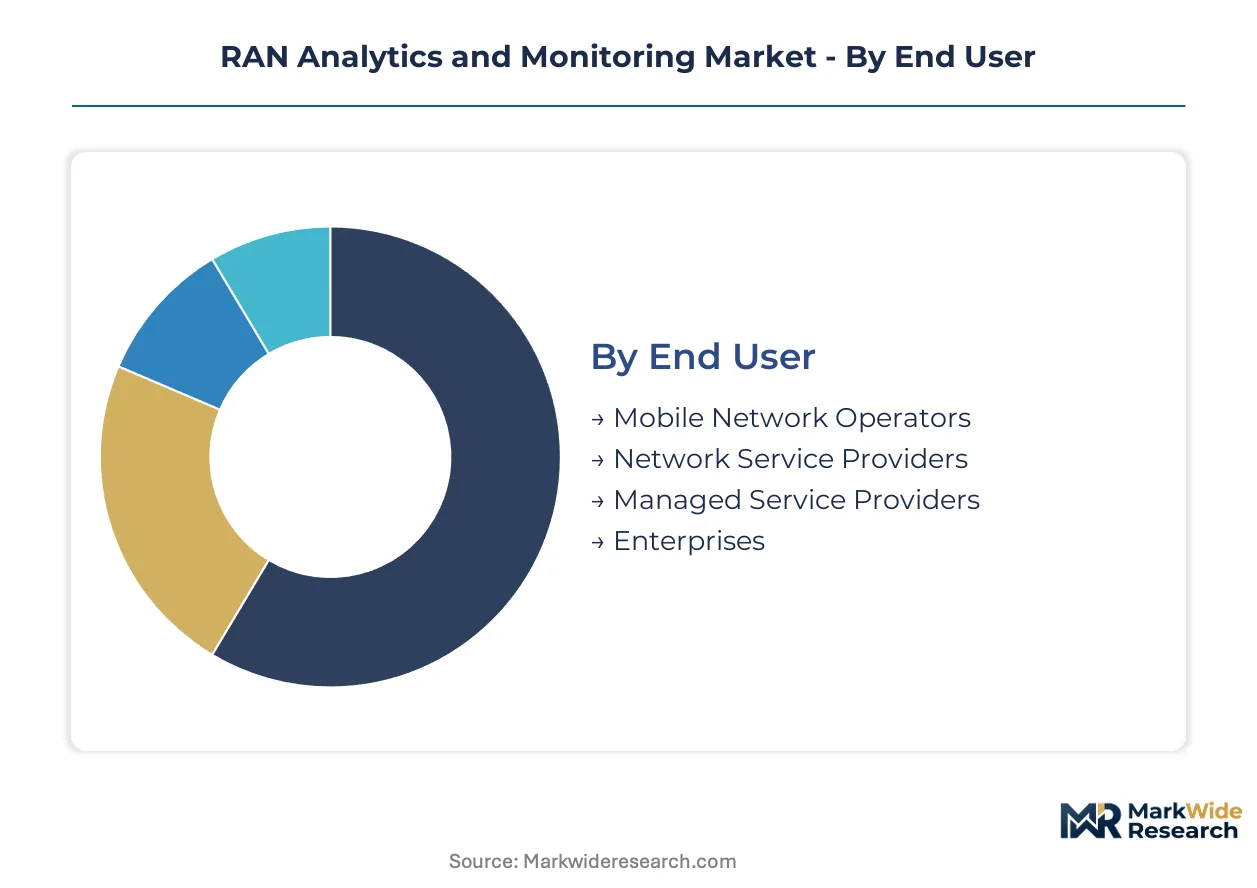
RAN analytics and monitoring segments diverge sharply in compliance exposure and procurement complexity. Mobile operators face ETSI MANO certification requirements that managed service providers circumvent through shared infrastructure models. Deployment architecture choices determine whether systems fall under EU AI Act algorithmic audit mandates or escape via edge-localized processing.
End User:
Mobile Network Operators carry the heaviest certification burden under FCC reliability mandates and EU AI Act risk classifications, while Enterprises navigate lighter B2B software procurement standards.
- Mobile Network Operators:Tier-one carriers deploy comprehensive telemetry stacks spanning gNodeB clusters to centralized units, driven by FCC network reliability reporting requirements that compel granular observability across distributed radio infrastructure. Procurement concentrates in Germany and France where spectrum efficiency mandates from national regulators accelerate AI-driven optimization platform adoption.
- Network Service Providers:Wholesale infrastructure operators aggregate multi-tenant analytics across carrier-neutral facilities, with demand clustering in South Korea where Samsung Electronics and domestic operators establish procurement templates for real-time RAN intelligence architectures that neighboring markets emulate.
- Managed Service Providers:Outsourced operations teams leverage standardized toolsets across heterogeneous vendor environments.
- Enterprises:Private 5G campus networks require localized monitoring without carrier-grade regulatory exposure.
Mobile Network Operators sit at the top of the volume ranking, with Enterprises climbing the fastest as private network deployments proliferate.
Deployment Model:
Cost tier stratification separates sovereign-cloud premiums from commodity edge hardware, with hybrid architectures capturing mid-budget operators seeking staged migration paths.
- On-Premise:Tier-one carriers with stringent data sovereignty requirements retain dominance through captive data centers feeding machine learning pipelines, constrained by specialized silicon procurement bottlenecks for AI inference accelerators concentrated in Taiwan and South Korea.
- Cloud-Based:Elastic compute models capture fastest expansion as operators seek sporadic traffic surge capacity without stranded capital, though divergent national cloud localization requirements force redundant infrastructure deployment that dilutes platform economics.
- Hybrid:Staged workload migration appeals to capital-constrained operators balancing legacy on-premise investments against cloud-native orchestration.
- Edge Computing:Sub-millisecond inference latency demands drive radio unit co-location with analytics appliances.
On-Premise deployments retain the largest installed base, with Edge Computing gaining share fastest as 5G-Advanced radio interfaces mandate real-time processing.
Technology:
Application maturity determines which technology layers absorb the deepest R&D investment, with AI inference engines commanding premium pricing against commoditized data visualization modules.
- Machine Learning:Predictive maintenance algorithms processing ETSI MANO telemetry streams dominate procurement cycles, with European operators under EU AI Act compliance mandates restructuring model architectures to satisfy explainability requirements that diverge from performance-optimized black-box alternatives.
- Artificial Intelligence:Real-time radio resource management systems compete on inference latency metrics, though RF engineering talent scarcity at the intersection of radio frequency expertise and machine learning operations constrains deployment velocity across operator engineering teams.
- Data Analytics:Visualization and reporting layers standardize around 3GPP TS 28.532 protocol implementations.
- IoT:Sensor fusion from distributed antenna systems expands telemetry collection scope for environmental monitoring.
Machine Learning commands the deepest margin pools, with Artificial Intelligence expanding most quickly as intent-based network management displaces rule-based configuration systems.
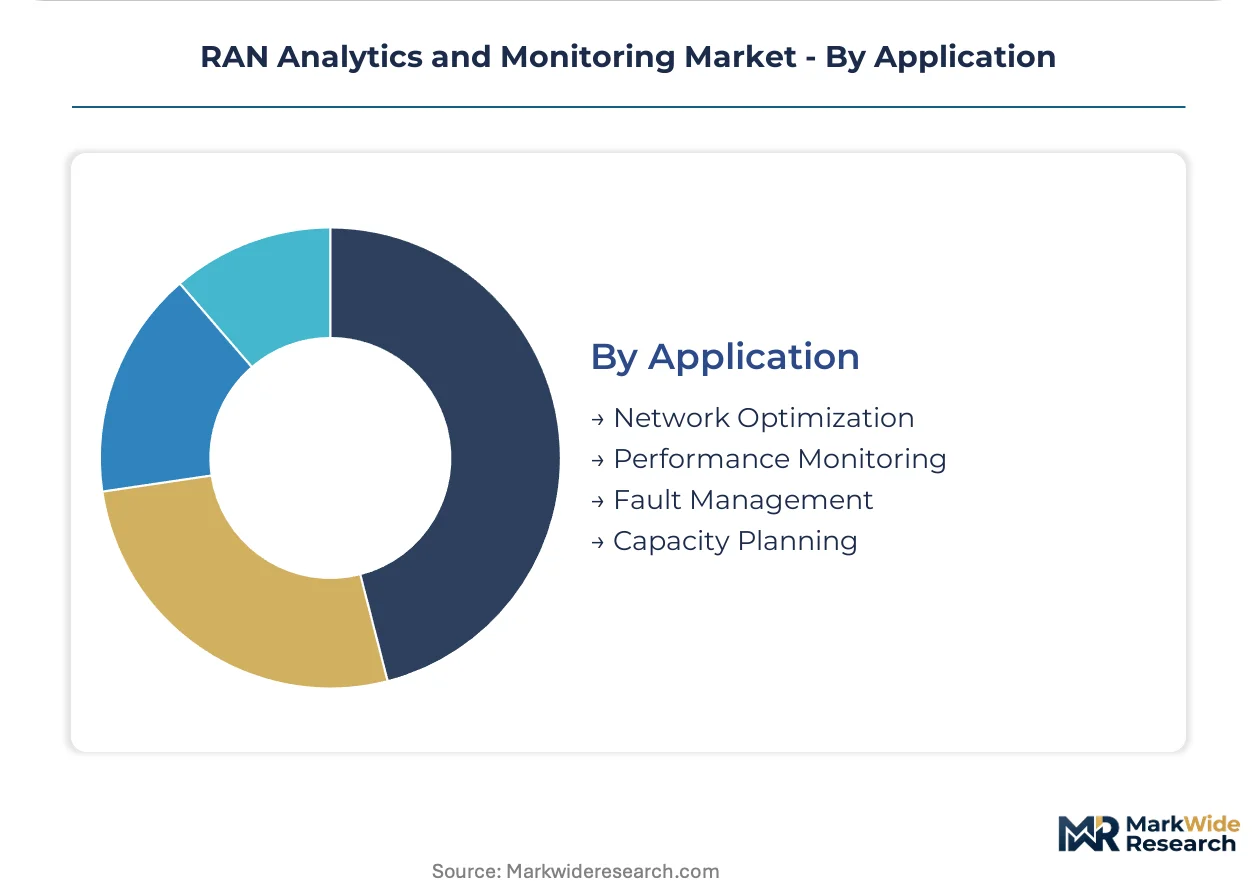
Application:
Customer-type differentiation separates procurement funded by capital efficiency mandates from operational budgets targeting subscriber experience protection.
- Network Optimization:Direct correlation with spectral efficiency gains and customer experience metrics positions this application at the apex of vendor pricing power, with Japanese carriers under METI coordination piloting usage-metered contracts that align vendor compensation with measured outcomes rather than upfront platform fees.
- Performance Monitoring:Real-time KPI dashboards feed network operations center workflows across tier-one carriers, with South Korean domestic operators deploying at-scale testbeds that establish real-time analytics performance as a de facto qualification criterion for supplier selection.
- Fault Management:Automated incident response reduces mean-time-to-repair for distributed baseband unit failures.
- Capacity Planning:Traffic forecasting models preempt congestion before subscriber experience degrades across dense urban clusters.
Network Optimization sits at the top of the volume ranking, with Fault Management climbing the fastest as AI-driven automation compresses decision cycles across radio access networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as compliance costs diverge across jurisdictions. Operators in South Korea and Japan face stricter algorithmic audit mandates than their counterparts in India, prompting technology transfer toward lower-cost compliance environments.
United States
FCC network reliability reporting requirements compel tier-one carriers to maintain granular RAN observability across distributed infrastructure. The Commission's outage reporting mandates accelerate procurement of real-time telemetry platforms. Dense operator clusters in Dallas-Fort Worth and Northern Virginia drive edge computing deployments for sub-millisecond inference latency.
Germany
Spectrum efficiency mandates from the Federal Network Agency force operators to document automated handover decisions for regulatory review. Grid stability requirements position AI-driven power management as a compliance-driven procurement criterion. Industrial automation corridors in Bavaria and Baden-Württemberg anchor private 5G campus network deployments requiring localized monitoring.
South Korea
Domestic operators under METI-coordinated testbeds establish real-time analytics performance as a de facto qualification criterion for supplier selection. Samsung Electronics structures partnerships around outcome-indexed payments rather than upfront platform fees. Seoul Capital Area deployments provide reference architectures that neighboring Asia-Pacific markets emulate.
India
TRAI spectrum efficiency directives and PLI scheme manufacturing incentives create first-mover advantages for localized analytics platforms. Data localization requirements under the Digital Personal Data Protection Act force redundant infrastructure deployment. Telangana and Karnataka host emerging vendor engineering centers serving domestic operator procurement cycles.
Japan
METI coordinates 5G-Advanced testbeds where analytics performance serves as qualification criteria for domestic supplier selection. The ministry's standardization push accelerates Open RAN interface adoption. Kanto and Kansai industrial clusters concentrate private network deployments demanding campus-scale monitoring without carrier-grade regulatory exposure.
RAN Analytics and Monitoring Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native orchestration and edge-localized inference. The vendor base stratifies across three tiers: telecom infrastructure incumbents with captive operator relationships, test and measurement specialists with RF domain expertise, and cloud-centric entrants leveraging elastic compute models. Dominant competitive moves include strategic partnerships for multi-vendor interoperability and portfolio diversification into intent-based network management platforms.
Among telecom infrastructure incumbents, Ericsson and Nokia exemplify contrasting geographic positioning strategies. Huawei Technologies occupies a constrained position where regulatory barriers limit addressable markets. Samsung Electronics anchors the Asia-Pacific tier through domestic operator partnerships that establish procurement templates for regional expansion. These three represent distinct archetypes: European multi-region standard-setters, China-origin vendors facing structural market access limitations, and Asia-Pacific specialists leveraging home-market scale for regional export.
| Leading Market Players |
|---|
| Ericsson |
| Nokia |
| Huawei Technologies |
| ZTE Corporation |
| Samsung Electronics |
| Cisco Systems |
| VIAVI Solutions |
| Keysight Technologies |
| NetScout Systems |
| Others |
Value Network & Pricing Analysis
EU AI Act compliance mandates for automated network management systems gate qualified supply to vendors with explainable AI frameworks, restricting premium-tier pricing access to Ericsson and Nokia while forcing Huawei Technologies and ZTE Corporation into discounted positioning in constrained markets.
Pricing Analysis
Distributor margins for RAN analytics platforms compress as direct-to-OEM contracts proliferate among tier-one carriers. Subscription-based SaaS licensing dominates procurement, with price differentiation hinging on ETSI MANO certification tier and edge inference latency guarantees. Pricing pressure intensifies from outcome-indexed payment structures piloted by South Korean operators. Mobile Network Operators exhibit highest price sensitivity due to capital constraints, while Enterprises in private 5G deployments accept premium positioning for localized sovereignty.
Supply Chain Analysis
ETSI MANO and 3GPP TS 28.532 certification requirements gate supplier qualification, filtering component sourcing to Taiwan, South Korea, and Germany for AI inference accelerators, radio unit chipsets, and edge server assemblies. Supply chains draw from specialized silicon foundries, high-bandwidth memory fabricators, and precision RF component manufacturers. Single-source vulnerability concentrates in Taiwan-based AI accelerator production. Distribution runs through telecom infrastructure vendors with captive operator relationships rather than independent channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RAN Analytics and Monitoring Market reads as a late-cycle quality story where procurement templates from South Korea's 5G-Advanced testbeds filter upward toward premium specifications across Asia-Pacific and European deployments.
For Market Incumbents: Anchor multi-vendor interoperability leadership through deeper Open RAN interface certification investments, countering emerging cloud-native entrants threatening orchestration layer margins. Prioritize backward integration into edge AI silicon supply through partnerships with Taiwan and South Korea foundries, mitigating procurement bottlenecks that constrain deployment velocity against Samsung Electronics. For New Entrants and Emerging Players: Launch via consumption-metered contracts aligned with spectral efficiency outcomes, targeting capital-constrained tier-two operators in India under TRAI spectrum efficiency directives. Penetrate the Managed Service Provider segment where standardized toolset requirements favor cloud-native architectures over incumbent proprietary stacks. For Investors and Strategic Acquirers: Valuations sit cheapest among test and measurement specialists with RF domain expertise but limited AI/ML platform integration. Long-term viability centers on vendors bridging radio frequency engineering with machine learning operations capabilities. Monitor EU AI Act enforcement patterns in Germany and France as the inflection signal for explainable AI platform premiums versus black-box discounting.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interface Certification | Enables multi-vendor analytics orchestration previously locked to Ericsson and Nokia single-supplier stacks. |
| Edge AI Accelerator Partnership | Secures sub-millisecond inference latency supply from Taiwan and South Korea foundry capacity. |
| Outcome-Indexed Contracting | Aligns vendor compensation with METI-coordinated spectral efficiency benchmarks in Japanese carrier procurement. |
| Explainable AI Architecture Restructuring | Satisfies EU AI Act algorithmic audit mandates for German and French operator deployments. |
| Private 5G Campus Expansion | Captures enterprise demand localized monitoring without carrier-grade FCC reliability reporting exposure. |
Research Methodology
Multiple input streams — primary interviews with network operations executives, RAN engineering directors, and procurement leads at tier-one carriers; secondary validation through 3GPP specification databases, ETSI MANO certification registries, and FCC outage reporting filings; plus customs data on AI inference accelerator trade flows — were reconciled through bottom-up deployment modeling and top-down market sizing triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation by deployment architecture, end-user category, technology layer, and application function. CAGRs derived from elasticity-adjusted adoption curves incorporating 5G-Advanced radio interface deployment timelines and spectrum efficiency mandate compliance deadlines. Forecast inputs included operator capex disclosure patterns and silicon foundry capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged Taiwan semiconductor supply disruptions. Deviation in Open RAN interface standardization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Mobile App Attribution Tool Market
Analytics
Event Stream Processing Market
Analytics
North America Crowd Analytics Market
Analytics
Global Telecom Analytics Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
Data Analytics Market
Analytics
Data Discovery Market
Analytics
Web Analytics Market
Analytics
Attribution Software Market
Analytics
Latin America Location Analytics Market
Analytics
Digital Analytics Solutions Market
Analytics
Europe Data Monetization Market
Analytics
North America Location Analytics Market
Analytics
Face Analytics Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Big Data Analytics Market