
 Statistical Analytics Market | 2026-2036
Statistical Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
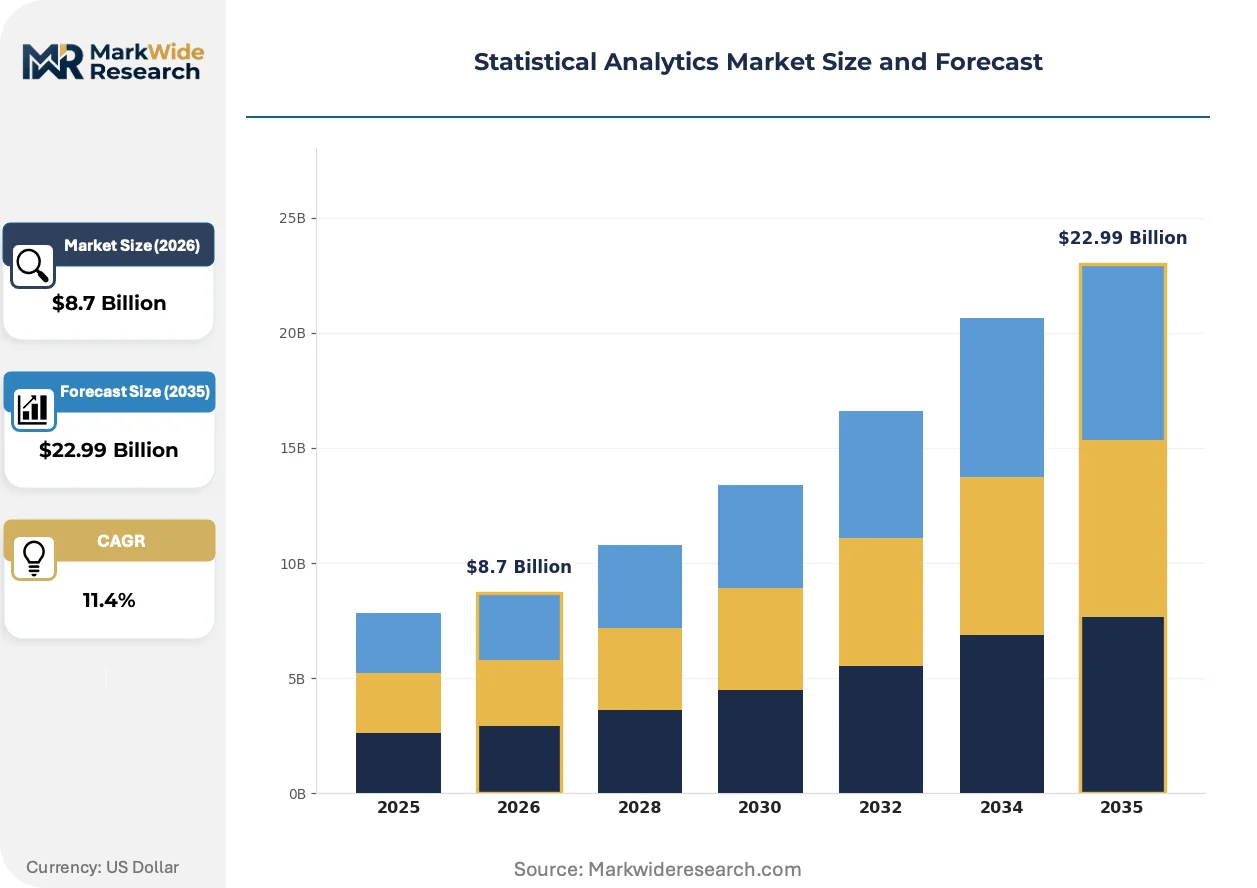
Statistical Analytics Market Outlook
India's expanding data science workforce is reconfiguring how statistical analytics services get delivered to Western enterprises. SAS Institute leverages decades of statistical software heritage to sustain premium positioning in regulated industries. Palantir Technologies anchors government and defense contracts through specialized analytics platforms. IBM competes across the full stack with hybrid cloud deployments that integrate statistical modeling with enterprise data warehouses.
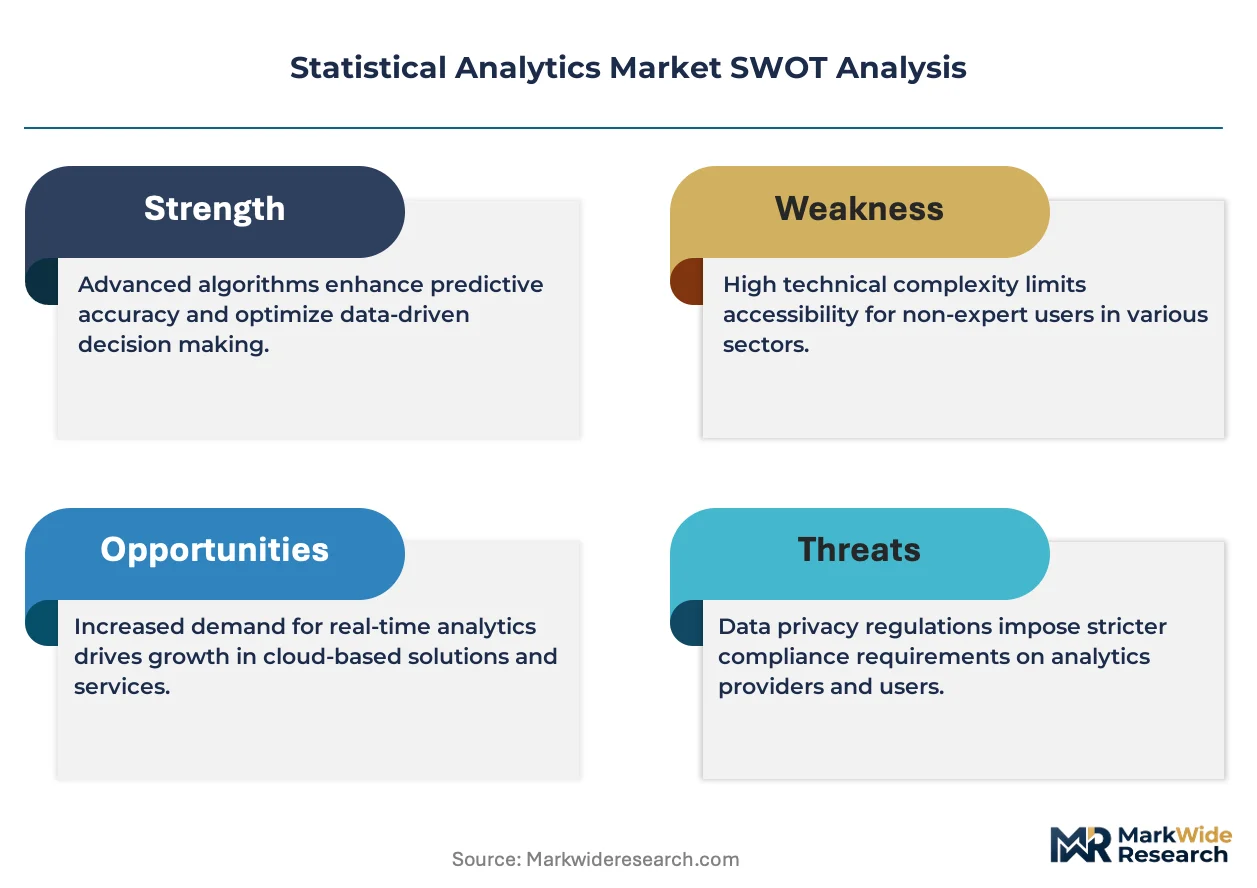
Statistical analytics encompasses the systematic application of mathematical models, probability theory, and computational algorithms to structured and unstructured datasets, typically processing millions of observations through regression, clustering, and time-series methods to generate actionable intelligence. Its primary commercial purpose centers on reducing uncertainty in operational and strategic decisions across risk-laden environments. Predictive analytics commands the largest revenue share as financial institutions deploy credit default models and demand forecasting systems at scale. Cloud-based deployment is expanding fastest among mid-market retailers seeking elasticity without capital-intensive infrastructure commitments. Diagnostic analytics retains concentrated margin pools in healthcare, where root-cause analysis of patient readmissions justifies specialist consulting fees.
FDA guidelines on algorithmic clinical decision support shape product validation requirements for healthcare-facing analytics vendors. HIPAA data handling rules and emerging state-level AI governance bills in California and New York constrain how patient records enter statistical pipelines. The SEC's expanding disclosure expectations around quantitative risk models push financial services firms toward auditable statistical frameworks. Stakeholders must weigh compliance architecture against model agility as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Cloud migration is compressing deployment cycles for statistical analytics platforms as enterprises abandon multi-year on-premises implementation timelines in favor of elastic, consumption-based infrastructure models.
Growth Catalysts
- HIPAA-aligned healthcare analytics:Patient outcome modeling mandates from federal reimbursement programs pull predictive tools into hospital procurement pipelines.
- GPU-accelerated inference:Specialized silicon for probabilistic computation cuts model training costs for mid-market financial services firms.
- India:Bangalore and Hyderabad data science clusters now deliver statistical modeling services to Western enterprises at compressed cost structures.
Market Restraints
- PhD-level talent scarcity:Bayesian modeling and causal inference expertise concentrates in coastal US metros and select European university towns.
- Cloud egress fees:AWS, Azure, and GCP data transfer pricing erodes margins for analytics vendors running multi-tenant architectures.
- FDA validation timelines:Algorithmic clinical decision support tools face 18-36 month approval pathways that freeze product roadmaps.
Strategic Opportunities
- Brazil:ANVISA's nascent digital health framework creates first-mover positioning for validated statistical platforms in Latin America's largest healthcare market.
- Federated learning architectures:Privacy-preserving computation enables cross-institutional modeling without raw data centralization.
- EU AI Act compliance services:Risk classification mandates for high-stakes statistical systems open consulting revenue pools.
Industry Challenges
- Legacy ERP integration:SAP and Oracle data warehouses resist API-native connectivity, forcing custom pipeline development.
- Model drift monitoring:Production statistical systems require continuous recalibration that strains DevOps resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Statistical Analytics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Diagnostic Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Retail, Finance, Manufacturing Application Area: Market Basket Analysis, Risk Management, Forecasting, Customer Segmentation |
| Companies Covered | Deloitte, Palantir Technologies, SAS Institute, Fractal Analytics, Databricks, IBM, McKinsey & Company, Mu Sigma, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Statistical Analytics Market Strategic Shifts
Statistical analytics infrastructure is fragmenting across specialized compute layers as vendors race to optimize for latency-sensitive inference versus batch training workloads.
Automated machine learning (AutoML) platforms are migrating from experimental data science teams into operational business units. Retail demand forecasting teams at mid-market chains now deploy seasonal models without dedicated statistical staff. This compression of expertise requirements is expanding addressable market size while pressuring specialist consulting rates.
The SEC's quantitative risk model disclosure rules are forcing auditable documentation standards across financial services analytics. Model lineage tracking and version control systems now sit beside statistical packages as mandatory procurement criteria. Sell-side institutions are responding by embedding compliance checkpoints directly into model development workflows.
Subscription-based platform licensing is displacing perpetual software sales in enterprise statistical analytics procurement. Healthcare systems prefer OpEx-aligned contracts that bundle compute, storage, and modeling tools. This shift is most pronounced in United States hospital networks navigating constrained capital budgets and uncertain reimbursement trajectories.
Statistical Analytics Market Segmentation
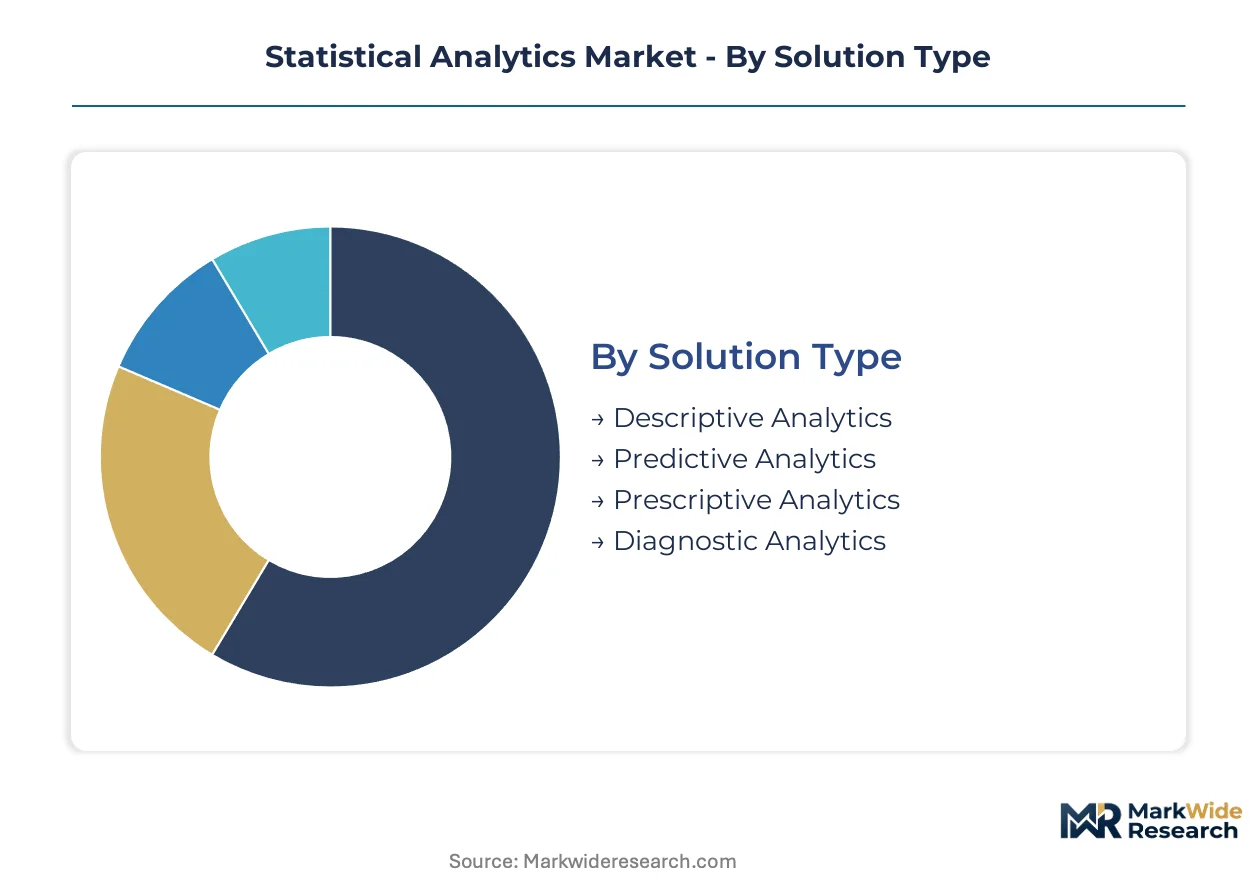
Statistical analytics vendors structure product portfolios around solution maturity, infrastructure flexibility, and vertical specialization. Segmentation reveals where pricing power concentrates and which deployment modes compress sales cycles.
Solution Type:
Mature descriptive tools anchor enterprise renewals while emerging prescriptive platforms command implementation premiums.
- Descriptive Analytics:Retrospective dashboards and historical reporting tools process structured ERP data into variance analyses and operational KPIs. Manufacturing plants in Germany and Japan deploy these systems for OEE tracking and downtime root-cause documentation, with procurement teams favoring bundled BI suites over standalone licenses.
- Predictive Analytics:Probabilistic models—regression, random forests, neural networks—project future states from training datasets. US hospital networks and Brazilian insurers drive demand here, with HIPAA-aligned clinical decision support and ANVISA validation requirements shaping vendor roadmaps.
- Prescriptive Analytics:Optimization engines recommend specific actions through simulation and decision trees. Supply chain teams at discrete manufacturers pilot these for inventory positioning.
- Diagnostic Analytics:Drill-down capabilities isolate causal factors in anomalous outcomes. Healthcare readmission analysis retains specialist consulting margins.
Descriptive analytics retains volume leadership; prescriptive analytics holds the steepest expansion curve.
Deployment Model:
Cost tiers separate capital-intensive ownership from elastic consumption economics.
- Cloud-Based:SaaS delivery of statistical platforms eliminates server procurement and reduces time-to-insight from quarters to weeks. Mid-market retailers across France and the United Kingdom favor this model for seasonal demand forecasting without infrastructure commitments.
- Hybrid:Sensitive data remains on-premises while compute-intensive training workloads burst to public cloud. Financial services firms in Singapore and Switzerland architect around data residency requirements and SEC audit trail mandates.
- On-Premises:Perpetual licenses with dedicated hardware persist in defense and intelligence applications where air-gapped networks are non-negotiable.
- Managed Services:Third-party operation of statistical infrastructure including model monitoring and retraining. Healthcare systems with constrained IT headcount outsource entire analytics stacks.
Cloud-based deployment is gaining share fastest; on-premises retains concentration in regulated defense applications.
End User:
Application sophistication varies sharply across customer types.
- Healthcare:Patient outcome modeling, population health stratification, and clinical trial analytics. FDA 21 CFR Part 11 compliance and EU MDR requirements constrain vendor selection.
- Finance:Credit scoring, algorithmic trading surveillance, and quantitative risk disclosure. Basel III stress testing and SEC model governance rules mandate auditable lineage systems.
- Retail:Demand forecasting, price elasticity estimation, and churn prediction. Seasonal volatility drives preference for elastic infrastructure.
- Manufacturing:Predictive maintenance, quality control SPC, and yield optimization. Industrial IoT sensor integration expands addressable data volume.
Healthcare commands the highest solution premiums; retail is expanding most quickly among cloud-native adopters.
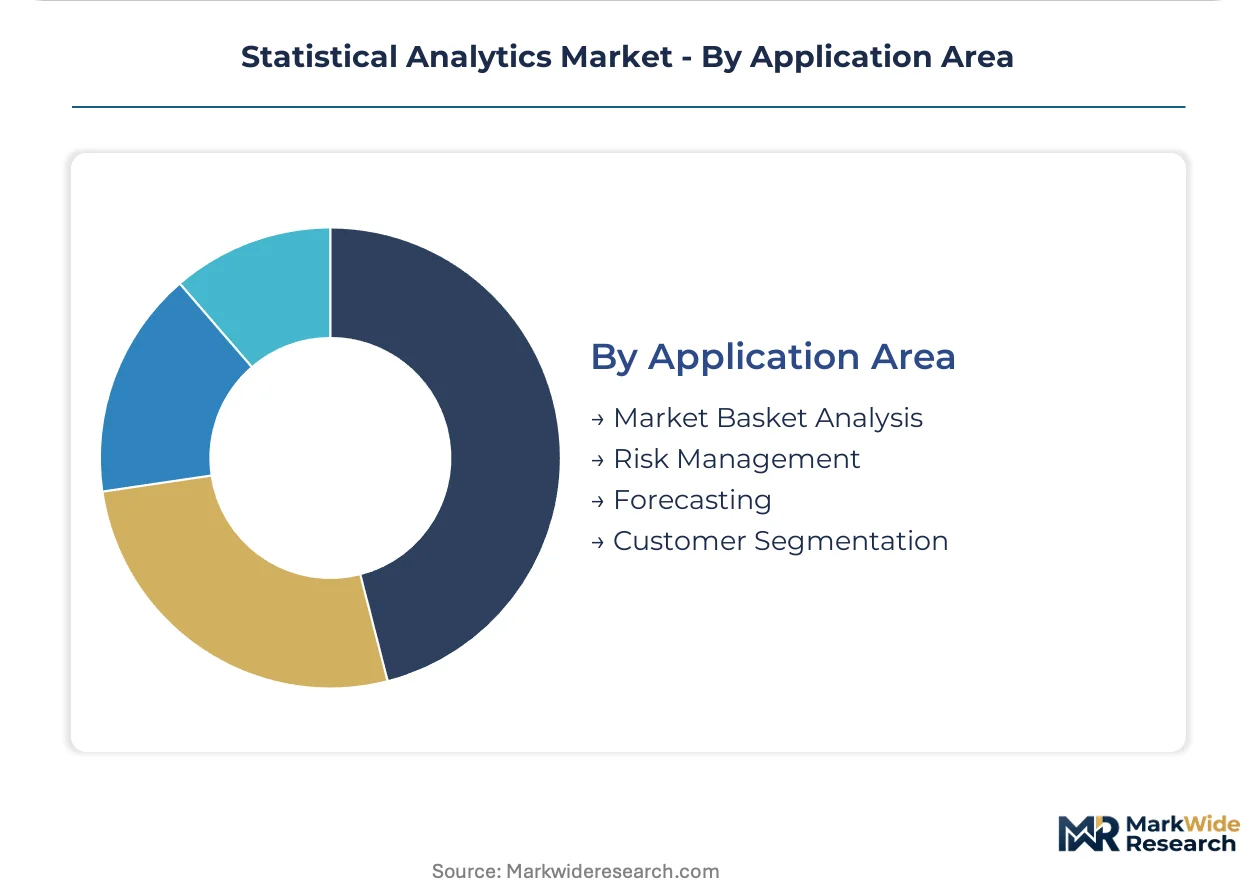
Application Area:
Functional use cases align with specific computational methods and data architectures.
- Risk Management:Value-at-risk calculations, stress scenario modeling, and operational risk quantification. Banks in the United States and United Kingdom deploy Monte Carlo simulations at portfolio scale.
- Forecasting:Time-series methods including ARIMA, Prophet, and LSTM networks project demand, revenue, and resource requirements. Energy traders and consumer goods planners represent core demand.
- Market Basket Analysis:Association rule mining (Apriori, FP-Growth) identifies product affinities for shelf placement and promotional bundling. Grocery chains and e-commerce marketplaces apply these techniques.
- Customer Segmentation:Clustering algorithms partition populations for targeted outreach. Marketing teams in digital-native industries favor RFM and k-means implementations.
Risk management retains the deepest enterprise penetration; forecasting is climbing the fastest as supply chain volatility intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize HIPAA-aligned clinical platforms; German manufacturers favor predictive maintenance suites; Indian enterprises seek cost-optimized cloud deployments.
United States
Federal reimbursement programs mandate patient outcome modeling, pulling predictive tools into hospital procurement pipelines. The FDA's 21 CFR Part 11 validation requirements constrain vendor selection for clinical decision support. Boston and San Francisco data science clusters anchor healthcare analytics development, with Mayo Clinic and Kaiser Permanente piloting federated learning architectures.
Germany
Industrial IoT integration drives demand for predictive maintenance and quality control SPC systems among automotive and machinery producers. The EU AI Act's risk classification mandates push manufacturers toward auditable statistical frameworks. Stuttgart and Munich engineering hubs concentrate Industry 4.0 analytics deployments, with Bosch and Siemens deploying Monte Carlo simulations for supply chain optimization.
India
Bangalore and Hyderabad data science clusters deliver statistical modeling services to Western enterprises at compressed cost structures. The RBI's expanding expectations around quantitative risk models push domestic banks toward auditable frameworks. Mumbai financial services firms and Delhi-NCR IT services exporters represent the fastest-growing cloud-native adopter base.
United Kingdom
Basel III stress testing and SEC-aligned model governance rules mandate auditable lineage systems among London-based sell-side institutions. The FCA's quantitative disclosure expectations force documentation standards across risk management workflows. The City of London and Edinburgh fintech clusters drive demand for GPU-accelerated inference platforms.
Brazil
ANVISA's nascent digital health framework creates first-mover positioning for validated statistical platforms in Latin America's largest healthcare market. Private insurers in São Paulo and Rio de Janeiro deploy credit scoring and demand forecasting systems at scale. The country's national pharmaceutical regulator's evolving guidance shapes product validation requirements for clinical analytics vendors.
Statistical Analytics Market Competitive Environment
Capability concentration sits with specialized statistical heritage players; scale advantage sits with global consulting networks and cloud-native platforms. The market structures around three tiers: legacy statistical software vendors with decades of methodological depth, hyperscale cloud providers offering elastic compute, and boutique data science consultancies delivering bespoke modeling. Consolidation pressures intensify as mid-market retailers and healthcare systems demand integrated platforms over point solutions. Strategic moves center on federated learning partnerships and vertical-specific compliance certifications.
Within the heritage statistical tier, SAS Institute and IBM exemplify methodological depth anchored in regulated industries. Palantir Technologies occupies a specialized position serving government and defense contracts through purpose-built analytics architectures. Among India-based delivery specialists, Mu Sigma and Fractal Analytics represent the cost-optimized services model that Western enterprises increasingly leverage for non-core modeling workloads.
| Leading Market Players |
|---|
| Deloitte |
| Palantir Technologies |
| SAS Institute |
| Fractal Analytics |
| Databricks |
| IBM |
| McKinsey & Company |
| Mu Sigma |
| Accenture |
| Others |
Value Chain & Pricing Dynamics
GPU undercapacity in Taiwan and South Korea is compressing training-cycle economics for statistical analytics vendors, forcing subscription pricing toward consumption-based models while cloud providers ration accelerator access through reserved-instance tiers.
Pricing Analysis
Long-term enterprise commitments anchor pricing in the statistical analytics market, with three-year SaaS contracts commanding 15-20% discounts against month-to-month tiers. Price differentiation hinges on FDA validation status and HIPAA attestation level, with certified clinical platforms sustaining premiums over general-purpose tools. Pricing pressure stems from India's cost-optimized delivery clusters undercutting Western consulting rates. Mid-market retailers exhibit highest price sensitivity, while defense and intelligence buyers prioritize air-gapped security over cost.
Supply Chain Analysis
Contract manufacturing concentration rests with TSMC and Samsung Foundry for GPU silicon, with NVIDIA and AMD designing specialized inference accelerators. Geographic supply concentration centers on Taiwan, South Korea, and the United States for advanced semiconductor fabrication. Raw material dependencies span high-bandwidth memory from SK Hynix and Micron, plus rare earth elements for magnetics in data center cooling. Single-source vulnerability around TSMC's leading-edge nodes threatens model training capacity. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Statistical analytics sits in early-cycle expansion as federated learning architectures unlock cross-institutional modeling without raw data centralization, accelerating penetration among privacy-constrained healthcare networks.
For Market Incumbents: Build regulatory certification moats through FDA 21 CFR Part 11 and EU AI Act high-risk system validations. Deepen backward integration into GPU cloud infrastructure to secure training capacity against TSMC allocation constraints. Consolidate around vertical-specific compliance architectures as ANVISA and emerging Asian regulators fragment validation requirements. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA-aligned clinical analytics segment where first-mover positioning remains open. Target mid-market European manufacturers seeking EU AI Act compliance services without legacy vendor lock-in. Lead with federated learning implementations that bypass incumbent data centralization requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GPU-accelerated inference platforms as reserved-instance commitments replace elastic consumption. Long-term viability favors platforms with regulatory certification depth and hybrid deployment architectures. Acquire specialist firms with FDA-validated clinical decision support pipelines. Watch hyperscaler capex allocation to AI infrastructure as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Enables Mayo Clinic and Kaiser Permanente to model across institutions without HIPAA violations. |
| EU AI Act Compliance Certification | Positions vendors for Stuttgart and Munich manufacturers facing risk classification mandates. |
| GPU Cloud Capacity Reservation | Secures training infrastructure against TSMC allocation constraints for mid-market financial services. |
| ANVISA Validation Pathway | Unlocks São Paulo and Rio de Janeiro private insurer procurement for clinical analytics platforms. |
| AutoML Platform Launch | Expands addressable market to French and UK mid-market retailers without dedicated statistical staff. |
Study Parameters
Cross-validation between primary interviews with healthcare CIOs, financial services risk officers, and cloud platform engineers and secondary sources including FDA 510(k) filings, SEC quantitative risk disclosures, and hyperscaler capex reports anchors the qualitative findings. Bottom-up sizing triangulates against top-down spend analysis from hospital procurement databases and GPO contracts. Stakeholder roles span biomedical engineers validating clinical decision support, IT procurement officers at US hospital networks, and data science leads at Bangalore delivery centers.
Calibration against historical adoption curves in healthcare IT and financial services risk technology shapes the projection framework. Segmentation dimensions include solution maturity tier, deployment architecture, vertical end-use, and regional regulatory cluster. CAGR derivation incorporates GPU cost decline trajectories, cloud egress fee trends, and FDA validation timeline compression. Industry-specific inputs capture HIPAA-aligned reimbursement mandate expansion and EU AI Act implementation pacing.
Sensitivities concentrate around TSMC capacity allocation shifts, FDA guidance evolution on algorithmic clinical support, and cloud provider pricing actions. Forecasts reflect assumptions on federated learning adoption velocity and mid-market retailer AutoML penetration. Quarterly review of hyperscaler AI infrastructure capex, ANVISA regulatory guidance updates, and hospital network procurement pipeline indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Canada Contact Center Analytics Market
Analytics
Multichannel Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
Spain Geospatial Analytics Market
Analytics
Attribution Software Market
Analytics
Augmented Analytics Market
Analytics
Speech and Voice Analytics Market
Analytics
Regression Analysis Tool Market
Analytics
Speech Analytics Market
Analytics
Datacenter Analytics Market
Analytics
Global Sentiment Analytics Software Market
Analytics
Service Analytics Market
Analytics
Data Analytics Outsourcing Market
Analytics
Global Systems of Insight Market
Analytics
In-Memory Analytics Tools Market
Analytics
Online Analytical Processing Market