
 Location Intelligence Market | 2026-2036
Location Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Location Intelligence Market Intelligence
The EU AI Act is decoupling algorithmic transparency from traditional data licensing, raising the cost-of-entry for vendors selling automated spatial decision tools in European jurisdictions. Esri leverages decades of proprietary geodatabase architecture to sustain premium positioning in government accounts. Google anchors its location intelligence layer within the broader cloud ecosystem, competing on integration breadth rather than standalone GIS depth.
Location intelligence denotes the practice of deriving actionable insight from geospatial data through spatial analytics, mapping software, and geographic information systems, typically processing coordinates, topology, and remote sensing feeds at sub-meter resolution for commercial and operational decision-making. Spatial analytics and mapping software command the largest current revenue pools, while cloud-based and hybrid cloud deployment models capture the fastest expansion as enterprises migrate from legacy on-premises GIS servers. Government agencies and telecommunications providers represent the most structurally entrenched end-user verticals, with financial institutions emerging as a high-margin growth segment for risk management applications.
The Federal Communications Commission shapes spectrum allocation rules that directly determine the density and precision of carrier-grade location data in the United States, while the EU Green Deal and GDPR collectively constrain how environmental geospatial datasets may be collected, shared, and monetized across member states. Stakeholders must monitor whether emerging national data sovereignty frameworks fragment cross-border geospatial cloud architectures before committing to centralized platform investments.
Market Dynamics
Telecommunications providers are deploying spatial analytics at scale to optimize 5G network density and reduce signal propagation errors, while the EU AI Act imposes algorithmic transparency mandates that fragment vendor compliance architectures across European jurisdictions.
Growth Catalysts
- EU AI Act compliance mandates:Automated geospatial decision systems in member states must now meet explainability standards, creating replacement demand for transparent spatial analytics platforms in government and defense procurement.
- Telecommunications network densification:5G rollouts require sub-meter precision in antenna placement and interference mapping, pulling carrier-grade location intelligence spending upward across Germany, France, and the United Kingdom.
- Federal smart city initiatives:United States municipal governments are consolidating GIS contracts to capture operational efficiencies in traffic management, emergency response routing, and utility asset tracking.
Market Restraints
- Remote sensing data licensing costs:High-resolution satellite imagery from commercial providers commands premium pricing that compresses margins for mid-tier analytics vendors serving agricultural and insurance verticals.
- GDPR cross-border transfer constraints:Environmental geospatial datasets containing personal location traces face restricted monetization pathways across EU member states, limiting cloud-native platform architectures.
- Legacy on-premises GIS sunk costs:Government agencies in the United States and Japan retain substantial investments in server-based Esri deployments that slow migration timelines to SaaS alternatives.
Strategic Opportunities
- Financial risk management applications:Insurers and reinsurers in Switzerland and the United Kingdom are adopting catastrophe modeling platforms that integrate property exposure data with real-time flood and wildfire perimeter feeds.
- Edge computing convergence with spatial analytics:Autonomous vehicle manufacturers are testing distributed inference architectures that process LiDAR and camera feeds locally before transmitting compressed feature vectors to central training pipelines.
- India's geospatial data liberalization:Recent policy shifts permit private sector access to previously restricted survey-grade coordinates, opening municipal planning and logistics optimization segments to foreign platform vendors.
Industry Challenges
- Geospatial data science talent scarcity:The intersection of GIS expertise, machine learning implementation, and domain knowledge in telecommunications or defense remains underpopulated relative to platform deployment timelines.
- Interoperability with legacy CAD systems:Engineering firms and utilities require bidirectional data exchange between modern cloud-native location intelligence tools and decades-old infrastructure design file formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location Intelligence Market |
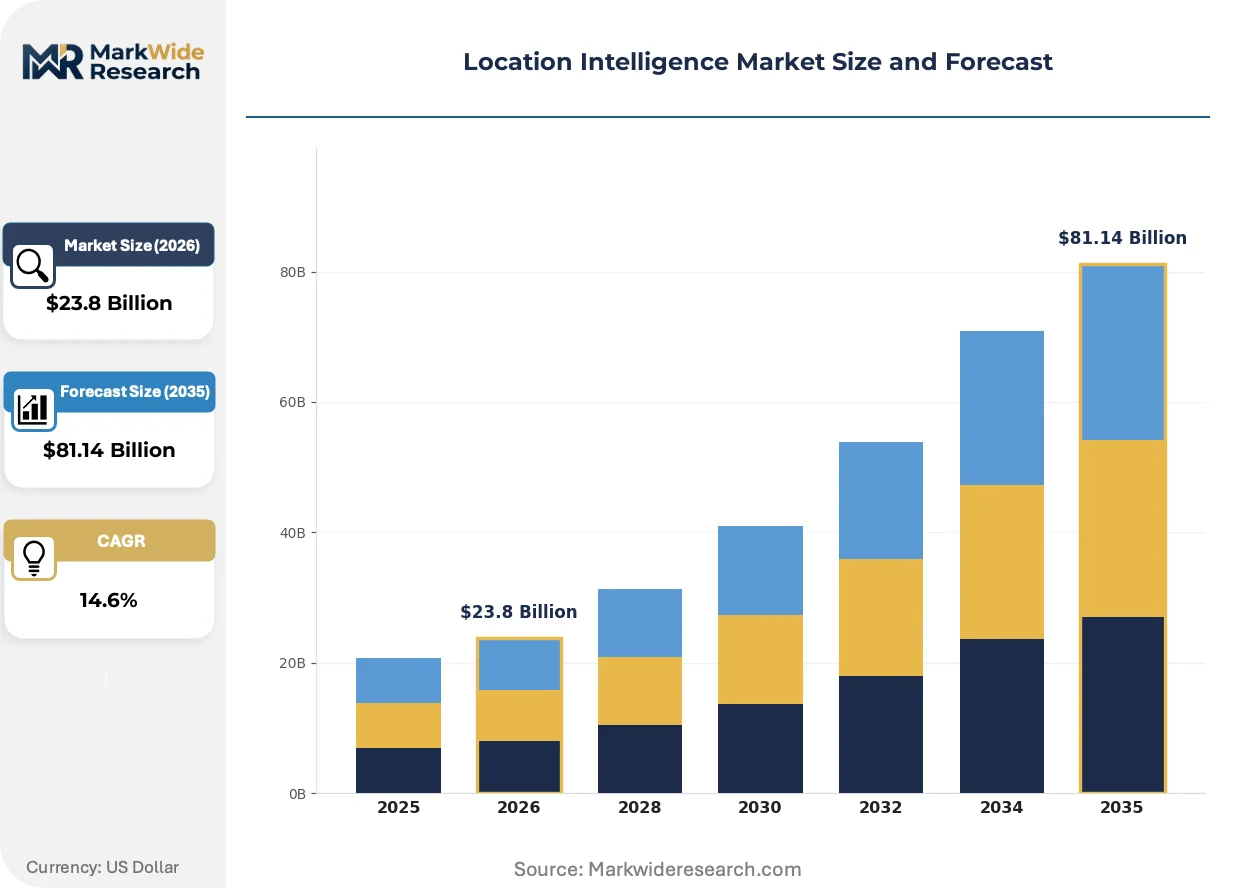
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $81.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Spatial Analytics, Geographic Information System, Mapping Software, Data Visualization, Data Integration Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Software as a Service, Platform as a Service Application: Supply Chain Optimization, Site Selection, Risk Management, Customer Segmentation, Urban Planning End User: Telecommunications Providers, Government Agencies, Financial Institutions, Transportation Operators, Real Estate Developers |
| Companies Covered | Esri, Google, Microsoft, HERE Technologies, TomTom, IBM Corporation, Trimble, Pitney Bowes, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location Intelligence Market Strategic Shifts & Innovations
Digital twin technology is compressing the feedback loop between physical asset monitoring and predictive spatial modeling, forcing platform vendors to rearchitect around real-time sensor ingestion rather than batch geoprocessing workflows.
Digital twin platforms are integrating building information modeling with IoT sensor networks to create persistent 3D replicas of urban infrastructure. Municipal governments in Singapore and Dubai are deploying these systems for flood simulation and energy grid optimization. This convergence is integrating previously siloed engineering datasets into unified spatial operating pictures that displace static master planning documents.
The EU AI Act's risk classification framework is imposing documentation burdens on automated geospatial decision systems used in credit scoring and insurance underwriting. Vendors must now maintain model cards and training data provenance records that satisfy national supervisory authorities. Financial services deployments across Germany and France are experiencing elongated procurement cycles as compliance teams validate algorithmic transparency claims.
Subscription-based platform access is displacing perpetual license models in mid-market government and utility accounts. Esri's ArcGIS Online and competing cloud-native alternatives are capturing municipal GIS budgets that previously funded on-premises server maintenance. This transition is most visible in United States counties with constrained IT capital budgets and limited in-house geodatabase administration expertise.
Location Intelligence Market Segmentation
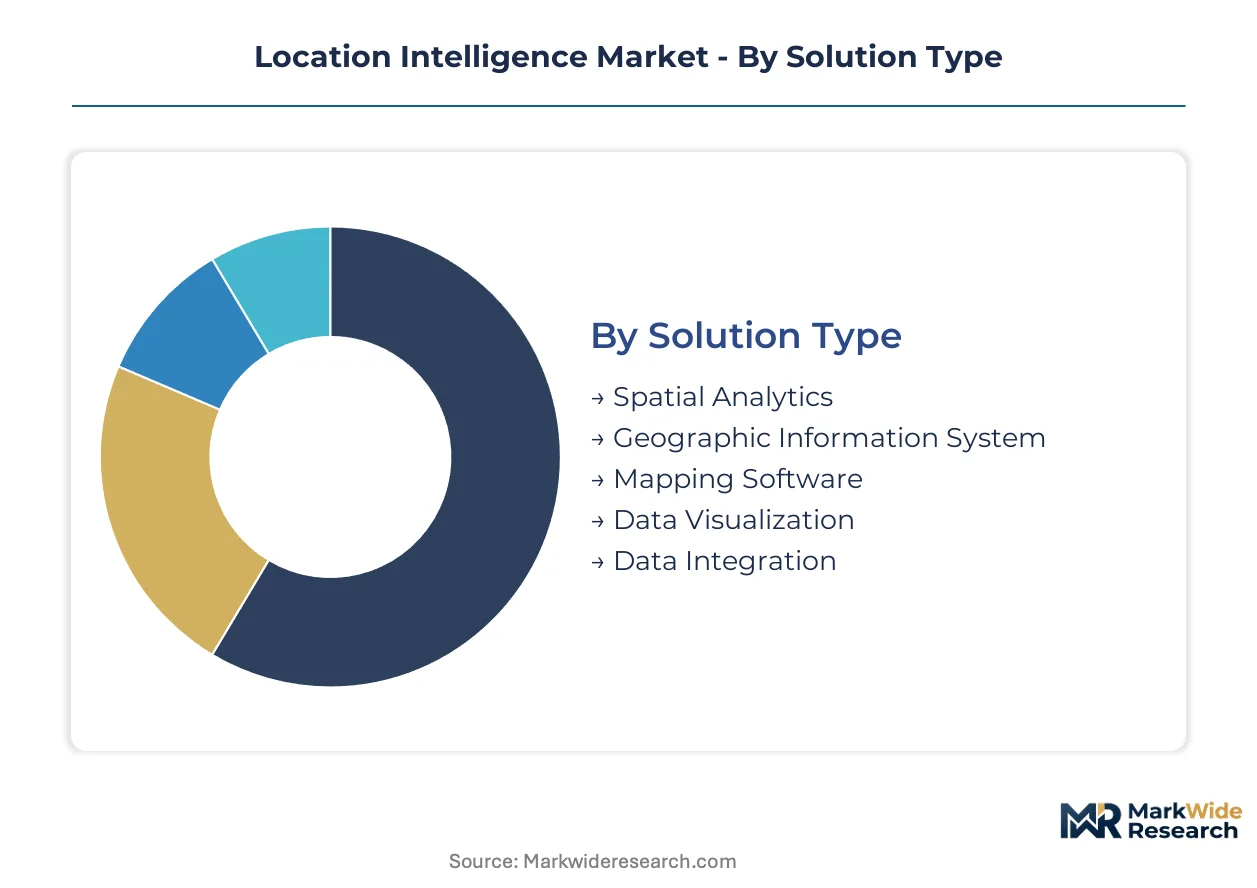
Location intelligence vendors configure product architectures around distinct technical capabilities, infrastructure preferences, and operational use cases. Procurement patterns diverge sharply between legacy government accounts with sunk server investments and cloud-native enterprises seeking elastic geoprocessing capacity.
Solution Type:
Supply concentration clusters around established geodatabase architectures and real-time spatial processing engines that differentiate vendor positioning in enterprise accounts.
- Spatial Analytics:Statistical and machine learning models applied to coordinate-based datasets, including proximity analysis, spatial clustering, and predictive geofencing. Telecommunications providers in Germany and the United Kingdom deploy these tools for 5G propagation modeling and antenna density optimization. FCC spectrum allocation rules directly shape the precision requirements carriers demand from these platforms.
- Geographic Information System:Comprehensive platforms integrating data capture, storage, manipulation, and visualization with topological relationship management. Government agencies in the United States and Japan retain substantial Esri deployments that slow migration timelines to cloud alternatives. Sunk infrastructure costs and specialized workforce training entrench these systems in municipal planning and defense applications.
- Mapping Software:Visualization-centric tools rendering geospatial data as interactive cartographic outputs with layer management and annotation capabilities.
- Data Visualization:Dashboard and reporting interfaces translating spatial query results into operational intelligence for non-technical decision-makers.
- Data Integration:ETL pipelines and API connectors consolidating geospatial feeds from satellite imagery, IoT sensors, and proprietary survey databases into unified analytical environments.
Geographic Information Systems absorb the bulk of installed capacity; Spatial Analytics is expanding most quickly.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from operational expenditure models favored by mid-market accounts with constrained IT budgets.
- On-Premises:Dedicated server infrastructure hosting geodatabases and spatial processing engines within organizational data centers. Japanese prefectural governments and U.S. federal defense installations maintain these deployments for air-gapped security requirements and sub-millisecond query latency on classified datasets.
- Cloud-Based:Fully managed geoprocessing environments with elastic compute scaling and consumption-based pricing. Singapore's municipal digital twin initiatives and Dubai's smart city programs leverage these architectures for real-time sensor ingestion and flood simulation workloads.
- Hybrid Cloud:Split architectures retaining sensitive geodatabases on-premises while routing analytical workloads to public cloud infrastructure.
- Software as a Service:Subscription access to browser-based mapping and analytics tools with minimal client-side infrastructure requirements.
- Platform as a Service:Developer-facing environments enabling custom application deployment atop vendor-managed geospatial infrastructure.
On-Premises retains the largest installed base; Cloud-Based deployments are climbing the fastest as municipal governments consolidate IT budgets.
Application:
Volume concentration tracks capital expenditure cycles in network infrastructure, real estate development, and public sector asset management programs.
- Supply Chain Optimization:Route planning, warehouse location modeling, and logistics network design using distance matrices and traffic pattern analysis. India's logistics sector applies these tools following geospatial data liberalization policies that opened previously restricted survey-grade coordinates to private sector platforms.
- Site Selection:Multi-criteria decision analysis combining demographic overlays, competitive proximity, and accessibility metrics for retail and industrial facility placement. Swiss and United Kingdom insurers integrate property exposure data with real-time flood perimeter feeds for catastrophe modeling and risk-adjusted underwriting decisions.
- Risk Management:Geospatial assessment of natural hazard exposure, climate vulnerability, and infrastructure resilience for financial and operational continuity planning.
- Customer Segmentation:Location-based clustering of consumer behavior patterns for targeted marketing and service territory design.
- Urban Planning:Land use zoning, transportation network design, and utility infrastructure coordination using cadastral and topographic datasets.
Site Selection commands the greatest current investment intensity; Supply Chain Optimization is gaining share fastest as India's logistics market liberalizes.
End User:
Customer type determines pricing architecture, with government procurement cycles and telecommunications carrier contracts anchoring long-term revenue visibility.
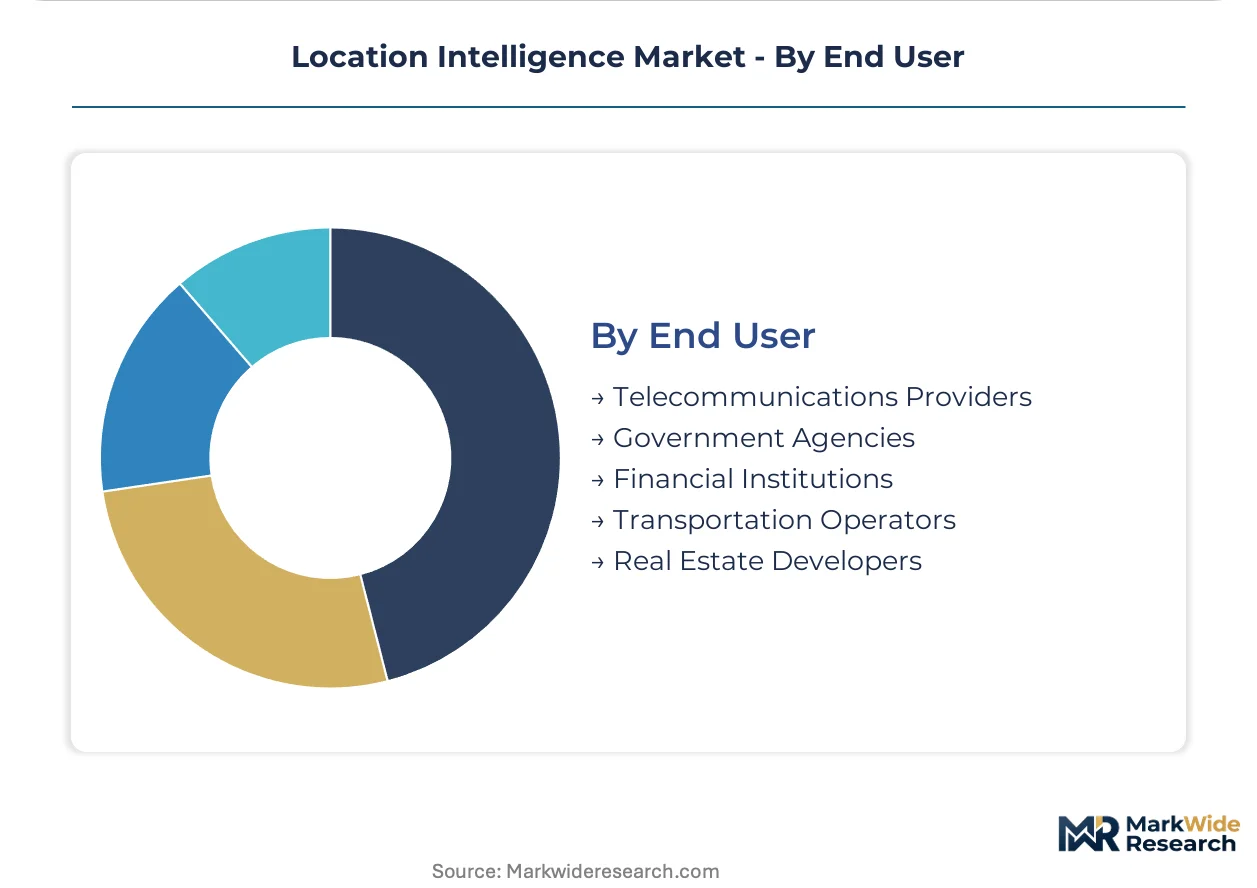
- Telecommunications Providers:Carriers deploying spatial analytics for network densification, spectrum interference mapping, and subscriber density forecasting. Germany's 5G rollout programs and France's mobile infrastructure investments pull carrier-grade location intelligence spending upward as EU member states mandate sub-meter precision in antenna placement.
- Government Agencies:Federal, state, and municipal entities managing land records, emergency response routing, and defense geospatial operations. United States counties with constrained IT capital budgets are consolidating GIS contracts to capture operational efficiencies in traffic management and utility asset tracking.
- Financial Institutions:Banks, insurers, and reinsurers applying geospatial risk models to credit scoring, property valuation, and catastrophe bond structuring.
- Transportation Operators:Rail, aviation, and maritime entities optimizing route efficiency, maintenance scheduling, and terminal capacity planning.
- Real Estate Developers:Property investment firms and construction enterprises evaluating market potential and construction feasibility through demographic and environmental overlays.
Government Agencies anchor the largest contract values; Financial Institutions are expanding most quickly as EU AI Act compliance requirements reshape algorithmic transparency standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and Singapore concentrate location intelligence infrastructure investments, with tax incentives pulling platform vendors toward municipal digital twin deployments and logistics optimization hubs.
United States
Federal smart city initiatives and defense geospatial spending drive procurement consolidation across municipal governments. The FCC shapes spectrum allocation rules that determine carrier-grade location data precision requirements. Greater Boston and the Pacific Northwest host dense clusters of spatial analytics startups serving federal intelligence contracts.
Germany
Telecommunications providers deploy sub-meter precision tools for 5G antenna placement and interference mapping. The EU AI Act imposes algorithmic transparency mandates on automated spatial decision systems used in credit scoring. Berlin-Brandenburg anchors government procurement for transparent geospatial platforms in defense and municipal planning.
India
Geospatial data liberalization policies opened previously restricted survey-grade coordinates to private sector logistics and municipal planning platforms. The country's national geospatial regulator oversees compliance frameworks for foreign platform vendors. Maharashtra and Karnataka host emerging clusters of supply chain optimization vendors targeting port and highway infrastructure.
United Kingdom
Insurers and reinsurers adopt catastrophe modeling platforms integrating property exposure data with real-time flood perimeter feeds. GDPR cross-border transfer constraints limit environmental geospatial dataset monetization pathways. London anchors financial services deployments where compliance teams validate algorithmic transparency claims for underwriting applications.
Singapore
Municipal digital twin initiatives leverage cloud-based architectures for real-time sensor ingestion and flood simulation workloads. The country's smart nation program funds persistent 3D replicas of urban infrastructure integrating building information modeling with IoT networks. The city-state's special economic zone status attracts platform vendors targeting Southeast Asian municipal planning exports.
Location Intelligence Market Key Industry Players
United States producers anchor the premium government and defense tier; European specialists hold positions in telecommunications and automotive navigation. The vendor base stratifies across three layers: comprehensive geodatabase platforms, cloud-native spatial analytics engines, and component specialists in mapping data or positioning hardware. Strategic moves concentrate on SaaS migration programs and API ecosystem expansion to capture mid-market municipal accounts.
Within the comprehensive platform tier, Esri and Google occupy distinct positioning archetypes. Esri leverages decades of proprietary geodatabase architecture to sustain premium positioning in government accounts with substantial sunk infrastructure investments. Google anchors its location intelligence layer within broader cloud ecosystem integration, competing on breadth rather than standalone GIS depth. HERE Technologies represents the telecommunications and automotive specialization vector, with heritage in carrier-grade navigation data feeding into 5G network optimization platforms.
| Leading Market Players |
|---|
| Esri |
| Microsoft |
| HERE Technologies |
| TomTom |
| IBM Corporation |
| Trimble |
| Pitney Bowes |
| Qualcomm Technologies |
| Others |
Cost & Logistics Intelligence
Premium government-grade geodatabase platforms diverge sharply from cloud-native SaaS alternatives, with that performance gap manifesting in both subscription pricing power and supply chain concentration around legacy Esri-certified system integrators versus API-first development shops.
Pricing Analysis
Short lead-time deployments command 40-60% premiums over standard implementation cycles. The dominant pricing structure runs subscription-based SaaS tiers differentiated by data volume thresholds and API call limits. Price differentiation rests on certification level—FedRAMP-authorized deployments versus commercial cloud—and vertical integration depth with legacy CAD systems. Pricing pressure stems from telecommunications carriers consolidating vendor relationships around 5G network optimization bundles. Mid-market municipal governments exhibit highest price sensitivity, while defense and intelligence agencies show lowest sensitivity given air-gapped security requirements.
Supply Chain Analysis
Dual-sourcing requirements from U.S. federal procurement rules mandate multi-supplier qualification for geospatial intelligence contracts, fragmenting vendor concentration. Supply concentrates in the United States, Germany, and India—American firms anchor defense-grade platforms, German specialists serve telecommunications network optimization, and Indian developers supply cost-engineered municipal planning tools. Raw material dependencies include commercial satellite imagery from Maxar and Planet Labs, LiDAR sensor hardware from Velodyne and Hesai, and cloud compute from AWS and Azure. Single-source vulnerability sits with high-resolution satellite imagery licensing. Distribution runs through systems integrators and direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The location intelligence market occupies a technology-transition phase where cloud-native spatial analytics engines displace legacy on-premises GIS server deployments.
For Market Incumbents: Deepen vertical integration into proprietary geodatabase architectures to defend government account stickiness against cloud-native challengers. Prioritize FedRAMP and EU AI Act compliance certification investments to sustain premium positioning. Esri's decades of sunk infrastructure entrenchment represents the core defensive moat, though SaaS migration timelines compress as municipal IT budgets consolidate. For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for transparent spatial analytics platforms that satisfy algorithmic explainability mandates in credit scoring and insurance underwriting. Target financial services risk management applications as the most penetrable segment, with catastrophe modeling for Swiss and UK insurers offering immediate white-space opportunity. Pursue API-first go-to-market strategies that embed within existing cloud ecosystems rather than displacing entrenched GIS workflows. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native spatial analytics specialists given telecommunications carrier spending acceleration on 5G network densification. Long-term viability favors vendors with hybrid deployment architectures bridging on-premises security requirements and elastic cloud capacity. Watch India's geospatial data liberalization enforcement as the signal indicating whether foreign platform vendors capture municipal planning and logistics optimization share.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription models capture municipal budgets shifting from capital to operational expenditure. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation satisfies German and French financial services procurement requirements. |
| Telecommunications Carrier Partnership | 5G network optimization bundles anchor long-term revenue visibility with spectrum allocation-dependent precision tools. |
| Digital Twin Integration | Real-time sensor ingestion architectures displace batch geoprocessing in Singapore and Dubai municipal deployments. |
| Geospatial Talent Acquisition | GIS-machine learning intersection expertise remains underpopulated relative to platform deployment timelines. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with GIS platform product managers, municipal IT procurement officers, telecommunications network planning engineers, and defense geospatial intelligence leads. FCC spectrum allocation dockets, EU AI Act implementation guidance, India's Survey of India liberalization notifications, and satellite imagery licensing contracts furnished validation sources. Bottom-up deployment model sizing and top-down vertical spending analysis triangulated market estimates.
Data-stream reconciliation across solution type, deployment model, application, and end-user verticals structured the analytical framework throughout the projection horizon. CAGRs derived from elasticity modeling against telecommunications capital expenditure cycles and government fiscal year procurement patterns. Modeled inputs included 5G antenna density requirements per FCC rules, EU member state smart city budget allocations, and India's logistics infrastructure investment pipelines.
The model assumes a particular technology adoption path where cloud-native spatial analytics displace on-premises GIS; alternative pathways for edge computing convergence with distributed LiDAR processing would alter the outlook. Deviation in EU AI Act enforcement intensity or India's geospatial data sovereignty implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
China Location-Based Services Market