
 Asia-Pacific Edge Analytics Market | 2026-2036
Asia-Pacific Edge Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Edge Analytics Market Insights
Distributed inference at the network edge is reshaping how analytics capabilities embed into operational technology stacks. Huawei Technologies anchors its position through deep vertical integration across silicon, equipment, and platform layers for industrial deployments. Cisco Systems competes by extending enterprise networking dominance into edge orchestration software. Intel sustains relevance through dedicated silicon architectures optimized for low-latency inference workloads.
Asia-Pacific edge analytics encompasses software, hardware, and services that process data proximate to its source, typically operating with sub-50 millisecond latency thresholds to enable real-time decisioning without cloud round-trips. The primary commercial purpose centers on reducing bandwidth costs while enabling autonomous responses in latency-constrained environments. Software solutions currently occupy the largest revenue share, though hardware components for specialized inference accelerators are registering the fastest expansion as OEMs embed analytics directly into machinery. Hybrid deployment models are gaining traction fastest among large enterprises seeking to balance on-premises control with cloud elasticity for model training.
China's MIIT standards for industrial internet platforms and Japan's METI guidelines on Society 5.0 implementation create compliance-driven procurement requirements that favor certified edge infrastructure vendors. India's TRAI recommendations on data localization and edge computing frameworks add another regulatory layer shaping domestic deployment architectures. Stakeholders must monitor how divergent national certification regimes fragment interoperability standards across the region.
Market Dynamics
China's MIIT industrial internet standards and Japan's METI Society 5.0 mandates are compressing procurement timelines for certified edge infrastructure, forcing vendors to pre-integrate compliance layers into hardware-software bundles before deployment.
Growth Catalysts
- Smart factory mandates:India's PLI scheme for electronics manufacturing and Tamil Nadu's industrial corridor incentives are accelerating edge analytics procurement for predictive maintenance and quality control workflows.
- MIIT certification requirements:China's industrial internet platform standards create compliance-driven demand for domestic edge infrastructure vendors serving state-owned manufacturing conglomerates.
- 5G private networks:Japan's manufacturing facilities are deploying ultra-reliable low-latency connectivity to enable real-time inference at production line endpoints without cloud dependency.
Market Restraints
- Silicon supply concentration:Specialized inference accelerator chip fabrication concentrates in Taiwan and South Korea foundries, exposing deployment timelines to geopolitical supply disruptions.
- Interoperability fragmentation:Divergent national certification regimes across China, Japan, India, and Australia prevent seamless cross-border equipment standardization and raise integration costs.
- Legacy OT integration:Brownfield manufacturing environments running proprietary SCADA protocols require costly protocol translation layers before edge analytics deployment.
Strategic Opportunities
- Indonesian industrial zones:Batam and Karawang manufacturing corridors remain underpenetrated for edge analytics despite government industrial estate expansion programs.
- Converged AI-OT platforms:Integration of computer vision models with edge hardware is creating new service revenue streams for system integrators serving quality inspection applications.
- Vietnam's FDI manufacturing:Samsung and Foxconn supplier ecosystems in Bac Ninh and Hai Phong are beginning to specify edge analytics for supplier compliance monitoring.
Industry Challenges
- Embedded systems talent scarcity:Shortage of engineers proficient in both machine learning model optimization and real-time operating systems delays deployment timelines for complex inference workloads.
- Multi-vendor integration complexity:Enterprises assembling edge stacks from disparate silicon, networking, and software vendors face debugging accountability gaps when latency thresholds fail.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Edge Analytics Market |
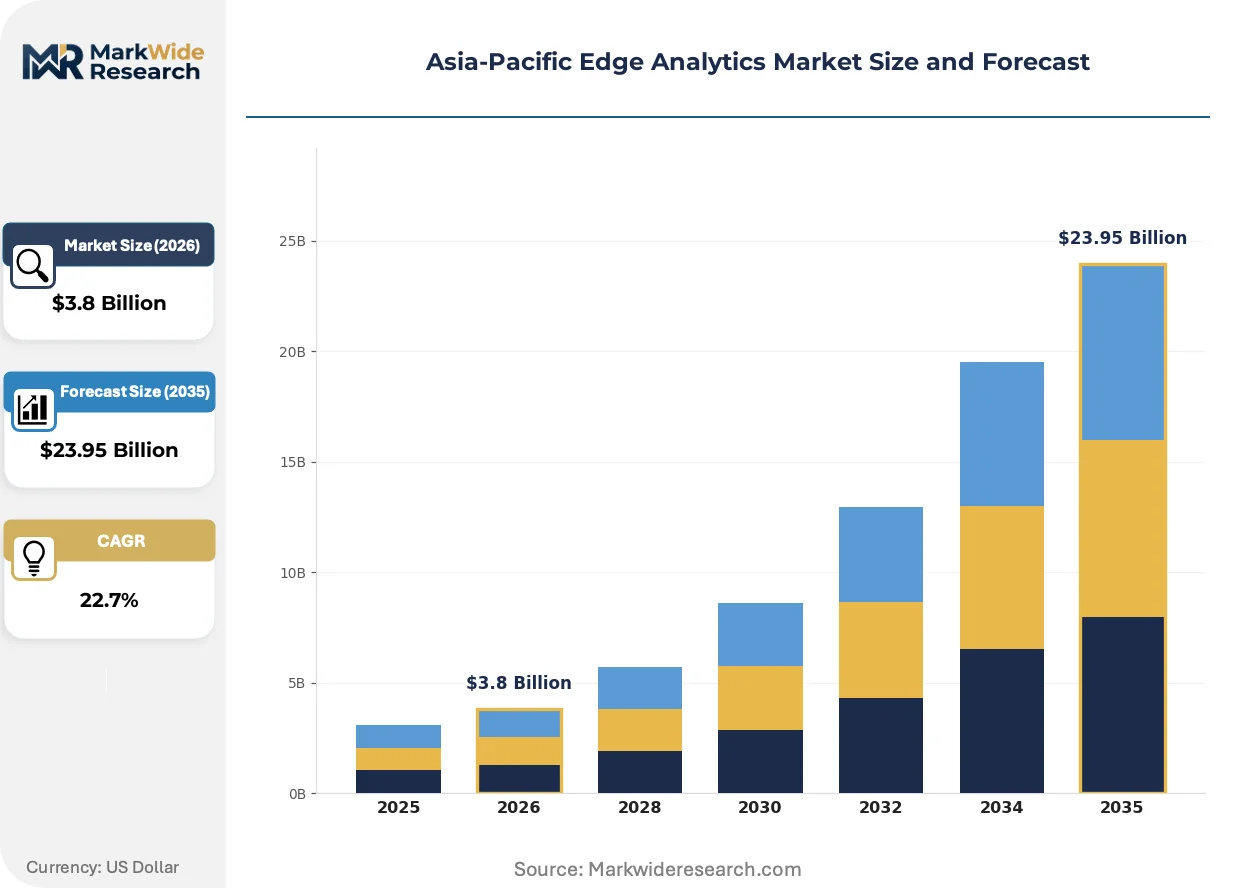
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Deployment: On-premises, Cloud, Hybrid, Multi-cloud End User: Manufacturing, Retail, Healthcare, Energy Application: IoT Analytics, Predictive Maintenance, Real-time Monitoring, Data Processing |
| Companies Covered | Huawei Technologies, Cisco Systems, Hewlett Packard Enterprise, IBM, Microsoft, SAP, Schneider Electric, EdgeConneX, Intel, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Edge Analytics Market Trends and Innovations
Edge-native software architectures are displacing cloud-dependent analytics workflows across Asia-Pacific manufacturing and energy infrastructure. Three developments are compressing deployment timelines and reshaping competitive positioning.
Containerized microservices orchestration is digitizing how analytics workloads distribute across heterogeneous edge hardware. Japanese automotive suppliers are adopting Kubernetes-based edge platforms to standardize model deployment across multi-facility networks. This architecture is digitizing operational technology stacks by decoupling application logic from proprietary hardware dependencies.
METI's data governance framework for industrial data spaces is mandating localized processing for sensitive manufacturing parameters. Japanese chemical and pharmaceutical producers must now retain quality data within facility premises, accelerating on-premise inference hardware procurement. Medical device manufacturers in Osaka and Nagoya industrial zones are most affected, retrofitting cleanroom lines with certified edge nodes.
Buyers are unbundling hardware procurement from managed analytics services, forcing vendors to price inference accelerators separately from software subscriptions. Large Japanese electronics assemblers now source NVIDIA and Intel silicon through distribution channels while negotiating platform licenses directly. This bifurcation is most visible in South Korea's semiconductor packaging facilities, where equipment capex and operational software budgets sit under separate procurement functions.
Asia-Pacific Edge Analytics Market Segmentation
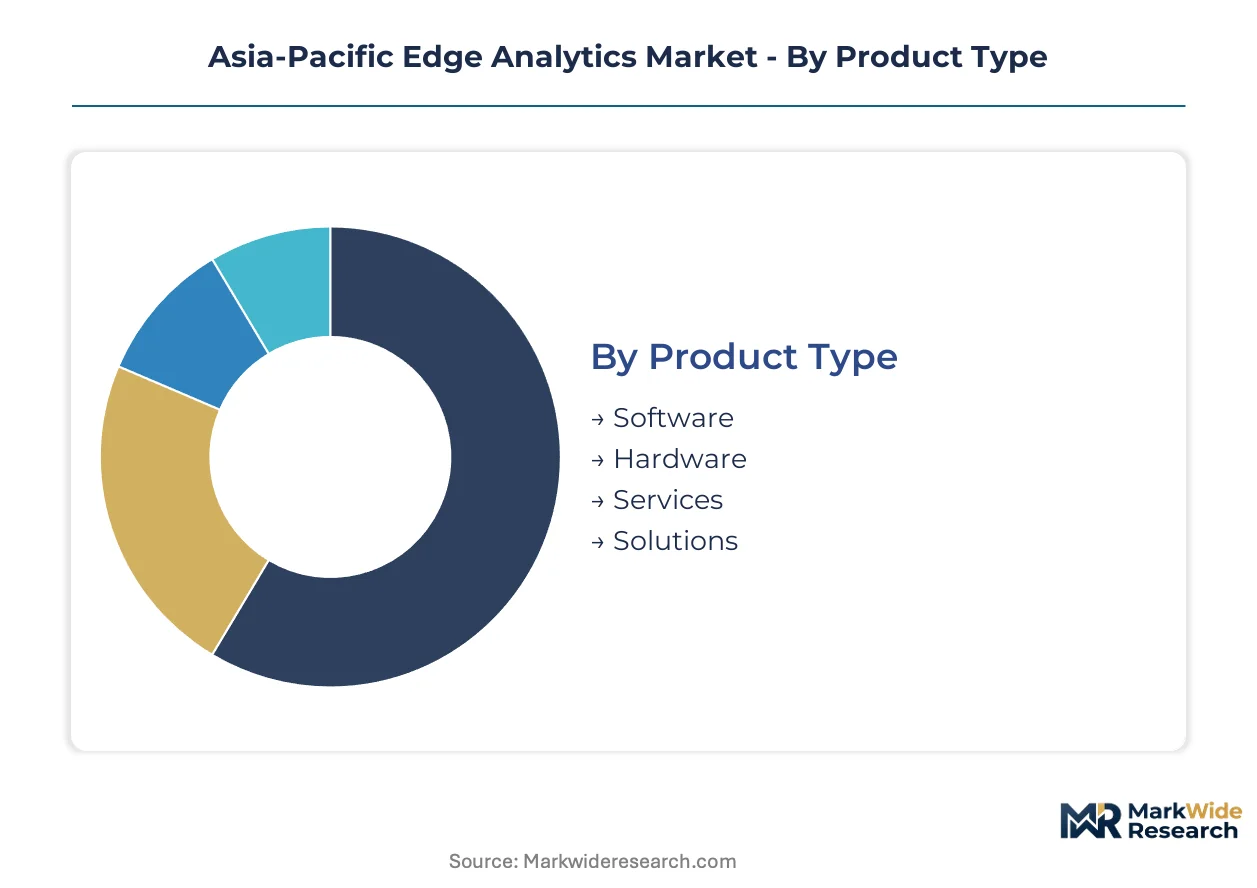
Edge analytics procurement in Asia-Pacific follows distinct patterns across product layers and deployment architectures. Buyers segment investments based on latency requirements, data sovereignty mandates, and integration complexity with legacy operational technology stacks.
Product Type:
After-sales service intensity varies sharply across product categories, with hardware deployments demanding field engineering support while software subscriptions rely on remote platform management.
- Software:Analytics platforms and inference engines deploy as containerized microservices across heterogeneous edge hardware. Japanese automotive suppliers in Aichi Prefecture are standardizing on Kubernetes-based orchestration to decouple application logic from proprietary equipment dependencies.
- Hardware:Specialized inference accelerators, edge servers, and ruggedized gateway devices embed silicon optimized for sub-50 millisecond latency thresholds. South Korean semiconductor packaging facilities in Pyeongtaek and Icheon are sourcing NVIDIA and Intel accelerators through separate procurement channels from their software licenses.
- Services:System integration and managed analytics offerings address brownfield protocol translation requirements.
- Solutions:Bundled hardware-software packages incorporating compliance certification layers for MIIT and METI mandates.
By volume, Software leads. By growth pace, Hardware is ahead.
Deployment:
Cost tier differentiation separates enterprise-grade on-premises control from consumption-based cloud elasticity, with hybrid architectures commanding premium integration services.
- On-premises:Fully localized infrastructure retains sensitive manufacturing parameters within facility premises per METI data governance frameworks. Osaka and Nagoya pharmaceutical producers retrofit cleanroom lines with certified edge nodes to satisfy localized processing mandates.
- Cloud:Centralized model training and batch analytics workloads leverage hyperscaler elasticity for non-latency-constrained applications.
- Hybrid:Split architectures balance edge inference with cloud-based model refinement, gaining traction among large Japanese electronics assemblers seeking operational control plus training scalability.
- Multi-cloud:Distributed deployments across competing hyperscaler platforms reduce vendor lock-in for multinational manufacturing networks.
Hybrid deployments capture the steepest expansion trajectory as procurement budgets bifurcate between capex equipment and operational software functions.
End User:
Application maturity determines segment prioritization, with manufacturing automation commanding established budgets while healthcare diagnostics builds regulatory compliance foundations.
- Manufacturing:Predictive maintenance and real-time quality control workflows dominate procurement across Japan's automotive suppliers and India's Gujarat industrial corridor electronics assembly plants.
- Retail:Computer vision applications for inventory management and customer analytics deploy at distribution centers and flagship stores.
- Healthcare:Medical device manufacturers and hospital networks deploy edge analytics for diagnostic imaging and patient monitoring, constrained by PMDA and CDSCO certification timelines.
- Energy:Grid operators and renewable asset managers process sensor telemetry for predictive maintenance of transmission infrastructure.
Manufacturing claims the largest installed base. Healthcare is expanding most quickly as regulatory frameworks mature.
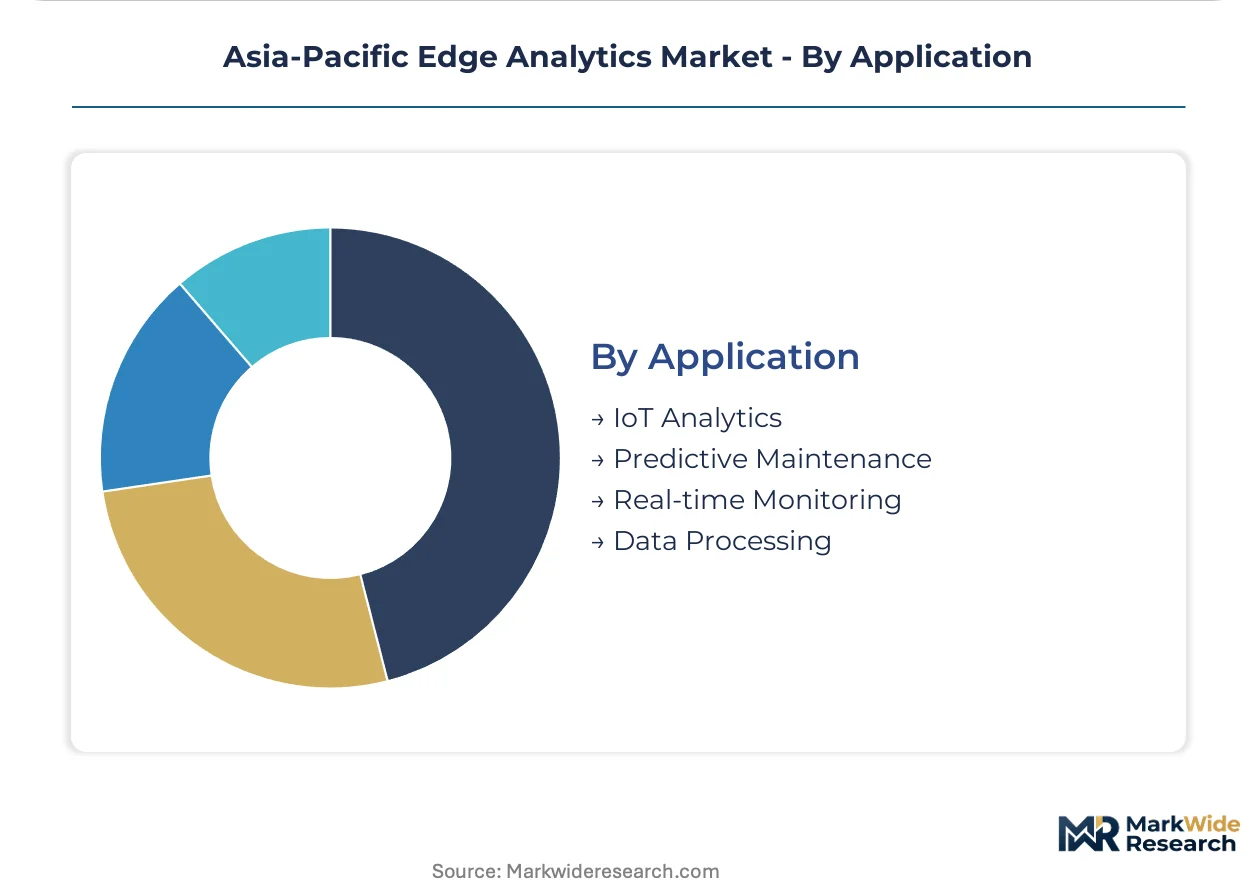
Application:
Customer type segmentation separates industrial automation buyers seeking operational efficiency from infrastructure operators prioritizing asset uptime.
- IoT Analytics:Sensor data ingestion and pattern recognition across connected device fleets. China's state-owned manufacturing conglomerates deploy MIIT-certified platforms for industrial internet connectivity.
- Predictive Maintenance:Machine learning models forecast equipment failure from vibration, thermal, and acoustic signatures. Tamil Nadu's automotive component suppliers specify edge analytics for supplier compliance monitoring under PLI scheme incentives.
- Real-time Monitoring:Sub-second anomaly detection for production line quality control and safety systems.
- Data Processing:Edge-side aggregation, filtering, and transformation reducing bandwidth costs for cloud transmission.
Predictive Maintenance leads by current deployment scale. IoT Analytics is gaining share fastest as 5G private networks proliferate across Japanese manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision manufacturing equipment to Vietnam's expanding electronics assembly sector, creating technology transfer corridors that accelerate edge analytics adoption across Southeast Asian supplier networks.
China
State-owned manufacturing conglomerates drive procurement of MIIT-certified industrial internet platforms for real-time production monitoring. MIIT guidelines mandate domestic edge infrastructure certification for suppliers serving strategic industries. Shanghai and Shenzhen industrial zones deploy edge nodes for semiconductor packaging quality control under dual carbon compliance frameworks.
Japan
Automotive suppliers in Aichi Prefecture standardize on containerized edge orchestration for multi-facility predictive maintenance networks. METI's Society 5.0 implementation guidelines compress procurement timelines for certified infrastructure vendors. Osaka pharmaceutical producers retrofit cleanroom lines with localized inference hardware per data governance mandates.
India
Electronics manufacturers in Gujarat and Tamil Nadu industrial corridors specify edge analytics for supplier compliance under PLI scheme incentives. TRAI recommendations on data localization shape domestic deployment architectures for multinational contract manufacturers. Bengaluru's industrial technology parks host system integrators serving predictive maintenance workflows for automotive component suppliers.
South Korea
Semiconductor packaging facilities in Pyeongtaek and Icheon bifurcate procurement between silicon capex and software operational budgets. The country's national technology regulator enforces cybersecurity certification for industrial edge deployments. Busan-Ulsan manufacturing zones integrate computer vision edge nodes for quality inspection in shipbuilding supply chains.
Vietnam
Samsung and Foxconn supplier ecosystems in Bac Ninh and Hai Phong specify edge analytics for compliance monitoring as FDI manufacturing scales. The government's industrial estate expansion programs in northern provinces create greenfield deployment opportunities. Ho Chi Minh City logistics corridors pilot edge-enabled inventory tracking for export-oriented electronics assembly.
Asia-Pacific Edge Analytics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered vendor structure where networking incumbents leverage enterprise relationships against silicon vendors pushing dedicated inference architectures. The market fragments vertically across hardware, platform, and services layers rather than horizontally by end-use segment. Three archetypes dominate: full-stack infrastructure vendors with captive silicon, enterprise networking extenders with orchestration software, and component suppliers selling through distribution channels. Competitive moves center on pre-integrating compliance certification layers for national regulators and unbundling hardware procurement from managed service subscriptions.
Within the full-stack infrastructure tier, Huawei Technologies exemplifies vertical control across silicon, equipment, and platform layers for industrial deployments. Cisco Systems occupies a position as a networking incumbent extending enterprise dominance into edge orchestration software. Intel anchors the component supplier archetype through dedicated accelerator architectures optimized for low-latency inference workloads.
| Leading Market Players |
|---|
| Huawei Technologies |
| Cisco Systems |
| Hewlett Packard Enterprise |
| IBM |
| Microsoft |
| SAP |
| Schneider Electric |
| EdgeConneX |
| Intel |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Ningbo port freight corridors transmit cost volatility from concentrated silicon foundries directly into edge hardware pricing tiers, compressing margins for mid-tier inference accelerator suppliers while amplifying premium capture for MIIT-certified domestic vendors serving state-owned manufacturing conglomerates.
Pricing Analysis
Current-generation NVIDIA H100 accelerators command substantial premiums over prior-generation A100 silicon and anticipated next-generation Blackwell deployments, creating a three-tier pricing structure across premium, standard, and economy levels. Subscription-based software licenses for Kubernetes orchestration platforms stratify by inference throughput capacity and METI compliance certification grade. Cost compression in mid-tier hardware is intensifying because Chinese domestic suppliers are scaling MIIT-certified alternatives under industrial internet mandates. Small-to-mid electronics assemblers in Vietnam and Indonesia exhibit highest price sensitivity, while Japanese automotive tier-1 suppliers prioritize latency performance over unit economics.
Supply Chain Analysis
Export control regimes restricting advanced GPU shipments to Chinese data centers are fragmenting regional supply flows and accelerating domestic silicon substitution programs. Specialized inference accelerator fabrication concentrates in Taiwan and South Korea, with advanced packaging operations in Malaysia and Vietnam. Supply chains draw from cobalt-doped substrates, high-bandwidth memory stacks, and precision thermal interface materials. Single-source vulnerability in TSMC's CoWoS advanced packaging capacity exposes deployment timelines for complex multi-die accelerators. Distribution runs through authorized distributors for hardware components and direct enterprise sales for platform software licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge analytics procurement cycles track manufacturing capital expenditure waves, with current recovery momentum anchored in India's PLI scheme disbursements and Japan's Society 5.0 infrastructure buildouts.
For Market Incumbents: Pre-empt domestic vendor displacement in China by accelerating MIIT pre-certification for next-generation hardware-software bundles before 2025 compliance deadlines tighten. Consolidate channel control through exclusive distribution agreements with industrial system integrators in Tamil Nadu and Aichi Prefecture, neutralizing emerging local platform competitors leveraging government procurement preferences. For New Entrants and Emerging Players: Build out managed analytics service capabilities targeting brownfield SCADA integration in Indonesia's Batam and Karawang industrial corridors, where greenfield edge deployment penetration remains below regional benchmarks. White-space concentration in Vietnamese supplier compliance monitoring for Samsung and Foxconn ecosystems offers the most penetrable entry vector, best accessed through partnerships with established industrial automation distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial technology divisions seeking to monetize non-core edge software assets amid portfolio restructuring pressures. Long-term viability hinges on sustained manufacturing automation intensity across Asia-Pacific, with acquisition premiums flowing to vendors possessing both MIIT and METI certification pipelines. Monitor Japanese automotive supplier capital expenditure guidance as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Pre-Integration | Accelerates procurement eligibility for state-owned manufacturing conglomerates under industrial internet mandates. |
| Kubernetes-Native Platform Development | Decouples analytics workloads from proprietary hardware dependencies for Japanese automotive multi-facility networks. |
| Indonesian System Integrator Partnership | Establishes early presence in Batam and Karawang corridors ahead of industrial estate expansion completion. |
| Inference Accelerator Supply Diversification | Mitigates Taiwan foundry concentration risk through South Korean and domestic Chinese packaging alternatives. |
| Hybrid Deployment Architecture Launch | Captures bifurcated procurement budgets separating capex equipment from operational software subscriptions. |
Research Methodology
The analysis maps edge hardware accelerators, containerized orchestration platforms, and managed analytics services, each validated through chief technology officers at automotive suppliers, industrial system integrators, and semiconductor packaging facility engineers. Primary interviews with platform engineering directors and IT procurement officers at electronics manufacturers in Gujarat, Tamil Nadu, Aichi, and Pyeongtaek combined with secondary validation against MIIT industrial internet guidelines, METI Society 5.0 implementation reports, TRAI data localization recommendations, and hyperscaler edge capex disclosures. Bottom-up deployment estimates triangulated against top-down manufacturing automation spending forecasts.
Assumption sets held regulatory certification timelines and 5G private network deployment schedules fixed while varying manufacturing FDI flow intensity and silicon supply availability. The analytical framework models product type, deployment architecture, end-user industry, and application workload segmentation dimensions across the projection horizon. CAGRs derived from deployment run-rate analysis and replacement cycle assumptions, incorporating edge-native software revenue recognition patterns and inference accelerator unit economics as industry-specific inputs.
Practitioners should monitor MIIT certification regime expansion, METI data governance enforcement intensity, and Taiwan semiconductor supply disruptions for early signals of forecast revision. Forecasts reflect documented assumptions on manufacturing automation intensity and regulatory compliance cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Greece ICT Market
Analytics
Marketing Mix Optimization Market
Analytics
United States Geospatial Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Asia-Pacific Emotion Analytics Market
Analytics
Israel ICT Market
Analytics
Europe Big Data and Business Analytics Market
Analytics
Embedded Business Intelligence Market
Analytics
Data Analytics Outsourcing Market
Analytics
Data Wrangling Market
Analytics
Legal Analytics Market
Analytics
Spend Analytics Software Market
Analytics
Imagery Analytics Market
Analytics
Cyprus ICT Market
Analytics
Augmented Analytics in BFSI Market
Analytics
Customer Analytics in E-Commerce Market