
 Middle East and Africa Location Analytics Market | 2026-2036
Middle East and Africa Location Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Location Analytics Market Foresight
Modular deployment architectures is decoupling software licensing from hardware commitments across buyer organizations. Microsoft leverages its Azure cloud footprint to anchor hybrid deployment conversations with African telecommunications providers. Oracle competes through database-to-analytics integration that sustains enterprise stickiness in South African retail banking. SAP differentiates via embedded geographic information system modules within its broader enterprise resource planning stack.
Middle East and Africa location analytics encompasses the processing, visualization, and predictive modeling of georeferenced data to support spatial decision-making across commercial and public sector workflows. The technology stack typically ingests GPS coordinates, cellular triangulation, and Bluetooth beacon signals to generate heat maps, route optimization matrices, and demographic overlay analyses. Cloud-based deployment leads technology adoption as Gulf-based data center investments reduce latency for real-time fleet and asset tracking applications. Retail analytics commands substantial application-level attention where mall operators and quick-service restaurant chains deploy footfall pattern recognition to optimize tenant mix and promotional placement. Edge computing represents the fastest-growing deployment modality as Nigerian and Kenyan telecommunications firms push analytics closer to base station infrastructure to manage backhaul costs.
South Africa's Information Regulator enforces POPIA compliance for any location data processing involving consumer identifiers, directly shaping vendor data architecture requirements. The UAE's Telecommunications and Digital Government Regulatory Authority mandates sovereign data residency for government contracts, restricting pure public cloud delivery for certain federal applications. Saudi Arabia's National Data Management Office issues classification standards that determine which geospatial datasets require on-premise containment. Stakeholders must monitor evolving data localization decrees across Gulf states as these rules increasingly determine whether hybrid or edge configurations become the default procurement specification.
Market Dynamics
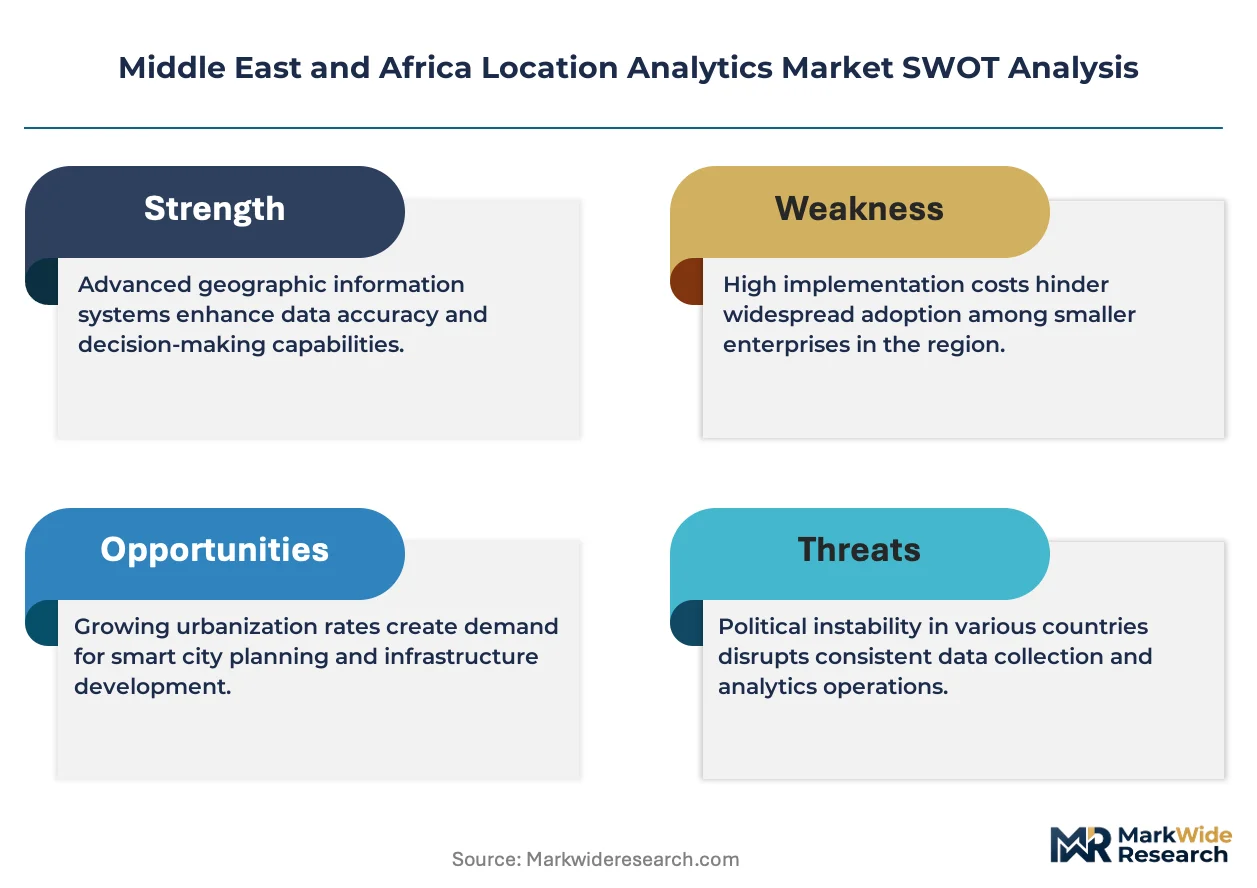
Sovereign data residency mandates across Gulf Cooperation Council states are fragmenting deployment architectures, forcing vendors to engineer hybrid edge-cloud configurations that satisfy divergent national containment requirements while preserving real-time analytics performance.
Growth Catalysts
- Smart city infrastructure mandates:Dubai and Riyadh municipal governments deploy geospatial platforms for traffic flow optimization and utility network management, creating anchor demand for integrated location intelligence suites.
- POPIA compliance frameworks:South Africa's Protection of Personal Information Act establishes precedent for consumer location data governance, enabling compliant vendors to differentiate in retail banking and telecommunications procurement cycles.
- Cellular edge densification:Nigerian and Kenyan telecommunications firms install analytics nodes at base station infrastructure to reduce backhaul expenditure, expanding addressable hardware-software bundles for equipment suppliers.
Market Restraints
- Data localization hardware costs:On-premise containment requirements under Saudi Arabia's National Data Management Office classification standards inflate capital deployment budgets versus pure cloud alternatives.
- Subsea cable concentration:Gulf-to-Europe connectivity routes through Egypt's Suez Canal corridor create single-point vulnerability for cloud-dependent analytics platforms serving UAE federal contracts.
- Triangulation accuracy limitations:Dense urban environments in Cairo and Lagos degrade GPS signal reliability, constraining fleet tracking precision for logistics operators below acceptable service thresholds.
Strategic Opportunities
- Kenyan agricultural digitization:Smallholder crop monitoring via satellite-derived vegetation indices remains underpenetrated, offering first-mover positioning for precision agriculture analytics providers.
- 5G network slicing convergence:Integration of ultra-reliable low-latency communication with location engines enables industrial asset tracking in Saudi petrochemical facilities previously unreachable with legacy cellular.
- UAE federal sovereign cloud procurement:Telecommunications and Digital Government Regulatory Authority mandates create dedicated contracting vehicles for domestic data center operators with embedded analytics capabilities.
Industry Challenges
- Geospatial data science talent scarcity:Gulf-based system integrators compete for limited pools of professionals combining Python-based spatial analysis with Arabic-language regulatory interpretation.
- Legacy ERP integration complexity:South African retail banks maintain decades-old core banking infrastructure that resists API-based connectivity with modern geographic information system modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Location Analytics Market |
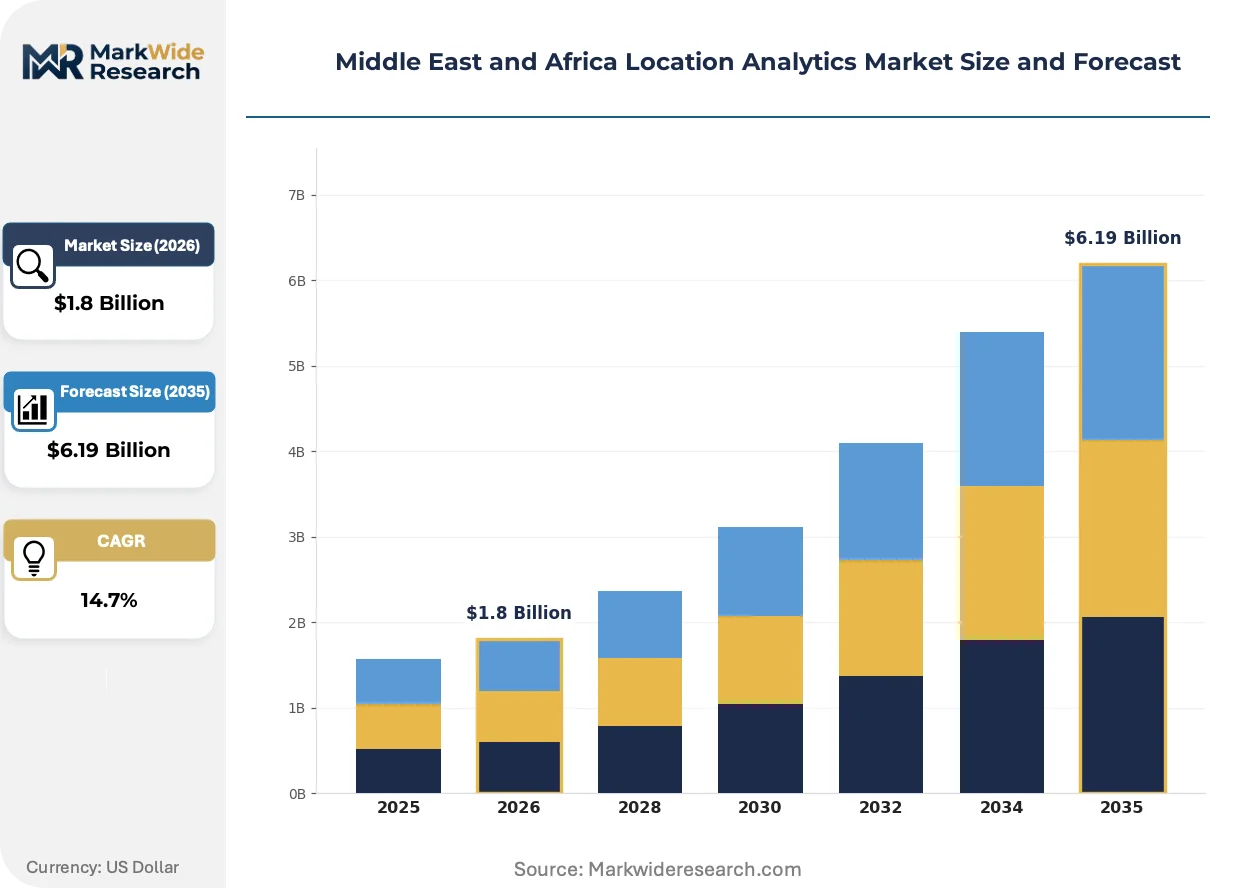
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.19 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Retail Analytics, Urban Planning, Transport Management, Emergency Services Technology: Geographic Information System, Bluetooth Beacons, GPS, RFID End User: Government, Transportation, Retail, Telecommunications Deployment: On-premise, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Esri, Microsoft, Oracle, Cisco, Google, IBM, SAP, Precisely, TomTom, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Location Analytics Market Shifts & Advancements
Edge-native processing architectures are compressing the distance between sensor ingestion and actionable insight, redefining competitive positioning around latency performance rather than historical cloud-scale advantages.
Digital twin platforms for urban infrastructure are absorbing real-time location feeds from IoT sensors, municipal transit systems, and drone-mounted cameras to simulate traffic scenarios and emergency response routing. Dubai's Roads and Transport Authority deploys these synthetic environments for metro expansion planning. The technology is absorbing capital previously allocated to static geographic information system licenses, compressing vendor revenue models toward subscription-based simulation services.
Saudi Arabia's National Data Management Office classification standards mandate tiered containment protocols for geospatial datasets, forcing multinational software vendors to architect sovereign cloud instances within Kingdom borders. Industrial consequence includes mandatory local partnership structures for federal contract eligibility. Defense and critical infrastructure segments are responding by procuring through Saudi Data and Artificial Intelligence Authority pre-qualified vendor lists.
Buyer procurement patterns are fragmenting across departmental lines as chief data officers assert independent contracting authority for analytics platforms outside traditional IT governance. Mall operators in Abu Dhabi and quick-service restaurant chains in Johannesburg now source footfall analytics directly from specialized vendors, bypassing enterprise software procurement committees. This disintermediation is most visible in retail verticals where marketing departments control technology budgets previously centralized under chief information officers.
Middle East and Africa Location Analytics Market Segmentation
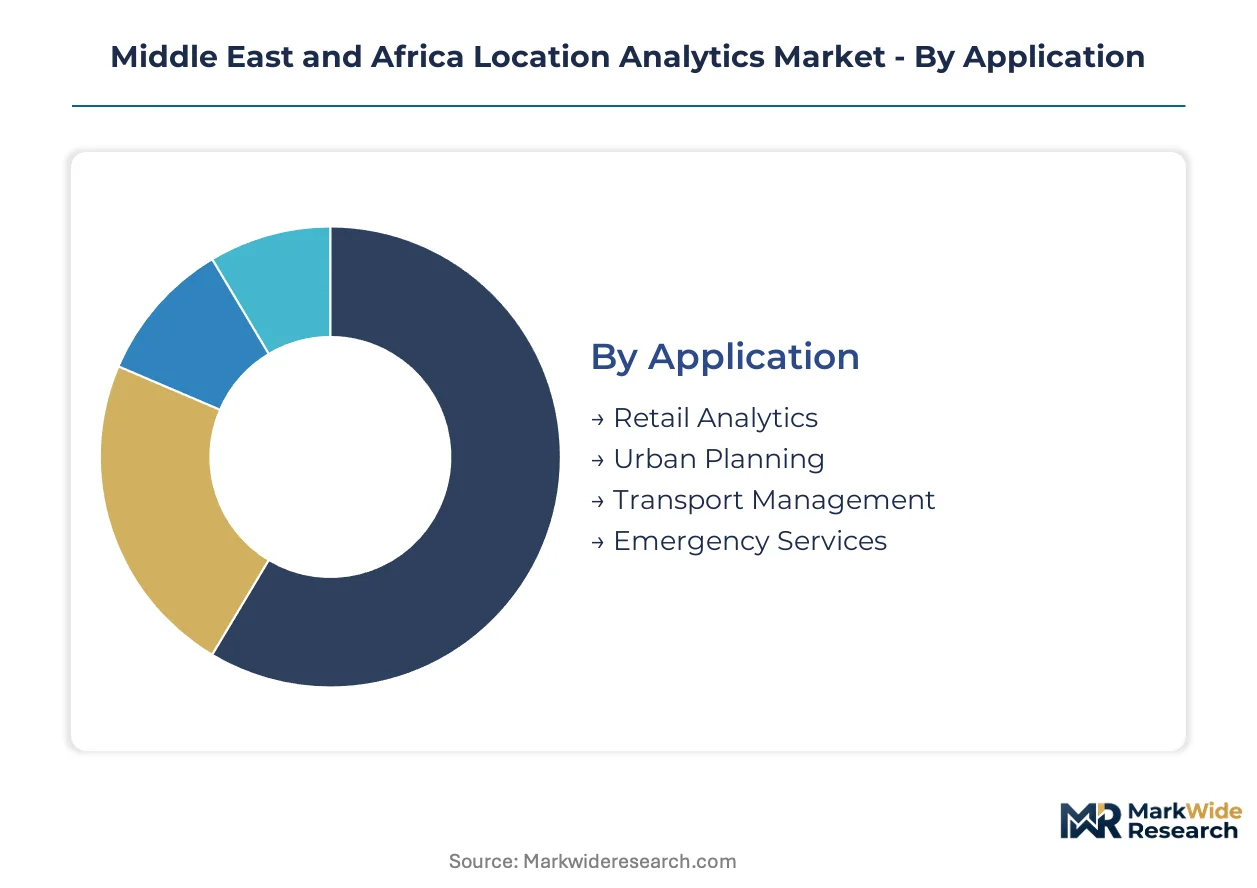
Location analytics procurement across the Middle East and Africa fragments along technology maturity curves and regulatory containment requirements. Buyers prioritize deployment flexibility over feature depth as sovereign data mandates reshape vendor selection criteria.
Application:
Technology sophistication varies sharply across use cases, with real-time processing requirements determining architecture choices.
- Retail Analytics:Footfall pattern recognition and tenant mix optimization dominate mall operator procurement in Dubai and Johannesburg. Quick-service restaurant chains deploy heat mapping for promotional placement, with marketing departments bypassing traditional IT governance to contract directly with specialized vendors.
- Urban Planning:Digital twin platforms synthesize IoT sensor feeds, municipal transit data, and drone-mounted camera inputs for traffic scenario simulation. Dubai's Roads and Transport Authority anchors regional demand through metro expansion planning contracts.
- Transport Management:Route optimization matrices serve fleet operators managing cross-border logistics corridors.
- Emergency Services:Georeferenced dispatch systems coordinate response routing for municipal public safety departments.
Retail analytics leads on scale; urban planning leads on momentum as smart city mandates accelerate.
Technology:
Integration complexity separates incumbent platforms from emerging sensor modalities.
- Geographic Information System:Core spatial data infrastructure supports layering, visualization, and demographic overlay analysis. South African retail banks maintain decades-old core banking infrastructure that resists API-based connectivity, creating integration bottlenecks for modernization projects.
- Bluetooth Beacons:Proximity-based indoor positioning enables sub-meter accuracy for retail environments where GPS signals degrade. Mall operators in Abu Dhabi deploy dense beacon grids for precision footfall tracking.
- GPS:Satellite-derived positioning dominates outdoor fleet tracking despite accuracy limitations in dense urban environments like Cairo and Lagos.
- RFID:Asset tagging systems support supply chain visibility for logistics operators managing container movements.
Geographic Information System retains installed base dominance; Bluetooth beacons gain share fastest through retail digitization.
End User:
Budget authority decentralization is reshaping procurement patterns across organizational hierarchies.
- Government:Municipal and federal agencies drive anchor demand through smart city infrastructure mandates. Saudi Arabia's National Data Management Office classification standards mandate tiered containment protocols, forcing sovereign cloud procurement through pre-qualified vendor lists.
- Transportation:Fleet operators and logistics providers prioritize real-time tracking precision for cross-border route optimization.
- Retail:Marketing-controlled technology budgets enable direct vendor relationships outside enterprise software committees.
- Telecommunications:Nigerian and Kenyan firms install analytics nodes at base station infrastructure to reduce backhaul expenditure, expanding hardware-software bundle demand.
Government contracts anchor revenue stability; telecommunications represents the steepest expansion trajectory through edge densification investments.
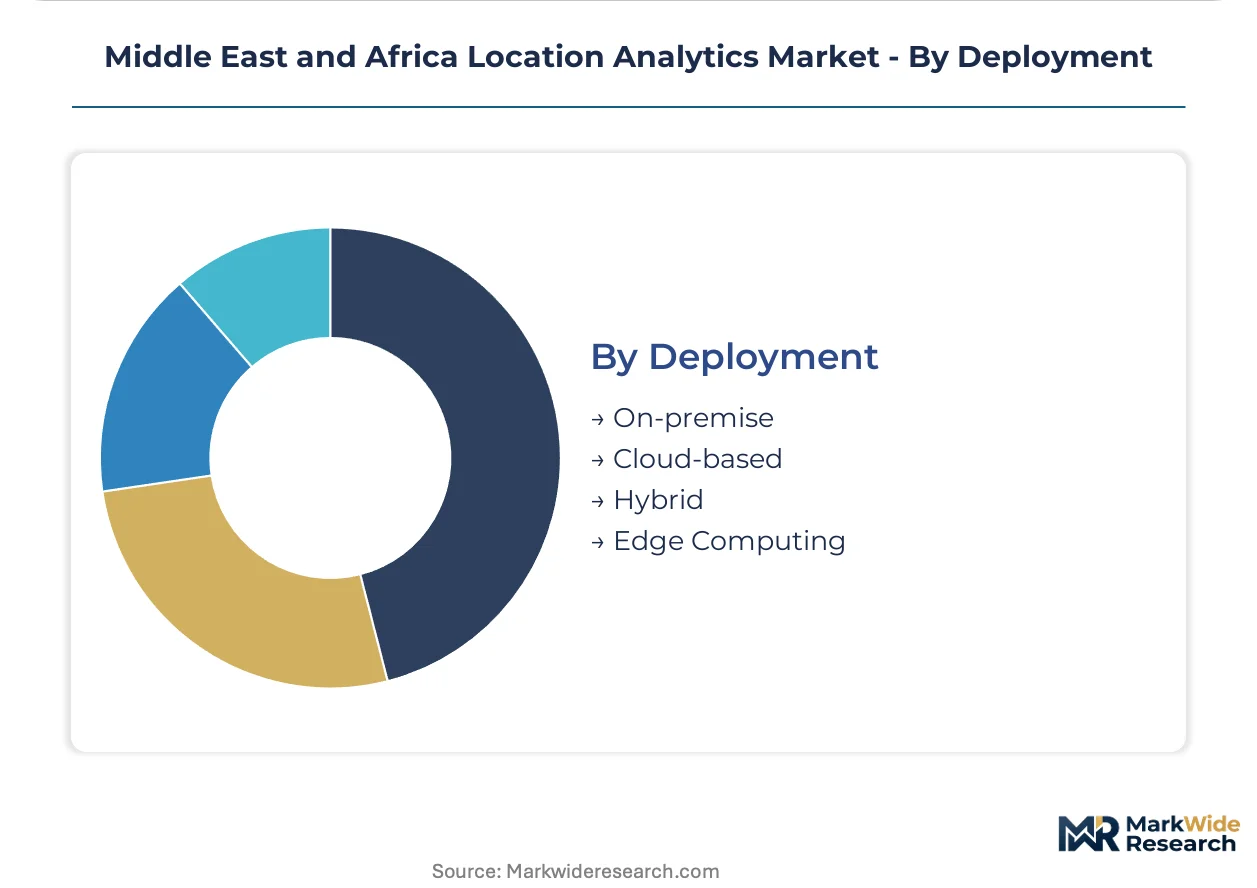
Deployment:
Latency requirements and data residency rules determine architecture selection across buyer organizations.
- Cloud-based:Gulf-based data center investments reduce latency for real-time fleet and asset tracking applications. The UAE's Telecommunications and Digital Government Regulatory Authority mandates sovereign data residency for government contracts, restricting pure public cloud delivery for certain federal applications.
- Edge Computing:Analytics nodes deployed at telecommunications base stations compress processing distance to sensor sources. Kenyan and Nigerian operators lead regional adoption to manage bandwidth costs.
- Hybrid:Configurations blend on-premise containment for sensitive datasets with cloud scalability for non-critical workloads.
- On-premise:Full local infrastructure satisfies Saudi Arabia's strictest geospatial data classification tiers.
Cloud-based deployment retains volume leadership; edge computing climbs the fastest as telecommunications infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa location analytics sector traces its commercial roots to South African mining GIS deployments in the 1990s, later scaling through UAE smart city investments and Gulf telecommunications infrastructure digitization.
United Arab Emirates
Dubai's Roads and Transport Authority anchors regional demand through digital twin contracts for metro expansion planning. The Telecommunications and Digital Government Regulatory Authority mandates sovereign data residency for federal contracts, restricting pure public cloud delivery. Abu Dhabi's mall operators deploy dense Bluetooth beacon grids for precision footfall analytics, bypassing traditional IT procurement channels.
Saudi Arabia
The National Data Management Office issues classification standards determining which geospatial datasets require on-premise containment, inflating capital deployment budgets. Riyadh's municipal government drives smart city infrastructure mandates for traffic flow optimization and utility network management. The Saudi Data and Artificial Intelligence Authority maintains pre-qualified vendor lists for defense and critical infrastructure procurement.
South Africa
Retail banking and telecommunications procurement cycles prioritize POPIA-compliant vendors for consumer location data governance. Johannesburg mall operators and quick-service restaurant chains deploy heat mapping for tenant mix optimization. Cape Town-based system integrators compete for limited pools of professionals combining Python-based spatial analysis with regulatory interpretation.
Nigeria
Telecommunications firms install analytics nodes at base station infrastructure to reduce backhaul expenditure, expanding hardware-software bundle demand for equipment suppliers. Lagos dense urban environments degrade GPS signal reliability, constraining fleet tracking precision for logistics operators. The national communications commission shapes data localization expectations for cloud-dependent analytics platforms.
Kenya
Telecommunications edge densification investments position the country as the steepest expansion trajectory for analytics node deployment. Nairobi-based agricultural digitization initiatives apply satellite-derived vegetation indices for smallholder crop monitoring, offering first-mover positioning for precision agriculture providers. The communications authority regulates data residency frameworks for cross-border analytics service delivery.
Middle East and Africa Location Analytics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment architecture complexity, with sovereign cloud capabilities commanding pricing power against standardized SaaS offerings. The vendor base organizes into three strategic archetypes: hyperscale cloud platforms anchoring hybrid conversations, enterprise software incumbents integrating geographic information system modules into broader stacks, and specialized location intelligence vendors competing on sector-specific analytics depth. Dominant competitive moves include mandatory local partnership structures for federal contract eligibility in Saudi Arabia and direct departmental contracting authority bypassing centralized IT procurement in retail verticals.
Within the enterprise software tier, Esri occupies a foundational position as the archetypal geographic information system specialist, while Microsoft and Oracle exemplify cloud-database integration strategies that sustain enterprise stickiness. SAP represents the embedded-module approach within broader enterprise resource planning deployments. These three anchors illustrate divergent paths to market participation: pure-play specialization, platform ecosystem leverage, and suite integration respectively.
| Leading Market Players |
|---|
| Esri |
| Microsoft |
| Oracle |
| Cisco |
| IBM |
| SAP |
| Precisely |
| TomTom |
| Others |
Supply & Pricing Matrix
Sovereign wealth fund-backed data center operators in the UAE and Saudi Arabia anchor capital deployment, compressing pricing power for foreign software vendors while elevating margin capture for domestic infrastructure partners. This financing pattern concentrates supply-side leverage within Gulf Cooperation Council borders, forcing multinational analytics providers to absorb localization costs or cede federal contract eligibility.
Pricing Analysis
Subscription-based tiering across sovereign cloud, hybrid, and pure SaaS levels dominates vendor pricing architecture. Price differentiation rests on data residency certification grade and edge node proximity to buyer infrastructure. Cost compression in standardized SaaS tiers intensifies as hyperscale cloud platforms absorb margin through volume bundling. Government procurement committees in Riyadh and Dubai exhibit lowest price sensitivity; Kenyan agricultural cooperatives and Nigerian logistics SMEs face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements embedded in UAE federal contracting mandate redundant qualification of analytics hardware suppliers across domestic and international vendor pools. Component concentration centers on semiconductor fabrication in Taiwan, sensor manufacturing in South Korea, and edge server assembly in China. Single-source vulnerability runs through Egypt's Suez Canal corridor for subsea connectivity to European cloud regions. Distribution feeds from hyperscale distributor networks into system integrator channels serving municipal and federal buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa location analytics sector compounds steadily as sovereign data mandates perpetuate infrastructure replacement cycles across Gulf municipal governments.
For Market Incumbents: To counter disintermediation by specialized retail analytics vendors, Esri and Microsoft should deepen API connectivity investments for South African retail banking core systems. SAP can fortify position through embedded geographic information system certification under Saudi Data and Artificial Intelligence Authority pre-qualification protocols. For New Entrants and Emerging Players: The mid-market gap between premium sovereign cloud deployments and economy-tier SaaS offerings creates entry space for edge-native specialists targeting Kenyan agricultural digitization and Nigerian telecommunications infrastructure. Precision agriculture analytics for smallholder crop monitoring remains the most penetrable white-space segment. For Investors and Strategic Acquirers: Hyperscale cloud platforms are the most active acquirer in this space, consolidating specialized location intelligence vendors to anchor hybrid deployment conversations. Long-term viability hinges on regulatory compliance capabilities rather than feature differentiation. The signal to watch is POPIA enforcement intensity in South African retail banking procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | UAE Telecommunications and Digital Government Regulatory Authority mandates create dedicated federal contracting vehicles for compliant domestic operators. |
| Edge Node Deployment | Nigerian and Kenyan telecommunications firms reduce backhaul expenditure through base station analytics infrastructure expansion. |
| API Modernization for Legacy ERP | South African retail banks require connectivity bridges between decades-old core banking systems and modern geographic information system modules. |
| Precision Agriculture Platform Launch | Satellite-derived vegetation indices for Kenyan smallholder crop monitoring remain underpenetrated versus Gulf urban applications. |
| Digital Twin Integration Partnership | Dubai Roads and Transport Authority metro expansion planning absorbs capital from static geographic information system license budgets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal chief data officers, telecommunications infrastructure planners, retail bank procurement leads, and system integrator technical directors with secondary validation against UAE Telecommunications and Digital Government Regulatory Authority filings, Saudi National Data Management Office standards, South African Information Regulator POPIA guidance, and hyperscaler capex disclosures. Bottom-up deployment volume estimates and top-down market sizing triangulated across data center operator investments and vendor revenue attribution.
Historical reference periods anchored the projection horizon to observed adoption curves across smart city infrastructure buildouts, telecommunications edge densification waves, and retail analytics procurement cycles. The analytical framework modeled deployment architecture, end-user vertical, application complexity, and regional regulatory cluster as primary segmentation dimensions. CAGRs derived from fitted growth curves applied to infrastructure investment trajectories and software penetration rates within government, telecommunications, and retail verticals.
The model assumes a particular technology adoption path; alternative pathways for edge-native processing architectures would alter the outlook if latency requirements shift or backhaul costs collapse. Forecasts reflect assumptions around sovereign data mandate persistence and telecommunications infrastructure investment continuity. Deviation in Gulf Cooperation Council data localization decree enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Document Analytics Market
Analytics
Global Social Intelligence Market
Analytics
Big Data in Automotive Market
Analytics
Load (ETL) Market
Analytics
Global in-Store Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Global Enterprise Performance Management Market
Analytics
Israel Geospatial Analytics Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Behavior Analytics Market
Analytics
Emotion Analytics Market
Analytics
Procurement Analytics Market
Analytics
Capacity Management Analytics Market
Analytics
United States Geospatial Analytics Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Active Data Warehousing Market