
 SME Big Data Market | 2026-2036
SME Big Data Market Size, Share, and Industry Trends Forecast 2026-2036
SME Big Data Market Analytics
Enterprise-grade analytics tier is reorganizing competitive dynamics across the SME Big Data landscape. Sisense leverages embedded analytics architectures to deepen dashboard penetration in mid-market software ecosystems. ScienceSoft anchors its position through intensive R&D in hybrid deployment frameworks. Innowise Group competes on geographic dominance across Eastern European delivery corridors.
SME big data encompasses distributed data architectures, streaming ingestion pipelines, and cloud-native storage systems processing terabyte-scale operational datasets for commercial decision-making. Cloud deployment leads solution uptake as subscription economics displace capital-intensive on-premises infrastructure; predictive analytics commands premium positioning due to specialized machine-learning engineering requirements. Data management functions mature fastest where standardization reduces implementation friction, while data visualization extracts margin pools through user-experience differentiation.
FDA guidelines on algorithmic transparency in healthcare analytics, EU GDPR data-localization mandates, and India's BIS cloud security standards collectively shape product certification pathways and cross-border service eligibility. Stakeholders must monitor evolving compliance thresholds to sustain platform access across regulated end-user verticals.
Market Dynamics
Cloud-first mandates from EU data sovereignty rules are reorganizing vendor qualification criteria across the SME Big Data landscape, forcing platform providers to rebuild certification pathways around localized infrastructure requirements.
Growth Catalysts
- EU GDPR Localization Mandates:Data residency requirements in Europe accelerate procurement of region-housed analytics infrastructure among mid-market enterprises.
- India MSME Digitization Programs:Government-backed platform subsidies compress adoption timelines for cloud-native data warehouses among small manufacturers.
- Real-Time Inventory Analytics:Retail chains deploy streaming pipelines to sharpen operational decisions and reduce carrying costs.
Market Restraints
- Specialized ML Engineering Scarcity:Predictive analytics tier commands premium positioning due to concentrated talent pools in select urban technology corridors.
- Hybrid Deployment Complexity:Technical limitations in seamless workload portability between on-premises and cloud environments extend implementation cycles.
- Algorithmic Transparency Requirements:FDA guidelines for healthcare analytics create certification friction that delays platform deployment in regulated clinical settings.
Strategic Opportunities
- Underpenetrated Eastern European Corridors:Delivery networks spanning Poland, Romania, and Bulgaria offer geographic white space for platform localization.
- EU AI Act Compliance Services:Emerging demand for audit-ready analytics frameworks creates adjacent revenue streams for certification-support vendors.
- Edge-Cloud Convergence:Streaming ingestion pipelines combined with distributed storage architectures enable latency-sensitive use cases in manufacturing.
Industry Challenges
- Data Visualization Talent Gap:User-experience differentiation requires scarce design-engineering hybrids capable of building intuitive dashboard interfaces.
- Legacy System Integration Friction:Terabyte-scale operational datasets often reside in incompatible formats that complicate migration to cloud-native architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SME Big Data Market |
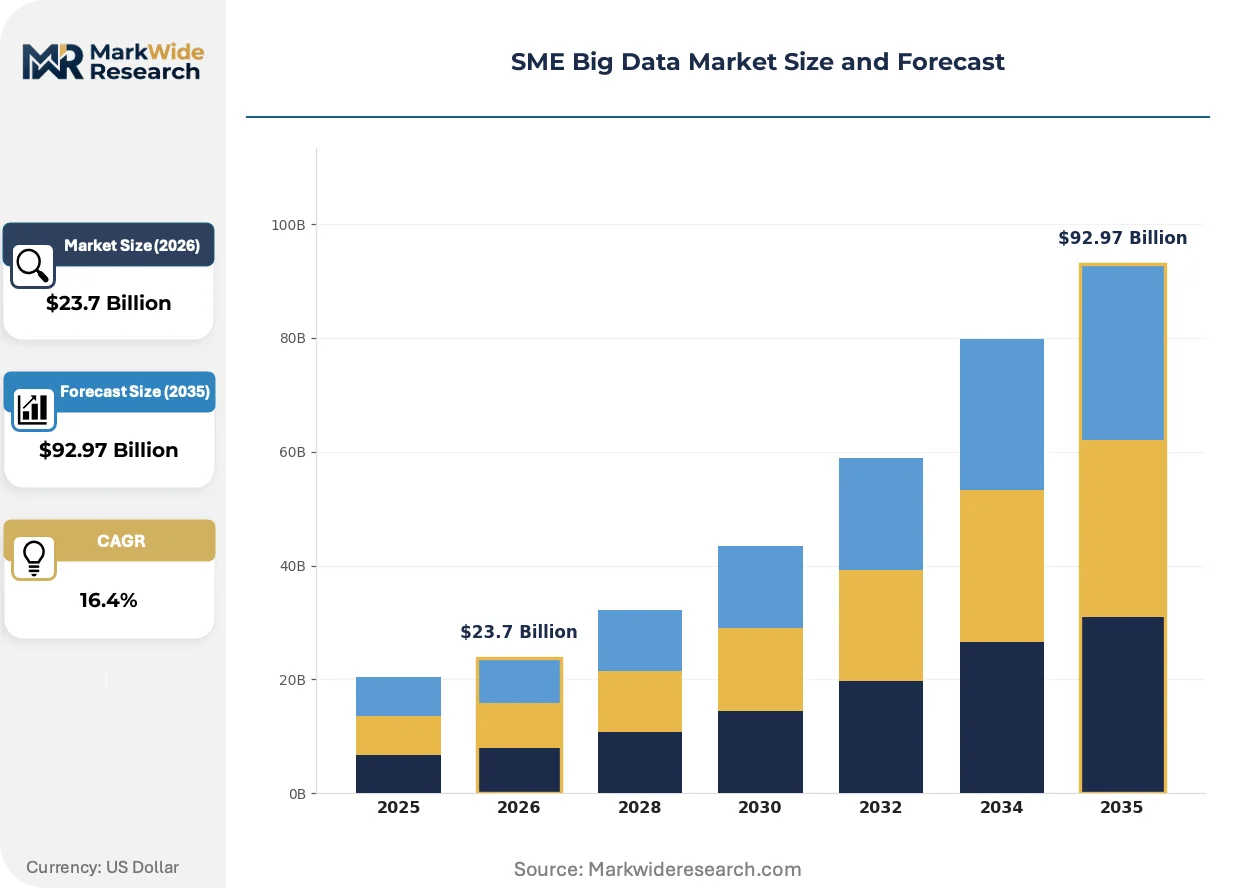
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $92.97 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Edge Solution: Data Analytics, Data Management, Data Visualization, Predictive Analytics End User: Retail, Healthcare, Manufacturing, Financial Services Application: Customer Insights, Risk Management, Operational Efficiency, Market Analysis |
| Companies Covered | DataToBiz, Innowise Group, Entrans, Talentica Software, Sigma Data Systems, SG Analytics, ScienceSoft, instinctools, Sisense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SME Big Data Market Evolving Landscape
Embedded analytics architectures are penetrating mid-market software ecosystems, reshaping how smaller enterprises consume intelligence without standalone platform investments.
Serverless query engines are displacing provisioned cluster models across the SME Big Data stack. Mid-market SaaS vendors embed these engines to offer pay-per-scan economics that eliminate upfront infrastructure commitments. This displacement is compressing pricing power among traditional warehouse providers and forcing subscription model reinvention.
India's BIS cloud security standards are mandating encryption protocols and access controls that exceed baseline international frameworks. Platform providers must rebuild certification documentation to satisfy these requirements. Healthcare and financial services verticals in Mumbai and Bangalore face the steepest compliance ramps.
Consumption-based billing models are replacing fixed-term contracts in analytics procurement. Channel partners unbundle implementation services from software licensing to capture margin from deployment complexity. Germany's Mittelstand manufacturers exhibit the strongest preference for this flexibility, driving vendor pricing architecture redesigns.
SME Big Data Market Segmentation
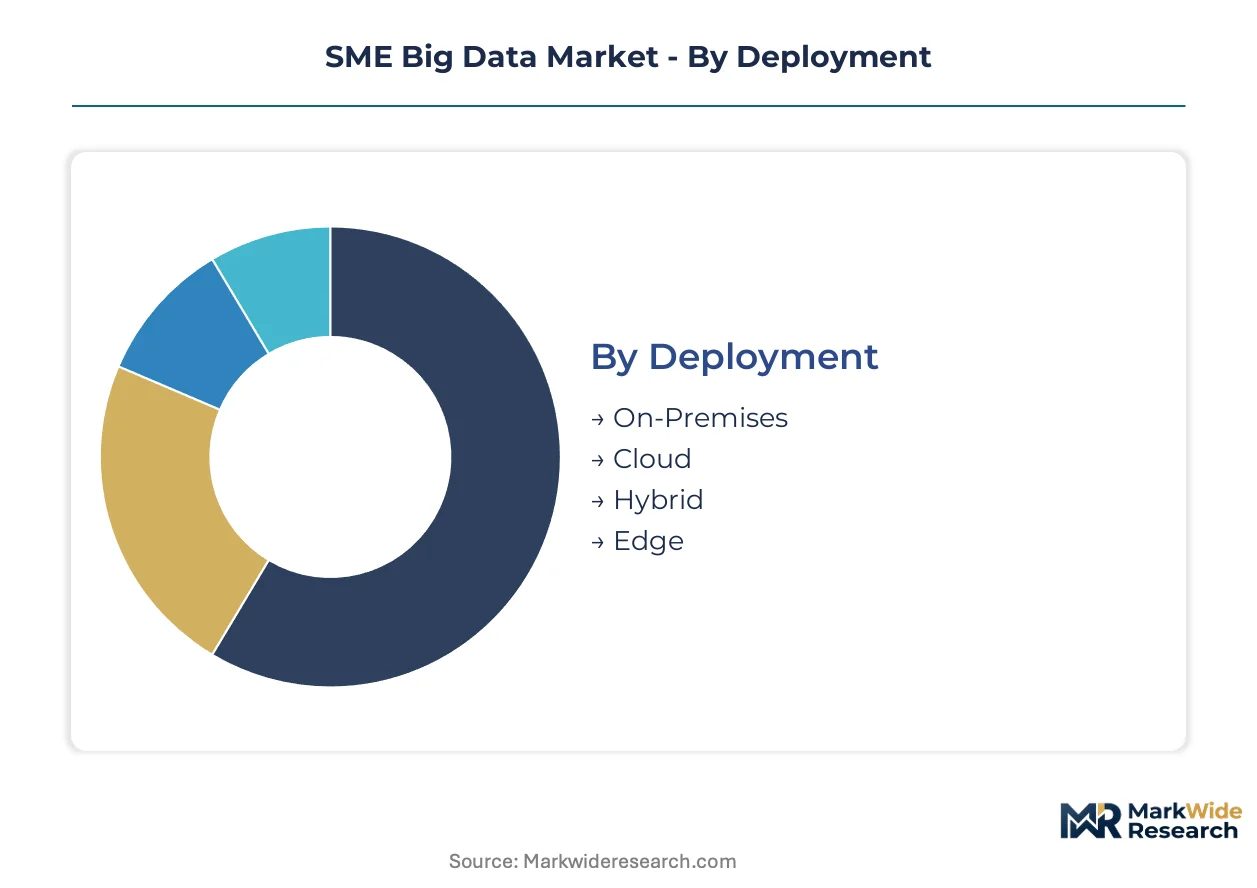
Segmentation in the SME Big Data Market exposes how infrastructure choices, solution types, and vertical applications concentrate procurement budgets. Deployment architecture and end-user verticals drive the steepest differentiation in platform requirements and vendor qualification pathways.
Deployment:
Cloud deployment faces substitution pressure from edge architectures as latency-sensitive use cases demand localized processing power.
- On-Premises:Capital-intensive infrastructure requiring dedicated hardware stacks and in-house systems administration. German Mittelstand manufacturers sustain demand here due to data sovereignty preferences and legacy system dependencies that resist cloud migration.
- Cloud:Subscription-based consumption of elastic compute and storage resources through hyperscaler or specialized analytics platforms. Indian MSME digitization programs channel government subsidies toward cloud-native procurement, compressing adoption timelines for small manufacturers in Mumbai and Bangalore industrial corridors.
- Hybrid:Workload portability across on-premises and cloud environments with orchestration layers managing data gravity constraints.
- Edge:Distributed processing nodes positioned proximal to data generation sources, enabling real-time inference without round-trip latency to centralized facilities.
Cloud deployment anchors the volume base while edge architectures gain share at the steepest rate.
Solution:
Cost tier stratification separates commoditized data management from premium predictive analytics requiring scarce machine-learning engineering talent.
- Data Analytics:Descriptive and diagnostic processing of historical operational datasets through SQL-based query engines and business intelligence dashboards. Retail chains across Poland and Romania deploy these capabilities for inventory optimization and demand forecasting.
- Predictive Analytics:Machine-learning models forecasting future states from pattern recognition in training datasets, commanding premium positioning due to specialized engineering requirements concentrated in urban technology corridors.
- Data Management:Governance, quality assurance, and lineage tracking functions standardizing ingestion pipelines and storage architectures.
- Data Visualization:Front-end interface layers translating complex datasets into consumable graphical representations, extracting margin pools through user-experience differentiation.
Data management functions anchor the volume base while predictive analytics climbs the fastest as vertical-specific model demand intensifies.
End User:
Application maturity varies sharply by vertical, with healthcare and financial services facing the steepest compliance ramps under sector-specific regulations.
- Retail:Real-time inventory analytics and customer segmentation driving streaming pipeline investments. EU GDPR localization mandates force mid-market chains toward region-housed infrastructure, reshaping vendor qualification criteria across German, French, and Italian procurement offices.
- Healthcare:Clinical analytics and population health management subject to FDA algorithmic transparency guidelines that create certification friction delaying platform deployment.
- Manufacturing:Operational efficiency and predictive maintenance applications leveraging sensor data from production lines.
- Financial Services:Risk management and fraud detection workloads governed by RBI and SEBI data localization requirements in India, with comparable mandates from ECB-affected jurisdictions in Europe.
Retail anchors the volume base while healthcare expands most quickly despite regulatory headwinds.
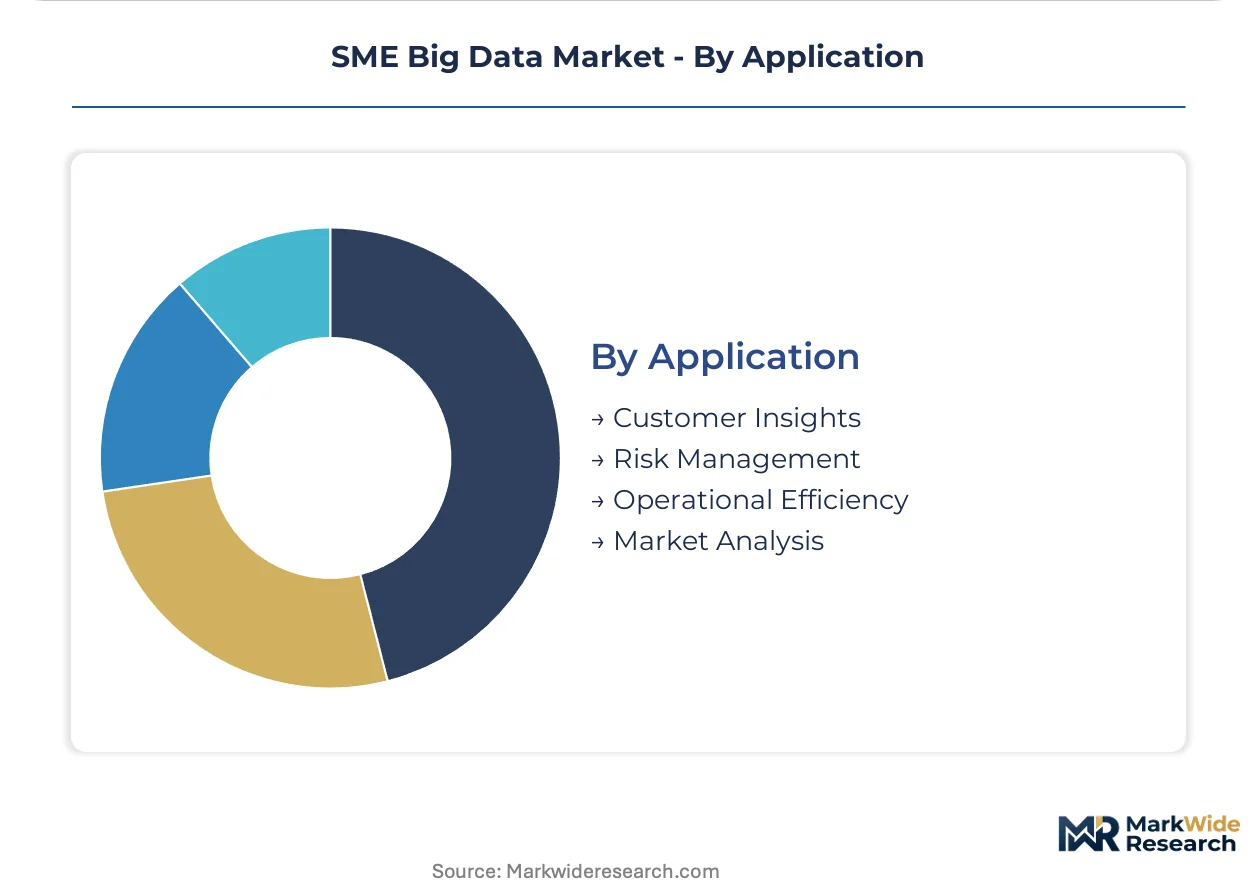
Application:
Customer-facing use cases concentrate procurement budgets as competitive pressure forces differentiation through data-driven engagement.
- Customer Insights:Behavioral segmentation and preference modeling enabling personalized engagement strategies. Bulgarian and Romanian e-commerce platforms invest here to close the gap with Western European competitors.
- Operational Efficiency:Process optimization and resource allocation analytics reducing unit costs in production and logistics environments.
- Risk Management:Credit scoring, fraud detection, and compliance monitoring applications subject to stringent regulatory oversight.
- Market Analysis:Competitive intelligence and trend identification supporting strategic planning and new market entry decisions.
Operational efficiency anchors the volume base while customer insights shows the steepest expansion trajectory as personalization becomes table stakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers exhibit the highest price elasticity as government subsidies compress procurement budgets, while German Mittelstand manufacturers sustain premium tolerance due to data sovereignty mandates. This demand-elasticity contrast shapes vendor pricing architectures across regional deployment strategies.
United States
Healthcare analytics and retail personalization drive platform investments among mid-market enterprises. FDA algorithmic transparency guidelines create certification friction that delays deployment in clinical settings. Boston and San Francisco technology corridors concentrate specialized machine-learning engineering talent for predictive analytics development.
Germany
Industrial automation and Mittelstand manufacturing sustain on-premises infrastructure preferences despite cloud migration pressure. EU GDPR data-localization mandates force region-housed analytics procurement across procurement offices in Munich and Stuttgart. Baden-Württemberg automotive suppliers deploy edge architectures for latency-sensitive production line monitoring.
India
MSME digitization programs channel government subsidies toward cloud-native data warehouse adoption among small manufacturers. BIS cloud security standards mandate encryption protocols exceeding baseline international frameworks. Mumbai and Bangalore industrial corridors face the steepest compliance ramps for healthcare and financial services verticals.
United Kingdom
Financial services risk management and fraud detection workloads anchor demand among London-based mid-market institutions. FCA operational resilience requirements intersect with EU GDPR legacy obligations for data governance architecture. Southeast England technology clusters concentrate embedded analytics vendors serving SaaS ecosystems.
Poland
Retail chains and e-commerce platforms invest in customer segmentation and inventory optimization capabilities. EU AI Act compliance services create adjacent revenue opportunities for audit-ready framework providers. Warsaw and Krakow delivery corridors attract platform localization investments from Eastern European service providers.
SME Big Data Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the SME Big Data landscape, producing a tiered competitive structure rather than consolidated dominance. Specialized analytics vendors compete against full-service consultancies on implementation depth versus geographic coverage. Three archetypes dominate: embedded analytics specialists, hybrid deployment engineers, and geographic delivery networks. Competitive moves concentrate on strategic partnerships for technology access and geographic expansion through delivery corridor establishment.
Among the embedded analytics tier, Sisense occupies a position exemplifying dashboard penetration strategies in mid-market software ecosystems. ScienceSoft and Innowise Group represent contrasting archetypes—ScienceSoft anchors intensive R&D positioning in hybrid deployment frameworks, while Innowise Group exemplifies geographic dominance across Eastern European delivery corridors. These three players illustrate how vendor qualification criteria diverge based on buyer priorities around localization, integration depth, or specialized engineering access.
| Leading Market Players |
|---|
| DataToBiz |
| Innowise Group |
| Entrans |
| Talentica Software |
| Sigma Data Systems |
| SG Analytics |
| ScienceSoft |
| instinctools |
| Sisense |
| Others |
Value Network & Pricing Analysis
EU GDPR data-localization mandates gate both vendor qualification and price differentiation across the SME Big Data landscape, forcing platform providers to absorb regional infrastructure costs while buyers in Germany and France pay premiums for certified compliance.
Pricing Analysis
Implementation services and extended support contracts drive lifetime value in analytics procurement. Consumption-based billing models are displacing fixed-term contracts as German Mittelstand manufacturers demand pay-per-scan flexibility. Price differentiation hinges on certification grade under FDA and BIS frameworks and vertical integration depth into cloud infrastructure. Cost compression in commoditized data management tiers is intensifying because serverless query engines eliminate provisioned cluster economics. Indian MSMEs exhibit the highest price elasticity, while German automotive suppliers sustain premium tolerance for edge-deployment sovereignty.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for hardware-dependent edge deployments. Cloud infrastructure concentrates in the United States, India, and Germany, with hyperscaler regions anchoring elastic compute supply. Specialized GPU accelerators and encrypted storage modules constitute critical component dependencies. Single-source vulnerability around NVIDIA AI silicon creates procurement risk for predictive analytics tier providers. Distribution runs through hyperscaler marketplaces and systems integrator channels with geographic delivery specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SME Big Data market is recovering from a cyclical trough as delayed cloud migrations resume and government digitization subsidies unlock frozen procurement budgets.
For Market Incumbents: Shield embedded analytics market share by deepening dashboard penetration in mid-market SaaS ecosystems against standalone platform substitutes. Prioritize certification investment under India's BIS cloud security standards to defend access to Mumbai and Bangalore healthcare verticals. Build backward integration into localized infrastructure to offset GDPR-mandated data residency cost inflation. For New Entrants and Emerging Players: Anchor in underpenetrated Eastern European delivery corridors spanning Poland, Romania, and Bulgaria where geographic white space remains for platform localization. Target EU AI Act compliance services as an adjacent revenue stream with audit-ready analytics frameworks. Pursue channel partnerships with Warsaw and Krakow systems integrators to bypass direct enterprise sales friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across serverless and consumption-based deployment models, compressing working capital requirements for scaled platforms. Long-term viability favors acquisition targets with hybrid deployment engineering capabilities and established certification pathways under FDA or BIS regimes. Monitor hyperscaler capex allocation shifts as the inflection signal for infrastructure supply-demand rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Audit-ready frameworks unlock regulated healthcare and financial services procurement in Frankfurt and Paris. |
| Hybrid Deployment Engineering | Workload portability between on-premises and cloud environments addresses German Mittelstand sovereignty requirements. |
| Edge-Cloud Convergence Partnership | Streaming pipelines with distributed storage enable latency-sensitive manufacturing analytics in Baden-Württemberg. |
| Embedded Analytics Integration | Dashboard penetration in mid-market SaaS ecosystems displaces standalone platform investments. |
| Geographic Expansion into Eastern Europe | Delivery corridor establishment in Warsaw and Krakow captures retail and e-commerce platform demand. |
Research Methodology
The analysis maps cloud deployment architectures, predictive analytics tiers, and edge-processing frameworks, each validated through CTOs, IT procurement officers, platform engineers, and channel partners across the United States, Germany, and India. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, BIS certification registries, and EU regulatory databases establish demand-side and supply-side triangulation. Bottom-up segment sizing and top-down macroeconomic anchoring ensure consistency across modeling approaches.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models deployment model, organization size, vertical application, integration complexity, and regional adoption pattern as core segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to disclosed platform procurement timelines and government subsidy program trajectories. Industry-specific forecast inputs include MSME digitization program budget allocations and EU GDPR enforcement escalation patterns.
Material uncertainties — regulatory enforcement intensity, hyperscaler pricing architecture shifts, and talent pool concentration in machine-learning engineering — sit outside the modeled envelope. Forecasts reflect documented assumptions about subsidy program continuity and certification pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Edge Analytics Market
Analytics
Cloud-Based Predictive Analytics Platform Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
Global Social Intelligence Market
Analytics
Mobile Analytics Market
Analytics
Human Resource Analytics Market
Analytics
Datacenter Analytics Market
Analytics
Content Analytics Market
Analytics
Prescriptive Analytics Market
Analytics
UK Geospatial Analytics Market
Analytics
Assortment Analytics Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Document Analytics Market
Analytics
Global Recommendation Engine Market