
 India Geospatial Analytics Market | 2026-2036
India Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
India Geospatial Analytics Market Insights
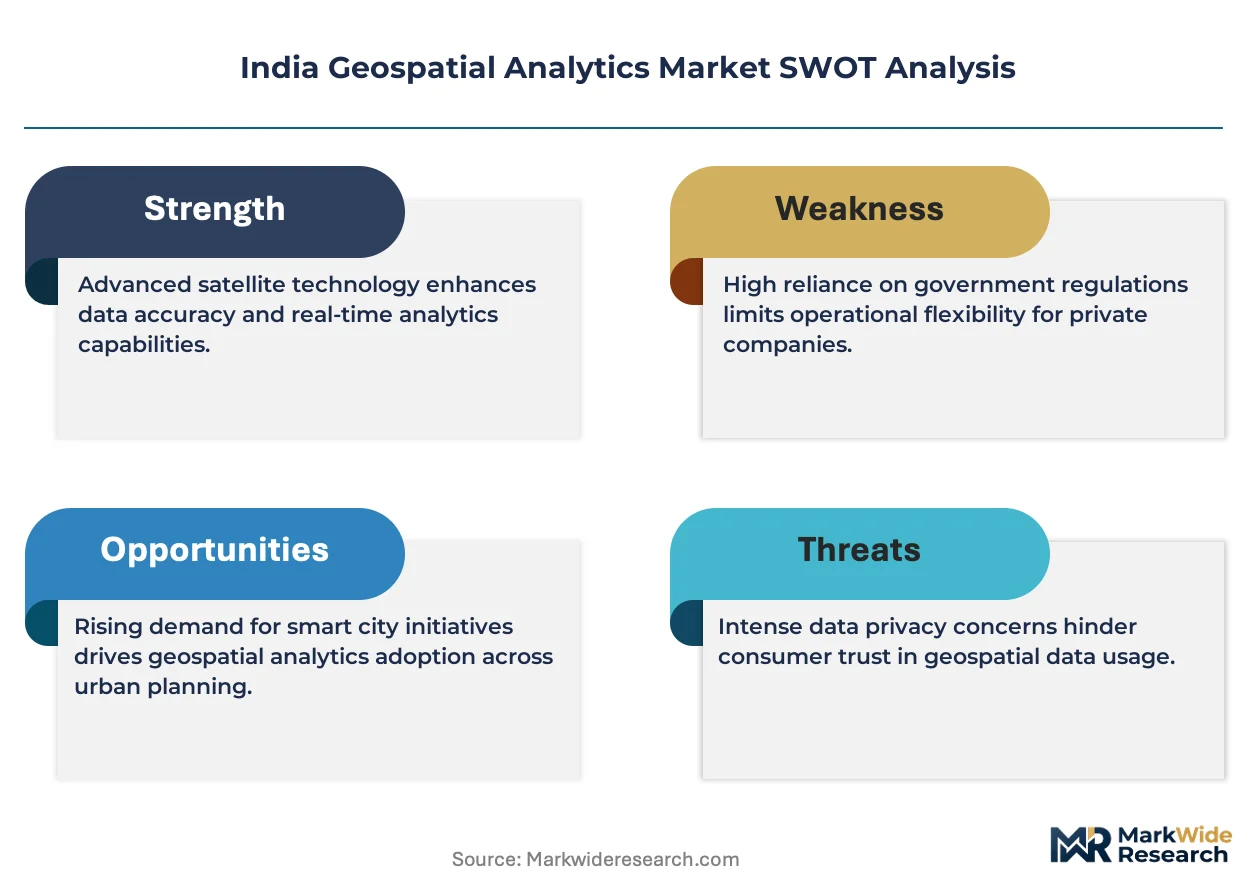
Platform bundling is rebalancing procurement patterns across Indian state governments and municipal corporations. MapmyIndia leverages its proprietary digital mapping database to anchor large-scale smart city contracts. Esri India Technologies Private Limited competes through deep integration with ArcGIS ecosystems and government training programs. RMSI specializes in photogrammetry and remote sensing services for infrastructure and disaster management clients.
Geospatial analytics encompasses the capture, storage, manipulation, analysis, and visualization of geographic data using satellite imagery, GPS coordinates, and spatial algorithms to generate location-intelligent insights for planning and operations. The technology stack processes raster and vector data through coordinate reference systems with sub-meter accuracy for cadastral and environmental applications. Remote Sensing and GIS together dominate the technology layer, with Image Processing gaining traction as drone-captured data volumes multiply across Agriculture and Environmental Monitoring applications. Cloud-Based deployment is expanding fastest among state government buyers, while On-Premise systems persist in defense and sensitive infrastructure sectors where data sovereignty requirements remain stringent.
BIS standards for geospatial data interoperability, combined with SVAMITVA scheme mandates from the Ministry of Panchayati Raj, are reshaping procurement specifications and vendor qualification criteria across state-level tenders. The Survey of India and DST guidelines on geospatial data liberalization are opening previously restricted topographic datasets to private analytics providers. Stakeholders must monitor how rapidly state governments shift from pilot drone surveys to operational recurring contracts for land administration and crop monitoring.
Market Dynamics
Platform bundling is rebalancing procurement patterns across Indian state governments and municipal corporations, as buyers consolidate vendor relationships around integrated mapping-database-analytics stacks rather than point solutions.
Growth Catalysts
- SVAMITVA scheme mandates:The Ministry of Panchayati Raj's drone-based land survey initiative is generating recurring demand for cadastral mapping services across rural Maharashtra and Karnataka.
- Drone data proliferation:Agriculture and environmental monitoring applications are multiplying captured imagery volumes, forcing investment in automated image processing pipelines.
- Smart city infrastructure:Tier-1 metros are embedding geospatial layers into urban planning workflows for traffic management, utilities, and disaster response.
Market Restraints
- Data sovereignty requirements:Defense and sensitive infrastructure sectors mandate on-premise deployment, blocking cloud-native vendors from classified contracts.
- Skill concentration:Photogrammetry and remote sensing expertise clusters in Delhi-NCR and Hyderabad, creating hiring bottlenecks for regional project execution.
- Interoperability friction:Legacy cadastral systems in state land revenue departments resist integration with modern GIS platforms, delaying digitization timelines.
Strategic Opportunities
- Tier-2 city expansion:Municipal corporations in Jaipur, Lucknow, and Coimbatore are initiating pilot smart city projects with lower vendor competition than saturated metros.
- AI-IoT convergence:Real-time sensor networks combined with spatial analytics are opening predictive maintenance contracts for utilities and transportation agencies.
- PLI scheme tailwinds:Production-linked incentives for drone manufacturing are reducing hardware costs for survey service providers.
Industry Challenges
- Cadastral data fragmentation:Village-level land records maintained in regional languages and non-standard formats require expensive manual cleansing before analytics deployment.
- Certification bottlenecks:BIS geospatial data interoperability standards are evolving faster than vendor compliance timelines, delaying contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Geospatial Analytics Market |
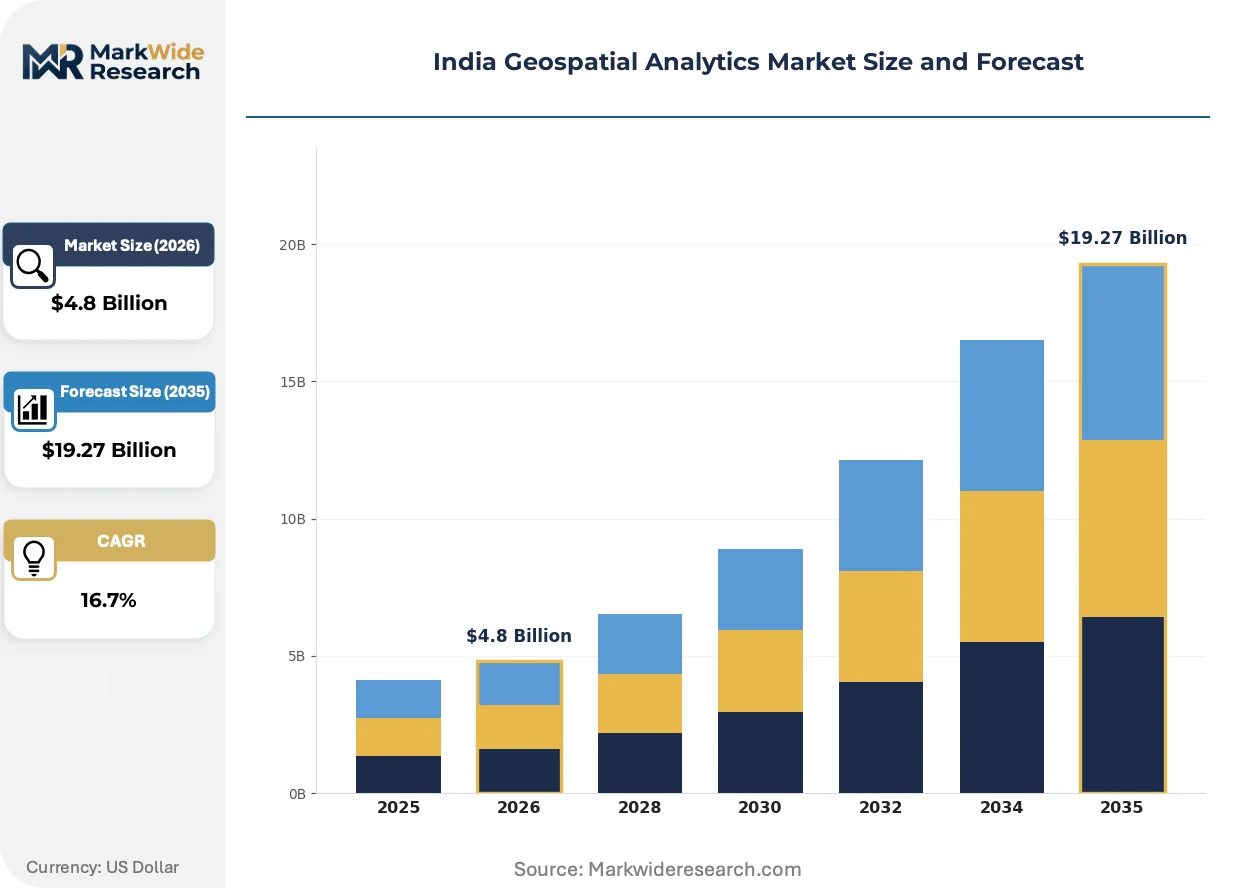
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GIS, Remote Sensing, Image Processing, Spatial Database Application: Urban Planning, Disaster Management, Agriculture, Environmental Monitoring End User: Government, Agriculture Sector, Transportation, Real Estate Deployment: Cloud-Based, On-Premise, Hybrid, Mobile |
| Companies Covered | Esri India Technologies Private Limited, MapmyIndia, RMSI, Google LLC, Hexagon AB, Trimble Inc., Genesys International, Precisely Holdings LLC, Cyient, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Geospatial Analytics Market Trends and Innovations
Cloud-native architectures are displacing legacy on-premise installations as state governments prioritize scalability over data localization, while regulatory liberalization accelerates private-sector access to previously restricted topographic datasets.
Digital twin technology is integrating satellite imagery, IoT sensor feeds, and 3D building models into unified urban simulation platforms. Municipal corporations in Bengaluru and Chennai are piloting these systems for flood modeling and traffic optimization. The technology is compressing planning cycles from months to weeks by enabling real-time scenario testing.
BIS standards for geospatial data interoperability are mandating standardized coordinate reference systems and metadata schemas across state-level tenders. Survey of India guidelines on data liberalization are opening 1:50,000 scale topographic maps to private analytics providers. Defense and intelligence agencies remain exempt, creating a two-tier access regime that shapes vendor specialization.
State government buyers are consolidating vendor relationships around multi-year managed service contracts with embedded training and data refresh obligations. Municipal corporations are replacing transactional project-based procurement with recurring subscriptions for base map maintenance and analytics dashboards. This shift is most visible in Maharashtra and Gujarat, where urban development authorities have issued five-year integrated mapping contracts.
India Geospatial Analytics Market Segmentation
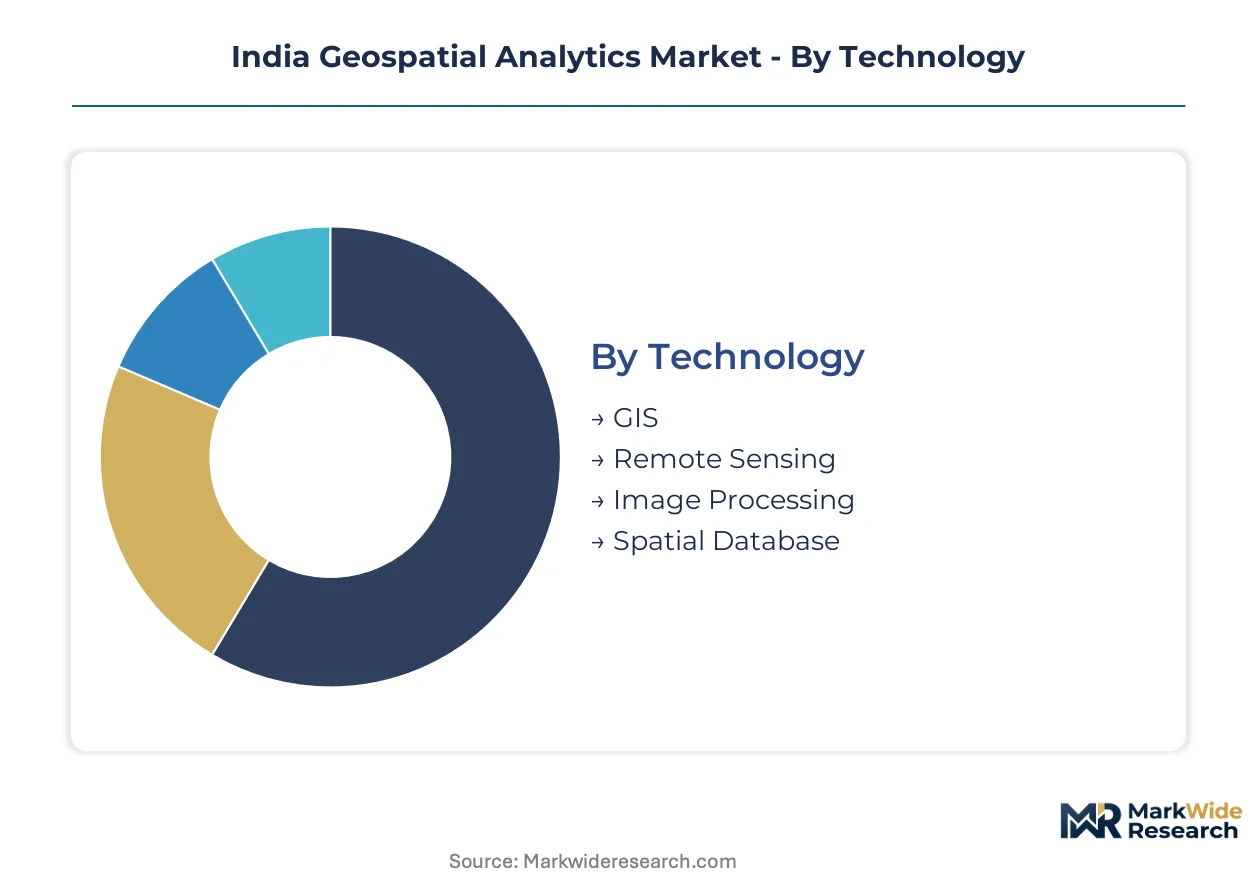
Segmentation reveals how procurement priorities diverge across Indian state governments, municipal corporations, and private infrastructure operators. Technology choices and deployment models reflect competing pressures between data sovereignty mandates and scalability imperatives.
Technology:
Legacy system replacement cycles are accelerating as state governments retire decade-old GIS installations that cannot process drone-captured imagery volumes.
- GIS:Spatial data management platforms anchor urban planning and cadastral mapping workflows across Maharashtra and Karnataka revenue departments. Demand concentrates in state-level smart city projects where BIS interoperability standards mandate standardized coordinate reference systems.
- Remote Sensing:Satellite imagery acquisition and analysis services process optical and synthetic aperture radar data for land use classification and change detection. SVAMITVA scheme mandates in rural districts are generating recurring contracts for high-resolution orthophoto generation.
- Image Processing:Automated pipelines for drone imagery orthorectification and feature extraction.
- Spatial Database:Enterprise-grade storage systems for vector and raster geospatial datasets.
Volume placements concentrate in GIS; the faster expansion belongs to Remote Sensing.
Application:
Cost tier differentiation separates pilot projects from operational deployments across state government budgets.
- Urban Planning:Zoning analysis, infrastructure siting, and development control systems integrate 3D city models with demographic overlays. Tier-1 metros in Delhi, Mumbai, and Bengaluru embed these layers into master plan revisions and building permission workflows.
- Disaster Management:Flood inundation mapping, cyclone track prediction, and post-event damage assessment leverage real-time satellite feeds. Coastal states in Odisha and Gujarat prioritize these capabilities following recurring cyclone impacts.
- Agriculture:Crop health monitoring and yield estimation through NDVI analysis and soil moisture mapping.
- Environmental Monitoring:Forest cover change detection, wetland delineation, and pollution source tracking for regulatory compliance.
Procurement volumes favor Urban Planning; Disaster Management is climbing the fastest as climate adaptation budgets expand.
End User:
Customer type determines deployment complexity and contract duration, with government buyers demanding multi-year managed service structures.
- Government:Central ministries, state revenue departments, and municipal corporations procure integrated mapping-database-analytics stacks under five-year contracts. The Ministry of Panchayati Raj's SVAMITVA scheme directs drone survey mandates to qualified vendors.
- Agriculture Sector:Cooperative societies and agribusiness operators subscribe to seasonal crop monitoring services. Punjab and Haryana irrigation departments pilot precision agriculture advisories based on satellite-derived soil moisture data.
- Transportation:Highway authorities and logistics operators require route optimization and asset tracking capabilities.
- Real Estate:Developers and property consultants utilize location intelligence for site selection and market analysis.
Contract value concentrates with Government end users; Agriculture Sector subscriptions are gaining share fastest as PLI scheme subsidies reduce drone survey costs.
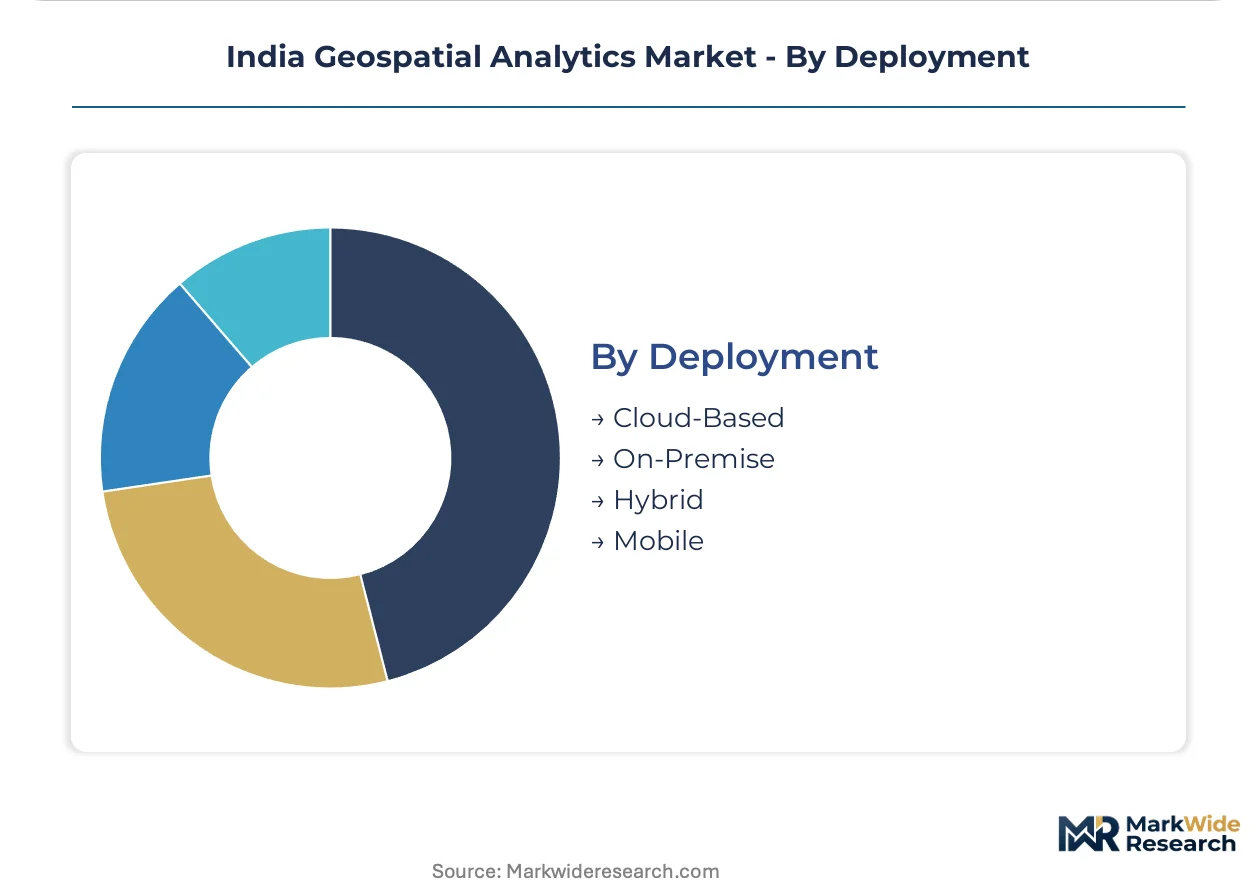
Deployment:
Maturity gradients separate early cloud adopters from conservative on-premise holdouts in sensitive infrastructure sectors.
- Cloud-Based:Scalable SaaS platforms eliminate capital expenditure for state governments with variable survey volumes. Municipal corporations in Gujarat and Tamil Nadu favor this model for smart city dashboards requiring elastic compute during monsoon response periods.
- On-Premise:Air-gapped installations satisfy defense and intelligence agency data sovereignty requirements. Survey of India and Ministry of Defence contracts explicitly exclude cloud-native vendors from classified topographic mapping tenders.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud analytics for non-classified workloads.
- Mobile:Field data collection applications for ground truthing and asset inspection.
Installation base tilts toward Cloud-Based; Hybrid deployments show the steepest expansion trajectory as state governments balance sovereignty concerns with cost efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of geospatial analytics services clusters in Delhi-NCR and Hyderabad where photogrammetry expertise concentrates, while consumption spreads across state revenue departments and municipal corporations executing SVAMITVA mandates and smart city contracts.
Maharashtra
Urban development authorities in Mumbai and Pune drive demand for 3D city modeling and traffic optimization dashboards. The state revenue department's integration of BIS interoperability standards into cadastral tenders accelerates vendor qualification cycles. Nagpur and Nashik municipal corporations are piloting drone-based property tax assessment systems under five-year managed service structures.
Karnataka
Bengaluru's municipal corporation embeds geospatial layers into building permission workflows and master plan revisions. State-level smart city projects in Mysuru and Hubli-Dharwad prioritize flood modeling capabilities following monsoon infrastructure damage. The Karnataka State Remote Sensing Applications Centre anchors technical capacity for satellite imagery interpretation serving agriculture and forestry departments.
Gujarat
Surat and Ahmedabad urban development authorities issue recurring subscriptions for base map maintenance rather than transactional project contracts. The state's coastal vulnerability mapping programs leverage real-time satellite feeds for cyclone preparedness. Gandhinagar-based state data centers host hybrid cloud-on-premise architectures balancing sovereignty with cost efficiency.
Tamil Nadu
Chennai's digital twin pilots integrate IoT sensor networks with spatial analytics for predictive flood management. State highways and minor ports departments procure route optimization and asset tracking capabilities from qualified vendors. Coimbatore and Madurai municipal corporations initiate smart city projects with lower vendor competition than saturated tier-1 metros.
Telangana
Hyderabad's geospatial technology park concentrates photogrammetry and remote sensing service providers serving national infrastructure clients. The state's drone survey mandates for land record digitization generate recurring contracts for high-resolution orthophoto generation. Ranga Reddy and Medchal districts pilot precision agriculture advisories based on satellite-derived soil moisture data.
India Geospatial Analytics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement cycles for state government and municipal contracts. The vendor base organizes around three strategic archetypes: mapping-database integrators anchoring smart city platforms, remote sensing specialists serving infrastructure and disaster management clients, and global technology licensors competing through ecosystem lock-in. Competitive moves concentrate on multi-year managed service contract capture and embedded training obligations that raise switching costs.
Among India-based specialists, MapmyIndia leverages proprietary digital mapping assets to anchor large-scale municipal contracts, while RMSI occupies a position exemplifying photogrammetry and remote sensing capabilities for infrastructure applications. Esri India Technologies Private Limited represents the global-licensor archetype, competing through deep ArcGIS ecosystem integration and government capacity-building programs.
| Leading Market Players |
|---|
| Esri India Technologies Private Limited |
| MapmyIndia |
| RMSI |
| Google LLC |
| Hexagon AB |
| Trimble Inc. |
| Genesys International |
| Precisely Holdings LLC |
| Cyient |
| Others |
Pricing and Supply Chain Analysis
Captive integration into drone manufacturing through PLI scheme subsidies anchors supply positioning for survey service providers while compressing hardware procurement costs and expanding margin capture on recurring cadastral mapping contracts.
Pricing Analysis
Cost-down pressure on cloud-native SaaS tiers accelerates as state governments consolidate vendor relationships around five-year managed service contracts with embedded training obligations. Three-tier pricing structure across premium certification-grade, standard BIS-compliant, and economy pilot-project levels separates vendors by interoperability compliance depth. Price differentiation hinges on SVAMITVA scheme qualification status and after-sales data refresh frequency. Municipal corporations in Gujarat and Maharashtra exhibit highest price sensitivity; defense agencies accept premium pricing for air-gapped on-premise deployments.
Supply Chain Analysis
Photogrammetry and remote sensing expertise scarcity in Delhi-NCR and Hyderabad concentrates production capacity for high-resolution orthophoto generation and 3D city modeling services. Component dependencies span satellite imagery feeds from ISRO's Cartosat constellation, drone hardware from DJI and indigenous PLI beneficiaries, and GPU compute from NVIDIA cloud instances. Single-source vulnerability concentrates in Survey of India's controlled topographic datasets, where defense exemptions block private access. Distribution runs through state-level tender portals and urban development authority procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform bundling mandates from state governments are forcing point-solution vendors toward acquisition or exit, consolidating procurement around integrated mapping-database-analytics stacks.
For Market Incumbents: Acquire photogrammetry and remote sensing talent pools in Hyderabad and Delhi-NCR to preempt hiring bottlenecks threatening project execution timelines. Deepen ArcGIS ecosystem lock-in through embedded training programs that raise switching costs for municipal corporations. Counter emerging drone-native entrants by certifying proprietary digital mapping assets under evolving BIS interoperability standards before tender qualification windows close. For New Entrants and Emerging Players: BIS data liberalization guidelines opening 1:50,000 scale topographic maps to private analytics providers create a window for niche positioning in previously restricted defense-adjacent applications. Target tier-2 municipal corporations in Jaipur, Lucknow, and Coimbatore where vendor competition remains thinner than saturated tier-1 metros. Enter through precision agriculture advisories in Punjab and Haryana irrigation departments, leveraging PLI scheme hardware subsidies to undercut established survey service pricing. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified IT services conglomerates seeking geospatial capabilities for smart city vertical integration. Five-to-ten year viability favors vendors with SVAMITVA scheme qualification and recurring state government contract backlogs over project-based transactional players. Monitor state revenue department procurement shifts from pilot drone surveys to operational recurring contracts as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| SVAMITVA Scheme Qualification | BIS certification unlocks five-year recurring contracts with Ministry of Panchayati Raj. |
| Drone Hardware Backward Integration | PLI scheme subsidies reduce survey service costs and expand margin capture. |
| Cloud-Native Platform Migration | Elastic compute during monsoon response periods attracts Gujarat and Tamil Nadu municipalities. |
| Digital Twin Capability Buildout | IoT-sensor integration wins Bengaluru and Chennai flood modeling pilots. |
| Tier-2 Geographic Expansion | Lower vendor competition in Coimbatore and Madurai accelerates contract capture. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with state revenue department IT directors, municipal corporation smart city project leads, drone survey service procurement officers, and BIS certification auditors. Secondary sources encompassed Survey of India data liberalization notifications, Ministry of Panchayati Raj SVAMITVA scheme tender documents, state urban development authority contract awards, and PLI scheme beneficiary disclosures. Bottom-up triangulation across vendor contract values and top-down validation against state budget allocations for geospatial digitization established market sizing.
Granularity-level modeling deployed technology-specific adoption curves across GIS, remote sensing, and image processing layers, with deployment mode splits between cloud-based, on-premise, and hybrid architectures. End-user segmentation captured government, agriculture sector, transportation, and real estate demand patterns. Application-level modeling covered urban planning, disaster management, agriculture, and environmental monitoring workflows. CAGRs derived from SVAMITVA scheme mandate expansion timelines and smart city infrastructure investment trajectories.
The model assumes a particular technology adoption path; alternative pathways for AI-IoT convergence in predictive maintenance would alter the outlook for utility and transportation agency contract values. Forecasts reflect assumptions on state government procurement consolidation speed and BIS standard evolution timelines. Material deviation in drone hardware cost curves or data sovereignty regulation tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Latin America Big Data Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Global Wi-Fi Analytics Market
Analytics
Global Industrial Analytics Market
Analytics
Network Traffic Analytics Market
Analytics
Embedded Analytics Software Market
Analytics
Global User and Entity Behavior Analytics Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Practice Analytics Market
Analytics
North America Speech Analytics Market
Analytics
Global Enterprise Performance Management Market
Analytics
Product Analytics Market
Analytics
Big Data Analytics in Manufacturing Market
Analytics
Location Analytics Adoption Spending Market