
 Global Data Fusion Market | 2026-2036
Global Data Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Fusion Market Foresight
North American cloud infrastructure expansion is reshaping competitive dynamics in data fusion platforms. Microsoft Corporation leverages its Azure sovereign cloud deployments to anchor government contracts requiring domestic data residency. Palantir Technologies specializes in ontology-based integration for defense and intelligence workflows. Amazon Web Services, Inc. competes through classified region offerings that extend FedRAMP authorization into tactical edge environments.
Data fusion combines heterogeneous sensor feeds, structured databases, and unstructured streams into unified analytical frameworks using schema alignment, entity resolution, and probabilistic correlation engines. The technology serves military command systems, autonomous vehicle perception stacks, and industrial IoT control rooms where millisecond latency thresholds govern operational decisions. Cloud deployment now leads solution type distribution as hyperscalers invest in GPU-accelerated fusion nodes, while edge computing represents the fastest-growing segment driven by battlefield and autonomous system requirements. Master data management commands the largest margin pool within solution types due to enterprise dependency on golden record accuracy across supply chain and customer domains.
The EU AI Act imposes conformity assessments on automated decision systems processing cross-border intelligence, directly shaping vendor certification requirements for European defense contracts. The US Federal Risk and Authorization Management Program and Department of Defense Impact Level 6 standards create parallel compliance tracks that filter market access for non-domestic suppliers. ISO/IEC 27001 and NIST SP 800-53 frameworks further segment procurement eligibility across NATO-aligned agencies. Stakeholders must monitor divergence between EU algorithmic accountability mandates and US national security carve-outs when architecting transatlantic product roadmaps.
Market Dynamics
Defense agencies are compressing sensor-to-decision timelines from hours to seconds, forcing vendors to re-architect fusion pipelines around GPU-accelerated inference and edge-deployable models.
Growth Catalysts
- EU AI Act:Conformity assessment mandates for cross-border automated decision systems are creating certified vendor ecosystems for European defense procurement.
- Multi-source intelligence platforms:Military command systems require unified analytical frameworks processing satellite, signals, and human intelligence feeds simultaneously.
- Federal modernization budgets:United States sensor-to-decision pipeline investments are accelerating classified cloud deployments and tactical edge infrastructure.
Market Restraints
- GPU supply concentration:Taiwan Semiconductor Manufacturing Company fabrication constraints limit availability of high-throughput inference accelerators for fusion nodes.
- FedRAMP authorization timelines:United States cloud vendors face 12-18 month certification cycles that filter non-domestic suppliers from federal contracts.
- Schema alignment complexity:Heterogeneous sensor feeds require probabilistic correlation engines that demand specialized ontology engineering talent.
Strategic Opportunities
- India defense modernization:Ministry of Defence indigenization mandates under the Defence Acquisition Procedure are opening procurement channels for local-assembly fusion platforms.
- Autonomous vehicle perception:Automotive OEMs are adopting millisecond-latency fusion stacks for LiDAR-radar-camera integration in urban navigation.
- Industrial IoT convergence:Manufacturing control rooms are merging operational technology sensor streams with enterprise data lakes for predictive maintenance.
Industry Challenges
- Entity resolution engineering:Golden record accuracy across supply chain domains requires scarce data steward expertise and continuous master data governance.
- Impact Level 6 compliance:United States Department of Defense facilities certification demands physical infrastructure investments that strain mid-tier vendor balance sheets.
- Interoperability fragmentation:NATO-aligned agencies operate under divergent NIST SP 800-53 and ISO/IEC 27001 implementations that complicate multi-national deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Fusion Market |
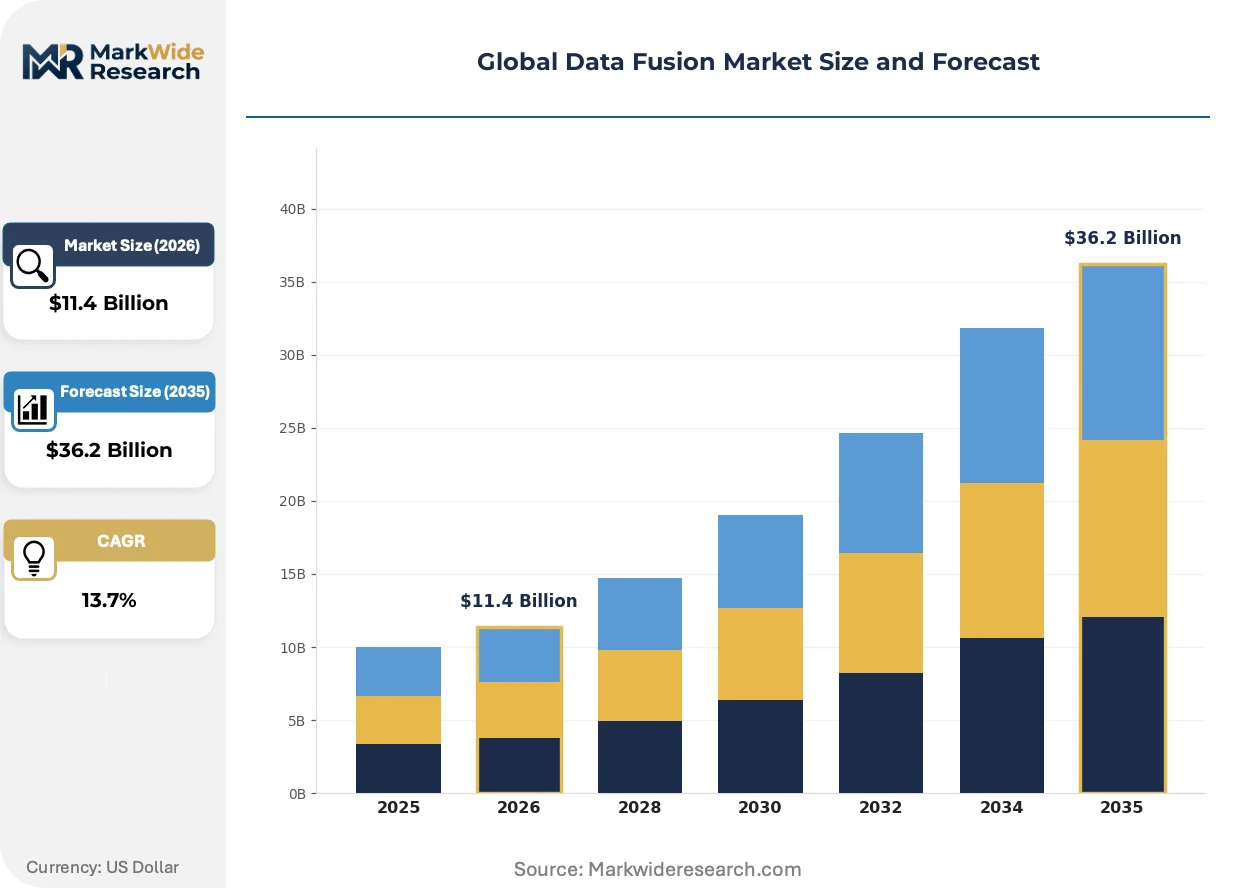
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $36.2 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Edge Computing Solution Type: Data Integration, Metadata Management, Data Quality, Master Data Management, Reference Data Management End User Industry: Telecommunications, Defense & Intelligence, Energy & Utilities, Automotive OEMs, Government Agencies Application: Real-Time Analytics, Threat Detection, Supply Chain Optimization, Customer Insights, Risk Management |
| Companies Covered | IBM Corporation, Oracle Corporation, Microsoft Corporation, SAP SE, Palantir Technologies, Amazon Web Services, Inc., Teradata Corporation, SAS Institute Inc., TIBCO Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Fusion Market Shifts & Advancements
Neuromorphic inference architectures and sovereign cloud deployments are redrawing competitive boundaries in analytical infrastructure. Vendors are racing to embed fusion capabilities directly into sensor hardware.
Probabilistic correlation engines are collapsing the latency gap between raw sensor ingestion and actionable intelligence output. Defense primes are deploying these engines aboard tactical platforms with severe power and thermal constraints. The compression of fusion timelines is eliminating traditional batch-processing architectures from frontline systems.
REACH substance restrictions and RoHS compliance mandates are constraining material choices for edge-deployable fusion hardware across European defense supply chains. Component vendors are reformulating solder alloys and substrate materials to maintain thermal performance under revised chemical thresholds. German and French procurement offices are now requiring full material disclosure documentation for tactical computing modules.
Sensor manufacturers are unbundling hardware sales from fusion software licensing, shifting revenue toward recurring analytics subscriptions. Industrial IoT buyers in Germany and Japan are resisting perpetual-license models in favor of consumption-based pricing tied to data throughput volumes. This contractual pivot is pressuring traditional platform vendors to restructure sales organizations and partner ecosystems.
Global Data Fusion Market Segmentation
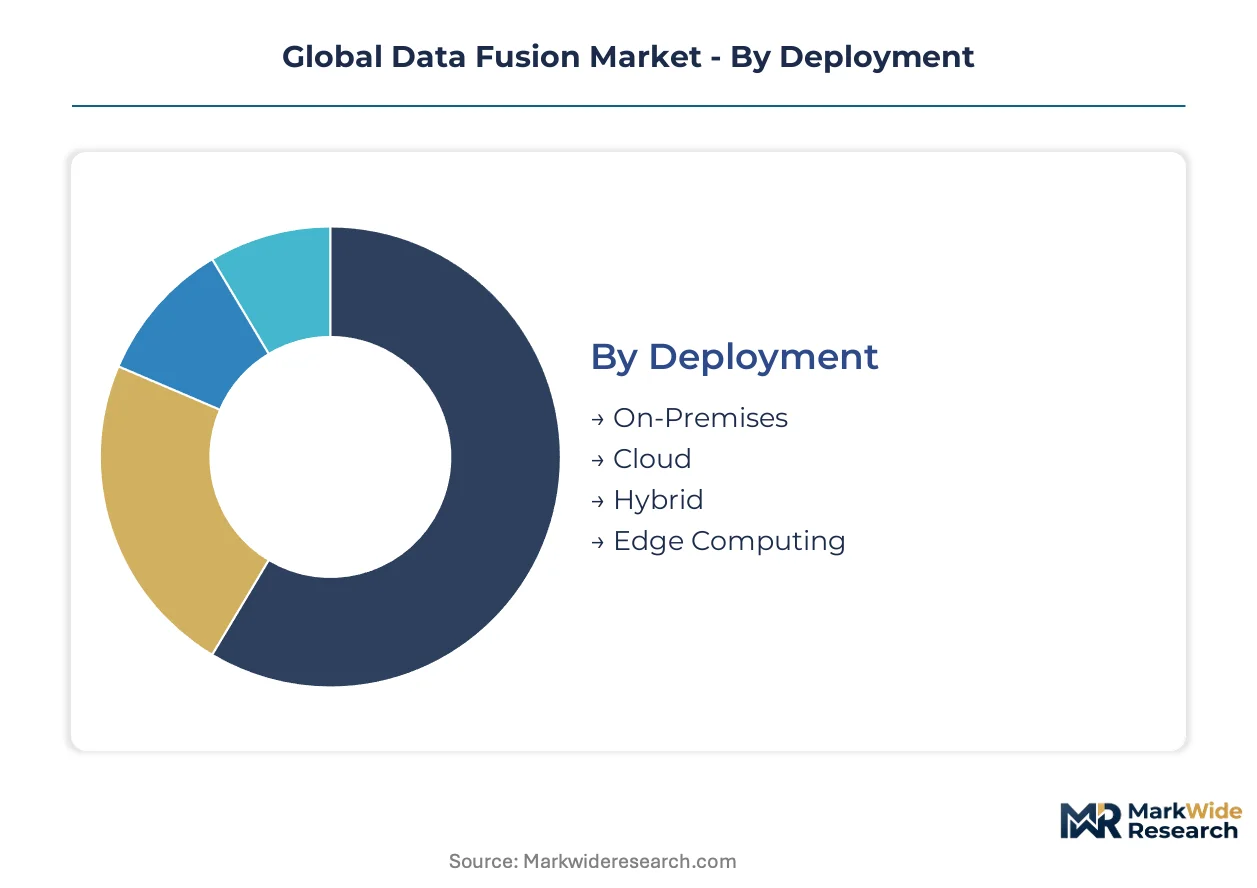
Segmentation reveals how data fusion architectures diverge across operational constraints. Deployment choices dictate hardware refresh cycles and compliance postures. Solution types separate commodity integration from high-margin governance layers. End-user industries impose distinct latency, security, and scale requirements that reshape vendor roadmaps.
Deployment:
After-sales service intensity varies sharply across deployment modes, with edge and hybrid configurations demanding sustained field engineering support.
- Cloud:Hyperscaler-managed infrastructure eliminates on-site maintenance while shifting service intensity toward API integration and data residency consulting. United States federal contracts concentrate here as Azure and AWS expand sovereign cloud footprints to satisfy domestic processing mandates.
- Edge Computing:Tactical platforms operate under severe power and thermal constraints requiring embedded thermal engineers and field-replaceable unit logistics. Defense agencies in Germany and France are procuring battlefield-hardened nodes with mandatory depot-level maintenance contracts.
- On-Premises:Legacy air-gapped facilities in classified environments drive specialized technician dispatch requirements.
- Hybrid:Split architectures combining cloud burst capacity with local retention create dual-support complexity for enterprise IT organizations.
Cloud holds the largest share; momentum sits with edge computing.
Solution Type:
Margin pools concentrate in governance-intensive categories where accuracy failures carry regulatory penalties.
- Master Data Management:Golden record accuracy across supplier and customer domains demands continuous stewardship and ontology engineering. German automotive OEMs and Japanese industrial conglomerates anchor procurement here, driven by supply chain traceability mandates under REACH and emerging CSRD disclosure requirements.
- Data Integration:Schema alignment and ETL pipeline construction represent the highest-volume segment with compressed pricing. Indian IT services vendors and European system integrators compete aggressively on labor-arbitraged implementation contracts.
- Metadata Management:Data lineage documentation serves financial services auditors and pharmaceutical quality systems.
- Data Quality:Profiling and cleansing tools address GDPR-driven rectification workflows in EU member states.
- Reference Data Management:Standardized code sets and hierarchies support cross-border regulatory reporting.
Master data management commands premium pricing; data integration delivers volume.
End User Industry:
Procurement sophistication separates defense-grade certification requirements from commercial velocity priorities.
- Defense & Intelligence:Impact Level 6 facilities and FedRAMP High authorizations filter vendor pools to domestic primes and cleared subcontractors. United States sensor-to-decision pipeline investments and NATO allied requirements for interoperability certification sustain multi-year contract visibility.
- Automotive OEMs:LiDAR-radar-camera perception stacks for autonomous navigation demand millisecond-latency fusion with ISO 26262 functional safety compliance. German and Japanese manufacturers are verticalizing fusion software development to protect differentiation.
- Telecommunications:Network slicing and subscriber analytics drive real-time stream processing investments.
- Energy & Utilities:Grid modernization and renewable intermittency forecasting require geospatial-temporal data correlation.
- Government Agencies:Smart city and public safety applications concentrate in France, South Korea, and UAE procurement frameworks.
Defense and intelligence absorb the highest contract values; automotive OEMs are expanding most quickly.
Application:
Use case maturity determines whether buyers prioritize proven throughput or experimental accuracy gains.
- Real-Time Analytics:Continuous query processing over streaming sensor and transaction feeds demands GPU-accelerated inference nodes. Financial trading floors in London and Singapore, alongside industrial control rooms in Germany, sustain demand for sub-100-millisecond decision pipelines.
- Threat Detection:Multi-source intelligence correlation for cyber and physical security fuses network telemetry with access control and satellite imagery. United States Cyber Command and European national CERTs anchor procurement with mandatory EU AI Act conformity assessments for automated decision systems.
- Supply Chain Optimization:Demand sensing and inventory positioning algorithms serve retail and manufacturing planners.
- Customer Insights:Cross-channel identity resolution supports personalization engines under GDPR consent constraints.
- Risk Management:Credit and operational risk quantification drives banking procurement with Basel III data granularity requirements.
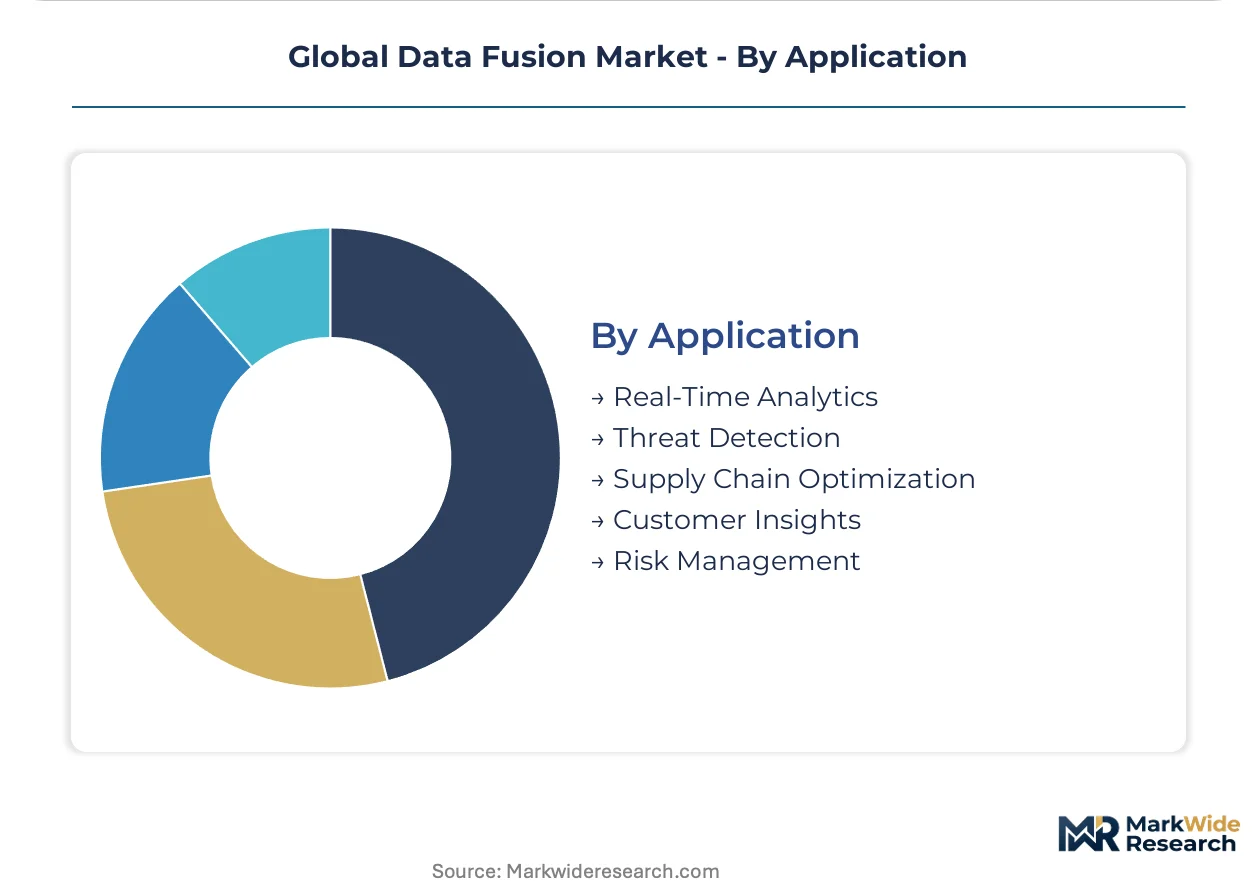
Real-time analytics leads deployment scale; threat detection is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler cloud infrastructure concentrates in the United States, while specialized edge hardware manufacturing clusters in Germany and Taiwan. Defense procurement patterns diverge sharply between NATO-aligned certification regimes and Indo-Pacific indigenization mandates.
United States
Federal sensor-to-decision pipeline investments and classified cloud modernization budgets drive procurement velocity. FedRAMP High and DoD Impact Level 6 standards filter vendor access to intelligence agency contracts. Northern Virginia's data center corridor hosts Azure and AWS sovereign cloud deployments serving Pentagon and IC requirements.
Germany
Automotive OEM demand for LiDAR-radar-camera perception stacks and industrial IoT convergence sustain platform adoption. REACH substance restrictions and RoHS compliance mandates constrain material choices for edge-deployable tactical hardware. Stuttgart and Munich anchor automotive fusion software development clusters with mandatory full material disclosure documentation.
China
Smart city surveillance infrastructure and autonomous vehicle testing corridors generate high-volume data integration demand. MIIT data localization requirements and GB standards for cross-border processing shape vendor certification pathways. Yangtze River Delta municipalities deploy real-time analytics for public safety and traffic management systems.
India
Ministry of Defence indigenization mandates under the Defence Acquisition Procedure open procurement channels for local-assembly fusion platforms. BIS certification requirements and PLI scheme incentives for electronics manufacturing attract component vendors. Bengaluru and Hyderabad host emerging defense-tech clusters developing indigenous multi-source intelligence capabilities.
United Kingdom
Financial services real-time analytics demand and cyber threat detection investments sustain stream processing infrastructure. GDPR-driven data lineage requirements and Financial Conduct Authority operational resilience mandates govern procurement specifications. London's trading floors and Cambridge security-tech cluster anchor sub-100-millisecond decision pipeline deployments.
Global Data Fusion Market Competitive Landscape
Hyperscale cloud providers and specialized defense-technology vendors split the market along sovereignty and latency vectors. Consolidation pressures concentrate around classified infrastructure contracts and automotive safety-critical certification requirements. Two archetypes dominate: horizontally integrated platform operators with sovereign cloud footprints, and vertically focused ontology engineers serving intelligence workflows. Competitive moves center on GPU-accelerated inference node deployment and tactical edge hardware partnerships.
Within the horizontally integrated tier, Microsoft Corporation and Amazon Web Services, Inc. anchor government cloud positions through domestic data residency offerings. Palantir Technologies occupies a specialized position exemplifying the ontology-engineering archetype for defense and intelligence agency workflows. These three entities represent the structural poles around which mid-tier vendors and regional system integrators organize partnership and subcontracting relationships.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Microsoft Corporation |
| SAP SE |
| Palantir Technologies |
| Amazon Web Services, Inc. |
| Teradata Corporation |
| SAS Institute Inc. |
| TIBCO Software Inc. |
| Others |
Supply & Pricing Matrix
The Trans-Pacific fiber cable corridor carries cloud workload traffic between US hyperscaler data centers and East Asian manufacturing nodes, with bandwidth cost volatility feeding directly into edge hardware pricing tiers and subscription model differentiation for defense-grade fusion platforms.
Pricing Analysis
FedRAMP authorization timelines dictate the pricing tier structure across deployment modes, separating cleared domestic vendors from excluded foreign competitors. Three-tier pricing structure across premium, standard, and economy levels aligns with Impact Level certification grades, with IL-6 facilities commanding substantial premiums over commercial cloud equivalents. Cost compression in the data integration segment intensifies as Indian IT services vendors and European system integrators compete on labor-arbitraged implementation contracts. Automotive OEMs exhibit the highest price sensitivity due to verticalization pressures, while defense agencies prioritize certification compliance over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing strategies for GPU-accelerated inference nodes. Taiwan, South Korea, and the United States anchor high-throughput accelerator fabrication, with advanced packaging capacity concentrated in Taiwan Semiconductor Manufacturing Company facilities. Supply chains draw from gallium nitride substrates, high-bandwidth memory stacks, and battlefield-hardened chassis alloys as critical inputs. Single-source vulnerability in TSMC's leading-edge node allocation creates procurement risk for tactical edge deployments. Distribution runs through cleared domestic primes and their subcontractor networks for classified contracts, while commercial segments leverage direct hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around hyperscaler cloud procurement offices and defense agency central acquisition commands, compressing vendor margins and favoring scale players with sovereign cloud footprints.
For Market Incumbents: Entrench classified infrastructure positions through Impact Level 6 facility investments and FedRAMP High authorization maintenance, countering mid-tier vendor balance sheet strain. Deepen ontology engineering capabilities to defend Palantir Technologies' intelligence workflow specialization against horizontally integrated platform competition. Prioritize GPU-accelerated inference node deployment in Northern Virginia data center corridors to anchor Pentagon sensor-to-decision pipeline contracts. For New Entrants and Emerging Players: Establish a beachhead in India's Defence Acquisition Procedure indigenization channels, where Ministry of Defence mandates open procurement for local-assembly fusion platforms. Target German automotive OEM perception stack development, where REACH compliance documentation requirements filter out incumbent hardware vendors. Pursue consumption-based pricing partnerships with industrial IoT buyers in Japan and Germany as a go-to-market angle against perpetual-license incumbents. For Investors and Strategic Acquirers: EU AI Act conformity assessment mandates reshape the acquisition landscape toward certified vendor ecosystems for European defense procurement. Long-term viability centers on ontology engineering talent scarcity and sovereign cloud data residency capabilities rather than commodity integration volume. Monitor divergence between EU algorithmic accountability mandates and US national security carve-outs as the critical inflection signal for transatlantic product roadmap investments.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Deployment | Azure and AWS domestic data residency offerings anchor Pentagon and intelligence community contracts. |
| GPU-Accelerated Inference Node Expansion | NVIDIA and AMD accelerator partnerships compress sensor-to-decision timelines for battlefield applications. |
| EU AI Act Certification Investment | Conformity assessment capabilities unlock European defense procurement channels previously filtered by algorithmic transparency mandates. |
| Edge Hardware Partnership | Tactical platform thermal engineering alliances address German and French depot-level maintenance contract requirements. |
| Ontology Engineering Acquisition | Specialized data steward talent pools defend master data management margin premiums against commodity integration competitors. |
Research Methodology
A standing panel of defense procurement officers, cloud platform engineers, intelligence workflow architects, and automotive perception stack developers provided ongoing calibration across primary interview cycles and secondary validation. Primary fieldwork combined structured conversations with Pentagon acquisition commands, NATO interoperability certification bodies, and German automotive OEM R&D directors. Secondary sources encompassed FedRAMP authorization databases, DoD budget justification documents, EU AI Act implementing guidance, and hyperscaler sovereign cloud capex disclosures. Bottom-up deployment mode sizing and top-down solution type margin analysis triangulated market structure estimates.
Scenario-bracketing around GPU supply constraints and regulatory divergence produced bounded range estimates across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type governance intensity, end-user industry certification requirements, and regional procurement framework alignment. CAGRs derived from fitted growth curves against historical federal modernization budget trajectories and automotive autonomous system deployment roadmaps. Industry-specific forecast inputs encompassed Taiwan Semiconductor Manufacturing Company fabrication capacity allocation schedules and EU AI Act enforcement timeline assumptions.
Sensitivities concentrate around TSMC node allocation disruptions, FedRAMP authorization timeline extensions, and transatlantic regulatory divergence on algorithmic accountability carve-outs. Forecasts embed assumptions regarding continued federal sensor-to-decision pipeline investment velocity and German automotive OEM verticalization limits. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Data Discovery Market
Analytics
Behavior Analytics Market
Analytics
United States Geospatial Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Digital Analytics Solutions Market
Analytics
Data Visualization Market
Analytics
Business Value Dashboard Market
Analytics
Regression Analysis Tool Market
Analytics
India Big Data Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Network Analytics Services Market
Analytics
IoT Analytics Market
Analytics
Europe Crowd Analytics Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Condition Monitoring Service Market
Analytics
North America Mobile Analytics Market