
 Saudi Arabia Geospatial Analytics Market | 2026-2036
Saudi Arabia Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Geospatial Analytics Market Insights
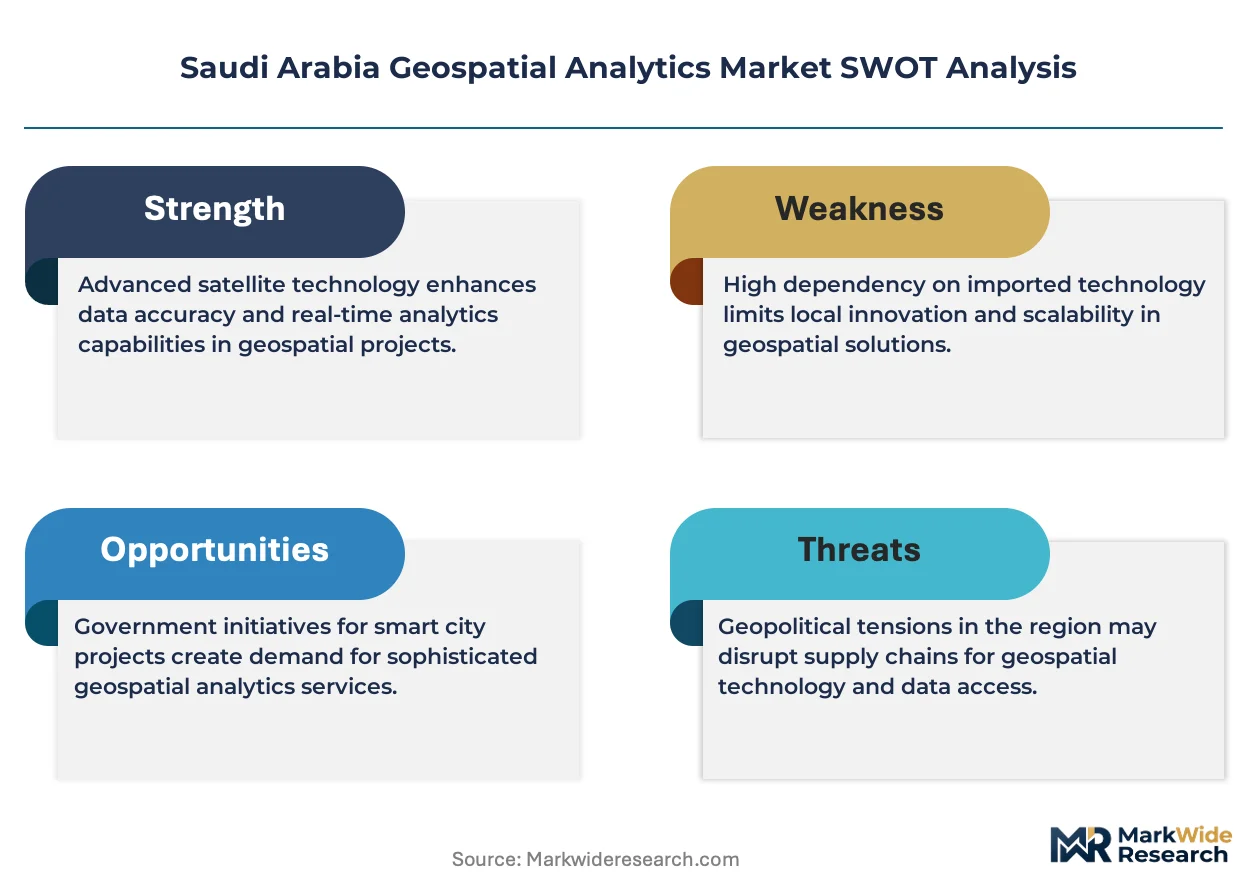
A shortage of certified GIS specialists and remote sensing engineers is unwinding project timelines across the Kingdom's giga-developments. Esri Saudi Arabia leverages its localized ArcGIS platform to dominate municipal mapping contracts in Riyadh and Neom. Hexagon AB sustains its position through precision agriculture and surveying solutions tailored to Saudi farm cooperatives. Trimble Inc. anchors the construction segment with GNSS hardware deployed on Red Sea Project sites.
Geospatial analytics encompasses the computational processing of location-based data through satellite imagery, coordinate systems, and spatial algorithms to generate actionable intelligence for asset management and territorial planning. The discipline relies on raster and vector data structures, coordinate reference systems such as UTM zone 38N, and spectral band analysis to model terrain, vegetation, and built environments. Remote Sensing technology leads technology adoption as Saudi Earth observation programs expand satellite downlink capabilities for environmental and security applications. Urban Planning commands the largest application share as the Ministry of Municipal and Rural Affairs deploys platforms for zoning, transportation routing, and utility mapping across expanding metropolitan boundaries. Cloud-based deployment is gaining traction among mid-sized engineering consultancies seeking to avoid capital-intensive server infrastructure.
The Saudi Data and Artificial Intelligence Authority enforces national geospatial data standards that shape platform interoperability requirements for government vendors. The Communications, Space and Technology Commission regulates satellite imagery licensing and foreign data transmission, constraining how international providers operate within the Kingdom. SFDA oversight applies where geospatial systems support pharmaceutical supply chain cold-chain tracking. Stakeholders must monitor how evolving data localization rules and emerging sovereign Earth observation capabilities reshape competitive access to government contracts and giga-project procurement pipelines.
Market Dynamics
The Saudi Data and Artificial Intelligence Authority's national spatial data infrastructure mandates are compressing vendor certification timelines while redirecting procurement toward interoperable platforms. This regulatory pressure is restructuring competitive access across municipal and giga-project verticals.
Growth Catalysts
- NEOM and Red Sea Project deployment schedules:Giga-project master planning requires continuous geospatial monitoring for terrain modeling, environmental baseline tracking, and construction progress verification. These programs generate sustained platform demand.
- Saudi Earth observation satellite programs:Domestic satellite downlink infrastructure expansion reduces reliance on foreign imagery providers. Enhanced sovereign data access accelerates defense, agriculture, and urban planning applications.
- Cloud migration among engineering consultancies:Mid-sized firms are abandoning on-premise server infrastructure for subscription-based geospatial platforms. This shift broadens addressable user bases beyond government and major energy operators.
Market Restraints
- Certified GIS specialist scarcity:The Kingdom's universities produce insufficient remote sensing engineers and spatial data scientists. Project timelines extend as contractors compete for limited talent pools.
- Data localization compliance costs:The Communications, Space and Technology Commission's satellite imagery licensing rules require foreign providers to establish domestic data processing nodes. This raises operational barriers for international vendors.
- High-precision GNSS hardware dependency:Survey-grade positioning equipment relies on imported chipsets and antenna systems. Supply concentration with European and North American manufacturers creates procurement vulnerability.
Strategic Opportunities
- Precision agriculture platform expansion:Saudi farm cooperatives in Al-Qassim and Al-Jawf regions lack sophisticated crop monitoring systems. Vegetation index analytics and irrigation optimization tools remain underdeployed.
- Integration of synthetic aperture radar with optical imagery:All-weather earth observation capabilities address dust-storm limitations affecting Red Sea coastal developments. Dual-sensor platforms enable year-round construction monitoring.
- SFDA pharmaceutical cold-chain tracking mandates:Geospatial systems supporting temperature-monitored logistics create specialized application demand. Location-aware supply chain visibility tools align with regulatory compliance requirements.
Industry Challenges
- Legacy CAD-BIM system interoperability:Municipal engineering departments operate fragmented software environments. Geospatial platform integration requires costly data format translation and workflow reconfiguration.
- Spatial data quality standardization gaps:Inconsistent coordinate reference system adoption across Riyadh Municipality, Arriyadh Development Authority, and private developers forces redundant data reconciliation efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Geospatial Analytics Market |
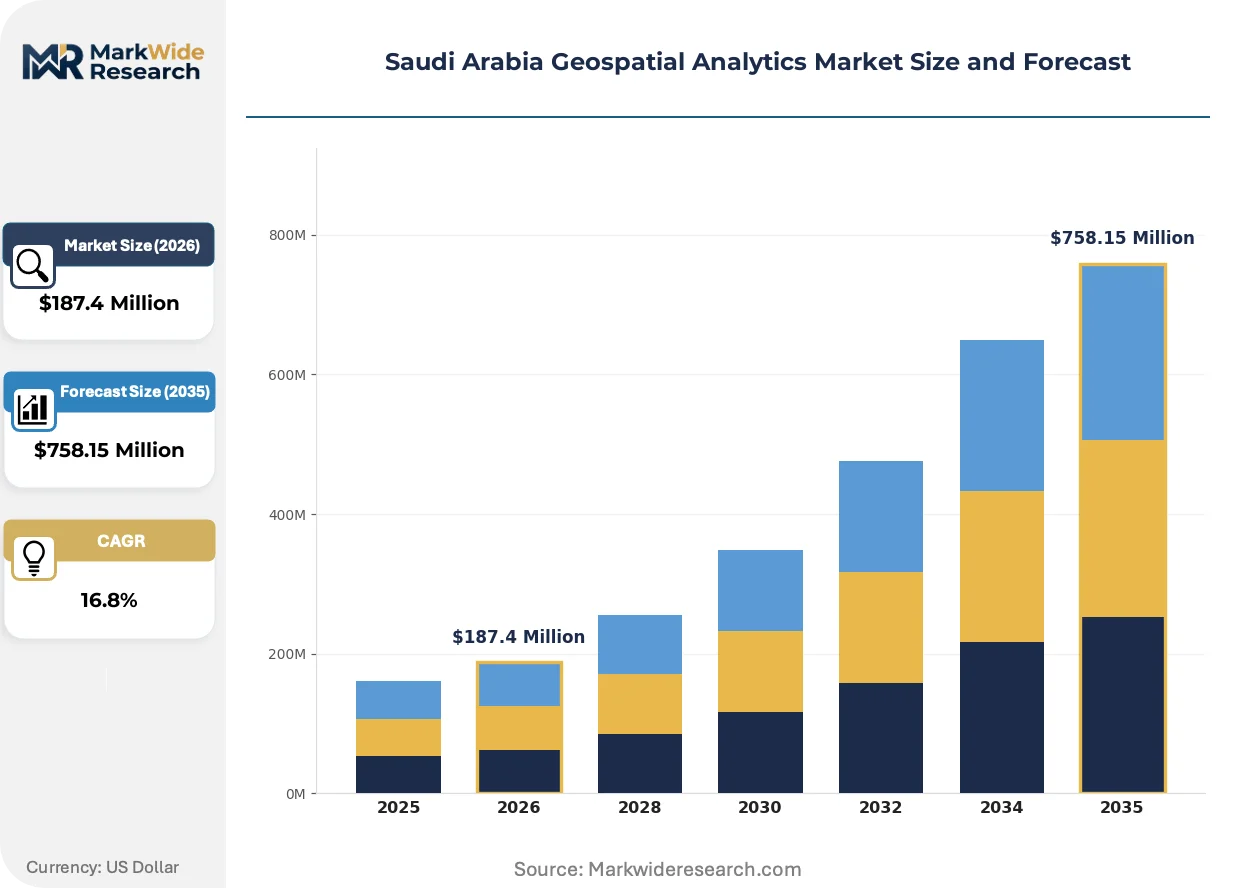
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Agriculture Management, Environmental Monitoring, Defense Operations Technology: GIS Software, Remote Sensing, GPS, Spatial Data End User: Government Agencies, Construction Sector, Energy Companies, Transportation Deployment: Cloud-based, On-premises, Hybrid, Mobile |
| Companies Covered | Esri Saudi Arabia, Hexagon AB, Trimble Inc., Autodesk Inc., Bentley Systems, HERE Technologies, Bayanat, Maxar Technologies, Neo Space Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Geospatial Analytics Market Trends and Innovations
Computational methods for location intelligence are fragmenting across specialized hardware, sovereign cloud infrastructure, and AI-augmented analytics engines. This technological diversification is reshaping vendor competitive positioning.
Digital twin platforms are bifurcating the municipal planning software stack. These systems fuse real-time IoT sensor feeds with 3D mesh terrain models to simulate traffic flows, flood scenarios, and energy consumption patterns. Riyadh Municipality and NEOM development authorities are deploying twin environments for scenario testing prior to physical construction. The technology is compressing traditional master planning cycles while elevating data freshness requirements for underlying geospatial substrates.
SFDA oversight of pharmaceutical supply chains is mandating location-aware temperature logging for cold-chain distribution. This regulatory pressure is forcing logistics operators to integrate geospatial tracking with warehouse management systems. Compliance documentation now requires spatial proof-of-delivery verification, affecting last-mile routing algorithms and vehicle telematics specifications.
Subscription-based platform access is displacing perpetual license procurement among mid-tier engineering consultancies. Riyadh-based infrastructure design firms are abandoning capital-intensive server deployments for browser-accessible spatial analysis tools. This purchasing pattern shift concentrates vendor negotiation leverage with platform operators while reducing client-side IT staffing requirements. The trend is most visible among firms serving Ministry of Municipal and Rural Affairs contracts.
Saudi Arabia Geospatial Analytics Market Segmentation
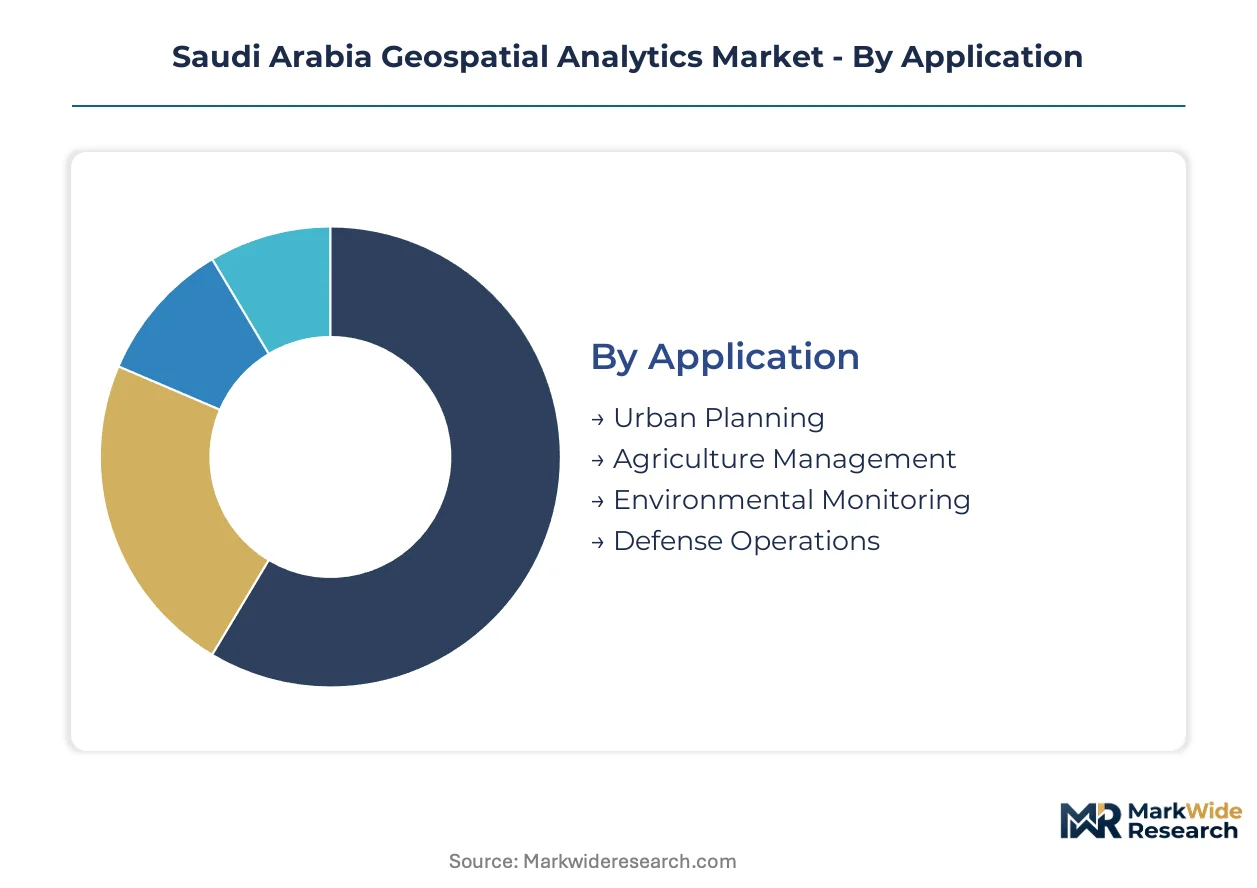
Geospatial analytics procurement in Saudi Arabia fragments across four distinct dimensions. Application requirements differ sharply between NEOM's master planning teams and Al-Qassim farm cooperatives. Technology choices reflect trade-offs between sovereign data control and computational scalability. Deployment preferences split along organizational IT maturity and capital availability lines.
Application:
Channel flows diverge markedly: municipal contracts route through systems integrators, while agricultural deployments often proceed direct-to-farmer via cooperative channels.
- Urban Planning:Zoning automation, transportation routing algorithms, and utility network mapping dominate municipal procurement. Riyadh Municipality and Arriyadh Development Authority deploy these platforms continuously for metropolitan boundary expansion. SFDA cold-chain mandates are pulling logistics visibility tools into this segment.
- Agriculture Management:Vegetation index analytics and precision irrigation optimization serve Al-Qassim and Al-Jawf farm cooperatives. Satellite-derived crop health monitoring remains underdeployed relative to groundwater stress in northern regions.
- Environmental Monitoring:Dust storm tracking and coastal erosion measurement support Red Sea Project environmental compliance. Domestic satellite downlink infrastructure reduces foreign imagery dependency for baseline assessments.
- Defense Operations:Border surveillance and critical infrastructure protection applications operate under Communications, Space and Technology Commission licensing constraints. Sovereign Earth observation programs are expanding data access for security applications.
By volume, Urban Planning leads. By growth pace, Agriculture Management is expanding most quickly.
Technology:
Cost tiers separate enterprise-grade platforms from cooperative-accessible tools, with mid-market solutions gaining traction among engineering consultancies.
- GIS Software:ArcGIS deployments anchor municipal and giga-project contracts through localized platform versions. Browser-accessible subscriptions are displacing perpetual licenses among mid-sized Riyadh infrastructure firms.
- Remote Sensing:Spectral band analysis and synthetic aperture radar processing enable all-weather earth observation. Dual-sensor platforms address dust-storm limitations affecting coastal construction monitoring.
- GPS:Survey-grade GNSS hardware relies on imported European and North American chipsets. Red Sea Project sites deploy Trimble positioning equipment for millimeter-level construction verification.
- Spatial Data:Vector and raster data structures underpin coordinate reference system standardization. Saudi Data and Artificial Intelligence Authority mandates are compressing interoperability compliance timelines.
By installed base, GIS Software dominates. By capability expansion, Remote Sensing is gaining share fastest.
End User:
Customer type determines procurement authority concentration versus fragmentation, shaping vendor sales motion economics.
- Government Agencies:Ministry of Municipal and Rural Affairs platforms standardize zoning and utility mapping across metropolitan boundaries. National spatial data infrastructure mandates redirect procurement toward interoperable systems.
- Construction Sector:NEOM and Red Sea Project master planning generates sustained demand for terrain modeling and progress verification. Legacy CAD-BIM system interoperability gaps force costly workflow reconfiguration.
- Energy Companies:Saudi Aramco infrastructure mapping programs expand adoption across pipeline and facility management. Geospatial asset tracking integrates with SCADA systems for operational visibility.
- Transportation:Riyadh Metro and giga-project mobility networks require continuous route optimization and traffic simulation. Digital twin deployments are elevating real-time data freshness requirements.
By contract value, Government Agencies lead. By deployment velocity, Construction Sector is climbing the fastest.
Deployment:
Maturity gradients separate capital-intensive on-premise installations from subscription-based cloud migrations among mid-tier firms.
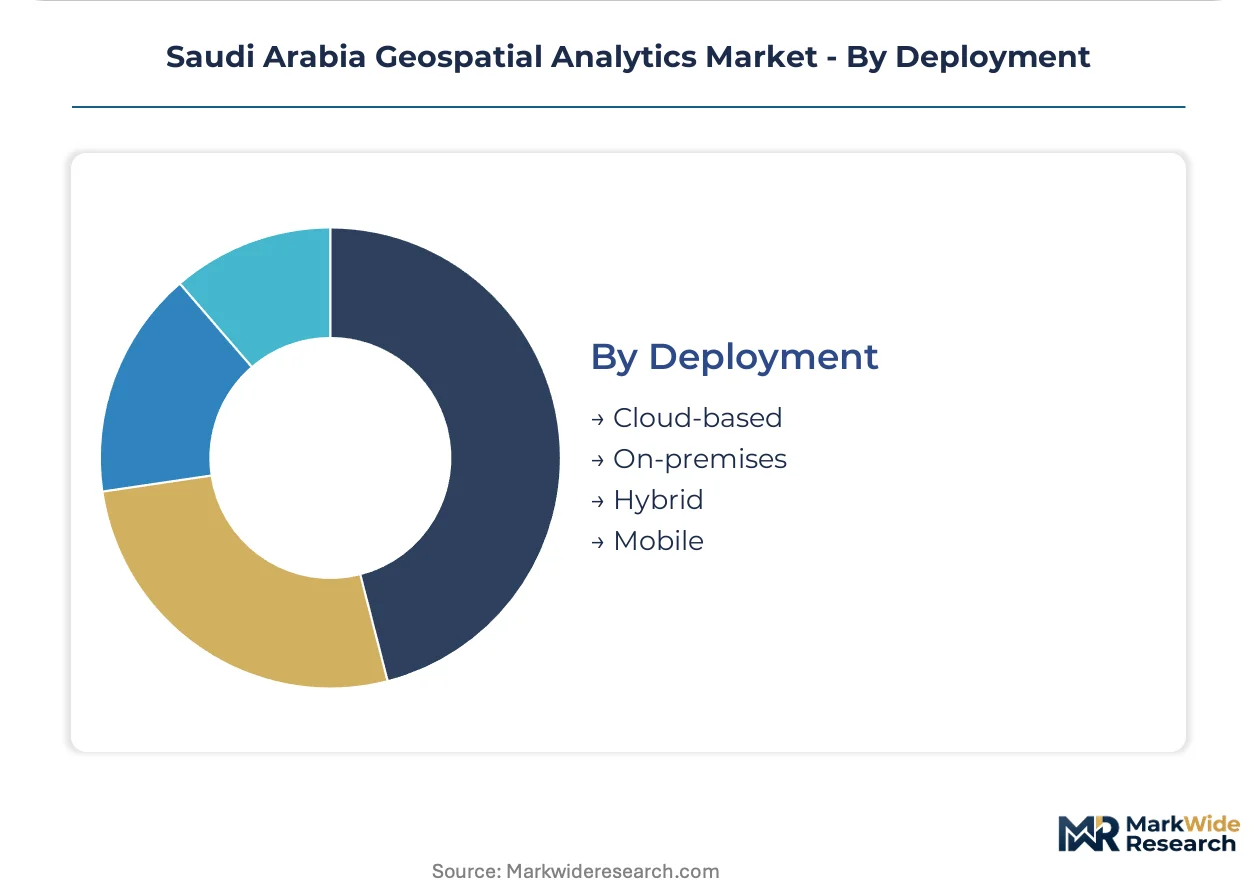
- Cloud-based:Browser-accessible spatial analysis tools eliminate server infrastructure requirements. Engineering consultancies serving Ministry of Municipal and Rural Affairs contracts are abandoning capital-intensive deployments.
- On-premises:Defense and critical infrastructure applications retain localized processing for data sovereignty compliance. High-performance computing clusters support complex terrain modeling workflows.
- Hybrid:Sensitive data remains on-site while compute-intensive processing leverages external infrastructure. This architecture balances regulatory compliance with scalability requirements.
- Mobile:Field survey crews and construction supervisors access lightweight mapping tools on ruggedized devices. Offline capability addresses connectivity gaps at remote giga-project sites.
By current deployment share, On-premises leads. By migration momentum, Cloud-based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geospatial analytics deployment varies sharply across Saudi Arabia's economic zones. Riyadh concentrates municipal planning platforms, while coastal regions prioritize environmental monitoring and construction verification systems.
Riyadh
Riyadh Municipality and Arriyadh Development Authority drive continuous demand for zoning automation and transportation routing algorithms. Saudi Data and Artificial Intelligence Authority mandates compress vendor certification timelines for interoperable platforms. The capital's smart city initiatives generate sustained procurement for utility network mapping and metropolitan boundary expansion tools.
Eastern Province
Saudi Aramco's energy infrastructure mapping programs anchor platform adoption across pipeline and facility management. Communications, Space and Technology Commission satellite imagery licensing rules require domestic data processing nodes for foreign providers. Dhahran's technology cluster hosts geospatial asset tracking integrated with SCADA systems for operational visibility.
Western Region
Red Sea Project sites deploy survey-grade GNSS hardware for millimeter-level construction verification and progress tracking. Dust storm limitations drive demand for synthetic aperture radar processing alongside optical imagery. Jeddah-based engineering consultancies are migrating from on-premise servers to browser-accessible spatial analysis tools.
NEOM Northwest
NEOM's master planning requires continuous geospatial monitoring for terrain modeling and environmental baseline tracking. Digital twin deployments fuse real-time IoT sensor feeds with 3D mesh terrain models for scenario testing. The development authority's procurement elevates data freshness requirements for underlying geospatial substrates.
Al-Qassim and Al-Jawf
Farm cooperatives in these northern regions lack sophisticated crop monitoring systems despite groundwater stress conditions. Vegetation index analytics and precision irrigation optimization tools remain underdeployed relative to agricultural potential. Satellite-derived crop health monitoring adoption is expanding fastest here among rural end-users.
Saudi Arabia Geospatial Analytics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Saudi Arabia's geospatial analytics market. The upper tier combines platform breadth with localized compliance capabilities, while specialists concentrate on precision hardware or sector-specific applications. Two strategic archetypes dominate: full-stack platform providers with government certification and component specialists with deep vertical expertise. Competitive moves center on securing municipal and giga-project procurement pipelines, alongside partnerships with systems integrators serving Ministry of Municipal and Rural Affairs contracts.
Within the platform provider tier, Esri Saudi Arabia and Hexagon AB exemplify contrasting approaches to market position. Esri Saudi Arabia anchors the municipal and giga-project vertical through localized ArcGIS deployments. Hexagon AB occupies a specialist position in precision agriculture and surveying solutions tailored to farm cooperatives. Trimble Inc. represents the hardware-centric archetype, with its positioning equipment deployed across Red Sea Project construction sites.
| Leading Market Players |
|---|
| Esri Saudi Arabia |
| Hexagon AB |
| Trimble Inc. |
| Autodesk Inc. |
| Bentley Systems |
| HERE Technologies |
| Bayanat |
| Maxar Technologies |
| Neo Space Group |
| Others |
Pricing and Supply Chain Analysis
Saudi Data and Artificial Intelligence Authority certification requirements gate both vendor qualification and price differentiation simultaneously. Compliance timelines compress as interoperability mandates redirect procurement toward certified platforms, elevating premium pricing for pre-approved systems while squeezing margins on uncertified alternatives.
Pricing Analysis
Project-based contracting dominates municipal and giga-project procurement, with subscription SaaS tiers gaining share among mid-sized engineering consultancies. Price differentiation rests on certification tier against SDAIA standards and after-sales service bundling including localized technical support. Cost compression in the mid-market tier intensifies as browser-accessible tools displace perpetual licenses. Government agencies exhibit lowest price sensitivity due to mandate-driven procurement, while farm cooperatives in Al-Qassim and Al-Jawf remain most price-constrained.
Supply Chain Analysis
Strategic stockpiling of survey-grade GNSS hardware prevails among Red Sea Project contractors due to lead time volatility, while software platforms migrate toward just-in-time cloud provisioning. Geographic supply concentration centers on European and North American sources for positioning chipsets and antenna systems, with domestic satellite downlink infrastructure expanding for imagery processing. Raw material dependencies include semiconductor components, precision optics, and rare earth elements for sensor fabrication. Single-source vulnerability runs through European GNSS manufacturers. Distribution runs through systems integrators serving Ministry of Municipal and Rural Affairs contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geospatial analytics in Saudi Arabia functions as a service-attach opportunity where recurring platform subscriptions and certified training programs expand faster than hardware sales. After-sales technical support and SDAIA compliance consulting now generate margins exceeding equipment provisioning.
For Market Incumbents: Shield municipal contract positions by deepening SDAIA certification portfolios before interoperability mandates fully phase in. Acquire specialized remote sensing engineering talent pools to offset certified GIS specialist scarcity compressing project timelines. Anchor platform stickiness through embedded workflow integration with legacy CAD-BIM systems that municipal engineering departments struggle to replace.
For New Entrants and Emerging Players: Precision agriculture platform gaps in Al-Qassim and Al-Jawf farm cooperatives offer white-space entry with vegetation index analytics and irrigation optimization tools underdeployed relative to groundwater stress. Synthetic aperture radar integration services for dust-storm construction monitoring present a second penetrable niche. Pursue direct-to-cooperative distribution bypassing systems integrator concentration in government channels.
For Investors and Strategic Acquirers: SDAIA's evolving sovereign Earth observation capability mandates reshape the acquisition landscape toward vendors with domestic data processing infrastructure. Long-term viability favors platform operators with recurring revenue bases over hardware-centric positioning equipment suppliers. Target acquisition archetype: mid-sized engineering consultancies with established Ministry of Municipal and Rural Affairs relationships and cloud migration momentum. Watch for satellite imagery licensing rule tightening as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| SDAIA Certification Investment | Secures interoperability compliance for municipal and giga-project procurement pipelines. |
| Domestic Data Processing Node Establishment | Satisfies Communications, Space and Technology Commission satellite imagery licensing constraints. |
| Synthetic Aperture Radar Capability Addition | Addresses dust-storm limitations affecting Red Sea coastal construction monitoring. |
| Precision Agriculture Platform Launch | Captures underdeployed vegetation index analytics demand in Al-Qassim and Al-Jawf cooperatives. |
| Cloud Subscription Migration | Aligns with mid-sized Riyadh engineering consultancies abandoning capital-intensive server infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from geospatial platform engineers, municipal procurement officers, farm cooperative managers, and satellite imagery licensing specialists and refined through secondary validation. Primary interviews combined with regulatory filings from the Communications, Space and Technology Commission, SDAIA interoperability standards documentation, and customs data on GNSS hardware imports. Bottom-up triangulation across deployment models and end-user segments converged with top-down macroeconomic anchoring.
Variance decomposition across the projection horizon isolates technology adoption curves, regulatory compliance phase-ins, and giga-project construction schedules as primary uncertainty sources. Segmentation dimensions modeled include application vertical, deployment architecture, end-user organization type, and technology platform category. CAGRs derive from fitted adoption curves against historical platform penetration patterns. Industry-specific inputs incorporate NEOM and Red Sea Project master planning timelines alongside Saudi Earth observation satellite program milestones.
Forecasts assume regulatory continuity in SDAIA certification regimes and Communications, Space and Technology Commission licensing frameworks; material policy shifts would require re-modeling. Forecasts reflect assumptions on certified specialist supply recovery and sovereign satellite infrastructure deployment pacing. Revision becomes warranted when domestic imagery downlink capacity crosses thresholds altering foreign provider dependency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Systems of Insight Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Global Analytics Market
Analytics
Israel Geospatial Analytics Market
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Identity Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Condition Monitoring Service Market
Analytics
Global Subscription Analytics Software Market
Analytics
Attribution Software Market
Analytics
Procurement Analytics Market
Analytics
Europe Network and Location Analytics Market
Analytics
Global Big Data Market
Analytics
Data Discovery Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Big Data Analytics Market