
 Spain Geospatial Analytics Market | 2026-2036
Spain Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Geospatial Analytics Market Insights
Spain's Ley de Cambio Climático y Transición Energética is repositioning the cost-of-entry calculus for geospatial service providers by mandating climate-risk disclosure in all public infrastructure tenders. Esri Geospatial Solutions Spain S L leverages its ArcGIS platform dominance to anchor municipal contracts across Madrid and Valencia. CARTO competes through cloud-native spatial data science tools that reduce deployment timelines for mid-sized consulting firms. Hexagon AB extends its sensor-to-software pipeline into Spanish precision agriculture, where Leica Geosystems hardware captures field-level crop stress indicators.
Geospatial analytics encompasses the computational processing of location-referenced data from satellite imagery, aerial photogrammetry, GPS telemetry, and ground-based sensors to extract spatial patterns and predictive intelligence. The discipline relies on coordinate reference systems, raster-vector data fusion, and machine learning classifiers trained on multispectral bands to support decisions in asset management, risk assessment, and resource allocation. Remote sensing technology leads technology segmentation due to Copernicus program data accessibility and Spain's robust ground segment infrastructure at Torrejón and Maspalomas. Environmental monitoring applications command structural priority within application segmentation as Iberian drought severity intensifies regulatory reporting obligations for watershed managers and coastal zone administrators.
BIS interoperability standards, Spain's Instituto Geográfico Nacional cartographic mandates, and EU INSPIRE directive compliance requirements collectively shape product specifications and data governance protocols for vendors seeking public-sector eligibility. The national regulator CEA enforces cadastral accuracy thresholds that filter out uncertified surveying subcontractors from utility mapping contracts. Stakeholders must monitor whether Madrid accelerates mandatory Building Information Modeling-Geographic Information System integration timelines, as this would force immediate capability upgrades across the vendor base.
Market Dynamics
Spain's Ley de Cambio Climático y Transición Energética is compressing procurement timelines for geospatial analytics vendors by embedding climate-risk disclosure mandates into every public infrastructure tender. Municipalities now require LiDAR-derived flood models and satellite-based land-use change detection as baseline deliverables, elevating technical entry barriers for uncertified surveyors and fragmenting contract awards between established platform providers and specialized remote sensing consultancies.
Growth Catalysts
- Copernicus data accessibility:Spain's Torrejón and Maspalomas ground stations provide free Sentinel-2 and Sentinel-1 imagery, eliminating raw data acquisition costs for regional environmental consultancies and accelerating project feasibility studies.
- EU Green Deal compliance:Watershed managers across the Ebro and Guadalquivir basins must submit satellite-validated drought impact assessments to national authorities, creating recurring demand for hyperspectral crop stress monitoring and evapotranspiration modeling.
- Barcelona smart-city cluster:Real-time mobility analytics now guide congestion pricing algorithms and transit expansion planning, with municipal agencies procuring integrated GPS-telemetry and computer-vision platforms for multimodal traffic optimization.
Market Restraints
- LiDAR sensor import concentration:Hardware procurement depends on German and Swiss photonics manufacturers, exposing Spanish survey contractors to euro-denominated price volatility and extended lead times for Leica Geosystems and RIEGL units.
- Cadastral accuracy thresholds:Spain's Instituto Geográfico Nacional mandates sub-meter positional certification for utility mapping contracts, filtering out small geomatics firms lacking ISO 19115-compliant quality management systems.
- Cloud infrastructure fragmentation:Mid-sized consulting firms face integration complexity when municipal clients specify incompatible data hosting environments across AWS, Microsoft Azure, and regional cloud providers.
Strategic Opportunities
- Andalusian precision agriculture:Olive cooperatives and vineyard estates in Jaén and Jerez de la Frontera remain underpenetrated for drone-based multispectral crop scouting, presenting white space for subscription-based analytics services.
- Building Information Modeling-GIS convergence:Madrid's potential acceleration of mandatory BIM-GIS integration timelines would force immediate capability upgrades across the vendor base, favoring early movers with Esri-ArcGIS and Autodesk interoperability.
- Coastal zone administration:Rising Mediterranean erosion rates are expanding satellite-derived shoreline change detection contracts for port authorities in Valencia, Algeciras, and Bilbao.
Industry Challenges
- Geomatics talent scarcity:Spanish universities produce insufficient graduates trained in Python-based geoprocessing and machine learning classifier development, forcing vendors to recruit from Portuguese and French labor markets.
- Legacy system integration friction:Municipal GIS departments in Castile and León operate decades-old Esri ArcMap installations, complicating migration to cloud-native spatial data science platforms and delaying project handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Geospatial Analytics Market |
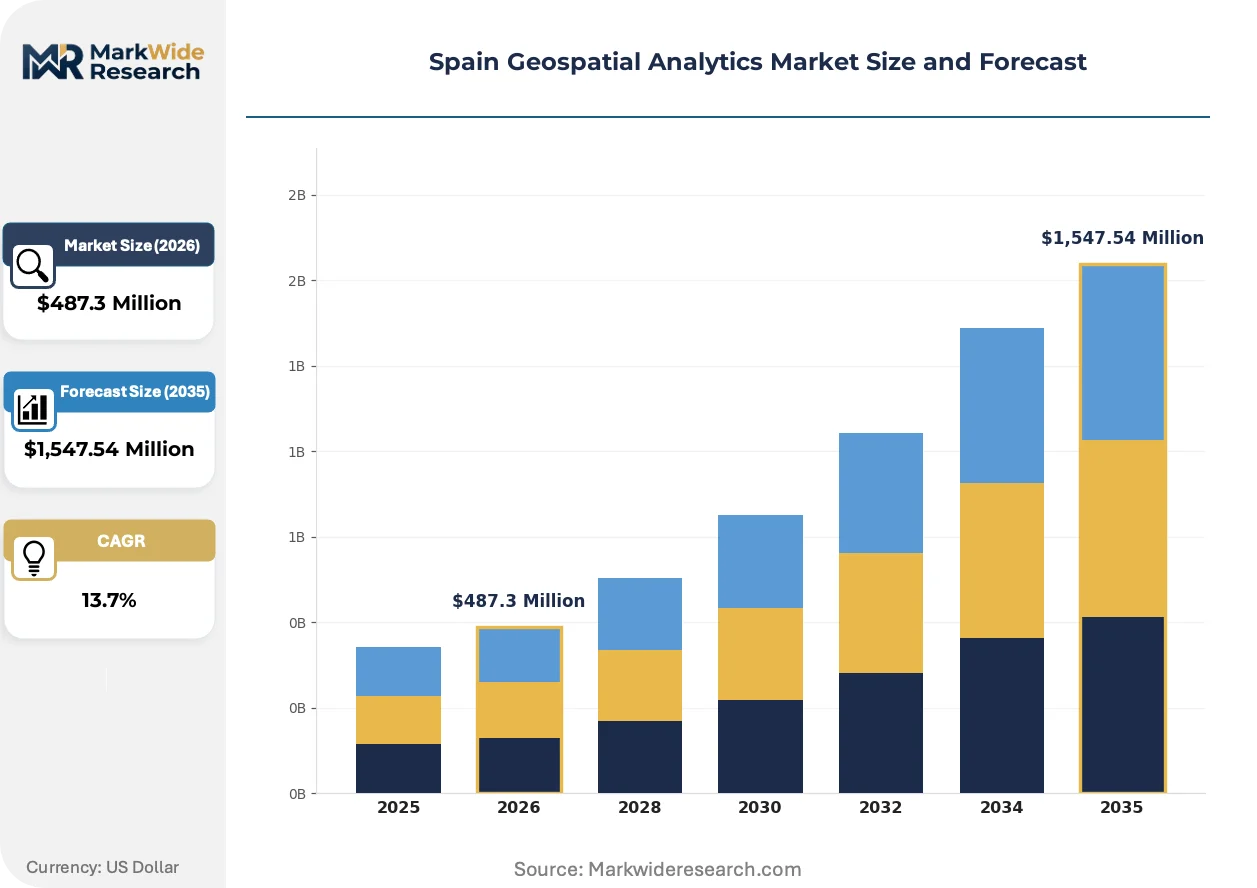
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,547.54 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Disaster Management, Transportation Analysis, Environmental Monitoring Technology: GIS Software, Remote Sensing, GPS Applications, Data Visualization End User: Government Agencies, Consulting Firms, Utility Companies, Real Estate Developers Service Type: Data Management, Consulting Services, Training, Custom Development |
| Companies Covered | Telespazio, Urban Data Analytics, Esri Geospatial Solutions Spain S L, Geoblink, inAtlas, CARTO, Nommon Solutions and Technologies S L, Vexiza, Hexagon AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Geospatial Analytics Market Trends and Innovations
Cloud-native spatial data science architectures are displacing on-premise geoprocessing workflows across Spanish municipal and regional agencies. This shift compresses deployment timelines from months to weeks while forcing traditional desktop-GIS vendors to restructure licensing models around consumption-based SaaS pricing.
Hyperspectral imaging is consolidating agricultural advisory services in Extremadura and La Rioja. Grape growers and nut producers now contract drone operators for weekly canopy health scans at 10-20 nanometer spectral resolution. This granularity enables early detection of fungal pressure and irrigation stress, compressing the competitive advantage of agronomists relying solely on visual scouting or Sentinel-2's 10-meter resolution.
Spain's national recovery plan mandates climate-adaptive urban development, compelling regional planners to integrate LiDAR and thermal infrared analytics into statutory master plans. Municipalities in Catalonia and the Basque Country now require 3D building models for solar potential assessment and heat-island mitigation. This regulatory pressure is accelerating procurement of airborne laser scanning services and pushing surveying firms to certify personnel in ISO 19650 asset information management.
Subscription-based geospatial intelligence is displacing perpetual-license software sales among mid-sized Spanish engineering consultancies. Firms serving transport infrastructure and environmental impact assessment now prefer monthly access to CARTO's spatial data science stack over capital expenditure on ArcGIS Enterprise deployments. This preference shift is most visible in Madrid's AEC cluster, where project-based revenue volatility makes operational expenditure accounting more attractive than balance-sheet software assets.
Spain Geospatial Analytics Market Segmentation
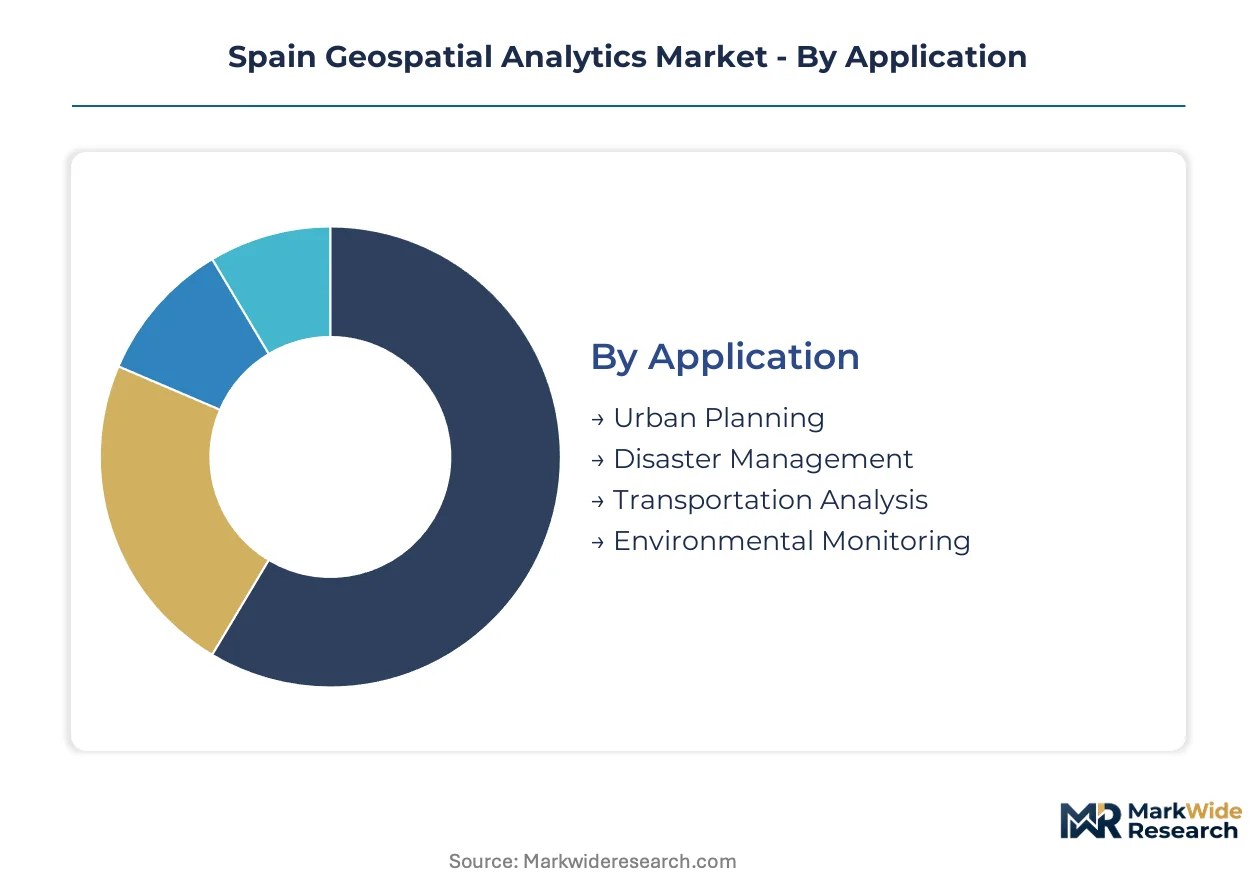
Segmentation in Spain's geospatial analytics market reveals how procurement priorities diverge between climate-mandated public infrastructure and precision agriculture commercialization. Understanding these splits allows vendors to align capability investments with buyers possessing committed budgets and regulatory timelines.
Application:
Municipal procurement teams prioritize applications delivering compliance-ready deliverables for EU Green Deal and national climate law submissions.
- Environmental Monitoring:Satellite-derived watershed assessment and coastal erosion tracking dominate demand from Ebro and Guadalquivir basin authorities. Iberian drought severity intensifies regulatory reporting obligations, forcing watershed managers to contract hyperspectral crop stress and evapotranspiration modeling services on recurring cycles.
- Urban Planning:Climate-adaptive master plans now require LiDAR-derived 3D building models and thermal infrared analytics for solar potential and heat-island mitigation. Catalonia and Basque Country municipalities mandate these datasets for statutory plan approvals, accelerating airborne laser scanning procurement.
- Disaster Management:Flood-risk zoning drives satellite-based land-use change detection contracts across Andalusia, Castile and León.
- Transportation Analysis:Barcelona's congestion pricing algorithms and transit expansion planning consume real-time mobility analytics integrating GPS telemetry with computer vision.
Environmental Monitoring leads on scale; Urban Planning leads on momentum as BIM-GIS integration timelines accelerate.
Technology:
Technology selection hinges on data sovereignty requirements and existing vendor relationships within Spain's Instituto Geográfico Nacional ecosystem.
- Remote Sensing:Copernicus program accessibility through Torrejón and Maspalomas ground stations eliminates raw data acquisition costs. Sentinel-2 and Sentinel-1 imagery feeds regional environmental consultancy feasibility studies and project accelerations.
- GIS Software:Cloud-native spatial data science architectures displace on-premise workflows, compressing deployment timelines from months to weeks. Consumption-based SaaS pricing restructuring challenges traditional desktop-GIS licensing models.
- GPS Applications:Real-time kinematic positioning supports cadastral surveys meeting sub-meter accuracy thresholds for utility mapping.
- Data Visualization:Dashboard platforms translate complex raster-vector fusions into decision-ready formats for regional planners.
Remote Sensing leads on scale; GIS Software leads on momentum as cloud migration accelerates.
End User:
End-user budgets reflect institutional scale and regulatory exposure to climate-risk disclosure mandates.
- Government Agencies:Municipal governments across Andalusia, Castile and León, and Catalonia deploy satellite-derived land-use analytics for flood-risk zoning and infrastructure prioritization. Spain's national recovery plan compels regional planners to integrate LiDAR and hyperspectral imaging into master plans.
- Consulting Firms:Mid-sized engineering consultancies prefer subscription-based access to spatial data science stacks over capital expenditure on enterprise deployments. Project-based revenue volatility in Madrid's AEC cluster drives operational expenditure accounting preferences.
- Utility Companies:Grid operators require ISO 19115-compliant quality management for cadastral mapping contracts.
- Real Estate Developers:Climate-risk disclosure requirements in public tenders increasingly shape site selection analytics.
Government Agencies lead on scale; Consulting Firms lead on momentum as SaaS adoption climbs fastest.
Service Type:
Service procurement patterns track client technical maturity and legacy system integration burdens.
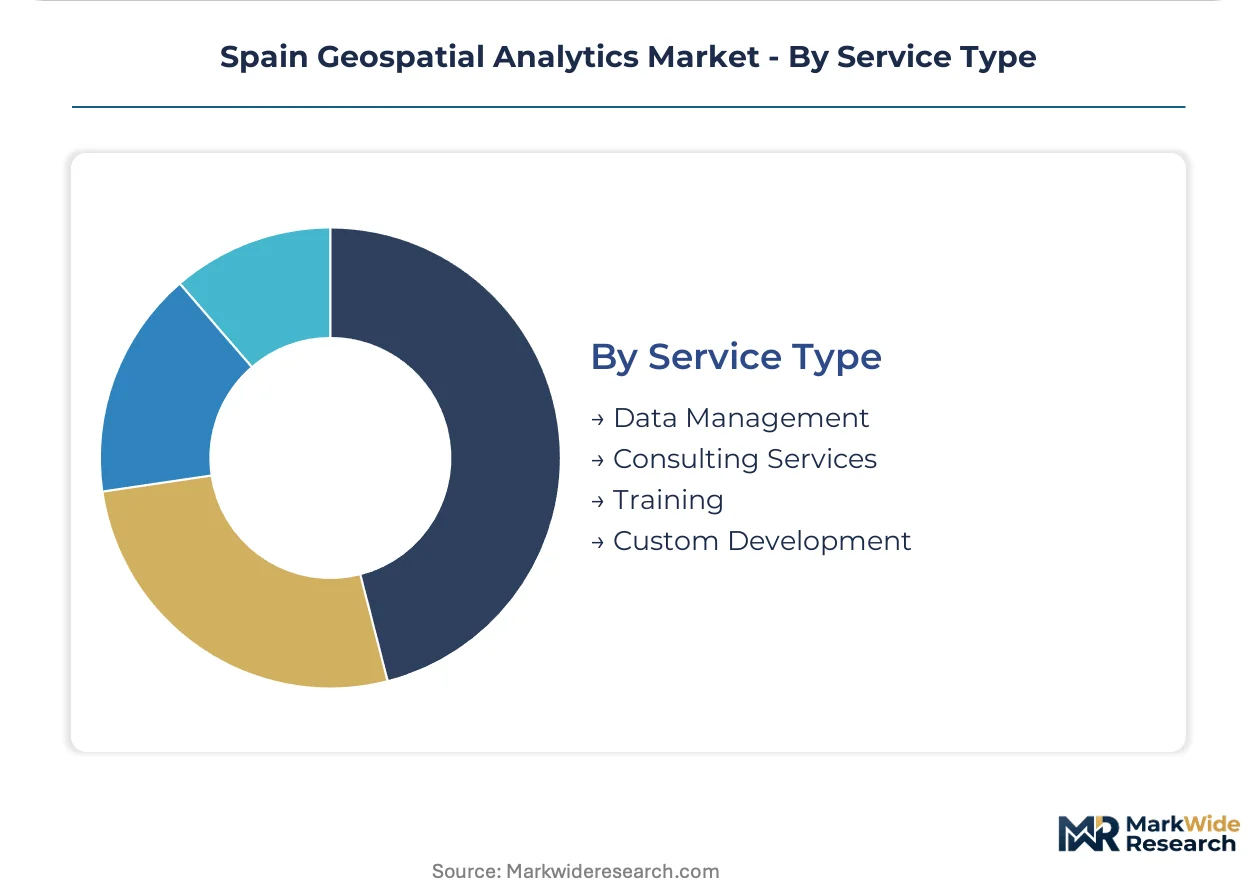
- Consulting Services:Specialized remote sensing consultancies capture fragmented contract awards alongside established platform providers. Climate-risk disclosure mandates in public infrastructure tenders elevate technical entry barriers, concentrating demand on certified analytical capabilities.
- Data Management:Cloud infrastructure fragmentation across AWS, Microsoft Azure, and regional providers complicates integration for mid-sized firms. Municipal client specifications force vendors to architect multi-environment compatibility.
- Training:Python-based geoprocessing and machine learning classifier development skills scarcity drives recruitment from Portuguese and French labor markets.
- Custom Development:Legacy Esri ArcMap installations in Castile and León municipal GIS departments delay migration to cloud-native platforms, sustaining bespoke integration demand.
Consulting Services leads on scale; Data Management leads on momentum as interoperability requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish geomatics talent clusters in Madrid and Barcelona anchor national capability development, with university research programs at Universidad Politécnica de Madrid and Universitat Politècnica de Catalunya feeding specialized labor pipelines into regional consultancy markets.
Madrid
Madrid concentrates national government procurement and AEC consultancy demand. Spain's Instituto Geográfico Nacional mandates cadastral accuracy thresholds that filter vendor eligibility for utility mapping contracts. The capital's engineering cluster drives subscription-based SaaS adoption for spatial data science platforms.
Catalonia
Barcelona's smart-city cluster consumes real-time mobility analytics for congestion pricing and transit optimization. Catalonia's climate-adaptive urban development regulations require LiDAR-derived 3D building models for statutory master plan approvals. Municipal agencies procure integrated GPS-telemetry and computer-vision platforms.
Andalusia
Olive cooperatives and vineyard estates in Jaén and Jerez de la Frontera generate underpenetrated demand for drone-based multispectral crop scouting. The Guadalquivir basin authority submits satellite-validated drought impact assessments to comply with EU Green Deal watershed reporting obligations. Regional environmental consultancies leverage Torrejón ground station Copernicus data access.
Basque Country
Industrial port authorities in Bilbao contract satellite-derived shoreline change detection services amid accelerating Mediterranean erosion. Basque municipalities mandate thermal infrared analytics for heat-island mitigation in urban planning submissions. The region's precision manufacturing base supports sensor-to-software pipeline integration.
Valencia
Valencia's port authority expands coastal zone administration contracts for erosion monitoring and infrastructure protection. The regional government deploys satellite-based land-use analytics for flood-risk zoning across Mediterranean watersheds. Local surveying firms pursue ISO 19650 certification to capture climate-risk disclosure mandated public tenders.
Spain Geospatial Analytics Market Competitive Landscape
The competitive structure tilts toward platform providers with established municipal relationships and specialized remote sensing consultancies with certified analytical capabilities. Esri Geospatial Solutions Spain S L anchors municipal contracts through ArcGIS platform dominance, while CARTO competes via cloud-native spatial data science tools. Strategic moves concentrate on SaaS licensing restructuring and BIM-GIS interoperability certification.
Within the platform-provider tier, Esri Geospatial Solutions Spain S L and CARTO exemplify divergent approaches to municipal market capture. Hexagon AB occupies a position bridging sensor hardware and software analytics for precision agriculture applications. Specialized consultancies including Nommon Solutions and Technologies S L and Geoblink sit within the remote sensing services segment, targeting climate-risk disclosure compliance workflows.
| Leading Market Players |
|---|
| Telespazio |
| Urban Data Analytics |
| Esri Geospatial Solutions Spain S L |
| Geoblink |
| inAtlas |
| CARTO |
| Nommon Solutions and Technologies S L |
| Vexiza |
| Hexagon AB |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISO 19115-compliant analytical services and uncertified surveying outputs manifests in both pricing premiums and supply chain sourcing patterns across Spanish municipal procurement. Municipalities in Catalonia and Madrid pay substantial markups for certified LiDAR-derived flood models and sub-meter positional accuracy, while procurement officers in Castile and León face extended vendor qualification timelines that compress project margins.
Pricing Analysis
Bundled service packages combining hardware acquisition with multi-year analytical subscriptions command premium positioning against unbundled per-project contracting. Three-tier pricing structure across premium certification-grade, standard compliance-tier, and economy uncertified levels separates Esri-anchored platform ecosystems from cloud-native alternatives. Pricing pressure stems from CARTO's consumption-based SaaS models eroding perpetual-license revenue pools. Mid-sized engineering consultancies in Madrid's AEC cluster exhibit highest price sensitivity due to project-based revenue volatility, while national utility mapping contracts show lowest sensitivity given regulatory non-negotiability.
Supply Chain Analysis
Workforce availability constraints in German and Swiss photonics manufacturing centers tether Spanish survey contractors to euro-denominated procurement cycles for Leica Geosystems and RIEGL LiDAR units. Hardware supply concentrates in Germany, Switzerland, and the United States, with sensor calibration dependencies resting on Torrejón ground station infrastructure. Single-source vulnerability runs through German photonics manufacturers for precision LiDAR components. Distribution runs through authorized surveying equipment dealers with ISO 17025-certified calibration facilities, creating bottleneck risk for uncertified subcontractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where municipal procurement teams are upgrading specifications toward climate-risk disclosure compliance. The named demand-shift toward ISO 19650-certified asset information management is forcing immediate capability investments across the vendor base.
For Market Incumbents: Anchor municipal relationships through accelerated BIM-GIS interoperability certification ahead of Madrid's potential regulatory acceleration. Defend against CARTO's cloud-native displacement by restructuring licensing toward consumption-based SaaS tiers. Vertical integration into Leica Geosystems hardware distribution secures sensor-to-software pipeline control for precision agriculture expansion. For New Entrants and Emerging Players: Capture underpenetrated olive cooperative demand in Jaén through subscription-based drone multispectral scouting services priced below agronomist-retained alternatives. Target Andalusian vineyard estates with weekly canopy health scan packages. Lead go-to-market through agricultural cooperative purchasing consortia rather than direct estate sales. For Investors and Strategic Acquirers: Consolidation pressure builds where geomatics talent scarcity intersects with mandatory certification inflation. Long-term viability favors platforms with established Instituto Geográfico Nacional relationships and recurring municipal revenue streams. Acquisition target archetype: remote sensing consultancies with ISO 19115 quality systems and existing Ebro basin authority contracts. Signal to watch: Madrid's publication of mandatory BIM-GIS integration timelines as inflection catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| BIM-GIS Interoperability Certification | Positions vendors for Madrid's anticipated mandatory integration timelines under national recovery mandates. |
| Cloud-Native Platform Migration | Compresses deployment timelines from months to weeks, matching CARTO's consumption-based SaaS competitive pressure. |
| Precision Agriculture Subscription Launch | Captures white-space demand from Jaén olive cooperatives and Jerez vineyard estates with underpenetrated analytics services. |
| Copernicus Ground Station Partnership | Secures preferential Sentinel-2 and Sentinel-1 data access through Torrejón and Maspalomas infrastructure anchoring. |
| ISO 19650 Asset Management Certification | Filters vendor eligibility for climate-adaptive urban development contracts in Catalonia and Basque Country municipalities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal GIS directors, regional environmental consultancy principals, precision agriculture drone operators, and Instituto Geográfico Nacional technical officers with secondary validation. Secondary sources included Spain's national recovery plan documentation, EU INSPIRE directive implementation reports, Copernicus program data accessibility disclosures, and municipal tender records from Barcelona, Madrid, and Valencia. Bottom-up project pipeline assessments and top-down regulatory mandate sizing were triangulated against vendor revenue disclosures.
Segment-weighting approaches distributed value across application dimensions including environmental monitoring, urban planning, disaster management, and transportation analysis, with technology splits between remote sensing, GIS software, GPS applications, and data visualization. End-user segmentation captured government agencies, consulting firms, utility companies, and real estate developers. CAGRs were derived from regulatory timeline commitments and procurement budget trajectories, incorporating climate-risk disclosure mandate acceleration and BIM-GIS integration speculation as scenario variables.
Regulatory timeline delays, Copernicus data service interruptions, and geomatics talent recruitment failures are the dominant revision risks that could compress forecast trajectories. Forecasts reflect documented assumptions regarding Madrid's regulatory acceleration and municipal SaaS adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Mobile Analytics Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Behavior Analytics Market
Analytics
Data Discovery Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Assortment Analytics Market
Analytics
Dark Analytics Market
Analytics
Content Intelligence Market
Analytics
Global Wi-Fi Analytics Market
Analytics
Global Digital Intelligence Platform Market
Analytics
Global Development Analytics Tools Market
Analytics
Embedded Analytics Software Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
North America Crowd Analytics Market
Analytics
Global Systems of Insight Market
Analytics
Mobile Apps and Web Analytics Market