
 Regression Analysis Tool Market | 2026-2036
Regression Analysis Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Regression Analysis Tool Market Analytics
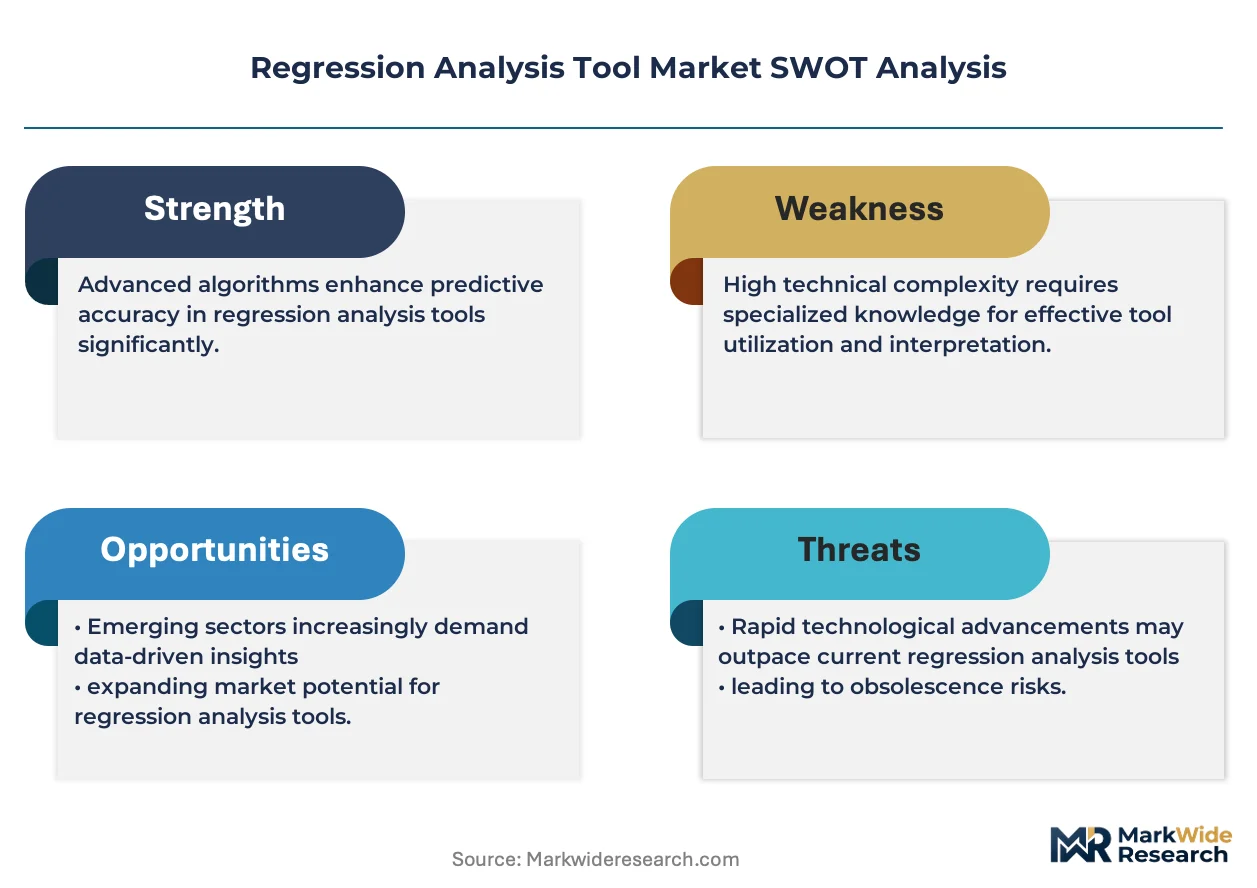
Cloud distribution channels is reshaping how regression analysis tools reach end users, with SaaS marketplaces and API-first platforms displacing traditional enterprise licensing. Microsoft leverages its Azure ecosystem to bundle statistical capabilities with cloud infrastructure. SAS Institute anchors its position through deep specialization in regulated industries requiring auditable modeling workflows. IBM competes by extending Watson analytics into hybrid deployment environments.
A regression analysis tool is statistical software that estimates relationships between dependent and independent variables through least-squares optimization, maximum likelihood estimation, or regularized fitting techniques, generating coefficients with standard errors and significance tests for prediction, inference, and causal analysis across commercial and research applications. Linear regression remains the most widely deployed product type due to interpretability requirements in financial reporting and clinical studies, while cloud-based deployment models capture the fastest expansion as organizations migrate computational workloads off aging on-premises servers. Ridge regression commands premium positioning in healthcare and genomics verticals where multicollinearity in high-dimensional datasets demands regularized coefficient shrinkage.
The EU AI Act and GDPR impose documentation and explainability mandates on automated decision systems using regression outputs, compelling vendors to embed interpretability dashboards and audit trails. The US SEC and FDA maintain parallel requirements for quantitative risk models and clinical trial analyses respectively, creating compliance complexity for cross-border software providers. Stakeholders must monitor evolving algorithmic accountability frameworks to anticipate product certification requirements and geographic market access conditions.
Market Dynamics
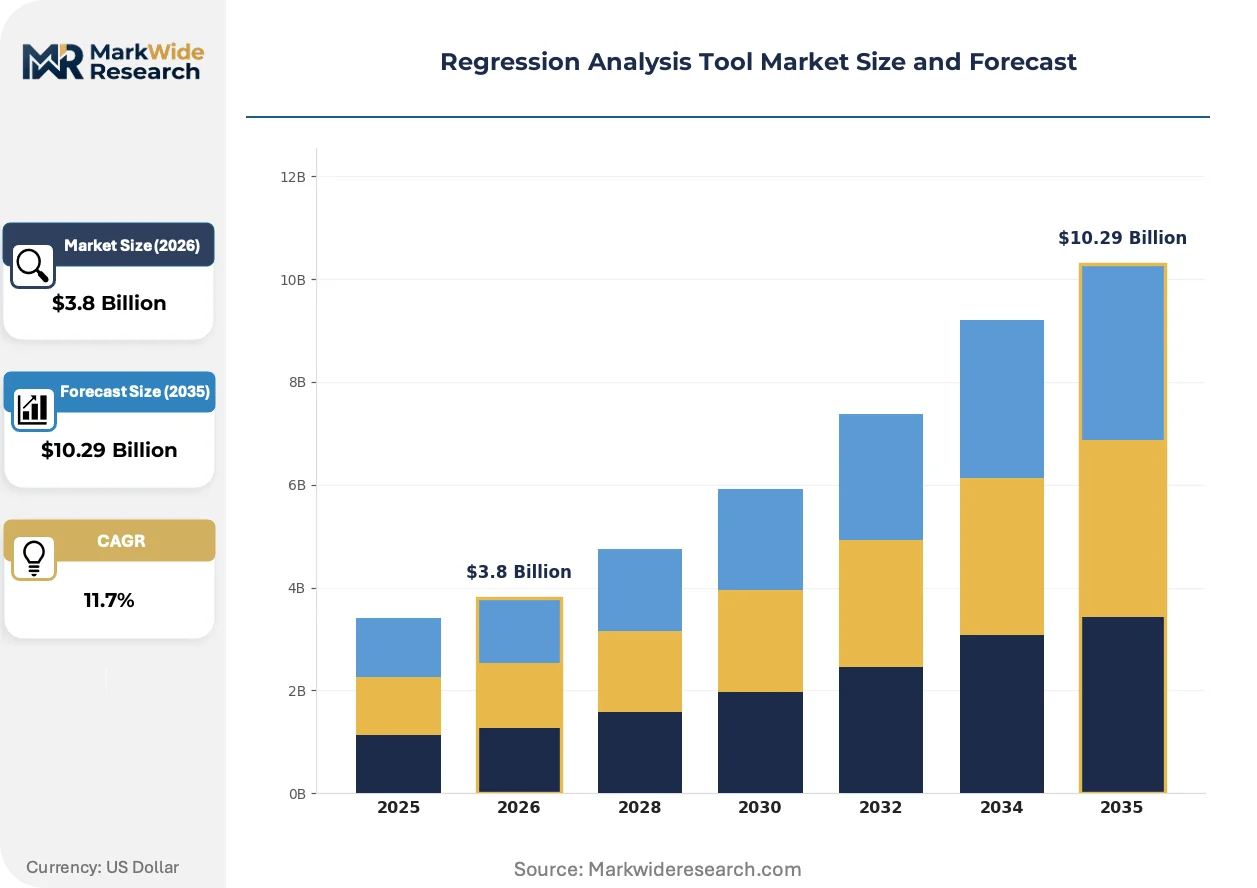
Cloud migration is restructuring how statistical software reaches end users, with API-first platforms and SaaS marketplaces displacing perpetual licensing while the EU AI Act imposes algorithmic transparency mandates on predictive modeling deployments.
Growth Catalysts
- EU AI Act compliance mandates:The regulation requires explainability dashboards and audit trails for automated decision systems, compelling financial services and healthcare providers to upgrade legacy statistical platforms.
- Automotive quality control demand:German automotive and industrial engineering sectors deploy advanced regression software for supply chain optimization and defect prediction in manufacturing lines.
- Genomics data proliferation:Ridge regression techniques capture expanded use in healthcare verticals where high-dimensional datasets with multicollinearity require regularized coefficient estimation.
Market Restraints
- Cross-border compliance friction:The US SEC and FDA maintain divergent documentation requirements for quantitative risk models and clinical trial analyses, complicating product certification for multi-territory vendors.
- Specialized talent scarcity:Shortage of statisticians capable of bridging classical econometrics with machine learning pipelines constrains enterprise implementation timelines.
- On-premises infrastructure sunk costs:Organizations with aging server investments face extended depreciation cycles that delay cloud migration decisions.
Strategic Opportunities
- Hybrid deployment architectures:Convergence of edge computing with centralized cloud analytics enables vendors to serve regulated industries requiring data residency alongside scalable processing.
- Interpretability tooling expansion:Regulatory pressure from GDPR and the EU AI Act creates white space for platforms embedding automated model documentation and bias detection workflows.
- API marketplace distribution:Statistical capabilities delivered through cloud marketplaces reduce customer acquisition costs and accelerate developer adoption in mid-market segments.
Industry Challenges
- Legacy system integration complexity:Enterprises running decades-old statistical environments face data pipeline reconstruction costs when adopting modern regression platforms.
- Model audit standardization delays:Absence of unified certification frameworks across FDA, EMA, and national regulators extends compliance validation timelines for clinical and financial applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regression Analysis Tool Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Regression, Logistic Regression, Polynomial Regression, Ridge Regression Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Academics, Financial Analysts, Data Scientists, Marketing Professionals Industry Vertical: Finance, Healthcare, Retail, Manufacturing |
| Companies Covered | Microsoft, SAS Institute, IBM, MathWorks, TIBCO Software, StataCorp, Minitab, GraphPad Software, Qualtrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regression Analysis Tool Market Evolving Landscape
Statistical computing is fragmenting across deployment modalities as buyers prioritize interoperability with existing cloud infrastructure over monolithic software suites, while regulatory pressure accelerates investment in explainable modeling interfaces.
Automated machine learning (AutoML) is migrating from experimental data science teams into production business intelligence workflows. Financial services risk departments adopt these tools at compressed procurement cycles, compressing the traditional six-month enterprise sales process into self-service API evaluations. The technology is migrating from standalone platforms into embedded capabilities within existing cloud data warehouses, collapsing the addressable market for pure-play statistical vendors.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes predictive applications in credit scoring and medical diagnosis. Industrial consequence includes mandatory human-in-the-loop review for algorithmic decisions affecting fundamental rights. Healthcare and financial services segments in Germany and France are responding by pre-emptively deploying interpretability layers and model cards ahead of enforcement deadlines.
Subscription-based consumption models displace perpetual licensing across mid-market buyers, with procurement teams favoring usage-based pricing tied to compute consumption rather than seat counts. Cloud marketplaces and API-first platforms capture growing share of new customer acquisition, particularly among technology-native verticals. This shift is most visible in Nordic markets where digital procurement maturity accelerates vendor switching and compresses contract renewal cycles.
Regression Analysis Tool Market Segmentation
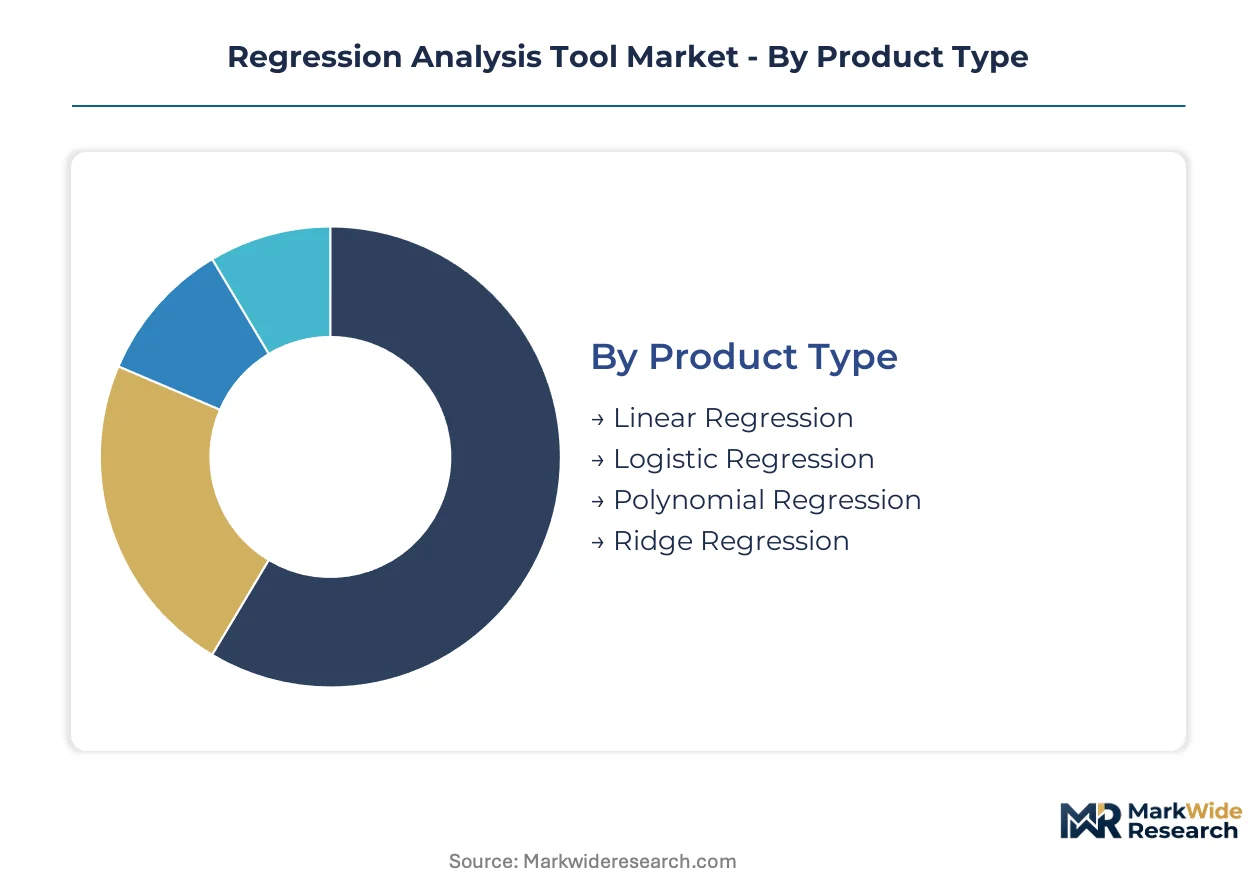
Segmentation in the regression analysis tool market reveals how deployment preferences, user sophistication levels, and regulatory exposure shape purchasing patterns. Vendors must align product architectures with distinct workflow requirements across statistical methods, infrastructure choices, and industry compliance burdens.
Product Type:
Statistical methods span from interpretable baseline techniques to regularized approaches handling high-dimensional complexity, with selection driven by dataset characteristics and regulatory auditability requirements.
- Linear Regression:Ordinary least-squares estimation produces coefficients with straightforward interpretation for financial reporting and clinical study documentation. Demand concentrates in US and European financial services where SEC and EU AI Act mandate explainable model outputs for credit decisions and risk assessments.
- Ridge Regression:L2 regularization shrinks correlated coefficients toward zero, enabling stable estimation in genomics datasets with thousands of predictors. German healthcare providers and pharmaceutical researchers deploy this for biomarker discovery and personalized medicine pipelines where multicollinearity would destabilize ordinary least squares.
- Logistic Regression:Maximum likelihood estimation for binary outcomes serves default prediction in marketing response modeling and medical diagnosis support systems.
- Polynomial Regression:Nonlinear basis expansion captures curvature in manufacturing process control and energy demand forecasting applications.
The dominant share belongs to Linear Regression, while Ridge Regression is closing the gap fastest.
Deployment Model:
Infrastructure choices reflect organizational cloud maturity, data residency constraints, and computational workload volatility across regulated and unregulated sectors.
- Cloud-Based:Scalable compute resources eliminate capital expenditure for variable analytical workloads, with API-first platforms reducing procurement friction. Nordic financial services and technology startups favor consumption-based pricing tied to query volume rather than perpetual licensing.
- Hybrid:Edge-to-cloud pipelines satisfy German automotive manufacturers and French healthcare networks requiring on-premises data residency for sensitive records while leveraging centralized elastic compute for model training.
- On-Premises:Air-gapped installations persist in US defense contractors and Swiss banking infrastructure with strict data sovereignty requirements.
- SaaS:Pre-configured statistical environments accelerate time-to-insight for mid-market retailers and marketing agencies without dedicated data engineering teams.
Cloud-Based deployment holds the dominant position, though Hybrid architectures are expanding most quickly as regulated industries navigate compliance complexity.
End User:
User technical proficiency determines interface complexity tolerance, with distinct workflows separating code-first statisticians from dashboard-dependent business analysts.
- Data Scientists:Python and R library integration, custom estimator development, and pipeline automation capabilities drive platform selection. Concentrated in technology hubs and research institutions across Germany, the United Kingdom, and the Netherlands.
- Financial Analysts:Spreadsheet-compatible outputs, audit trail generation, and regulatory report templates dominate requirements. US and European investment banks and insurance underwriters represent core demand.
- Academics:Citation-grade documentation, reproducibility features, and educational licensing shape procurement in university statistics departments.
- Marketing Professionals:Automated insight generation and campaign attribution dashboards reduce dependency on dedicated analytics support.
Data Scientists command the largest user base, while Financial Analysts are adopting specialized platforms at the steepest rate due to compliance pressure.
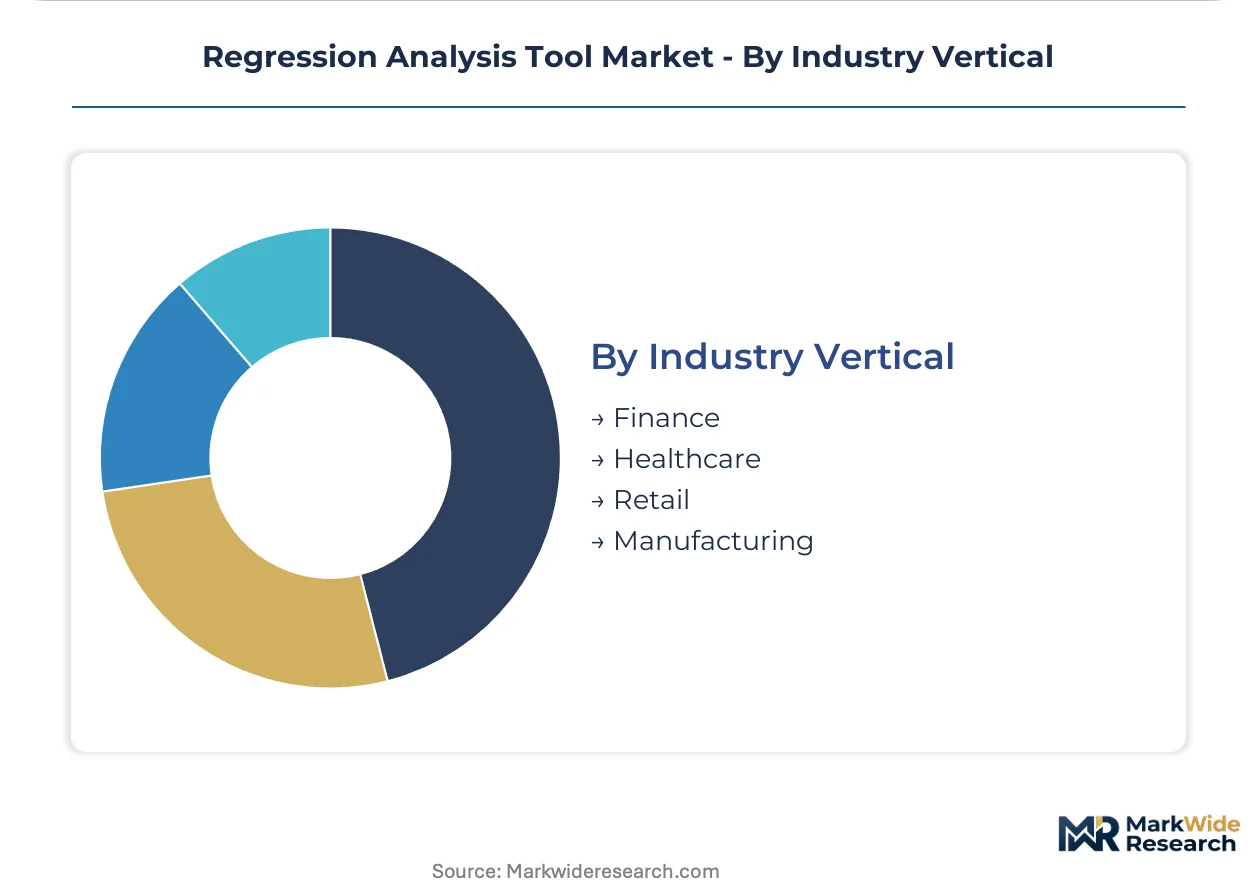
Industry Vertical:
Sector-specific regulatory frameworks and data infrastructure maturity create divergent requirements for model interpretability, validation documentation, and integration depth.
- Finance:Basel III risk-weighted asset calculations, SEC quantitative model disclosure, and EU AI Act credit scoring mandates require auditable regression workflows with human-in-the-loop decision protocols. German and French banking supervisors are accelerating enforcement timelines.
- Healthcare:FDA 21 CFR Part 11 electronic records compliance and EMA clinical trial statistical standards govern predictive modeling for drug development and patient stratification. Genomics applications in Germany and Switzerland drive Ridge regression adoption.
- Retail:Demand forecasting and price elasticity estimation prioritize speed-to-insight over regulatory documentation, favoring cloud-native AutoML integration.
- Manufacturing:Statistical process control and defect prediction in German automotive supply chains deploy real-time regression monitoring on hybrid edge-cloud infrastructure.
Finance retains the dominant vertical position, while Healthcare is gaining share fastest as regulatory clarity around algorithmic accountability crystallizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors regulatory gravity in Germany, where automotive and financial services sectors face accelerated compliance timelines for algorithmic decision systems.
United States
SEC disclosure mandates for quantitative risk models drive financial services procurement of auditable regression platforms. FDA 21 CFR Part 11 requirements govern clinical trial statistical software in pharmaceutical hubs. Boston and San Francisco anchor demand from biotech clusters and fintech accelerators deploying hybrid cloud architectures.
Germany
Automotive quality control and supply chain optimization propel regression tool deployment across industrial engineering. KBA and BaFin supervision tighten algorithmic accountability for credit scoring and manufacturing automation. Stuttgart and Munich concentrate vendor activity around automotive OEM statistical process control implementations.
United Kingdom
Financial conduct authority guidelines shape model risk management requirements for banking and insurance sectors. FCA operational resilience mandates accelerate cloud migration for legacy statistical infrastructure. London's quantitative hedge funds and Cambridge genomics institutes drive specialized Ridge regression adoption.
France
Healthcare networks deploy interpretability layers ahead of EU AI Act enforcement deadlines for high-risk medical devices. ANSM guidance on algorithmic clinical decision support clarifies documentation requirements. Paris and Lyon host pharmaceutical research clusters adopting regularized estimation for biomarker discovery pipelines.
Switzerland
Swissmedic pharmaceutical regulation and banking secrecy laws create dual compliance complexity for cross-border software providers. Precision medicine initiatives in Basel and Zurich drive Ridge regression demand for high-dimensional genomics datasets with strict data residency requirements.
Regression Analysis Tool Market Competitive Landscape
Cloud-native platforms and legacy statistical specialists split the market along deployment modality lines. Consolidation pressure concentrates around three strategic archetypes: hyperscale cloud bundlers, regulated-industry specialists, and open-source commercializers. Dominant competitive moves include API-first marketplace distribution and hybrid deployment architecture development.
Within the cloud-bundler tier, Microsoft and IBM exemplify platform leverage strategies that embed statistical capabilities within broader infrastructure ecosystems. SAS Institute occupies a position as the regulated-industry anchor, serving financial services and healthcare segments requiring auditable modeling workflows. These three companies represent the primary competitive poles shaping procurement patterns across compliance-sensitive verticals.
| Leading Market Players |
|---|
| Microsoft |
| SAS Institute |
| IBM |
| MathWorks |
| TIBCO Software |
| StataCorp |
| Minitab |
| GraphPad Software |
| Qualtrics |
| Others |
Value Network & Pricing Analysis
EU AI Act compliance documentation requirements determine both the premium spread for auditable regression platforms and the geographic distribution of supply chain investments. Vendors serving financial services and healthcare segments absorb certification overhead that widens pricing tiers between basic statistical tools and enterprise-grade solutions with embedded audit trails.
Pricing Analysis
The customization-premium spread separates configured-to-order deployments from standard SaaS offerings, with Ridge regression modules for genomics commanding substantial premiums over baseline linear regression packages. Subscription-based consumption models dominate, though price differentiation hinges on certification grade for EU AI Act compliance and vertical integration depth into cloud infrastructure. Pricing pressure stems from API-first platforms collapsing procurement cycles, compressing margins for traditional enterprise licensing. Mid-market retailers exhibit highest price sensitivity, while German automotive OEMs prioritize compliance-grade solutions over cost optimization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for semiconductor-dependent regression hardware acceleration. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from hyperscaler data center networks across Ireland, Singapore, and Virginia. Raw material dependencies include GPU accelerators, enterprise storage arrays, and specialized statistical computing libraries. Single-source vulnerability persists for NVIDIA-dependent training workloads. Distribution runs through cloud marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The regression analysis tool market functions as a service-attach opportunity where recurring revenue from compliance documentation and model monitoring subscriptions expands faster than core software licensing. Managed interpretability services and automated audit trail generation represent the fastest-growing revenue layer.
For Market Incumbents: Entrench regulatory moats by pre-certifying platforms against emerging EU AI Act enforcement timelines before smaller competitors complete documentation workflows. Deepen vertical integration into hybrid cloud infrastructure to capture data residency requirements from German automotive and French healthcare networks. The threat of API-first entrants collapsing sales cycles demands accelerated self-service marketplace presence.
For New Entrants and Emerging Players: Build out specialized Ridge regression capabilities for genomics applications in Switzerland and Germany where incumbent tooling remains underdeveloped for high-dimensional biomarker discovery. The most penetrable white space sits in mid-market Nordic financial services seeking consumption-based pricing without legacy migration complexity. A developer-first API distribution strategy bypasses entrenched procurement relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulated-industry specialists with pre-built compliance documentation. Long-term viability over the coming decade hinges on sustained regulatory fragmentation between FDA, EMA, and national AI accountability frameworks. Acquisition targets should demonstrate embedded interpretability tooling and existing certifications from German BaFin or French ANSM. The signal to watch is enforcement acceleration for EU AI Act high-risk system classifications.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Launch | Cloud marketplace distribution collapses customer acquisition costs for mid-market penetration. |
| Hybrid Deployment Architecture | Edge-to-cloud pipelines satisfy German KBA data residency mandates for automotive quality control. |
| Regulatory Certification Investment | Pre-emptive EU AI Act compliance documentation accelerates procurement in French healthcare networks. |
| Interpretability Tooling Expansion | Automated model cards address GDPR explainability requirements for credit scoring applications. |
| Strategic Partnership with Hyperscaler | Azure or AWS bundling embeds statistical capabilities within existing cloud infrastructure commitments. |
Research Methodology
A spread of perspectives from data science platform architects, financial services risk officers, healthcare biostatisticians, and cloud procurement specialists converged on the working assumptions governing market sizing. Primary interviews with these stakeholders were cross-referenced against secondary sources including SEC quantitative model disclosures, EMA statistical guidance documents, FDA 21 CFR Part 11 filings, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation validated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with deployment model, end-user sophistication, and industry vertical segmentation dimensions modeled independently. CAGRs were derived from fitted growth curves applied to each segment's adoption trajectory, incorporating cloud migration velocity, regulatory enforcement timelines, and genomics data proliferation as industry-specific forecast inputs.
Stress conditions across EU AI Act enforcement acceleration, cross-border data transfer restrictions, and GPU supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory clarity and cloud infrastructure expansion. Material shifts in German automotive demand or FDA statistical software guidance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Sales Performance Management Market
Analytics
Datacenter Analytics Market
Analytics
Assortment Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
Behavior Analytics Market
Analytics
China Contact Center Analytics Market
Analytics
Global Mobile BI Market
Analytics
Speech and Voice Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Content Analytics Market
Analytics
Brazil Big Data Analytics Market
Analytics
Italy Geospatial Analytics Market
Analytics
UK Geospatial Analytics Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Europe Location Data Analytics Market
Analytics
US Predictive Analytics Market