
 Germany Geospatial Analytics Market | 2026-2036
Germany Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Geospatial Analytics Market Insights
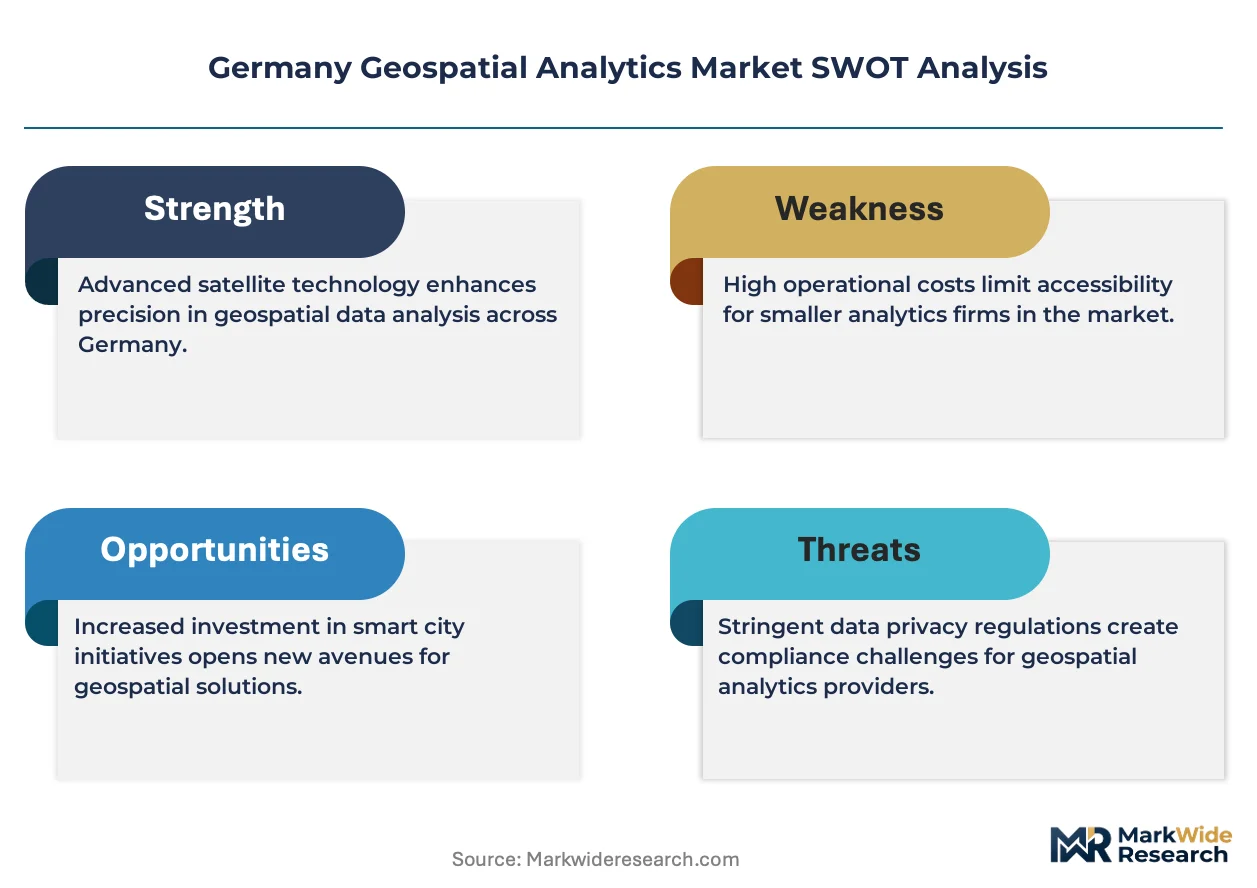
The EU Green Deal is expanding compliance burdens for spatial data providers serving carbon-accounting clients. Hexagon sustains R&D intensity across sensor fusion and digital twin architectures. HERE Technologies dominates automotive-grade mapping layers for German OEMs. Bentley Systems Inc anchors civil engineering workflows through integrated GIS-BIM pipelines.
Germany geospatial analytics encompasses the computational processing of location-based data through geographic information systems, remote sensing platforms, and cloud-native spatial databases to extract actionable intelligence from satellite imagery, LiDAR point clouds, and IoT sensor networks. The technology serves infrastructure planning, environmental compliance, and supply chain optimization across industrial and public sectors. GIS Software and Remote Sensing command the largest installed base, while Cloud Services and AI Integration represent the fastest-expanding margin pools as enterprises migrate from on-premise deployments to API-driven spatial analytics. Government Agencies remain the deepest-pocketed buyer segment, though Logistics Companies show the steepest adoption curve as fleet electrification demands route-level carbon tracking.
Federal Cartography regulations, GDPR location-privacy frameworks, and EU AI Act risk-classification rules collectively shape product roadmaps and data governance architectures for vendors operating in Germany. The country's national mapping agency enforces cadastral accuracy standards that filter market access for foreign platform providers. Stakeholders must weigh interoperability investments against the fragmentation emerging from federal-state data sovereignty tensions.
Market Dynamics
Federal-state data sovereignty tensions over cadastral control are fragmenting procurement decisions across German municipal governments, forcing platform vendors to architect dual-compliance stacks for both national INSPIRE mandates and Bavarian or Baden-Württemberg data localization requirements.
Growth Catalysts
- EU Green Deal carbon-accounting mandates:Spatial data providers face expanded compliance obligations from corporate sustainability reporting rules, pulling demand for geospatial tracking of supply chain emissions and land-use change across industrial clients.
- Precision agriculture sensor networks:Farm cooperatives in Lower Saxony and Schleswig-Holstein deploy sub-meter accuracy positioning systems for variable-rate input application, tightening integration between satellite imagery and autonomous machinery guidance.
- Autonomous vehicle mapping corridors:Dense LiDAR collection campaigns around Stuttgart and Munich generate recurring revenue streams for high-definition road geometry databases serving German OEM validation programs.
Market Restraints
- GDPR location-privacy enforcement:The Federal Commissioner for Data Protection imposes strict anonymization thresholds on mobility datasets, raising processing costs for fleet analytics providers and limiting historical trajectory retention.
- Cloud infrastructure vendor concentration:Hyperscale data center reliance creates single-point-of-failure exposure for geospatial platform operators, with most German mid-market vendors locked into AWS or Azure sovereign cloud instances.
- Cadastral accuracy standard rigidity:The Federal Agency for Cartography mandates sub-decimeter positional tolerances that foreign platform providers struggle to meet without local ground control point networks.
Strategic Opportunities
- AI Act risk-classification carve-outs:Geospatial analytics for infrastructure safety monitoring falls under limited-risk categories, creating regulatory headroom for computer-vision vendors to deploy automated defect detection without full high-risk system obligations.
- Digital twin convergence with BIM:Civil engineering firms in North Rhine-Westphalia integrate 4D spatiotemporal modeling into construction sequencing, opening subscription revenue for real-time site monitoring platforms.
- Eastern federal state underpenetration:Municipal governments in Saxony and Thuringia lag Bavaria in asset management digitization, presenting first-mover expansion paths for GIS vendors with localized German-language support.
Industry Challenges
- Photogrammetrist skill scarcity:German universities produce insufficient graduates trained in LiDAR point cloud classification and SAR interferometry, forcing vendors to poach talent from aerospace/defense sectors at premium compensation.
- Legacy CAD-GIS interoperability friction:Engineering departments maintain decades of AutoCAD and MicroStation archives that resist automated migration to cloud-native spatial databases, prolonging hybrid system maintenance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Geospatial Analytics Market |
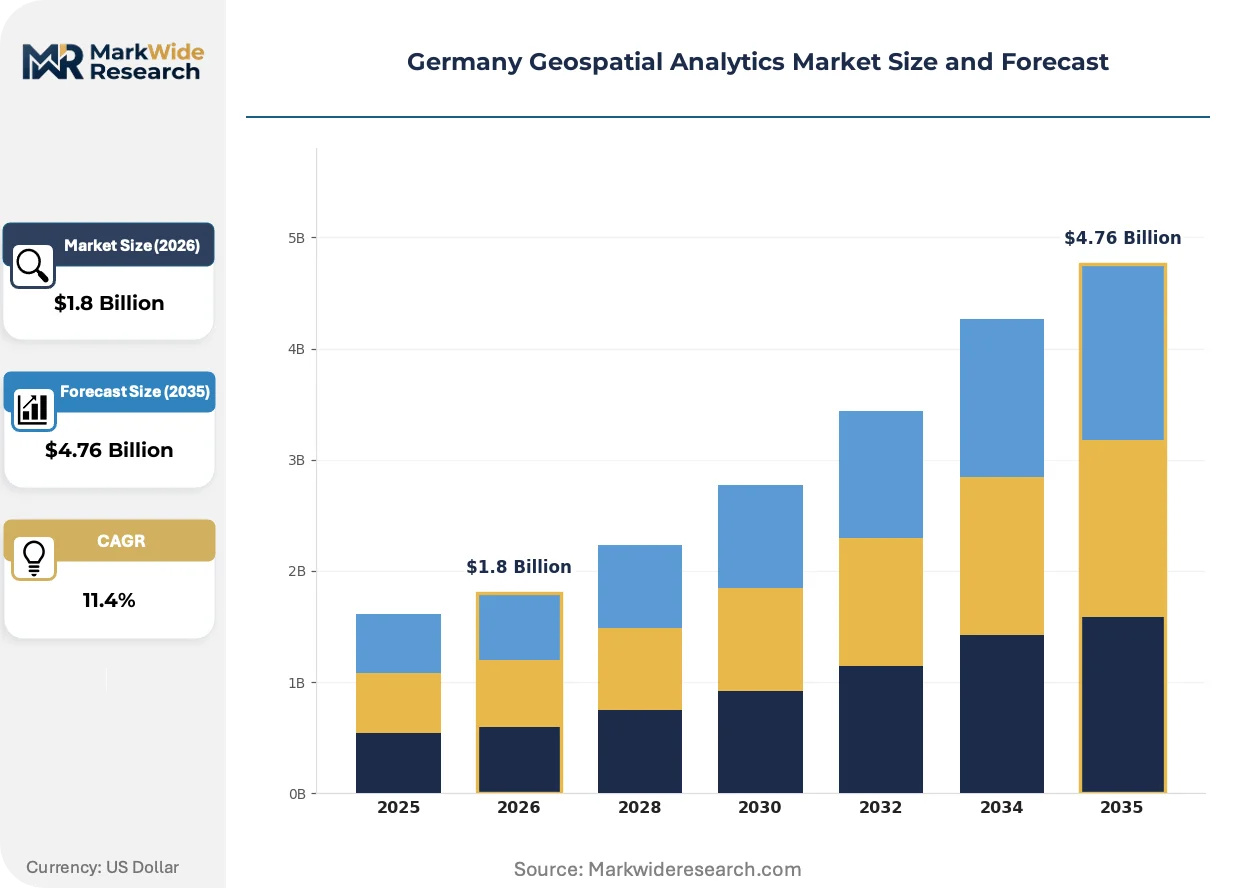
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GIS Software, Remote Sensing, Mapping Solutions, Cloud Services Application: Urban Planning, Environmental Monitoring, Transportation Management, Disaster Management End User: Government Agencies, Real Estate Firms, Logistics Companies, Academic Institutions Technology: AI Integration, Big Data Analytics, IoT, Satellite Imagery |
| Companies Covered | Bentley Systems Inc, UP42, Hexagon, HERE Technologies, SAP, ESRI Inc, Geospin, Capgemini, Trimble, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Geospatial Analytics Market Trends and Innovations
Computational architectures for geospatial processing are pivoting from batch-oriented desktop workflows toward real-time stream analytics, compressing decision cycles for infrastructure operators and environmental regulators who previously relied on monthly imagery refresh cycles.
Sensor fusion pipelines combining satellite SAR, aerial LiDAR, and ground IoT networks are unifying previously siloed data modalities into single coherent digital twin representations. Municipal utilities in Hamburg and Frankfurt deploy these integrated stacks for underground asset detection, collapsing the gap between as-designed BIM records and as-built field conditions. The technology is unifying procurement decisions that previously split budgets between separate remote sensing and field survey contracts.
The EU AI Act's risk-tiering framework is recalibrating product roadmaps for computer-vision vendors serving critical infrastructure inspection. High-risk classification for autonomous damage assessment algorithms triggers conformity assessment obligations through notified bodies, compressing time-to-deployment for German startups against established players with existing quality management certifications. Environmental monitoring applications face lighter oversight, accelerating pilot-to-production transitions for biodiversity tracking platforms.
Subscription pricing for geospatial platforms is displacing perpetual license models across municipal buyer segments. Procurement departments in Berlin and Munich favor operational expenditure structures that align software costs with annual tax revenue cycles, forcing legacy vendors to restructure channel relationships with systems integrators who previously captured multi-year maintenance margins. The shift is most visible among mid-sized cities with constrained capital budgets and mandates for cloud-first digital transformation.
Germany Geospatial Analytics Market Segmentation
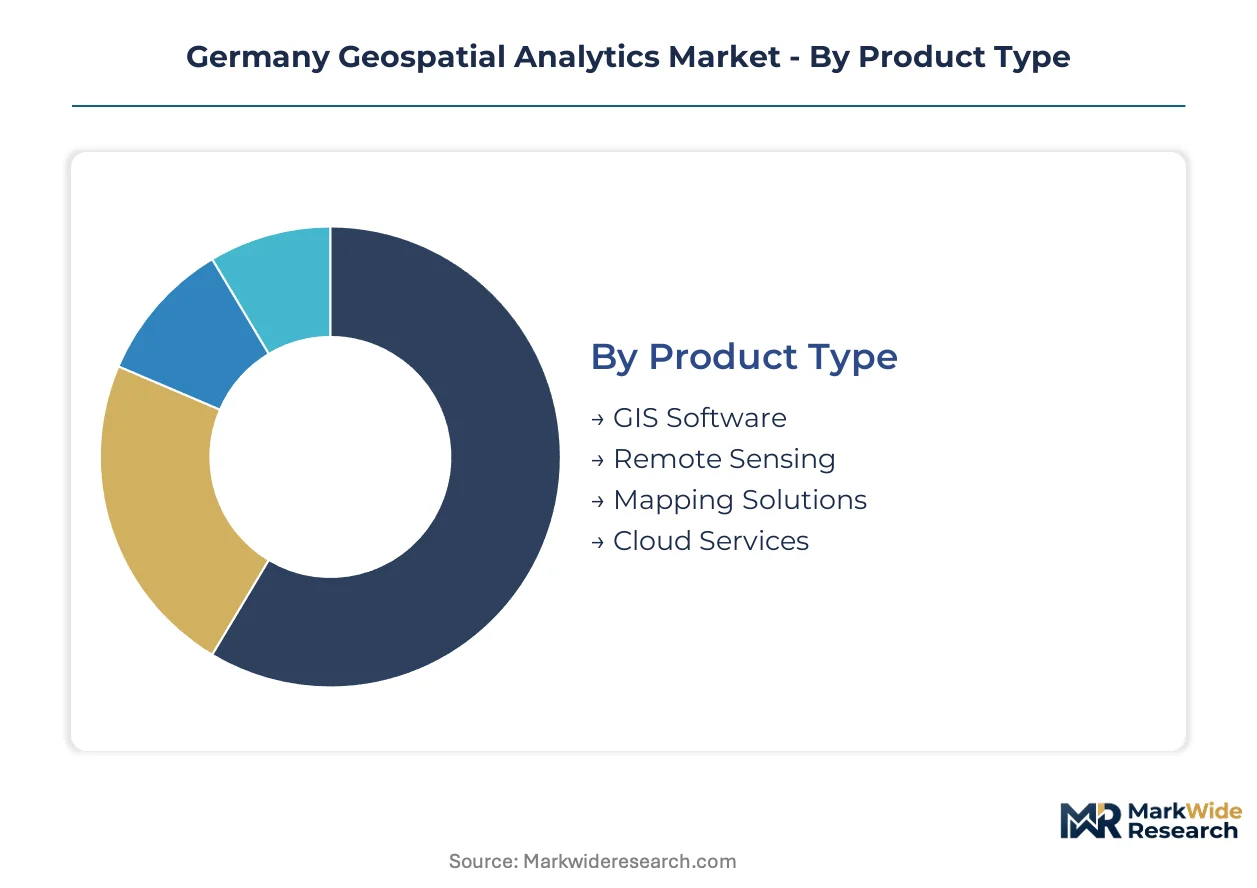
German procurement departments allocate budgets across four distinct product architectures, each carrying different compliance obligations under Federal Cartography standards and federal-state data sovereignty protocols. Vendor positioning requires matching technical capabilities to the specific integration depth each segment demands.
Product Type:
Procurement decisions hinge on deployment topology—on-premise legacy stacks versus API-driven cloud-native architectures—and the cadastral accuracy certifications each product carries.
- GIS Software:Desktop and server-based platforms process vector and raster data for municipal asset management workflows. Bavarian cities favor Esri-integrated stacks for cadastral parcel management, while Baden-Württemberg municipalities prioritize open-source QGIS deployments to reduce licensing exposure.
- Remote Sensing:Aerial and satellite imagery processing pipelines extract land-use classifications through spectral analysis algorithms. Farm cooperatives in Lower Saxony drive demand for Sentinel-2 integration, tightening procurement specifications around sub-meter orthorectification accuracy.
- Mapping Solutions:High-definition road geometry databases serve autonomous vehicle validation programs around Stuttgart and Munich.
- Cloud Services:API-driven spatial analytics platforms displace perpetual licenses across mid-sized municipal governments.
Volume sits with GIS Software; growth tilts toward Cloud Services.
Application:
Use-case maturity varies sharply—urban planning carries decades of institutional precedent while carbon-accounting applications face evolving EU Green Deal compliance specifications.
- Urban Planning:Zoning analysis and infrastructure corridor optimization leverage 3D city models integrated with BIM workflows. Berlin and Hamburg planning departments mandate Level of Detail 2+ building representations, compressing vendor qualification timelines for foreign platform providers.
- Environmental Monitoring:Biodiversity tracking and emissions verification platforms align with CSRD disclosure requirements. Industrial clients in the Ruhr region deploy satellite SAR for surface deformation monitoring around mining reclamation sites.
- Transportation Management:Fleet electrification demands route-level carbon tracking across logistics networks.
- Disaster Management:Flood risk assessment and wildfire propagation modeling serve federal-state civil protection agencies.
Revenue concentrates in Urban Planning; Environmental Monitoring climbs the fastest as compliance deadlines tighten.
End User:
Buyer sophistication spans from procurement-heavy government agencies to capital-constrained academic institutions, dictating pricing architecture and implementation support intensity.
- Government Agencies:Federal and municipal entities command the deepest procurement budgets but impose stringent INSPIRE interoperability mandates. The Federal Agency for Cartography enforces standardized geodata frameworks that filter vendor eligibility.
- Logistics Companies:Fleet operators show the steepest adoption curve as electrification mandates require granular route optimization. DHL and DB Schenker pilot geospatial carbon accounting platforms for EU emissions trading compliance.
- Real Estate Firms:Property valuation and site selection workflows integrate cadastral data with market analytics.
- Academic Institutions:Research consortia access subsidized licensing for remote sensing training and algorithm development.
Spending dominance rests with Government Agencies; Logistics Companies gain share fastest.
Technology:
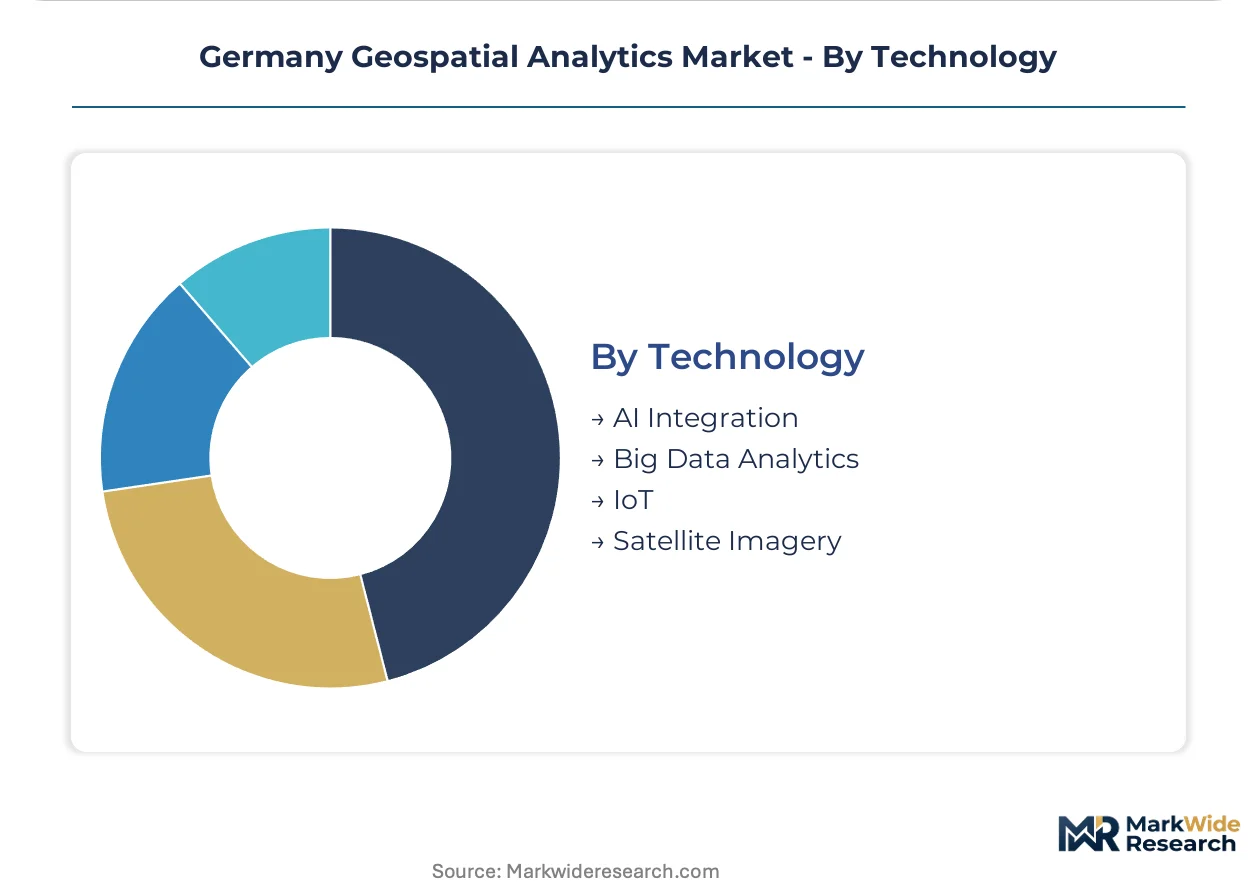
Technology selection determines processing latency, with batch-oriented satellite pipelines yielding to real-time IoT sensor fusion architectures.
- AI Integration:Computer vision algorithms automate feature extraction from LiDAR point clouds and orthophotography. Infrastructure inspection applications fall under limited-risk EU AI Act classifications, reducing conformity assessment burdens.
- IoT:Ground sensor networks feed real-time telemetry into digital twin representations. Hamburg municipal utilities deploy underground asset detection combining pressure transducers with satellite InSAR for pipeline integrity monitoring.
- Big Data Analytics:Distributed processing frameworks handle petabyte-scale imagery archives.
- Satellite Imagery:Optical and synthetic aperture radar constellations provide revisit frequencies down to daily intervals.
Deployment scale favors Satellite Imagery; AI Integration expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's High-Tech Strategy and Baden-Württemberg's Industry 4.0 clusters concentrate federal R&D tax incentives for spatial data processing, anchoring geospatial vendor headquarters and validation corridors across southern Germany.
Bavaria
Precision agriculture cooperatives and autonomous vehicle testing zones drive procurement intensity. The state's Digital Agenda mandates open-data portals for municipal geodata under INSPIRE-aligned frameworks. Munich anchors high-definition mapping R&D corridors serving German OEM validation programs.
Baden-Württemberg
Automotive-grade LiDAR collection and digital twin deployments for manufacturing dominate demand. State-level data localization requirements complement federal cadastral standards, filtering vendor eligibility. Stuttgart clusters HD map production facilities for autonomous driving validation.
North Rhine-Westphalia
Civil engineering firms integrate 4D spatiotemporal modeling into construction sequencing workflows. The state's building digitization roadmap accelerates GIS-BIM convergence mandates. Cologne and Düsseldorf municipal utilities deploy integrated sensor stacks for underground asset detection.
Lower Saxony
Farm cooperatives deploy sub-meter accuracy positioning systems for variable-rate input application. The Federal Agency for Cartography enforces standardized geodata frameworks that shape procurement specifications. Hanover anchors satellite imagery processing hubs for agricultural analytics.
Hamburg
Port logistics operators and municipal utilities drive demand for real-time IoT sensor fusion architectures. The city's smart infrastructure program mandates cloud-native spatial analytics for harbor asset management. Hamburg deploys combined pressure transducer and InSAR networks for pipeline integrity monitoring.
Germany Geospatial Analytics Market Competitive Landscape
German producers anchor the engineering-software tier; Swedish and US specialists hold sensor-hardware and cloud-platform positions. The vendor base stratifies across three layers: integrated GIS-BIM suite providers, automotive-grade mapping specialists, and API-driven cloud analytics platforms. Strategic moves concentrate on M&A for sensor-fusion capabilities and geographic expansion into eastern federal states.
Within the integrated engineering-software tier, Bentley Systems Inc and Hexagon exemplify platform consolidation strategies that merge civil design workflows with spatial analytics. HERE Technologies occupies a distinct position at the automotive-grade mapping vector, while ESRI Inc anchors the municipal GIS installed base. UP42 represents the cloud-native archetype, situating API-first spatial data access within the platform-economy segment. These four entities collectively illustrate the competitive tension between perpetual-license incumbents and subscription-model challengers reshaping procurement patterns across German public-sector buyers.
| Leading Market Players |
|---|
| Bentley Systems Inc |
| UP42 |
| Hexagon |
| HERE Technologies |
| SAP |
| ESRI Inc |
| Geospin |
| Capgemini |
| Trimble |
| Others |
Pricing and Supply Chain Analysis
Municipal procurement departments across Bavaria and Baden-Württemberg now mandate API-driven cloud architectures over perpetual licenses, forcing vendors to absorb migration costs and compressing margins on legacy GIS deployments while creating premium capture opportunities for subscription-native platforms.
Pricing Analysis
Short lead-time premiums dominate municipal tenders, with Berlin and Munich planning departments paying subscription surcharges for sub-30-day implementation timelines against standard 90-day onboarding cycles. Three-tier pricing structure across premium, standard, and economy levels separates INSPIRE-certified stacks from open-source QGIS deployments and basic desktop licenses. Cost compression in the economy tier is intensifying because Baden-Württemberg's data localization requirements force redundant infrastructure spend. Logistics companies show the highest price sensitivity, while federal agencies tolerate premium pricing for cadastral accuracy guarantees.
Supply Chain Analysis
Federal Agency for Cartography certification gates filter component sourcing, with sensor hardware drawing from Sweden, satellite imagery feeds anchored in France and Luxembourg, and cloud infrastructure concentrated in German sovereign AWS and Azure regions. LiDAR sensors, orthorectification software licenses, and ground control point networks constitute critical input dependencies. Single-source vulnerability runs through hyperscale cloud instances locked to AWS or Azure. Distribution runs through systems integrators who capture implementation margins and annual maintenance renewals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany geospatial analytics market sits in a technology-transition phase, with cloud-native API platforms displacing desktop GIS workflows and real-time sensor fusion architectures replacing batch-oriented satellite processing.
For Market Incumbents: Anticipate margin erosion in perpetual-license maintenance streams as municipal buyers shift to operational expenditure models. Consolidate position through backward integration into LiDAR sensor manufacturing to reduce hardware cost exposure. Prioritize certification investments for EU AI Act limited-risk classifications to accelerate automated defect detection deployment timelines against cloud-native challengers.
For New Entrants and Emerging Players: EU Green Deal carbon-accounting mandates in Germany open a window for supply chain emissions tracking platforms targeting industrial clients in the Ruhr region. White-space concentration sits with municipal governments in Saxony and Thuringia lagging Bavaria's digitization maturity. Target farm cooperatives in Lower Saxony with localized German-language support and Sentinel-2 integration as the most penetrable segment.
For Investors and Strategic Acquirers: The window for entry favors computer-vision specialists with existing quality management certifications that compress EU AI Act conformity assessment timelines. Long-term viability hinges on sensor-fusion capabilities unifying SAR, LiDAR, and IoT modalities into single-platform offerings. Watch for federal-state data sovereignty tensions escalating procurement fragmentation as the signal indicating platform consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | GIS-BIM convergence mandates in North Rhine-Westphalia accelerate 4D spatiotemporal modeling adoption. |
| Acquisition of Specialist Firm | LiDAR point cloud classification capabilities address photogrammetrist skill scarcity forcing premium talent poaching. |
| Geographic Expansion | Eastern federal state underpenetration in Saxony and Thuringia offers first-mover municipal procurement wins. |
| Strategic Partnership | Automotive OEM validation programs around Stuttgart demand HD map production alliances. |
| Product Launch | Real-time IoT sensor fusion architectures serve Hamburg port logistics and pipeline integrity monitoring contracts. |
Research Methodology
Federal Cartography regulatory filings, EU INSPIRE directive implementation reports, and municipal procurement databases formed the secondary backbone of this analysis. Primary interviews with GIS platform product managers, municipal IT procurement officers, and civil engineering firm technology directors combined with secondary validation across the modeling period. Bottom-up triangulation aggregated segment-level deployment data while top-down approaches cross-checked against federal R&D tax incentive distributions and state-level digital agenda budgets.
Bottom-up modeling built volume estimates from individual municipal contract values and enterprise subscription tiers, while top-down approaches validated against aggregate software spending reported in federal IT procurement disclosures. Segmentation dimensions across the analysis window included deployment topology, cadastral accuracy certification level, integration depth with BIM workflows, and federal-state data sovereignty compliance tier. CAGRs derived from year-over-year contract value analysis adjusted for cloud migration timing and INSPIRE mandate implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for edge-computing sensor fusion would alter the outlook if latency requirements shift faster than projected. Forecasts reflect assumptions regarding federal-state data sovereignty resolution timelines and EU AI Act enforcement consistency. A model refresh is warranted upon material change in German sovereign cloud infrastructure availability or Federal Cartography accuracy standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Visual Analytics Market
Analytics
Global People and HR Analytics Software Market
Analytics
Business Intelligence (BI) Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Capacity Management Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Global Mobile BI Market
Analytics
Latin America Big Data Analytics Market
Analytics
Global Cognitive Analytics Market
Analytics
Marketing Mix Optimization Market
Analytics
Speech Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Europe Emotion Analytics Market
Analytics
Personal Analytics Market