
 Europe Location Analytics Market | 2026-2036
Europe Location Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Location Analytics Market Foresight
Germany is reconfiguring its geospatial data infrastructure through federal smart-city investments and industrial digitalization programs. HERE Global B.V. leverages its native mapping heritage and automotive-grade location services to dominate European fleet and mobility applications. Esri Global, Inc. sustains deep penetration across government and environmental agencies with its ArcGIS platform stack. Microsoft Corporation anchors enterprise adoption by embedding spatial analytics within Azure cloud services and Power BI workflows.
Location analytics encompasses the computational processing of geospatial coordinates, spatial relationships, and geographic attributes to derive operational intelligence, typically integrating GPS telemetry, satellite imagery, and address-level demographic databases. The technology serves commercial and governmental decision-makers by visualizing asset distribution, optimizing route efficiency, and predicting demand patterns across physical networks. Software and cloud solutions capture the dominant share of product-type revenue as enterprises migrate from legacy GIS desktop licenses to scalable subscription architectures. Cloud-based and hybrid deployment models are expanding fastest among mid-market retailers and logistics operators seeking elastic compute without full infrastructure ownership. The logistics vertical within industry applications generates concentrated margin pools, driven by real-time fleet tracking requirements and warehouse site selection algorithms.
The EU AI Act imposes risk-classification requirements on automated geospatial decision systems, while GDPR mandates strict anonymization protocols for location data processing across member states. EASA guidelines increasingly influence drone-collected spatial imagery standards, affecting aerial survey and infrastructure monitoring workflows. Stakeholders must weigh compliance architecture investments against the competitive penalty of restricted data granularity in European markets.
Market Dynamics
Cloud-native spatial data platforms are compressing deployment cycles from months to days, forcing legacy GIS vendors to abandon perpetual licenses for subscription architectures. This shift redistributes margin pools toward infrastructure-as-code providers and managed analytics services.
Growth Catalysts
- GDPR-compliant data anonymization tooling:Automated pseudonymization pipelines unlock secondary use of mobility datasets across France and the Netherlands for retail footfall analytics.
- Real-time fleet telemetry integration:Logistics operators in Belgium deploy edge-computed GPS streams to optimize last-mile routing algorithms.
- EASA drone imagery standards:Standardized aerial capture protocols accelerate infrastructure inspection workflows across German rail and energy networks.
Market Restraints
- EU AI Act risk-classification overhead:Automated geospatial decision systems face mandatory conformity assessments, extending commercialization timelines.
- Cloud infrastructure concentration:Three hyperscale providers control over 70% of European data center capacity, creating single-point-of-failure exposure.
- Optical satellite imagery substitution:Synthetic aperture radar penetrates cloud cover, displacing electro-optical providers in Nordic maritime monitoring contracts.
Strategic Opportunities
- Polish and Romanian smart-city underpenetration:EU cohesion funds finance municipal digital twin deployments where location analytics penetration lags Western benchmarks.
- Carbon accounting mandates:CSRD scope 3 emissions reporting requires supply chain geospatial traceability, opening enterprise service contracts.
- Digital twin-GIS convergence:Building information modeling integrates with real-time sensor layers for predictive facility management in Dutch port complexes.
Industry Challenges
- Geospatial data engineering talent scarcity:European universities produce insufficient graduates combining GIS science with machine learning operations.
- Legacy ERP integration complexity:SAP and Oracle systems require custom API development to ingest spatial analytics outputs.
- Cross-border data residency fragmentation:Member state cloud localization rules complicate multi-national deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Location Analytics Market |
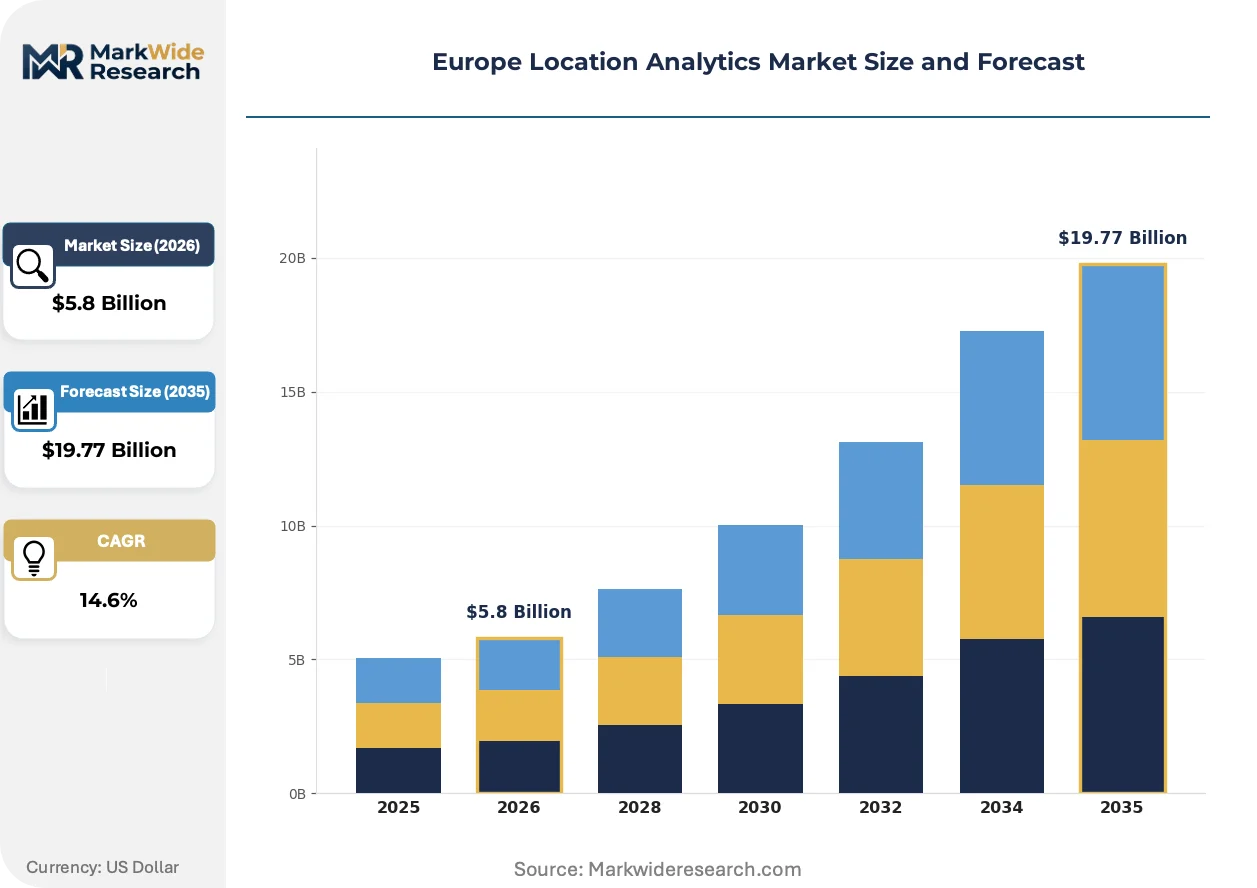
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.77 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Cloud Solutions, Integrated Platforms, APIs End User: Retailers, Government Agencies, Transportation, Telecom Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Industry Vertical: Logistics, Real Estate, Marketing, Finance |
| Companies Covered | Microsoft Corporation, Esri Global, Inc., HERE Global B.V., Google LLC, TomTom International B.V., Hexagon AB, SAP SE, IBM Corporation, SAS Institute Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Location Analytics Market Shifts & Advancements
Edge-computed spatial inference is redistributing analytics workloads from centralized clouds to field-deployed sensors, altering cost structures and latency benchmarks across mobility and infrastructure monitoring.
Serverless query engines for geospatial datasets are rendering obsolete provisioned data warehouse architectures. Mid-market retailers in Spain and Italy adopt on-demand spatial SQL without infrastructure ownership. This compression eliminates upfront capital requirements and accelerates pilot-to-production cycles.
The EU AI Act's risk-tiering framework imposes documentation burdens on automated location-based decision systems. High-risk applications in predictive policing and credit scoring face mandatory human oversight. German automotive OEMs are restructuring their mobility analytics stacks to segregate safety-critical from informational functions.
Subscription-based platform access displaces perpetual software licenses across municipal procurement. French regional governments consolidate vendor relationships through framework agreements. This consolidation favors multi-tenant SaaS architectures over on-premise deployments in public sector tenders.
Europe Location Analytics Market Segmentation
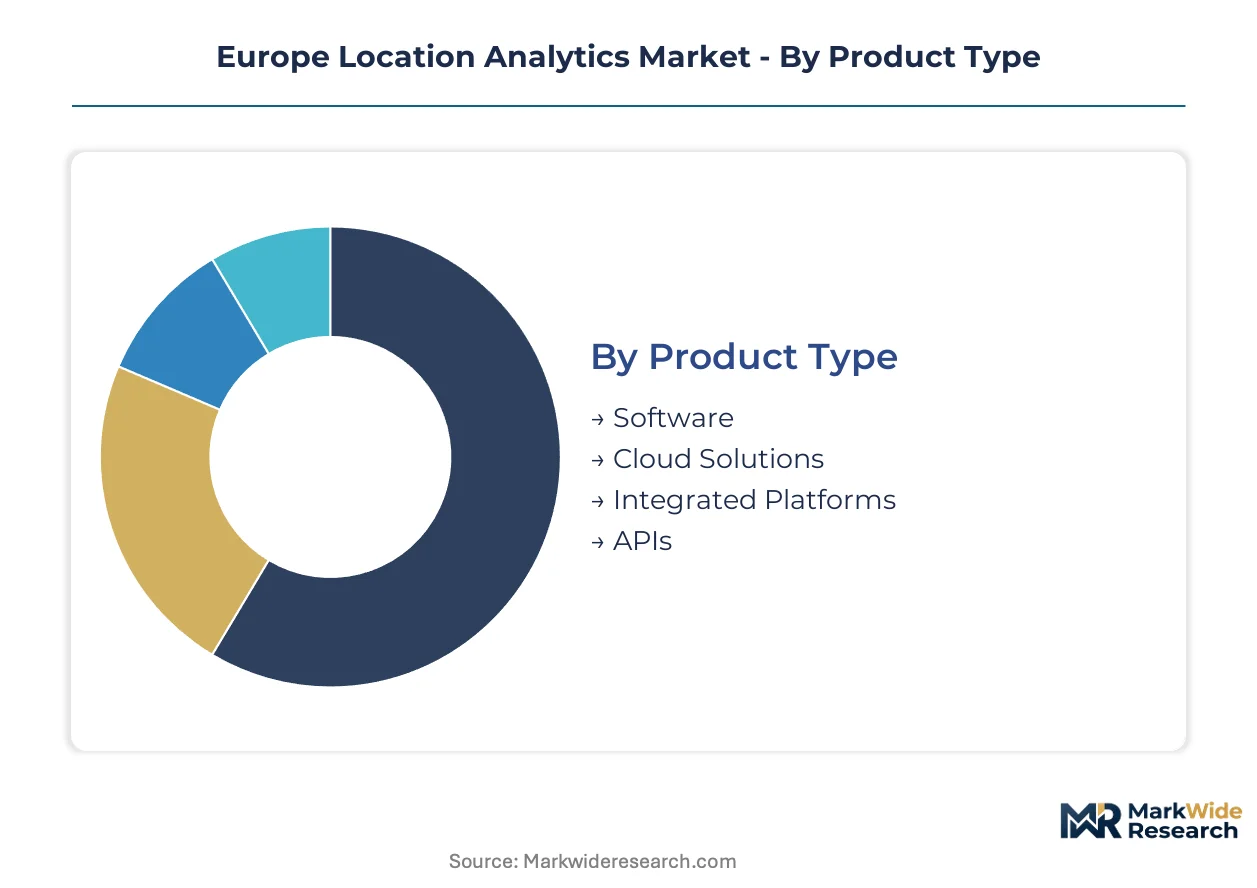
Segmentation in the Europe Location Analytics Market reflects divergent maturity curves across deployment architectures and compliance requirements. Procurement patterns cluster around subscription elasticity for mid-market adopters while government tenders favor integrated platform stacks.
Product Type:
Mature perpetual-license vendors compete against cloud-native entrants reshaping commercial terms across German automotive and French retail procurement cycles.
- Software:Desktop GIS suites with perpetual licensing persist in German municipal planning departments requiring offline sovereignty. Legacy Esri ArcGIS installations dominate environmental agency workflows where data residency mandates restrict cloud migration.
- Cloud Solutions:Subscription-based spatial analytics platforms compress deployment cycles from months to days. Dutch logistics operators and Belgian fleet managers prioritize elastic compute for seasonal demand spikes without infrastructure ownership.
- Integrated Platforms:Unified stacks combining visualization, ETL pipelines, and governance tooling. Spanish retail chains consolidate vendor relationships through framework agreements reducing procurement overhead.
- APIs:Embedded geocoding and routing services for application developers. Italian insurtech startups consume pay-per-request address validation without platform commitment.
Cloud Solutions handles the majority of throughput; APIs are expanding most quickly among developer-centric adopters.
End User:
Cost-tier differentiation separates enterprise-scale integrators from departmental pilot programs across public and private procurement channels.
- Retailers:Footfall analytics and site selection algorithms drive adoption. French hypermarket chains deploy GDPR-compliant mobility datasets for catchment area modeling while German discounters optimize last-mile distribution nodes.
- Government Agencies:Environmental monitoring and urban planning applications dominate. Dutch water boards and Belgian regional governments mandate open-data interoperability standards in tender specifications.
- Transportation:Real-time fleet telemetry and predictive maintenance integration. German rail operators and Polish logistics consortia prioritize EASA-compliant drone imagery for infrastructure inspection.
- Telecom:Network coverage optimization and 5G site planning. Nordic operators combine satellite-derived terrain models with subscriber density heatmaps for capital allocation.
Government Agencies anchor procurement volume through multi-year framework agreements; Retailers are climbing the fastest as GDPR-compliant anonymization tooling unlocks secondary data monetization.
Deployment:
Application-critical workloads determine infrastructure placement across latency-sensitive and compliance-bound use cases.
- On-Premises:Air-gapped installations for defense and intelligence applications. German federal agencies mandate sovereign data centers for classified geospatial processing under national security guidelines.
- Cloud-Based:Fully managed spatial data platforms with automatic scaling. Mid-market retailers in Spain and Italy adopt serverless query engines eliminating provisioned warehouse overhead.
- Hybrid:Sensitive data remains on-premise while compute-intensive processing shifts to cloud. French banking regulators approve this architecture for credit risk geospatial modeling.
- Edge Computing:Field-deployed inference for real-time decisioning. Belgian port authorities process container telemetry locally before cloud synchronization reducing latency for customs clearance.
Cloud-Based deployment captures the widest adoption base; Edge Computing is gaining share fastest among latency-critical logistics and infrastructure monitoring applications.
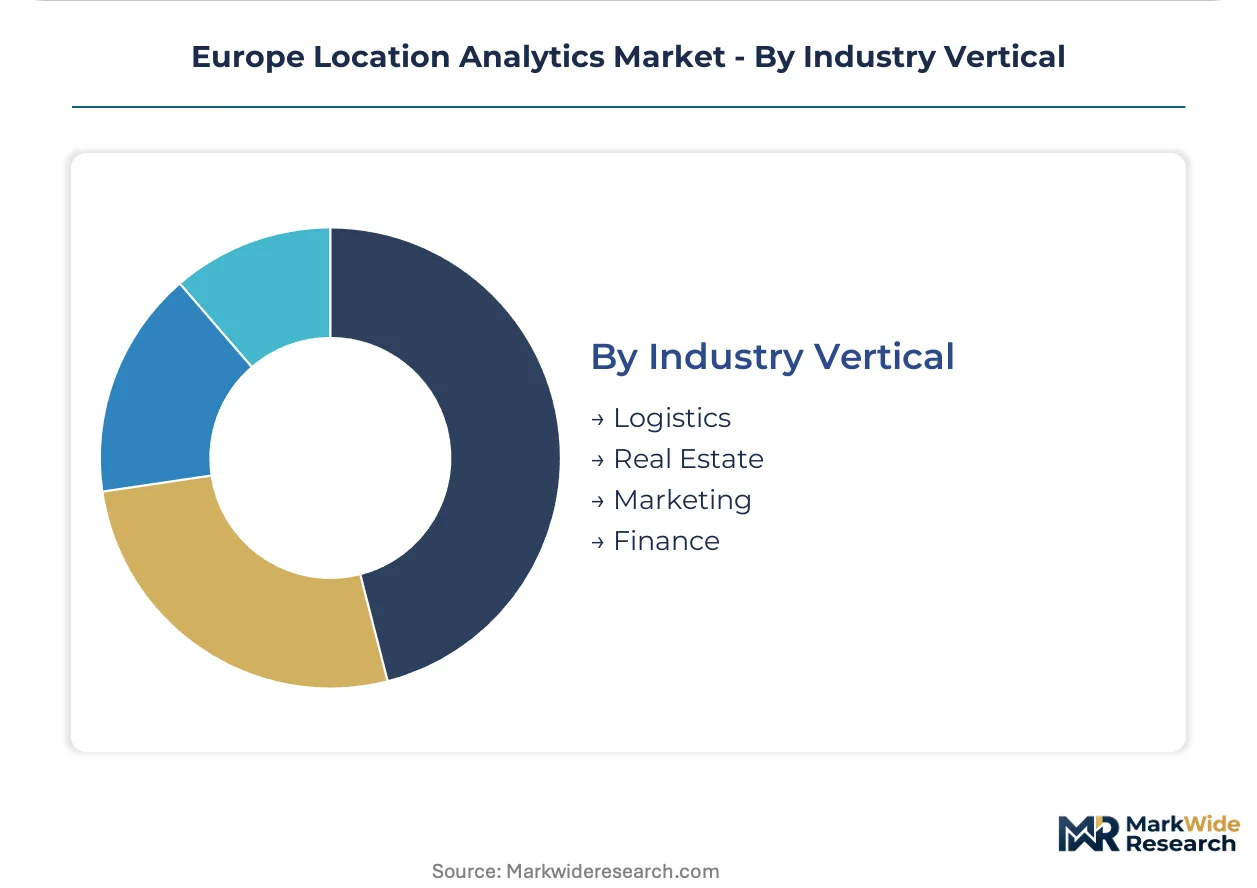
Industry Vertical:
Margin concentration follows regulatory compliance intensity and data granularity requirements across sectoral applications.
- Logistics:Fleet optimization and warehouse site selection generate concentrated service revenue. Dutch distribution hubs and German automotive supply chains deploy real-time GPS streams for predictive routing algorithms.
- Real Estate:Property valuation and development risk assessment. UK institutional investors and French REITs consume demographic overlay datasets for portfolio allocation decisions.
- Marketing:Location-based audience segmentation and campaign attribution. GDPR constraints limit precision compared to other regions, favoring aggregated mobility patterns over individual tracking.
- Finance:Credit scoring and insurance underwriting incorporating geographic risk factors. German insurers model flood exposure using high-resolution elevation data while Spanish banks assess branch network optimization.
Logistics handles the majority of vertical-specific throughput; Real Estate is the fastest mover on share as CSRD carbon accounting mandates require supply chain geospatial traceability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement by CNIL and other national regulators anchors demand patterns across Western Europe, while EU cohesion funds accelerate adoption in Eastern markets. Location analytics procurement clusters around logistics hubs and automotive manufacturing corridors.
Germany
Federal smart-city investments and industrial digitalization programs drive public-sector demand. The KBA influences automotive-grade geospatial standards for connected vehicle fleets. Bavarian automotive clusters and North Rhine-Westphalia logistics hubs deploy real-time fleet telemetry for predictive routing algorithms.
France
Hypermarket chains deploy GDPR-compliant mobility datasets for catchment area modeling and site selection. CNIL mandates strict anonymization protocols for retail footfall analytics. Paris-based banking regulators approve hybrid cloud architectures for credit risk geospatial modeling.
Netherlands
Dutch distribution hubs prioritize elastic compute for seasonal demand spikes in warehouse site selection. The EU AI Act risk-classification framework shapes automated port logistics systems. Rotterdam port authorities process container telemetry through edge-computed inference before cloud synchronization.
Belgium
Last-mile logistics operators deploy edge-computed GPS streams to optimize routing algorithms. GDPR-compliant data residency rules govern cross-border fleet data flows. Antwerp port complexes integrate building information modeling with real-time sensor layers for predictive facility management.
Poland
EU cohesion funds finance municipal digital twin deployments where location analytics penetration lags Western benchmarks. National cloud localization rules complicate multi-national deployment architectures. Warsaw and Krakow smart-city initiatives represent underpenetrated expansion opportunities for platform vendors.
Europe Location Analytics Market Competitive Landscape
Cloud-native specialists and legacy platform incumbents split the market along deployment architecture lines. The vendor landscape organizes around three strategic archetypes: mapping heritage providers with automotive-grade certifications, enterprise software integrators embedding spatial analytics within cloud productivity suites, and open-data platform operators monetizing API consumption. Consolidation pressures favor multi-tenant SaaS architectures over perpetual licensing. Competitive moves concentrate on subscription model transitions and framework agreement consolidation with regional governments.
Within the mapping heritage tier, HERE Global B.V. and TomTom International B.V. exemplify European-native geospatial infrastructure providers. Microsoft Corporation and Google LLC occupy positions as hyperscale cloud integrators embedding location services within enterprise productivity workflows. Esri Global, Inc. anchors the government and environmental agency segment through deep ArcGIS platform penetration.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Esri Global, Inc. |
| HERE Global B.V. |
| Google LLC |
| TomTom International B.V. |
| Hexagon AB |
| SAP SE |
| IBM Corporation |
| SAS Institute Inc. |
| Others |
Supply & Pricing Matrix
GDPR-compliant data residency requirements across member states compress pricing tier spreads while fragmenting supply chain architectures into national-cloud silos. This regulatory chokepoint forces vendors to replicate infrastructure across jurisdictions, inflating fixed costs that concentrate in premium-tier subscriptions while economy offerings face margin erosion from compliance overhead.
Pricing Analysis
Western European markets command 40-60% subscription premiums over Eastern European equivalents due to stricter anonymization tooling requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by data sovereignty certification and edge-compute latency guarantees. Cost compression in the economy tier intensifies because hyperscale cloud providers absorb compliance tooling into base platform fees. Mid-market retailers in Spain and Italy exhibit highest price sensitivity, while German federal agencies accept premium pricing for air-gapped sovereignty guarantees.
Supply Chain Analysis
Export-control restrictions on geospatial AI training hardware under EU dual-use regulations limit GPU cluster flows into certain deployment configurations. Supply concentrates in Ireland, the Netherlands, and Germany for hyperscale cloud infrastructure, while specialized edge-compute hardware sources from Taiwan and South Korea. Raw material dependencies span silicon photonics for LiDAR sensors, rare earth elements for GPS chipset magnetometers, and high-purity germanium for thermal imaging. Single-source vulnerability concentrates in EUV lithography equipment for processor fabrication. Distribution runs through framework agreements with regional government consortia and direct SaaS provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source geospatial engines and sovereign-cloud alternatives threaten incumbent platform margins by commoditizing core routing and visualization functions. Incumbents must defend subscription pricing power through compliance-integrated differentiation.
For Market Incumbents: Insulate recurring revenue by embedding GDPR and EU AI Act conformity assessments as non-discretionary platform features. Acquire specialized edge-compute hardware vendors to secure supply chain autonomy against semiconductor export restrictions. Prioritize framework agreement consolidation with French regional governments and Dutch water boards where multi-year procurement cycles lock out challenger platforms.
For New Entrants and Emerging Players: Pursue white-space expansion in Polish and Romanian municipal digital twin deployments where EU cohesion funds finance infrastructure without incumbent platform entrenchment. Target serverless geospatial query engines for Italian and Spanish mid-market retailers seeking pilot-to-production acceleration without capital commitment. Lead with carbon accounting traceability modules that align with CSRD scope 3 reporting mandates.
For Investors and Strategic Acquirers: The EU AI Act's high-risk system classification reshapes the acquisition landscape by elevating compliance documentation to due diligence centerpiece. Position holdings for long-term viability by favoring targets with automotive-grade HERE certifications or existing CNIL audit clearance. Monitor EASA drone imagery standard adoption rates as inflection signal for aerial survey platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Data Sovereignty Certification | CNIL and German BfDI audits unlock public-sector framework agreements worth multi-year recurring commitments. |
| Edge-Compute Hardware Backward Integration | Captive supply of field-deployed inference units reduces latency for Belgian port customs clearance workflows. |
| Carbon Accounting Module Launch | CSRD scope 3 traceability features capture enterprise service contracts from Dutch distribution hubs. |
| Framework Agreement Consolidation | French regional government tender aggregation displaces point-solution vendors from municipal GIS procurement. |
| Drone Imagery Platform Acquisition | EASA-compliant aerial capture capabilities accelerate German rail network inspection contract wins. |
Research Methodology
A spread of perspectives from fleet operations directors, municipal GIS procurement officers, cloud platform engineers, and regulatory compliance leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EU AI Act implementation guidance, CNIL anonymization enforcement patterns, EASA drone certification databases, and hyperscaler European data center expansion disclosures. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against EU cohesion fund allocation patterns anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling segmentation by deployment architecture, organization size tier, industry vertical, and national regulatory cluster. CAGRs derived from logistic curve fitting to cloud migration saturation patterns and edge-compute penetration trajectories. Forecast inputs incorporated automotive OEM connected-vehicle rollout schedules and CSRD reporting mandate compliance timelines without year-specific anchoring.
Sensitivities concentrate around EU AI Act enforcement intensity, hyperscale cloud concentration rulings, and synthetic aperture radar substitution rates for optical satellite contracts. Forecasts reflect documented assumptions on GDPR harmonization across member states and cohesion fund disbursement continuity. Material shifts in export-control regime stringency or EASA imagery standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Self Service Analytics Market
Analytics
Tourism Industry Big Data Analytics Market
Analytics
Business Value Dashboard Market
Analytics
Cloud Analytics Market
Analytics
Europe Data Monetization Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Contact Center Analytics Market
Analytics
Iraq ICT Market
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Automated Analytics Market
Analytics
North America Speech Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Process Analytics Market
Analytics
Spain Geospatial Analytics Market
Analytics
Predictive Analytics Market