
 Spain Geospatial Imagery Analytics Market | 2026-2036
Spain Geospatial Imagery Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Geospatial Imagery Analytics Market Insights
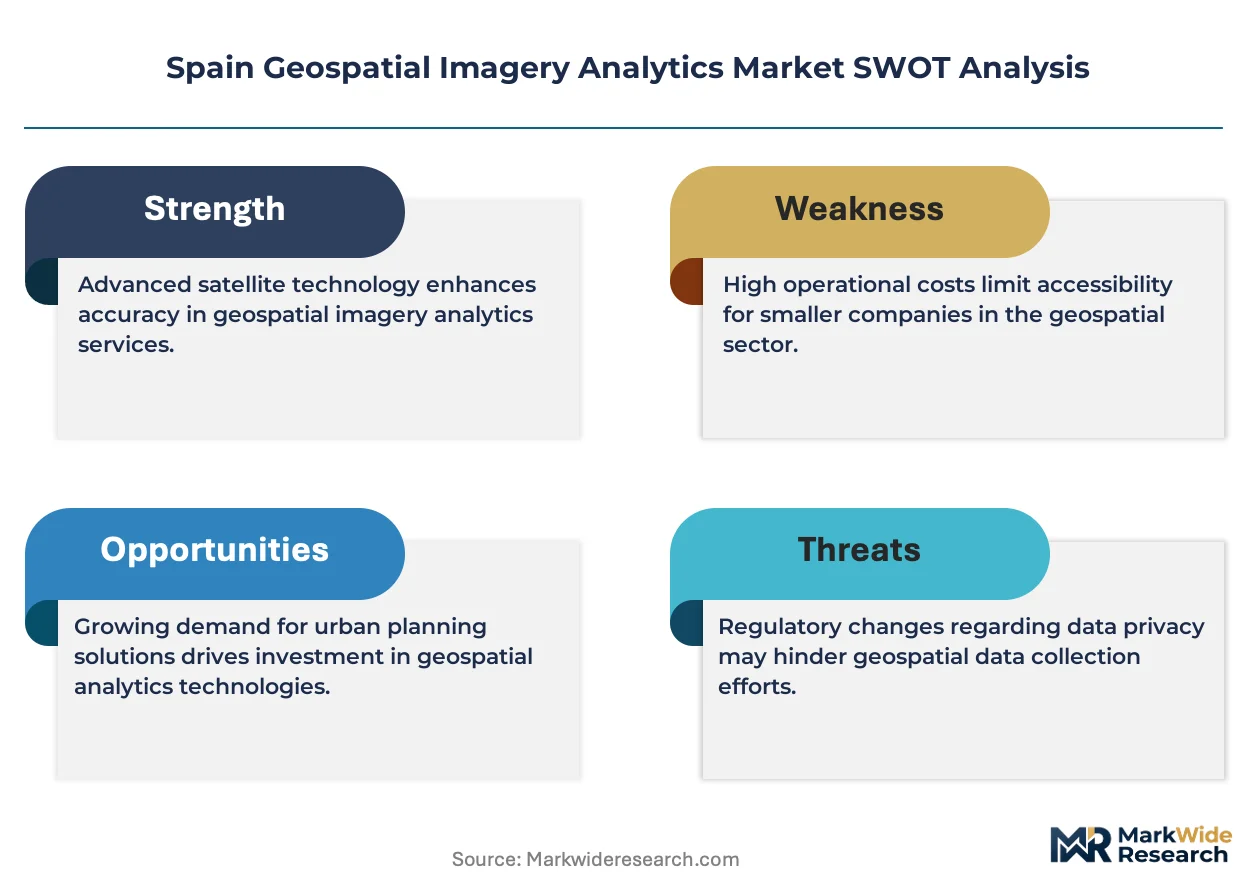
The gap between premium analytics platforms and commodity imagery feeds is repositioning competitive dynamics in Spain. Esri España leverages its ArcGIS ecosystem to dominate government and enterprise accounts with deep vertical workflows. Carto S.L. competes through cloud-native spatial data infrastructure tailored for real-time analytics. Indra Sistemas S.A. anchors defense and critical infrastructure segments with sovereign security clearances and satellite ground segment expertise.
Geospatial imagery analytics encompasses the extraction of actionable intelligence from Earth observation data through machine learning, spectral analysis, and geographic information system processing, typically operating across spatial resolutions from sub-meter to 30-meter pixels and temporal cadences from daily to seasonal revisits. Its primary commercial purpose centers on transforming raw satellite, aerial, and drone-captured imagery into decision-ready layers for asset tracking, risk assessment, and resource optimization. Environmental Monitoring and Disaster Response applications lead current deployment volumes given Spain's exposure to wildfire, drought, and flood events, while Agriculture Management represents the fastest-expanding margin pool as hyperspectral and SAR technology costs decline. The LiDAR segment occupies a specialized niche in precision terrain modeling for infrastructure engineering, though Optical Imaging still captures the majority of commercial transaction value.
Spain's national space strategy aligns with ESA funding frameworks and EU Green Deal monitoring obligations, creating compliance-driven demand for standardized Earth observation outputs across member state reporting protocols. CDTI, Spain's national aerospace technology institute, channels public procurement toward domestic platform developers, while GDPR constraints shape how location-analytics providers handle personal geodata in consumer-facing applications. Stakeholders must weigh sovereign data residency requirements against the cost advantages of pan-European cloud processing architectures as Copernicus data volumes scale.
Market Dynamics
The European Space Agency's Copernicus program is flooding Spain with free, high-resolution Earth observation data, compressing margins for raw imagery resellers while forcing analytics providers to differentiate through proprietary algorithm layers and vertical-specific workflow automation.
Growth Catalysts
- EU Green Deal monitoring obligations:Spain's agricultural cooperatives in Andalusia must submit standardized environmental compliance reports, creating recurring demand for automated land-use classification tools.
- Hyperspectral sensor cost declines:Vineyard operators in La Rioja now deploy drone-mounted hyperspectral cameras for early-stage pest detection, expanding the addressable market beyond satellite-dependent large farms.
- CDTI procurement preferences:Spain's national aerospace technology institute channels public contracts toward domestic platform developers, insulating local vendors from pan-European competition.
Market Restraints
- GDPR geodata constraints:Location-analytics providers face strict personal data handling rules that increase compliance overhead for consumer-facing applications.
- SAR processing talent scarcity:Synthetic aperture radar expertise concentrates among defense contractors, limiting commercial sector expansion.
- Copernicus dependency risk:Free ESA data access discourages private constellation investment, creating vulnerability if program funding shifts.
Strategic Opportunities
- Extremadura irrigation modernization:Spain's least digitized agricultural region presents white space for precision water management platforms.
- AI-SAR fusion:Machine learning integration with all-weather radar imagery enables flood prediction services for insurance underwriters.
- CSRD disclosure mandates:Corporate sustainability reporting requirements will force listed firms to purchase land-use change monitoring for Scope 3 emissions verification.
Industry Challenges
- Cloud-to-edge migration complexity:Agricultural drone operators struggle to deploy real-time analytics on low-bandwidth rural networks without expensive hardware retrofits.
- Copernicus data standardization lags:Inconsistent metadata formats across Sentinel missions force vendors to maintain costly preprocessing pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Geospatial Imagery Analytics Market |
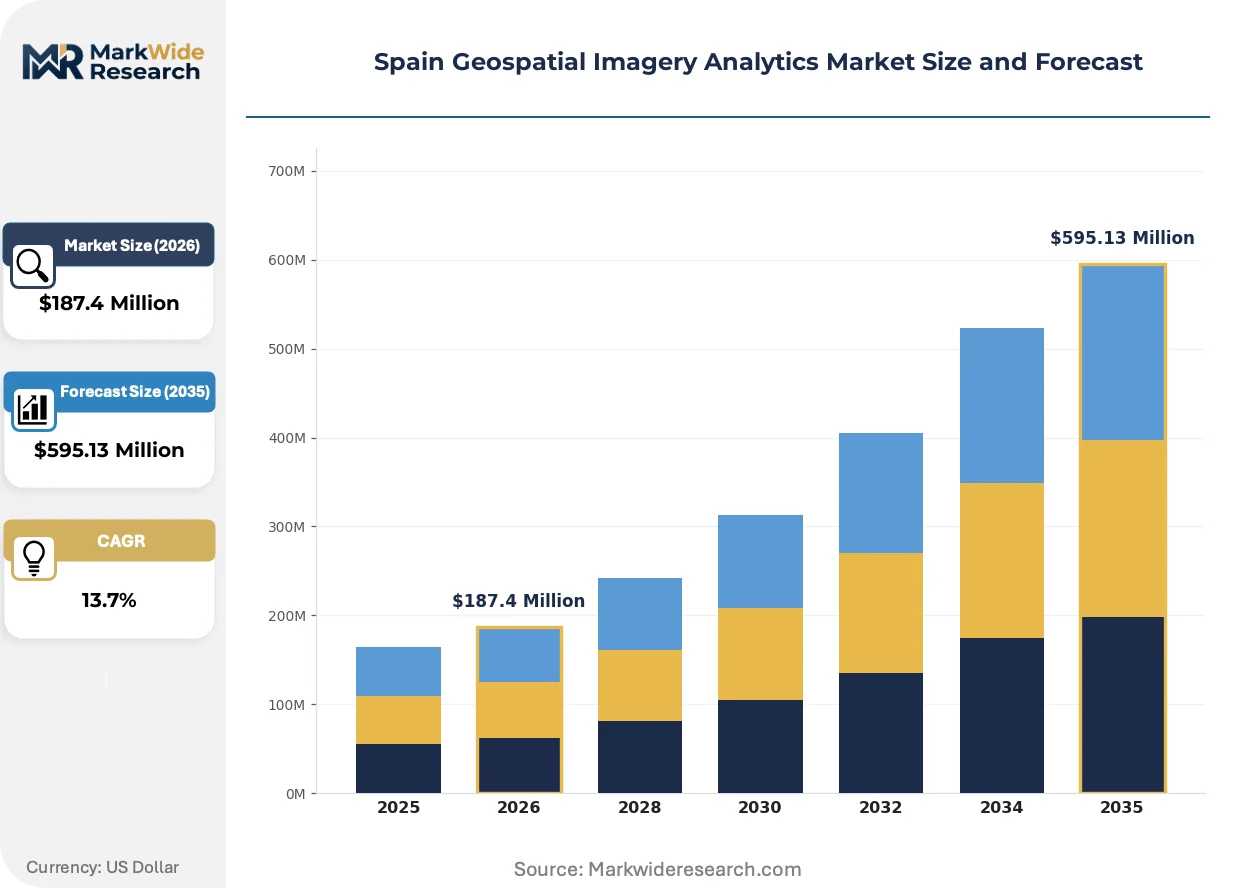
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $595.13 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Disaster Response, Environmental Monitoring, Agriculture Management Technology: SAR, Optical Imaging, LiDAR, Hyperspectral Imaging End User: Government Agencies, Research Institutions, Agriculture Firms, Energy Companies Service Type: Data Acquisition, Analytics Solutions, Consulting Services, Training & Support |
| Companies Covered | Carto S.L., Sitep Spatial Technologies, Esri España, Geoblink, Geographica, Indra Sistemas S.A., GMV Innovating Solutions, Deimos Space S.L.U., Telefónica Tech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Geospatial Imagery Analytics Market Trends and Innovations
Spanish geospatial providers are racing to embed artificial intelligence directly into data ingestion workflows, transforming raw satellite feeds into decision-ready agricultural and infrastructure intelligence without human annotation bottlenecks.
Synthetic aperture radar technology is integrating with cloud-native processing architectures to deliver all-weather crop monitoring. Large olive cooperatives in Jaén province are adopting these platforms to track soil moisture through winter cloud cover. The convergence is compressing the competitive window for optical-only analytics providers who cannot guarantee year-round service continuity.
CSRD disclosure rules are mandating granular land-use emissions tracking for listed Spanish corporations. Food processors and construction material suppliers must now document supply chain deforestation exposure, driving procurement of automated change-detection subscriptions. The regulatory pressure is most acute among Madrid-headquartered multinationals with Latin American sourcing operations.
Subscription-based platform access is displacing perpetual license sales across municipal government accounts. Provincial environmental agencies in Catalonia and Galicia prefer operational expenditure models that bundle software, data, and training. The shift favors vendors with robust customer success functions over traditional GIS software houses.
Spain Geospatial Imagery Analytics Market Segmentation
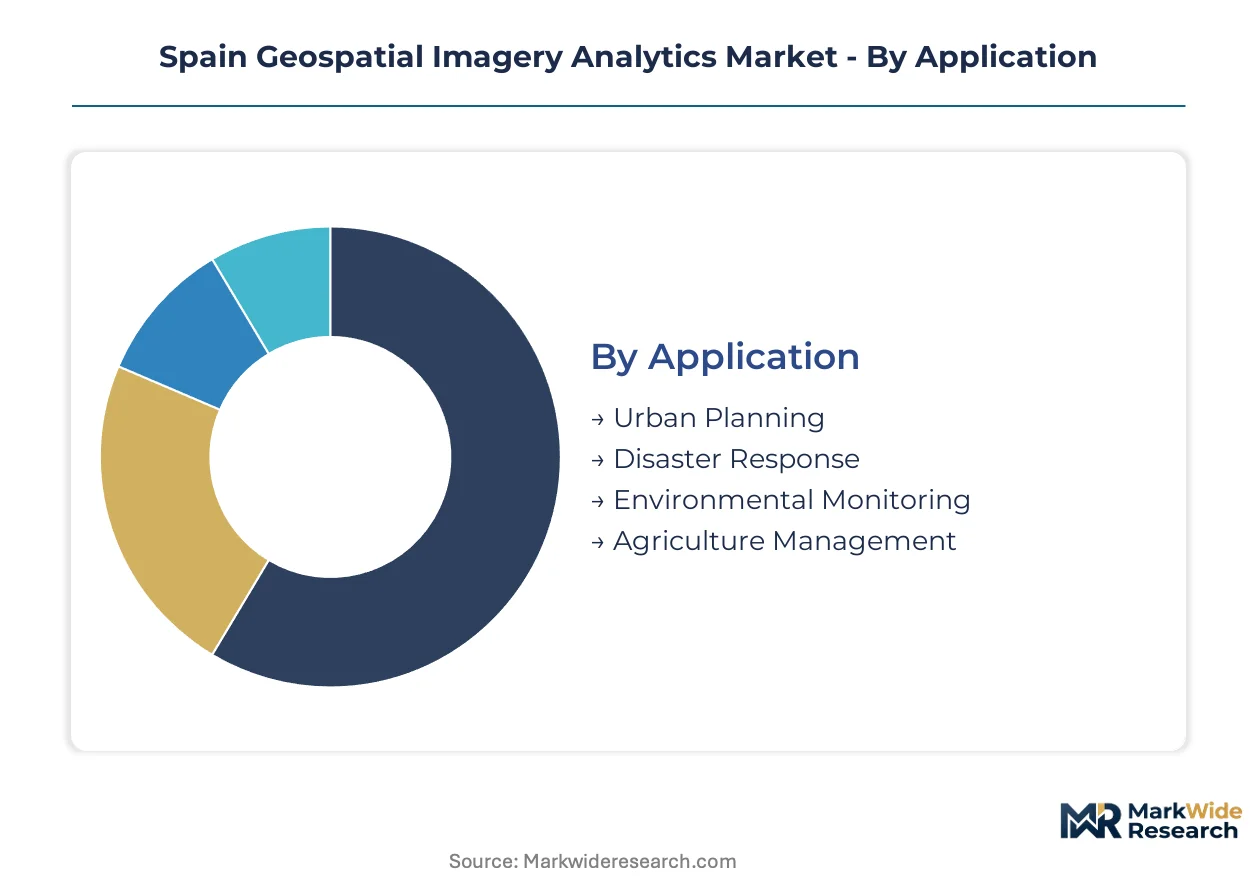
Spain's geospatial imagery analytics market fragments across four distinct category axes, each reflecting divergent procurement patterns between standardized government frameworks and customized enterprise deployments. Understanding these segment boundaries clarifies where platform vendors must choose between volume scalability and margin protection.
Application:
Standardized compliance reporting tools dominate government procurement, while agriculture and urban planning segments demand bespoke algorithm development for site-specific conditions.
- Agriculture Management:Precision farming platforms process multispectral and SAR feeds to monitor soil moisture, pest pressure, and irrigation efficiency. Andalusian olive cooperatives and La Rioja vineyard operators drive procurement as EU Green Deal reporting obligations harden. Hyperspectral drone deployments are climbing fastest among medium-sized farms seeking to bypass satellite dependency.
- Environmental Monitoring:Automated land-use classification and deforestation tracking systems serve CDTI-funded watershed management programs and corporate CSRD disclosure mandates. Catalonia's provincial environmental agencies represent the densest government cluster, while Madrid-headquartered multinationals with Latin American supply chains generate premium analytics demand for Scope 3 emissions verification.
- Disaster Response:Wildfire perimeter mapping and flood prediction services leverage near-real-time SAR processing for emergency coordination.
- Urban Planning:3D city modeling and infrastructure change detection support municipal zoning and construction permitting workflows.
Leading the category by volume: Environmental Monitoring. Growing fastest: Agriculture Management.
Technology:
Cost structures diverge sharply between mature optical stacks and emerging sensor modalities requiring specialized processing infrastructure.
- Optical Imaging:Visible and near-infrared spectrum platforms capture the majority of commercial transaction value through Copernicus Sentinel-2 integration. Standardized preprocessing pipelines and abundant analyst talent compress deployment costs for municipal and agricultural accounts. Cloud cover limitations constrain service continuity in northern Spain's Atlantic climate zones.
- SAR:Synthetic aperture radar penetrates cloud cover and darkness to deliver all-weather soil moisture and surface deformation monitoring. Jaén province olive cooperatives adopted SAR-first platforms after winter optical outages disrupted harvest timing decisions. Commercial sector expansion remains talent-constrained as SAR expertise concentrates among defense contractors.
- LiDAR:Laser-based terrain modeling supports precision engineering applications with centimeter-scale elevation accuracy.
- Hyperspectral Imaging:Narrow-band spectral analysis enables early-stage crop stress detection and mineral identification.
Optical Imaging commands the largest installed base. SAR is expanding most quickly as agricultural users prioritize reliability over spectral richness.
End User:
Procurement sophistication varies from CDTI-directed public tenders to research-driven experimental deployments with extended evaluation cycles.
- Government Agencies:National and provincial environmental, defense, and infrastructure authorities procure through CDTI-preferred vendor frameworks with sovereign data residency requirements. Madrid's government analytics cluster concentrates demand for cross-departmental spatial data infrastructure.
- Agriculture Firms:Cooperatives and large estate operators in Andalusia, La Rioja, and Extremadura purchase subscription-based crop monitoring with bundled agronomic advisory.
- Research Institutions:Universities and ESA collaborating centers access Copernicus data streams for climate and ecosystem modeling.
- Energy Companies:Solar and wind developers plus grid operators utilize terrain and land-use analytics for site selection and environmental impact assessment.
Government Agencies anchor procurement volume. Agriculture Firms are gaining share fastest as precision farming adoption broadens beyond early adopters.
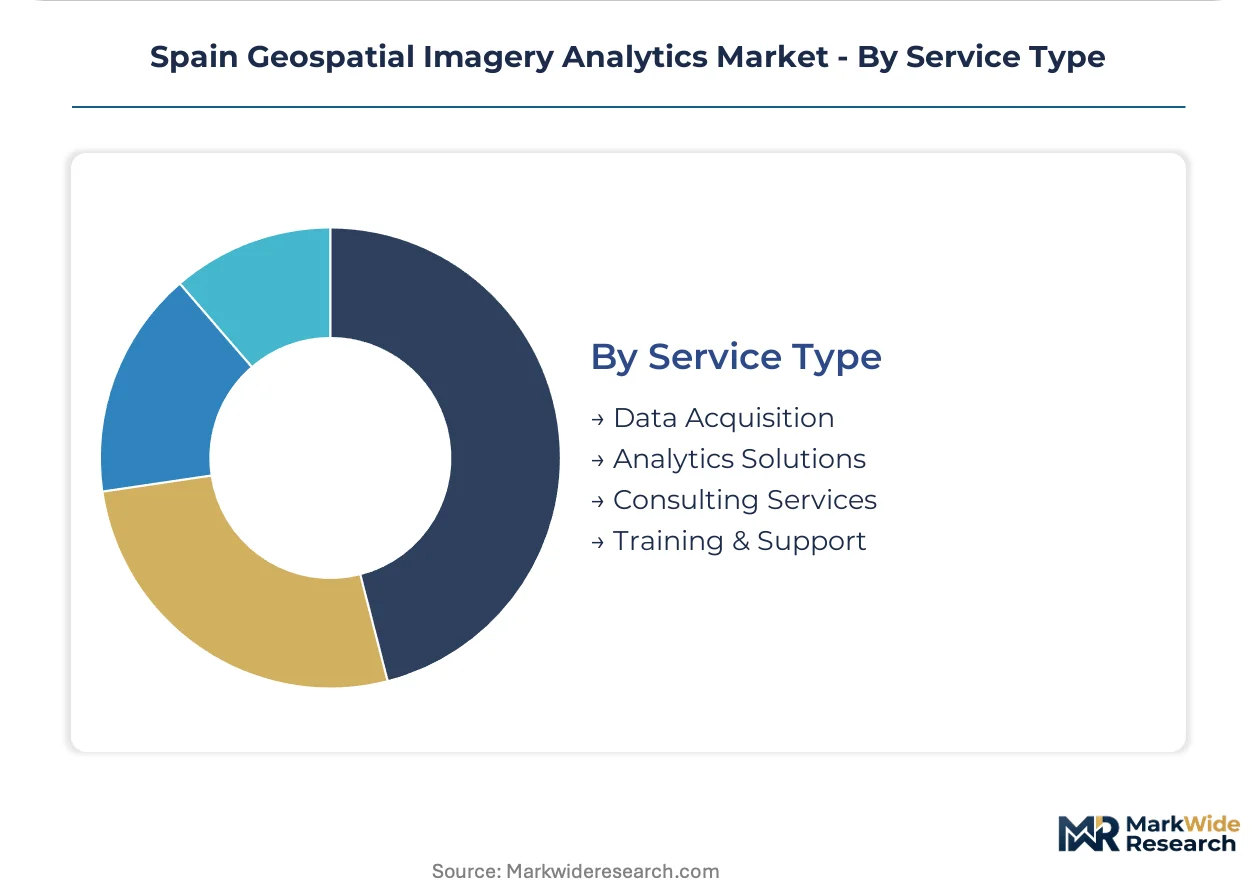
Service Type:
Revenue models are shifting from perpetual licenses toward recurring subscriptions that bundle data access with platform maintenance and user training.
- Analytics Solutions:Cloud-native platforms with embedded machine learning workflows transform raw imagery into decision-ready agricultural and infrastructure intelligence. Catalan and Galician provincial agencies prefer operational expenditure models combining software, data feeds, and customer success functions over traditional GIS license purchases.
- Data Acquisition:Satellite tasking, aerial survey coordination, and drone fleet management services for organizations lacking in-house collection infrastructure.
- Consulting Services:Custom algorithm development and vertical-specific workflow design for complex integration requirements.
- Training & Support:User certification programs and technical assistance for platform adoption and maintenance.
Analytics Solutions generate the dominant revenue stream. Training & Support shows the steepest expansion trajectory as subscription models embed ongoing enablement obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madrid's government analytics cluster concentrates Spain's geospatial procurement, with CDTI directing sovereign data contracts toward domestic platform developers. The capital's cross-departmental spatial data infrastructure anchors national environmental compliance and defense intelligence workflows.
Andalusia
Olive cooperatives in Jaén province drive SAR platform adoption for year-round soil moisture tracking through winter cloud cover. EU Green Deal reporting obligations harden procurement standards for automated land-use classification tools. The precision farming corridor linking Seville to Córdoba generates recurring subscription demand for bundled agronomic advisory services.
Catalonia
Provincial environmental agencies in Barcelona prefer operational expenditure models combining cloud-native platforms with customer success functions. CSRD disclosure mandates force listed firms with Latin American supply chains to document deforestation exposure through automated change-detection subscriptions. The regional cluster specializes in watershed management programs funded through CDTI frameworks.
Basque Country
Industrial engineering groups in Bilbao deploy LiDAR terrain modeling for precision infrastructure projects requiring centimeter-scale elevation accuracy. The region's aerospace technology institutes collaborate with ESA on Copernicus data preprocessing standardization. San Sebastián-based research centers concentrate SAR expertise transferred from defense contractor talent pools.
Valencia
Citrus farming operations in the autonomous community trial hyperspectral drone deployments for early-stage pest detection bypassing satellite dependency. Municipal zoning authorities adopt 3D city modeling for construction permitting workflows. The port logistics cluster experiments with real-time asset tracking across low-bandwidth rural network conditions.
Spain Geospatial Imagery Analytics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across algorithm differentiation and vertical workflow depth. Esri España leverages its ArcGIS ecosystem to dominate government accounts with deep sovereign security clearances. Carto S.L. competes through cloud-native spatial data infrastructure. Indra Sistemas S.A. anchors defense segments with satellite ground segment expertise. Strategic moves concentrate on proprietary algorithm layers and AI-SAR fusion capabilities.
Within the domestic platform developer tier, Esri España, Carto S.L., and Indra Sistemas S.A. represent the three archetypal competitive positions. Esri España exemplifies the incumbent ecosystem play with entrenched government relationships. Carto S.L. occupies the cloud-native challenger position targeting real-time analytics workloads. Indra Sistemas S.A. anchors the sovereign security tier where defense clearances create procurement barriers. These three Spanish entities sit within a vendor landscape shaped by CDTI procurement preferences and GDPR geodata constraints.
| Leading Market Players |
|---|
| Carto S.L. |
| Sitep Spatial Technologies |
| Esri España |
| Geoblink |
| Geographica |
| Indra Sistemas S.A. |
| GMV Innovating Solutions |
| Deimos Space S.L.U. |
| Telefónica Tech |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed platform developers anchored by CDTI procurement preferences exert pricing discipline through algorithm differentiation and vertical workflow depth rather than commodity imagery resale. Their ownership structure insulates domestic vendors from pan-European price competition while concentrating margin capture in proprietary processing layers.
Pricing Analysis
Value-based pricing tied to yield outcomes dominates agriculture subscriptions, with olive cooperatives in Jaén paying premiums for SAR-based soil moisture guarantees through winter cloud cover. Three-tier pricing structure across premium algorithm bundles, standard platform access, and economy data feeds separates Esri España's government accounts from Carto S.L.'s cloud-native tiers. Pricing pressure stems from Copernicus flooding Spain with free Sentinel-2 imagery, compressing raw data margins. Municipal environmental agencies show highest price sensitivity, while defense contractors with Indra Sistemas S.A. tolerate premium positioning for sovereign security clearances.
Supply Chain Analysis
Regional distribution centers in Madrid and Barcelona aggregate Copernicus data streams before downstream algorithm processing, creating hub-and-spoke patterns for cloud-native platform delivery. Upstream hardware dependence draws from Germany, France, and the Netherlands for hyperspectral sensor components and SAR processing chipsets. Raw material inputs include gallium arsenide semiconductors, precision optics, and specialized cooling systems. Single-source vulnerability concentrates in ESA ground segment infrastructure. Distribution runs through CDTI-preferred vendor frameworks channeling public contracts toward domestic developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where proprietary algorithm layers and AI-SAR fusion capabilities determine margin capture. Players are pursuing downstream control over customer success functions to lock in subscription renewals.
For Market Incumbents: Lock in government accounts by deepening ArcGIS ecosystem integration with CDTI procurement frameworks before Carto S.L.'s cloud-native challenge scales. Acquire SAR processing talent from Basque Country defense contractors to close the all-weather analytics gap. Prioritize algorithm differentiation over raw imagery volume as Copernicus data floods commoditize basic feeds.
For New Entrants and Emerging Players: The price-point gap between premium sovereign-security platforms and economy Copernicus-derived tools creates white space for mid-tier precision farming bundles. Target Extremadura's irrigation modernization as Spain's least digitized agricultural region with bundled water management subscriptions. Pursue hyperspectral drone partnerships with La Rioja vineyard operators seeking satellite bypass for pest detection.
For Investors and Strategic Acquirers: CSRD disclosure mandate enforcement is the leading indicator that land-use change monitoring demand will accelerate among Madrid-headquartered multinationals. Over the medium-term horizon, vertically integrated specialists combining SAR expertise with agricultural domain knowledge present optimal acquisition profiles. Watch for CDTI funding allocation shifts signaling sovereign data residency priority elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-SAR Fusion Platform Development | Machine learning integration with radar imagery enables flood prediction services for insurance underwriters in Catalonia. |
| Hyperspectral Drone Fleet Expansion | La Rioja vineyard operators deploy narrow-band spectral cameras for early-stage pest detection bypassing satellite dependency. |
| CDTI Procurement Framework Capture | Domestic platform developers secure sovereign data contracts insulating against pan-European cloud provider competition. |
| Customer Success Function Buildout | Catalan provincial agencies prefer operational expenditure models bundling software, data feeds, and ongoing training. |
| CSRD Compliance Tool Launch | Corporate sustainability reporting mandates force listed firms to purchase automated land-use change monitoring subscriptions. |
Research Methodology
Multi-period observation of Copernicus data utilization rates, CDTI procurement award patterns, and SAR platform adoption curves anchored the trend analysis, supplemented by interviews with platform engineering directors at domestic analytics providers, agronomic advisors at Andalusian olive cooperatives, environmental compliance officers at Madrid-headquartered multinationals, and procurement leads within CDTI-preferred vendor frameworks. Secondary validation drew from ESA program documentation, EU Green Deal implementation reports, CSRD regulatory filings, and provincial environmental agency budget disclosures. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-weighting across application categories, technology modalities, end-user archetypes, and service type revenue models structured the analytical framework. Deployment intensity indices for precision farming platforms, government analytics procurement cycles, and hyperspectral sensor cost curves fed into growth trajectory modeling. CAGRs were derived from fitted trend lines applied to normalized adoption curves across the projection horizon.
Inputs from ESA collaborating centers and CDTI funding databases were available through the study window; gaps in real-time SAR processing talent pool sizing and proprietary algorithm performance benchmarking introduce uncertainty bands around agricultural automation forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global in-Memory Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Face Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Europe Big Data and Business Analytics Market
Analytics
Identity Analytics Market
Analytics
Global Healthcare Cloud Based Analytics Market
Analytics
Practice Analytics Market
Analytics
Data Preparation Market
Analytics
Greece ICT Market
Analytics
United States Geospatial Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
AI Performance Marketing Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Multi-Touch Attribution Market
Analytics
Global Data Analysis Software Market