
 Global Precision Gearboxes Market | 2026-2036
Global Precision Gearboxes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precision Gearboxes Market Outlook
A widening capital-intensity gap between in-house gear grinding capability and outsourced assembly is rotating competitive advantage toward vertically integrated manufacturers. SEW-EURODRIVE leverages its captive gear-cutting capacity to sustain margin control across servo-integrated planetary lines. Nabtesco Corporation anchors the harmonic drive segment through proprietary flexspline metallurgy and Japanese precision machining expertise. WITTENSTEIN SE differentiates via compact coaxial designs that dominate European medical and semiconductor automation.
Precision gearboxes transmit torque with backlash below one arc-minute through hardened alloy-steel gearsets and preloaded bearing arrangements, enabling sub-micron positioning in servo-driven motion systems. Planetary gear configurations occupy the largest share of industrial volume due to their torque density and coaxial packaging advantage in machine tool axes and automated guided vehicles. Harmonic drives lead growth trajectory in robotics applications where zero-backlash strain-wave gearing enables repeatable articulated joint movement; electric actuation technology dominates new design-ins as servo motor integration displaces hydraulic alternatives in clean-environment automation.
CE marking under the EU Machinery Directive and the EU AI Act's risk-classification framework for autonomous systems are tightening accuracy-validation requirements for gearbox suppliers serving European robotics OEMs. Japan's METI enforces JIS B 1702 precision standards that constrain import eligibility for non-domestic harmonic drive manufacturers. China's SAMR administers GB standards for robotic reducer testing that shape procurement qualification for domestic automation integrators. Stakeholders must monitor regulatory divergence between European functional-safety mandates and Asian performance-certification regimes when allocating R&D and localization investments.
Market Dynamics
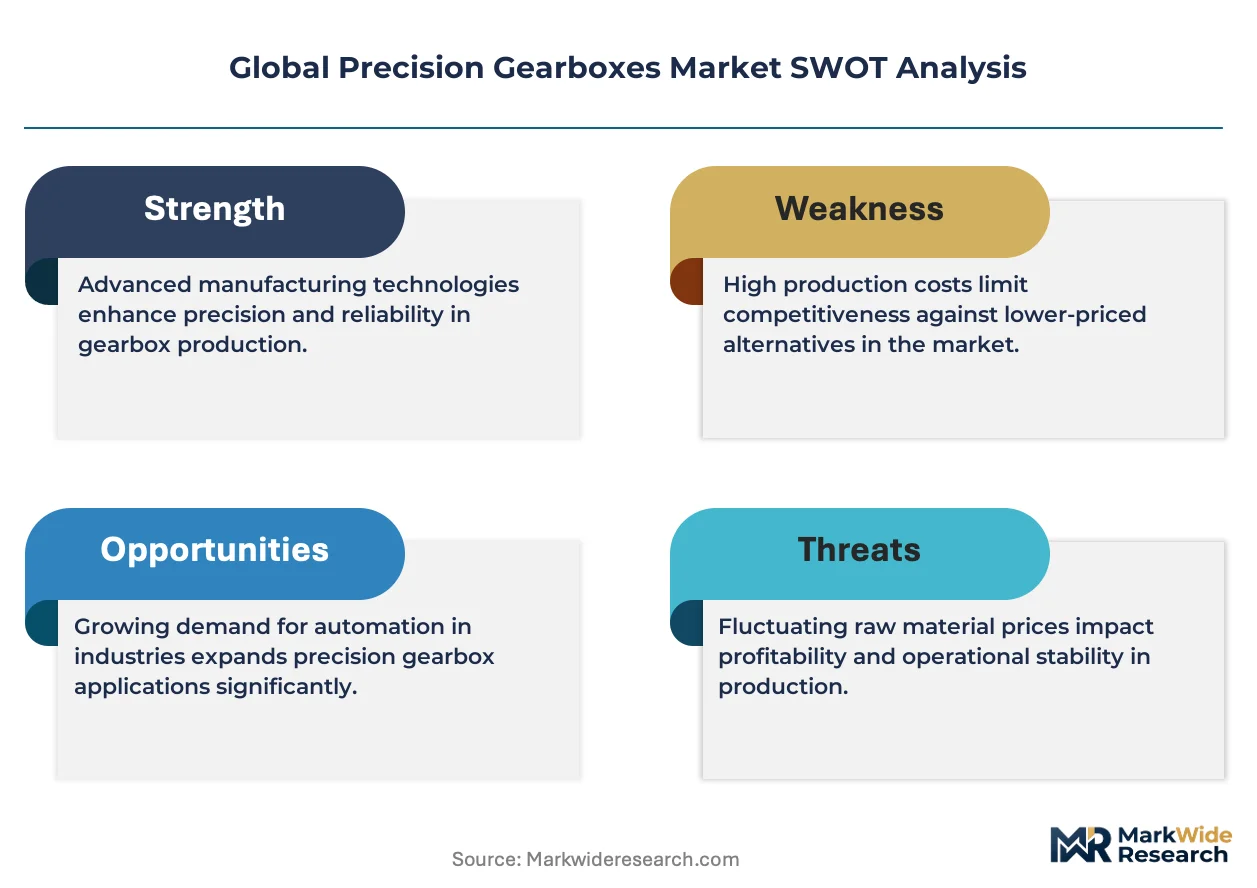
Electric actuation is displacing hydraulic power transmission in clean-environment automation, forcing precision gearbox suppliers to redesign for servo motor integration and sub-arc-minute backlash specifications.
Growth Catalysts
- EU AI Act risk classification:Autonomous robotics OEMs in Germany and France now require certified positional accuracy documentation for collaborative robot joints, expanding qualified supplier pools.
- Strain-wave gearing:Zero-backlash harmonic drive architectures enable repeatable articulated movement in six-axis industrial robots deployed across China's Yangtze River Delta automation cluster.
- Machine tool axis modernization:Japanese and German builders are retrofitting servo-integrated planetary lines to achieve sub-micron positioning in semiconductor wafer handling equipment.
Market Restraints
- Alloy-steel input volatility:Hardened gearset production depends on specialized vacuum carburizing steels concentrated among Japanese and German metallurgical suppliers.
- Harmonic drive supply concentration:Proprietary flexspline manufacturing expertise resides with a narrow base of Japanese precision machining houses.
- CE marking validation costs:EU Machinery Directive compliance requires third-party positional accuracy certification that extends qualification timelines for non-European entrants.
Strategic Opportunities
- Indian automation integration:Domestic machine tool builders under BIS standards adoption are localizing precision reducer procurement away from import-dependent supply chains.
- Medical device actuation:Compact coaxial gearbox designs are penetrating surgical robot joint applications where cleanroom compatibility and torque density converge.
- Semiconductor capital equipment:Wafer handling and lithography positioning stages demand backlash specifications below one arc-minute that strain-wave and planetary architectures can address.
Industry Challenges
- Gear grinding skill scarcity:Captive precision machining capability requires master-class machine operators trained in continuous generating grinding and profile dressing techniques.
- Servo integration complexity:Preloaded bearing arrangements and thermal compensation algorithms must align with third-party motor encoder feedback systems in multi-axis coordinated motion.
- JIS B 1702 certification timelines:Japanese precision standards constrain import eligibility for harmonic drive manufacturers seeking access to METI-regulated robotics supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precision Gearboxes Market |
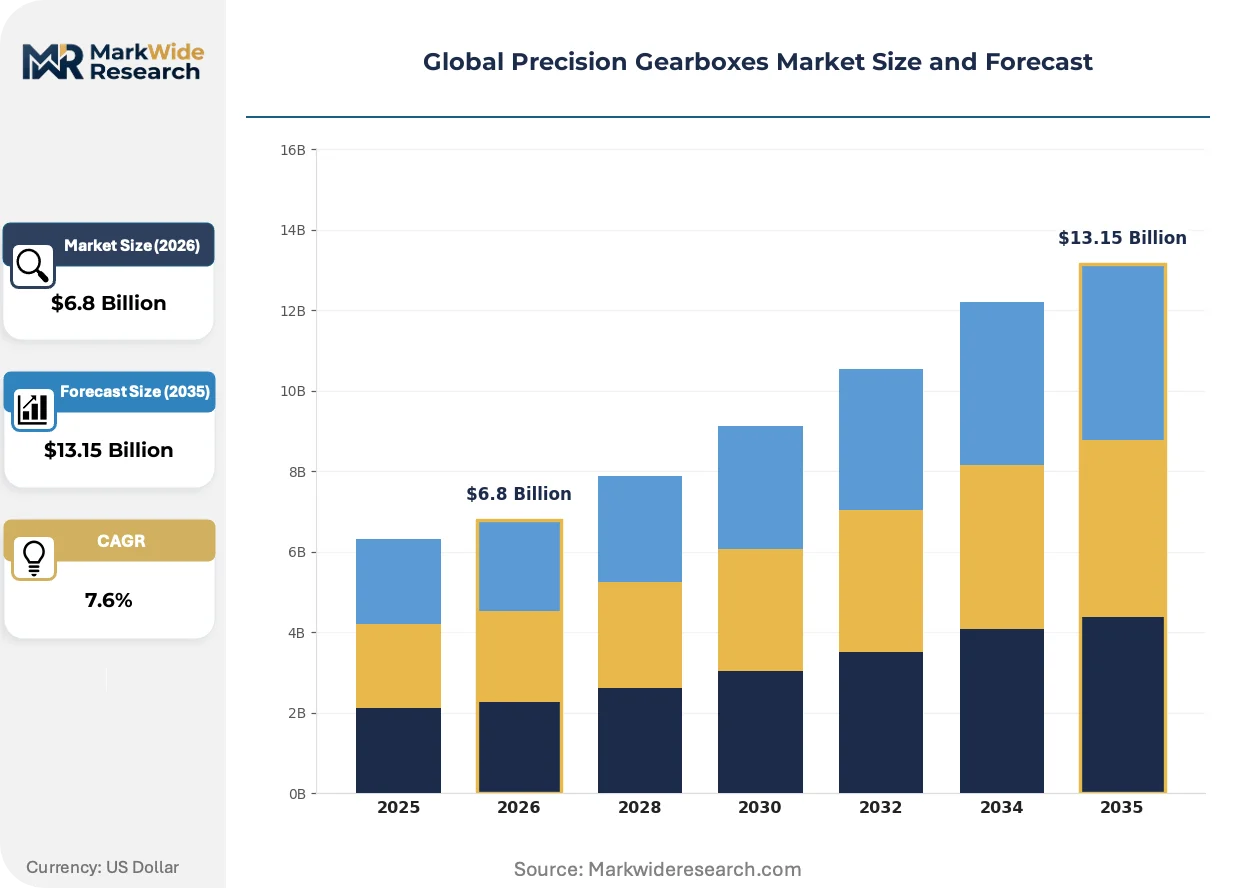
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harmonic Drive, Planetary Gear, Spur Gear, Bevel Gear End User: Aerospace, Robotics, Automotive, Industrial Machinery Application: Motion Control, Robotics Applications, Automation, Machine Tools Technology: Electric Actuation, Mechanical Actuation, Hydraulic Actuation, Pneumatic Actuation |
| Companies Covered | SEW-EURODRIVE, Neugart GmbH, WITTENSTEIN SE, Harmonic Drive LLC, Bonfiglioli Riduttori, Siemens, Nabtesco Corporation, Sumitomo Drive Technologies, NIDEC-SHIMPO CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precision Gearboxes Market Strategic Shifts
Precision gearbox architecture is splitting along performance-tier lines as clean-environment automation demands diverge from heavy-industrial torque transmission requirements.
Integrated servo-gearbox units combining planetary reduction with hollow-shaft motor mounting is bifurcating the competitive landscape. Medical device manufacturers and semiconductor OEMs are specifying these compact coaxial packages for cleanroom-compatible motion axes. The technology is compressing traditional multi-vendor assembly chains into single-source qualified supply relationships.
CE marking under the EU Machinery Directive now mandates functional safety validation for gearboxes deployed in autonomous collaborative robots. German and French certification bodies are enforcing ISO 13849-1 performance level documentation that extends engineering validation cycles. European medical and logistics robotics OEMs are responding by consolidating supplier qualification around vertically integrated manufacturers with captive testing laboratories.
Buyer specifications now unbundle after-sales service from hardware procurement in high-volume machine tool applications. Chinese automation integrators in the Yangtze River Delta are contracting directly with regional service depots for preventive maintenance, bypassing traditional manufacturer-direct service agreements. This channel fragmentation is most visible among domestic machine tool builders sourcing localized precision reducers under SAMR-administered GB standards.
Global Precision Gearboxes Market Segmentation
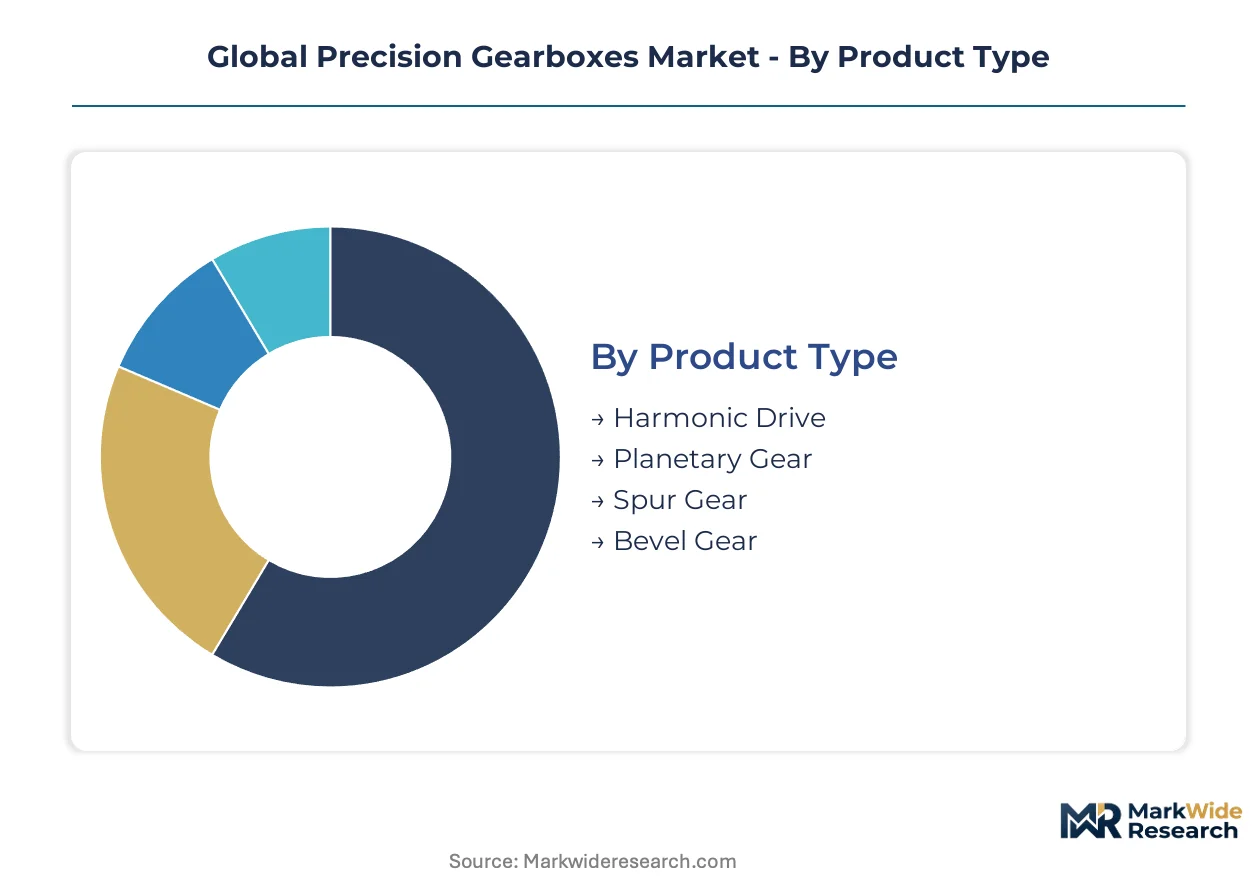
Precision gearbox segmentation reflects divergent regulatory requirements across application environments. Product architecture and actuation technology choices determine compliance pathways under EU machinery safety directives and Asian precision standards.
Product Type:
Regulatory differentiation in precision standards shapes competitive positioning across gearbox architectures. EU CE marking and Japanese JIS B 1702 certification impose distinct validation requirements on strain-wave versus planetary configurations.
- Harmonic Drive:Zero-backlash strain-wave gearing employs elliptical wave generators and flexsplines to achieve sub-arc-minute positioning repeatability. Robotics OEMs in Japan's METI-regulated supply chains source these for six-axis collaborative robot joints, constrained by proprietary flexspline metallurgy concentrated among domestic precision machining houses.
- Planetary Gear:Coaxial multi-stage reduction systems with hardened alloy-steel sun gears and planet carriers deliver torque density above 3 Nm/kg. German and Chinese machine tool builders in the Yangtze River Delta automation cluster specify servo-integrated planetary lines for CNC axis modernization, driven by SAMR-administered GB standards for robotic reducer testing.
- Spur Gear:Parallel-shaft configurations with straight-cut tooth profiles serve cost-sensitive industrial automation where backlash tolerance exceeds five arc-minutes.
- Bevel Gear:Right-angle power transmission for constrained installation envelopes in material handling and packaging machinery.
Established volume favors Planetary Gear; emerging adoption favors Harmonic Drive.
End User:
Customer procurement patterns split between performance-certified aerospace specifications and price-sensitive automotive volume contracts.
- Robotics:Articulated joint actuation demands backlash below one arc-minute through preloaded bearing arrangements and thermal compensation algorithms. Collaborative robot manufacturers in Germany and France require ISO 13849-1 performance level documentation under EU AI Act risk classification, consolidating supplier qualification around vertically integrated manufacturers with captive testing laboratories.
- Industrial Machinery:Machine tool axis retrofitting and automated guided vehicle propulsion systems absorb standardized planetary reducers. Chinese automation integrators contract directly with regional service depots for preventive maintenance, bypassing traditional manufacturer-direct service agreements.
- Aerospace:Flight control surface actuation and landing gear systems require AS9100-certified traceability and extended environmental testing protocols.
- Automotive:Powertrain testing rigs and assembly line positioning equipment prioritize cost-optimized spur gear configurations over precision-tier alternatives.
Procurement concentration sits with Industrial Machinery; steepest expansion trajectory belongs to Robotics.
Application:
Functional safety validation intensity varies sharply between autonomous collaborative systems and conventional machine tool axes.
- Motion Control:Multi-axis coordinated positioning in semiconductor wafer handling equipment demands sub-micron repeatability through integrated servo-gearbox units combining hollow-shaft motor mounting with planetary reduction. Medical device manufacturers specify these compact coaxial packages for cleanroom-compatible surgical robot joints.
- Machine Tools:CNC axis modernization and retrofitting programs in Japan and Germany absorb standardized planetary configurations with documented positional accuracy certification.
- Robotics Applications:Six-axis articulated joint movement and SCARA arm positioning systems.
- Automation:Generalized material handling and packaging line actuation with moderate precision requirements.
Specification complexity peaks in Motion Control; volume scale concentrates in Machine Tools.
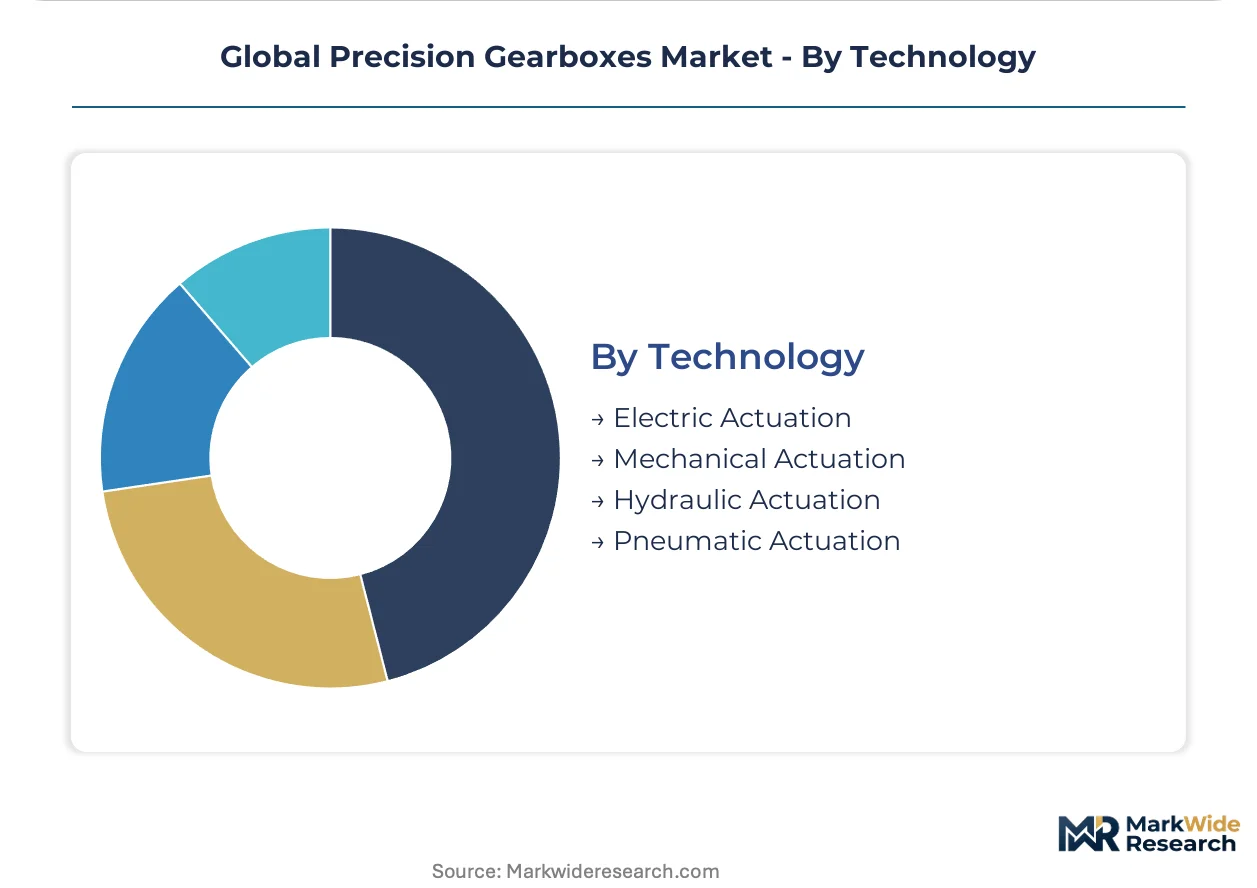
Technology:
Actuation modality selection determines cleanroom compatibility and energy efficiency compliance under regional environmental regulations.
- Electric Actuation:Servo motor integration with precision gearboxes displaces hydraulic alternatives in clean-environment automation, requiring redesigned preloaded bearing arrangements and thermal compensation algorithms aligned with third-party motor encoder feedback systems.
- Mechanical Actuation:Direct-coupled manual and cam-driven systems persist in legacy industrial equipment with minimal control system integration.
- Hydraulic Actuation:High-torque fluid power systems retain position in heavy-industrial forging and pressing applications where contamination tolerance permits.
- Pneumatic Actuation:Compressed-air systems serve low-precision positioning in food packaging and textile machinery with inherent cleanliness advantages.
Technology transition favors Electric Actuation; residual demand stabilizes Mechanical Actuation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across precision gearbox procurement. German and Japanese buyers prioritize certified positional accuracy and absorb premium pricing for JIS B 1702 and ISO 13849-1 compliance. Chinese automation integrators in the Yangtze River Delta drive volume through localized sourcing under SAMR-administered GB standards, squeezing margins on standardized planetary configurations.
Germany
Machine tool builders in Baden-Württemberg and Bavaria retrofit servo-integrated planetary lines for semiconductor wafer handling equipment. CE marking under the EU Machinery Directive and EU AI Act risk classification mandates ISO 13849-1 performance level documentation for collaborative robot joints. Stuttgart and Munich anchor demand for vertically integrated manufacturers with captive testing laboratories.
Japan
Six-axis industrial robot manufacturers source harmonic drives for articulated joint actuation requiring sub-arc-minute backlash. METI enforces JIS B 1702 precision standards that constrain import eligibility for non-domestic flexspline suppliers. Nagoya and Osaka precision machining houses concentrate proprietary metallurgy expertise for strain-wave gearing.
China
Domestic machine tool builders in the Yangtze River Delta automation cluster localize precision reducer procurement under SAMR GB standards for robotic reducer testing. Electric actuation displaces hydraulic alternatives in clean-environment automation across Shanghai and Suzhou manufacturing corridors. SAMR certification shapes qualification pathways for European and Japanese gearbox entrants.
United States
Medical device manufacturers specify compact coaxial gearbox designs for surgical robot joints requiring cleanroom compatibility. FDA device regulations intersect with ISO 13485 quality management for motion control subassemblies in minimally invasive surgical systems. Greater Boston and Minneapolis-St. Paul medical technology corridors concentrate demand for sub-micron positioning repeatability.
India
Domestic automation integrators under BIS standards adoption localize precision reducer procurement away from import-dependent supply chains. Machine tool builders in Maharashtra and Gujarat retrofit CNC axes with standardized planetary configurations. Pune and Ahmedabad industrial clusters drive backward integration into gear grinding capability for captive reducer production.
Global Precision Gearboxes Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in precision gearbox supply. Captive gear-cutting capacity and in-house flexspline metallurgy separate margin-sustainable manufacturers from assembly-dependent competitors. Three archetypes dominate: vertically integrated European servo-gearbox houses, Japanese precision machining specialists with proprietary strain-wave expertise, and Chinese domestic champions scaling under SAMR localization mandates. Competitive moves concentrate on backward integration into vacuum carburizing steel supply and captive testing laboratory accreditation for CE marking and JIS B 1702 certification.
Among German fabricators, SEW-EURODRIVE GmbH and Neugart GmbH exemplify the vertically integrated archetype with captive gear-cutting infrastructure. WITTENSTEIN SE occupies a position within the compact coaxial design specialization serving medical and semiconductor automation. Japanese specialists Nabtesco Corporation and Harmonic Drive LLC anchor the strain-wave gearing tier through precision machining expertise concentrated in domestic supply chains. These named entities represent competitive positioning patterns rather than specific strategic commitments or market share claims.
| Leading Market Players |
|---|
| SEW-EURODRIVE |
| Neugart GmbH |
| WITTENSTEIN SE |
| Harmonic Drive LLC |
| Bonfiglioli Riduttori |
| Siemens |
| Nabtesco Corporation |
| Sumitomo Drive Technologies |
| NIDEC-SHIMPO CORPORATION |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with Japanese and German metallurgical suppliers lock in vacuum carburizing steel access and freeze price visibility for harmonic drive manufacturers serving METI-regulated robotics supply chains. These contractual structures concentrate procurement power among vertically integrated gearbox houses while squeezing margin flexibility for assembly-dependent competitors in China's Yangtze River Delta.
Pricing Analysis
After-sales service contracts and preventive maintenance subscriptions drive lifetime value capture for precision gearbox manufacturers serving industrial machinery buyers. Three-tier pricing structure across premium, standard, and economy levels separates JIS B 1702-certified harmonic drives from CE-marked planetary lines and unbranded spur gear alternatives. Price differentiation hinges on certification grade and captive gear-cutting capability. Pricing pressure stems from Chinese automation integrators contracting directly with regional service depots, bypassing manufacturer-direct agreements. Machine tool builders in the Yangtze River Delta exhibit highest price sensitivity; medical device manufacturers in Greater Boston absorb premium positioning for cleanroom compatibility.
Supply Chain Analysis
Strategic stockpiling of specialized alloy-steel inputs dominates inventory strategy among Japanese precision machining houses, insulating flexspline production from metallurgical supply shocks. Manufacturing concentrates in Japan, Germany, and China. Raw material dependencies draw from vacuum carburizing steels, preloaded bearing assemblies, and servo motor encoder systems. Single-source vulnerability sits with proprietary flexspline metallurgy expertise concentrated in Nagoya and Osaka machining clusters. Distribution runs through OEM-direct channels for certified robotics applications and fragmented regional service depots for standardized machine tool retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision gearbox procurement is shifting toward integrated servo-gearbox platforms that compress multi-vendor assembly chains into single-source relationships, creating ecosystem lock-in effects around captive testing laboratories and certification documentation.
For Market Incumbents: Compound backward integration into vacuum carburizing steel supply and captive CE marking testing laboratories to defend margin sustainability against emerging Chinese domestic champions scaling under SAMR localization mandates. Prioritize JIS B 1702 certification maintenance for METI-regulated robotics supply chain access. For New Entrants and Emerging Players: Lead with medical device actuation applications in Greater Boston and Minneapolis-St. Paul corridors, where FDA device regulations and ISO 13485 quality requirements create qualification barriers that favor specialized compact coaxial designs over generalist planetary offerings. Target surgical robot joint specifications through direct OEM engineering partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with captive gear-cutting infrastructure and long-term service contracts in German machine tool and Japanese robotics supply chains. Five-to-ten year viability favors acquisition targets combining flexspline metallurgy expertise with CE marking testing accreditation. Watch for SAMR GB standards harmonization with EU machinery safety directives as inflection signal for Chinese market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Carburizing Steel | Captive metallurgy supply secures flexspline production capacity against Japanese and German input concentration. |
| CE Marking Testing Laboratory Accreditation | ISO 13849-1 performance level documentation enables qualified supplier status for EU AI Act-regulated collaborative robot OEMs. |
| Medical Device Actuation Partnership | FDA device regulation alignment with ISO 13485 opens surgical robot joint procurement in Greater Boston medical technology corridor. |
| Regional Service Depot Network Expansion | Direct contracting with Chinese automation integrators bypasses manufacturer-direct agreements fragmenting traditional channels. |
| Harmonic Drive Flexspline Metallurgy R&D | Proprietary strain-wave gearing expertise maintains zero-backlash positioning repeatability for six-axis articulated joint applications. |
Study Parameters
Cross-validation between primary interviews with robotics OEM procurement directors, machine tool builder engineering leads, and precision gearbox aftermarket service heads anchors the qualitative findings against secondary sources including METI JIS B 1702 certification records, SAMR GB standards documentation, and EU Machinery Directive CE marking registries. Bottom-up segmentation modeling triangulates with top-down trade flow analysis across Japanese, German, and Chinese customs data.
Sensitivity analysis on alloy-steel input cost trajectories and certification timeline variations shapes the analytical framework across the analysis window. Segmentation dimensions span product architecture, actuation technology, end-use industry, and regional regulatory cluster. CAGRs derive from installed base growth projections and replacement cycle dynamics in servo-integrated motion systems. Forecast inputs incorporate electric actuation displacement rates and collaborative robot joint density specifications.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement intensity or METI import eligibility continuity would require recalibration. Forecasts reflect documented assumptions on certification timeline standardization and metallurgical supply concentration persistence. Revision becomes warranted when SAMR GB standards harmonization with EU machinery safety directives crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Material Handling Equipment Telematics Market