
 Dump Tubs Market | 2026-2036
Dump Tubs Market Size, Share, and Industry Trends Forecast 2026-2036
Dump Tubs Market Analytics
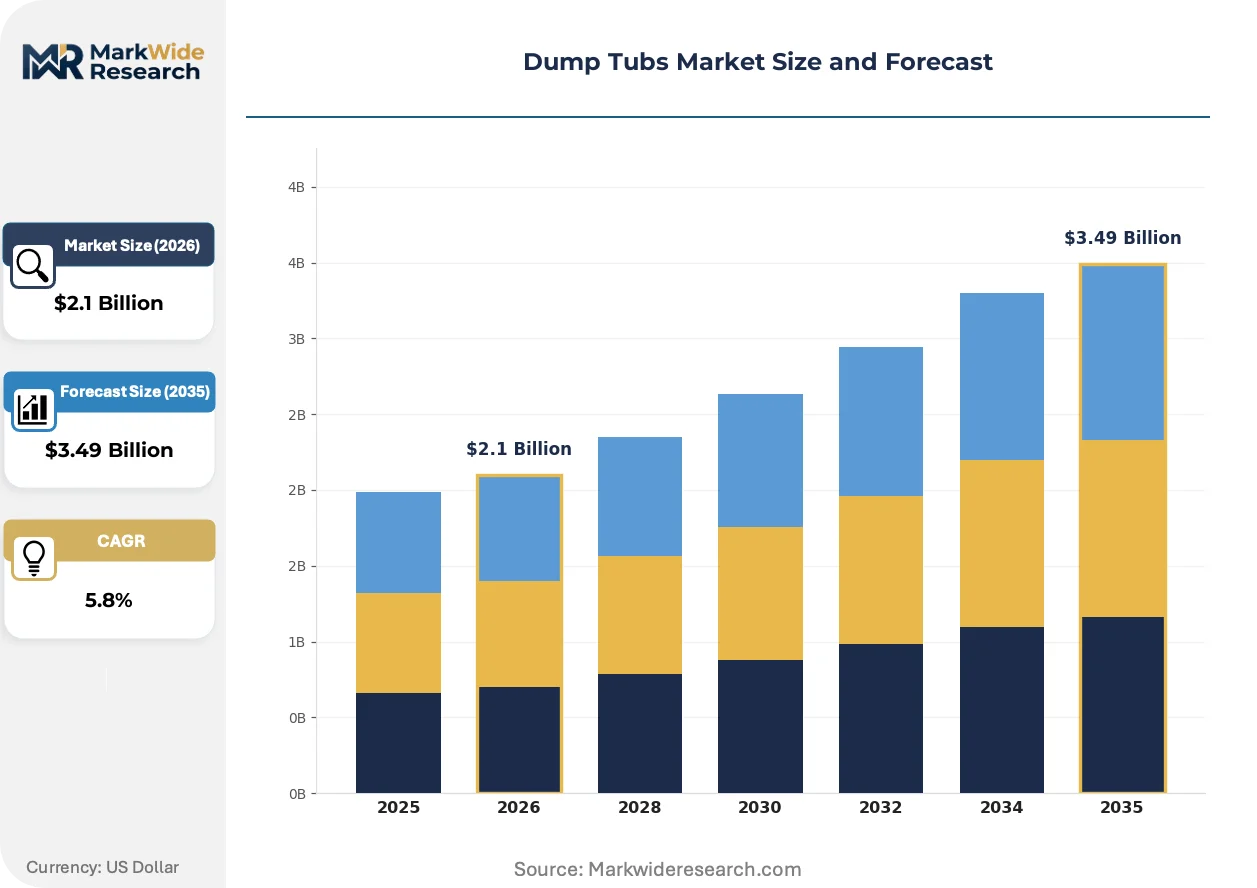
Subscription-based fleet maintenance programs is broadening revenue streams beyond unit sales for dump tub manufacturers. Schmitz Cargobull leverages its European service network to bundle predictive maintenance with trailer leases. Mac Trailer anchors its position through deep vertical integration into steel fabrication and custom coating operations. Kögel Trailers differentiates via modular tub configurations that adapt to agricultural and construction payloads without full fleet replacement.
Dump tubs are open-top containers mounted on trailer chassis or skid frames, typically fabricated from carbon steel, aluminum alloys, or high-density polyethylene, designed for bulk material transport in construction debris, agricultural harvest, and landscaping operations. Metal dump tubs retain dominance in heavy-duty commercial applications where abrasion resistance and load ratings exceed 15 tons, while plastic variants capture residential and light contractor segments where corrosion immunity and lower tare weight reduce fuel penalties. Medium capacity tubs lead volume shipments among contractors balancing maneuverability with payload efficiency, whereas extra large capacity units command premium positioning in mining and aggregate haulage where cycle time economics favor maximal single-trip volume.
The EPA enforces emissions and fuel economy standards for heavy-duty vehicles that indirectly shape dump tub specifications through weight reduction mandates, while OSHA governs worker safety in loading and tipping operations that influence hydraulic system design and operator guard requirements. ISO 9001 quality management certifications increasingly function as market access prerequisites for fleet procurement tenders across North American and European buyers. Stakeholders must monitor evolving material science breakthroughs in composite tub construction and assess whether captive maintenance networks or third-party service partnerships yield superior lifetime value capture.
Market Dynamics
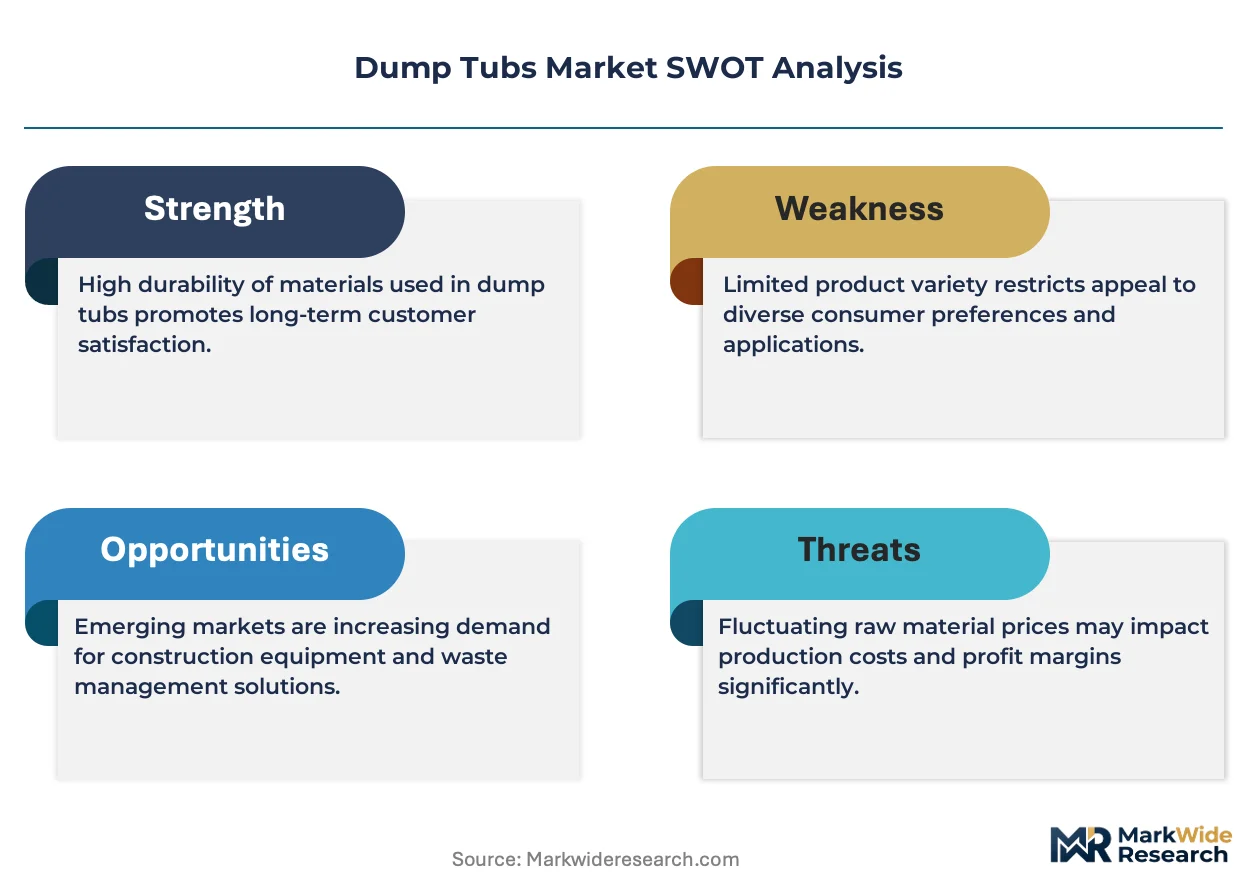
The EPA's emissions standards for heavy-duty trailers are compressing tare weight tolerances, forcing manufacturers toward aluminum alloy and composite formulations that preserve payload capacity while meeting fuel economy mandates. This regulatory pressure intersects with fleet operator demands for lower lifetime operating costs.
Growth Catalysts
- Construction sector fleet renewal:Medium-capacity metal tubs are capturing expanded orders from contractors balancing maneuverability with load ratings exceeding 15 tons in urban job sites.
- REACH material compliance:European coating formulations free of restricted substances are unlocking cross-border fleet standardization for multinational haulage operators.
- Midwest manufacturing corridor concentration:Demand clustering around Ohio, Michigan, and Illinois is generating localized economies of scale in tub fabrication and aftermarket service density.
Market Restraints
- Steel price volatility:Carbon steel input costs fluctuate with scrap metal and energy markets, compressing margin predictability for metal tub fabricators.
- Single-source aluminum supply risk:Primary aluminum smelting concentrates in China and Gulf states, exposing North American manufacturers to tariff and logistics disruptions.
- Hydraulic system integration limits:Existing tipping mechanisms impose design constraints on ultra-lightweight tub architectures, capping weight reduction potential.
Strategic Opportunities
- Agricultural payload modularity:Kögel Trailers-style configurable tub systems can displace dedicated harvest equipment in grain and silage operations without full fleet replacement.
- Subscription maintenance expansion:Predictive service bundling with trailer leases is expanding into construction and waste haulage segments previously served by break-fix models.
- IRA clean fleet incentives:US tax credits for zero-emission heavy-duty vehicles are creating pull-through demand for lightweight tubs that maximize electric drivetrain range.
Industry Challenges
- Welding automation talent scarcity:Advanced fabrication of alloy tubs requires certified robotic welding technicians, a skill set concentrated at specialty vocational programs.
- ISO 9001 certification timelines:Fleet procurement tenders increasingly mandate quality management certification, imposing 12-18 month compliance windows on smaller fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dump Tubs Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Dump Tubs, Metal Dump Tubs, Fiberglass Dump Tubs, Rubber Dump Tubs Application: Commercial Use, Industrial Use, Residential Use, Agricultural Use Capacity: Small Capacity, Medium Capacity, Large Capacity, Extra Large Capacity End User: Contractors, Landscapers, Farmers, Homeowners |
| Companies Covered | Mac Trailer, Schmitz Cargobull, Manac, East Manufacturing, Kögel Trailers, MAXX-D Trailers, Construction Trailer Specialists, JCBL Limited, Wielton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dump Tubs Market Evolving Landscape
Material science breakthroughs and service model reinvention are compressing traditional equipment procurement cycles. Fleet operators now evaluate total lifetime cost rather than unit acquisition price, reshaping manufacturer competitive priorities.
Hybrid composite tub construction combining carbon fiber reinforcement with aluminum substrate is expanding into heavy-haul mining and aggregate applications previously reserved for carbon steel. Australian and Canadian open-pit operators are piloting these configurations to test abrasion resistance against ore impact. The technology is expanding into premium fleet segments where cycle time economics justify 40% higher acquisition cost against fuel and maintenance savings.
EPA Phase 3 greenhouse gas standards for heavy-duty vehicles are mandating trailer-specific fuel efficiency improvements, indirectly regulating dump tub weight and aerodynamic profiling. Manufacturers must now certify tub designs within integrated tractor-trailer efficiency modeling rather than as standalone components. The rule most affects extra-large capacity units in long-haul aggregate transport, where operators are retrofitting side skirts and tail fairings to existing fleets.
Fleet procurement departments are consolidating vendor relationships around full-service maintenance agreements rather than discrete equipment purchases. Construction contractors in the US Midwest are awarding multi-year tub supply contracts bundled with predictive hydraulic service and coating refurbishment. This concentration is most visible among regional waste management operators with 50-200 unit fleets, who prioritize uptime guarantees over capital expenditure flexibility.
Dump Tubs Market Segmentation
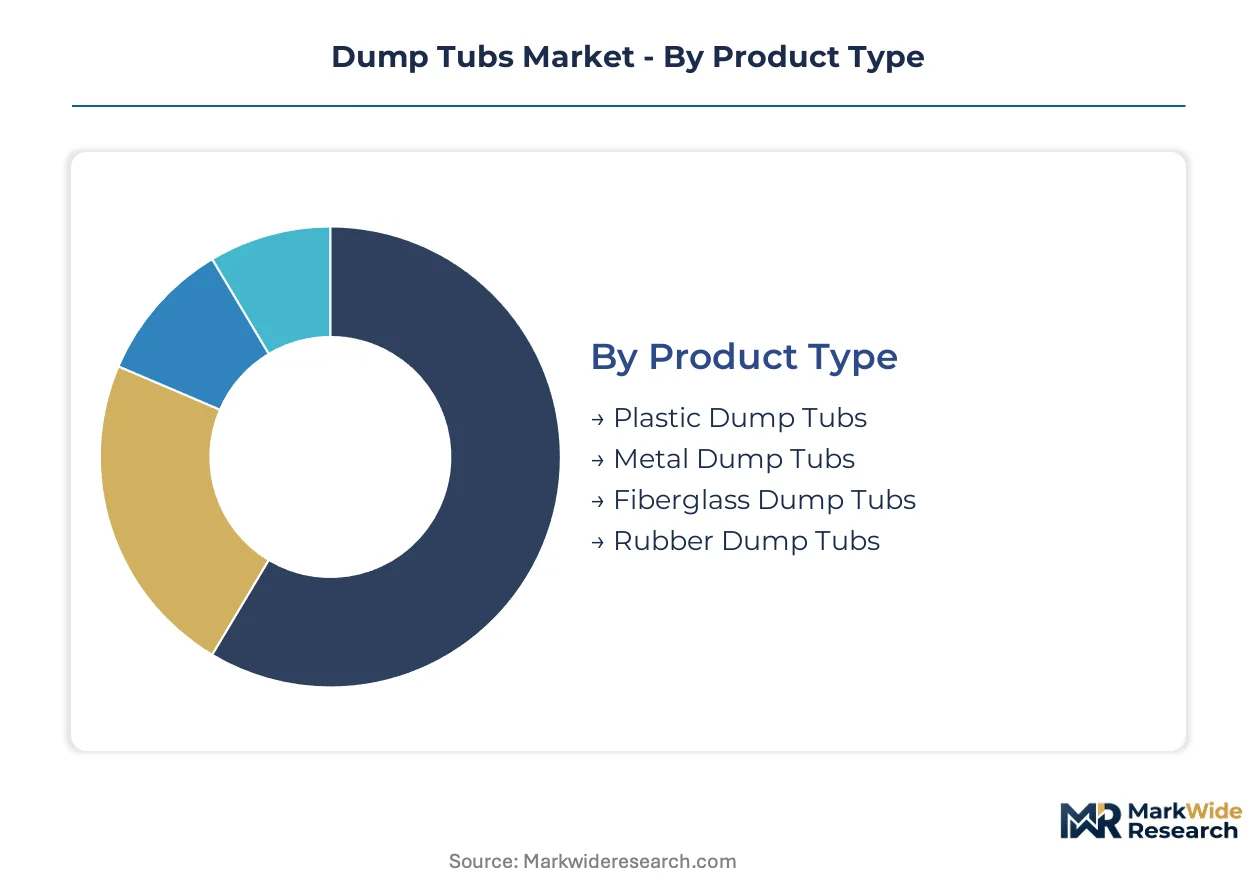
Dump tub specifications diverge sharply between heavy-haul commercial fleets and light-duty residential applications. Material selection and capacity ratings determine regulatory compliance pathways and lifetime operating economics for buyers.
Product Type:
Metal formulations dominate premium fleet procurement while plastic variants capture volume residential sales.
- Metal Dump Tubs:Carbon steel and aluminum alloy construction delivers abrasion resistance for loads exceeding 15 tons. EPA Phase 3 fuel economy mandates are accelerating aluminum adoption among long-haul aggregate operators in the US Midwest manufacturing corridor.
- Plastic Dump Tubs:High-density polyethylene formulations eliminate corrosion penalties and reduce tare weight for light contractor segments. Landscapers in residential zones favor these units for maneuverability on restricted-access job sites.
- Fiberglass Dump Tubs:Hybrid composite construction targets specialty chemical transport where corrosion resistance outweighs impact durability concerns.
- Rubber Dump Tubs:Flexible elastomer designs serve confined-space agricultural operations requiring dent-resistant handling of silage and feedstock.
Mature deployment sits with metal tubs. Newer deployment is concentrated in plastic variants.
Application:
Commercial infrastructure spending determines aggregate demand while residential renovation cycles drive replacement timing.
- Commercial Use:Construction contractors deploy medium-capacity metal tubs for urban debris removal where cycle frequency matters more than maximal volume. Fleet standardization around ISO 9001-certified suppliers is tightening vendor consolidation in this segment.
- Industrial Use:Mining and quarry operators specify extra-large capacity units with reinforced floor plates for ore impact resistance. Australian open-pit pilots of carbon-fiber hybrid tubs are testing weight reduction against steel benchmarks.
- Residential Use:Homeowners and small landscapers prioritize corrosion immunity and lower acquisition cost over load ratings. Plastic tubs with integrated wheel kits are displacing metal alternatives in this price-sensitive tier.
- Agricultural Use:Grain and silage operations demand modular configurations adaptable across harvest seasons without dedicated equipment investment. Kögel-style reconfigurable systems are gaining traction among European cooperative farms.
Commercial applications anchor manufacturer revenue. Agricultural deployment is expanding most quickly.
Capacity:
Mid-range specifications balance maneuverability constraints against payload efficiency for mixed-fleet operators.
- Medium Capacity:Contractors in Ohio, Michigan, and Illinois concentrate orders here for urban job site access. The segment captures volume leadership by satisfying both construction debris and agricultural transfer needs without specialized chassis requirements.
- Extra Large Capacity:Mining haulage operators accept premium positioning for single-trip volume maximization. EPA aerodynamic profiling rules are forcing side-skirt retrofits that add tare weight, intensifying pressure on tub lightweighting.
- Small Capacity:Residential gardeners and municipal maintenance crews favor these units for restricted-access landscaping.
- Large Capacity:Regional waste management fleets with 50-200 unit counts standardize here for route density optimization.
Medium capacity commands shipment volume. Extra large capacity delivers margin concentration.
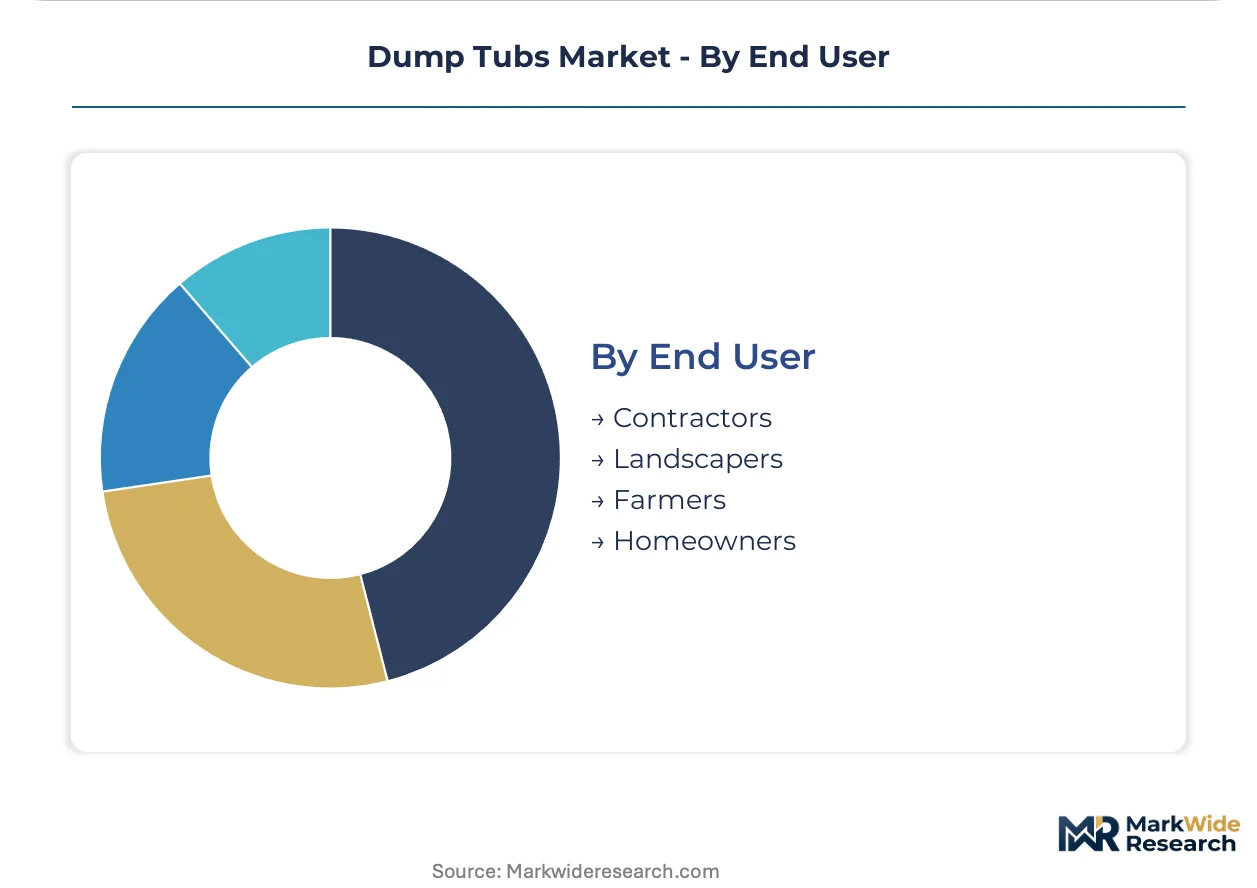
End User:
Professional contractors demand predictive maintenance bundling while homeowners prioritize upfront acquisition cost.
- Contractors:Construction fleet operators are consolidating vendor relationships around multi-year supply contracts with bundled hydraulic service and coating refurbishment. Subscription-based maintenance programs from Schmitz Cargobull-style service networks are displacing break-fix models.
- Farmers:Agricultural producers seek modular tub systems that reconfigure across grain, silage, and equipment transport without full fleet replacement. REACH-compliant coating formulations are unlocking cross-border standardization for multinational cooperatives.
- Landscapers:Light commercial operators balance corrosion immunity against maneuverability on residential streets with weight restrictions.
- Homeowners:Price-sensitive DIY buyers drive plastic tub volume through retail distribution channels with minimal service attachment.
Contractor procurement is professionalizing fastest. Homeowner demand remains transactionally fragmented.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States Midwest while consumption spreads across construction corridors in North America and European agricultural belts. This geographic split creates freight economics that favor regional fabrication over centralized supply. Trade flows respond to weight-to-value ratios that penalize long-haul tub shipment.
United States
Construction contractors in Ohio, Michigan, and Illinois are expanding medium-capacity metal tub orders for urban debris removal. EPA Phase 3 greenhouse gas standards mandate trailer-specific fuel efficiency improvements that compress tare weight tolerances. The Cleveland-Toledo manufacturing corridor generates localized economies of scale in steel fabrication and aftermarket hydraulic service density.
Germany
REACH-compliant coating formulations free of restricted substances are unlocking cross-border fleet standardization for multinational haulage operators. The EU Green Deal accelerates lightweight material adoption in heavy-duty trailers through embedded carbon accounting rules. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate modular tub system production for agricultural reconfiguration across grain and silage operations.
Canada
Open-pit mining operators in Alberta and British Columbia are piloting carbon-fiber hybrid tubs to test weight reduction against steel abrasion benchmarks. Environment and Climate Change Canada regulations on heavy-duty vehicle emissions parallel EPA stringency, creating regulatory alignment with US Midwest suppliers. The Edmonton-Calgary corridor anchors demand for extra-large capacity units in oil sands and aggregate haulage.
Australia
Iron ore and coal producers in Western Australia are deploying reinforced floor plate designs for maximal single-trip volume in remote site operations. The country's national heavy vehicle regulator enforces mass and dimension limits that intensify pressure on tub lightweighting without compromising impact resistance. The Pilbara mining region drives premium positioning for hybrid composite configurations previously reserved for carbon steel.
Poland
EU structural funds are modernizing agricultural cooperatives in Greater Poland and Lower Silesia with configurable tub systems adaptable across harvest seasons. The country's national environmental protection agency implements REACH-aligned chemical safety rules for coating formulations used in food-contact agricultural transport. Manufacturing investment in the Łódź-Warsaw corridor is expanding to serve German and Czech cross-border fleet procurement.
Dump Tubs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that fragments between integrated metal fabricators and specialized coating specialists. Tiering separates premium full-service networks from transaction-focused regional builders. Strategic archetypes include backward-integrated steel processors, modular configuration specialists, and predictive maintenance bundlers. Dominant competitive moves center on captive supply chain control and multi-year service contract consolidation.
Among European full-service networks, Schmitz Cargobull exemplifies the predictive maintenance archetype through lease-bundled service offerings. Kögel Trailers occupies a position within modular configuration specialists serving agricultural payload flexibility demands. Mac Trailer anchors the backward-integrated tier with in-house steel fabrication and custom coating operations. These three patterns represent the competitive vectors reshaping procurement relationships away from discrete equipment transactions.
| Leading Market Players |
|---|
| Mac Trailer |
| Schmitz Cargobull |
| Manac |
| East Manufacturing |
| Kögel Trailers |
| MAXX-D Trailers |
| Construction Trailer Specialists |
| JCBL Limited |
| Wielton |
| Others |
Value Network & Pricing Analysis
EPA Phase 3 fuel economy mandates compressing tare weight tolerances force fleet operators toward aluminum alloy and composite formulations, compelling manufacturers to absorb premium material costs or pass through pricing while defending payload capacity ratings. This specification-driven procurement pressure concentrates pricing power among backward-integrated fabricators with captive steel and coating operations.
Pricing Analysis
Margin tightening in medium-capacity metal tubs reflects carbon steel input volatility and the cost premium for EPA-compliant lightweight alloys. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified full-service bundles from transaction-focused regional builders. Pricing pressure stems from fleet procurement consolidation around multi-year maintenance contracts. Homeowner segments exhibit highest price sensitivity, while mining operators prioritize lifecycle cost over unit acquisition.
Supply Chain Analysis
Primary aluminum smelting rests on concentrated capacity in China and Gulf states, exposing North American fabricators to tariff and logistics disruptions. Carbon steel feedstock draws from domestic Midwest mills, while hydraulic system components rely on German and Japanese specialty manufacturers. Single-source aluminum dependency constitutes the dominant structural risk. Distribution runs through regional fabrication clusters serving localized construction corridors, with aftermarket service density determining vendor selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players securing upstream control over steel fabrication and downstream capture through predictive maintenance networks. The competitive race centers on who locks in captive supply before aluminum tariff exposure materializes.
For Market Incumbents: Extend predictive maintenance bundling from European networks into US Midwest construction fleets before regional competitors consolidate vendor relationships. Deepen backward integration into steel processing to buffer carbon steel price volatility. Certify ISO 9001 compliance ahead of fleet procurement tender windows to disqualify smaller fabricators. For New Entrants and Emerging Players: Agricultural equipment distributors represent the most accessible channel partners for modular tub configurations targeting European cooperative farms. Target Poland and Czech agricultural belts where EU structural funds modernize harvest operations. Lead with REACH-compliant coating formulations that unlock cross-border fleet standardization for multinational haulage operators. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap fabricators possessing robotic welding automation capabilities given the scarcity of certified technicians at specialty vocational programs. Five-to-ten year viability hinges on aluminum alloy formulation expertise and service network density. Watch EPA enforcement timing on Phase 3 trailer standards as the inflection trigger for lightweighting investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Processing | Captive supply of carbon steel insulates margin from scrap metal volatility in Midwest manufacturing corridors. |
| Predictive Maintenance Network Expansion | Lease-bundled service offerings from Schmitz Cargobull-style operators displace break-fix revenue models in construction fleets. |
| Modular Tub Configuration Development | Kögel Trailers-style adaptable systems capture agricultural payload flexibility without full fleet replacement investment. |
| ISO 9001 Certification Acceleration | Quality management credentials function as market access prerequisites for fleet procurement tenders across North America and Europe. |
| Lightweight Alloy Formulation Investment | Aluminum and hybrid composite architectures preserve payload capacity under EPA Phase 3 fuel economy mandates. |
Research Methodology
Independent corroboration across fleet procurement directors, plant engineers at Midwest fabrication facilities, aftermarket service heads, and regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from EPA enforcement records, ISO certification registries, customs trade data for aluminum and steel inputs, and SEC filings from trailer manufacturers. Bottom-up shipment estimates from regional fabrication clusters triangulate against top-down demand modeling from construction spending indicators.
Historical reference periods anchor the projection framework across the analysis window, with growth trajectories derived from segment-level elasticity to infrastructure investment cycles. Segmentation dimensions include material formulation, capacity tier, application vertical, and regional regulatory cluster. Modeled inputs incorporate fleet renewal timing, REACH compliance transitions, and IRA clean fleet incentive uptake curves.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations on primary aluminum, steel price spike events exceeding historical volatility bands, and hydraulic system technology breakthroughs that relax lightweighting constraints. Forecasts reflect documented assumptions about regulatory enforcement continuity and fleet operator procurement behavior stability. A small set of named triggers warrants ongoing watch: EPA Phase 3 implementation timing, aluminum smelting capacity expansion in non-Chinese jurisdictions, and welding automation training program graduation rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Freight Elevators Market