
 Asia-Pacific Forklift Truck Market | 2026-2036
Asia-Pacific Forklift Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Forklift Truck Market Analytics
Multi-source procurement for battery packs and drive systems is restructuring supply relationships across the Asia-Pacific forklift truck market. Toyota Industries Corporation leverages captive production of solid-state battery prototypes to secure early mover positioning in electrified material handling. Hangcha Group anchors its cost structure through integrated motor and controller manufacturing at its Zhejiang headquarters. KION Group AG navigates regional competition by extending its Linde and Baoli brand architecture across premium and value-tier distribution channels.
A forklift truck is a powered industrial vehicle with a hydraulically operated vertical mast and fork attachment, typically rated by load center capacity and lift height, designed to transport palletized goods within warehouse, factory, and port environments. Electric forklifts now dominate new orders in the Asia-Pacific region as Li-ion battery energy density improvements eliminate the multi-shift downtime penalties of legacy lead-acid systems. Automated Guided Vehicles represent the fastest-expanding technology segment, though margin pools remain concentrated in the 3-5 ton capacity class where manufacturing and distribution center procurement overlaps. Telemetry systems embedded in fleet management platforms are shifting vendor revenue from unit sales toward recurring software and uptime service contracts.
China's MIIT enforces GB standards for industrial vehicle emissions and safety certification, while Japan's METI administers JIS benchmarks that constrain import access for non-compliant equipment. India's BIS and CDSCO equivalent frameworks for industrial machinery safety are tightening inspection protocols at major port and logistics zones. Stakeholders must monitor how hydrogen fuel cell certification timelines in South Korea and Japan intersect with battery-electric infrastructure buildout decisions across ASEAN manufacturing hubs.
Market Dynamics
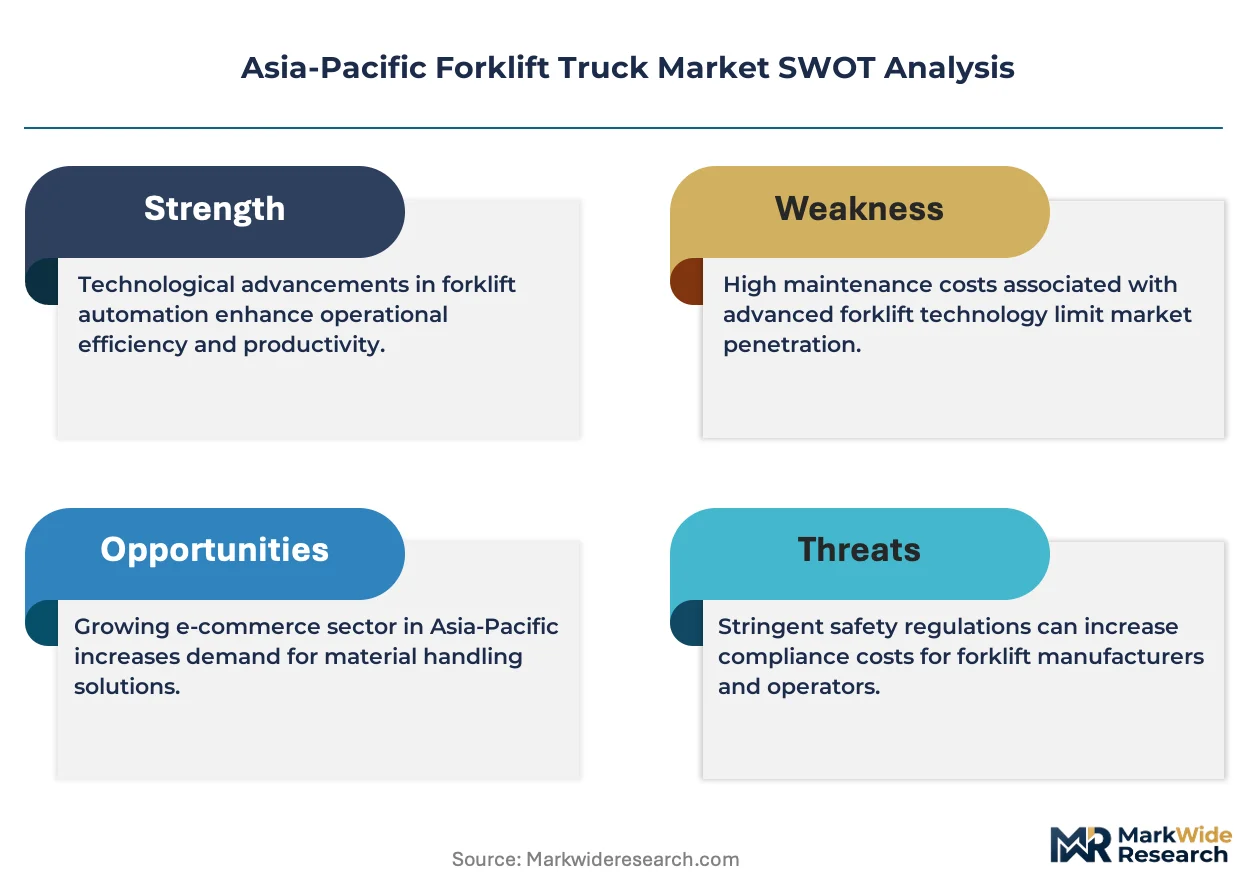
Electrification mandates across Asia-Pacific manufacturing hubs are compressing the transition timeline from internal combustion to battery-powered fleets, forcing procurement departments to accelerate capital replacement cycles ahead of residual value recovery.
Growth Catalysts
- E-commerce fulfillment density:Southeast Asian logistics networks are expanding automated storage and retrieval systems, creating synchronized demand for electric counterbalance trucks in multi-level distribution centers.
- China's dual carbon goals:MIIT enforcement of GB emission standards for industrial vehicles is prohibiting new internal combustion forklift registrations in key manufacturing zones.
- Li-ion energy density gains:Battery chemistry improvements now support continuous multi-shift operations without battery changeout infrastructure, eliminating the productivity penalty that slowed prior electric adoption.
Market Restraints
- Raw material concentration:Cathode active material processing concentrates in Chinese refining corridors, exposing non-Chinese OEMs to supply rationing during export quota periods.
- Charging infrastructure gap:High-voltage fast-charging station deployment lags fleet electrification timelines in Indonesian and Vietnamese industrial zones.
- Residual value collapse:Secondary markets for used internal combustion trucks are contracting as operating cost penalties and regulatory access restrictions accelerate functional obsolescence.
Strategic Opportunities
- Hydrogen fuel cell corridor:South Korean and Japanese port authorities are piloting fuel cell forklift fleets with dedicated hydrogen supply chains, creating first-mover positioning for equipment suppliers.
- ASEAN manufacturing relocation:Vietnam, Thailand, and Indonesia are absorbing capacity shifts from Chinese coastal zones, generating greenfield warehouse automation demand.
- Telemetry-as-revenue:Fleet management platforms are enabling subscription-based uptime guarantees, displacing traditional maintenance contract structures.
Industry Challenges
- Technician skill scarcity:High-voltage battery service and fuel cell system maintenance require certifications that outpace vocational training program output across the region.
- Legacy system integration:Automated Guided Vehicle deployment in existing warehouse management environments demands middleware development that extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Forklift Truck Market |
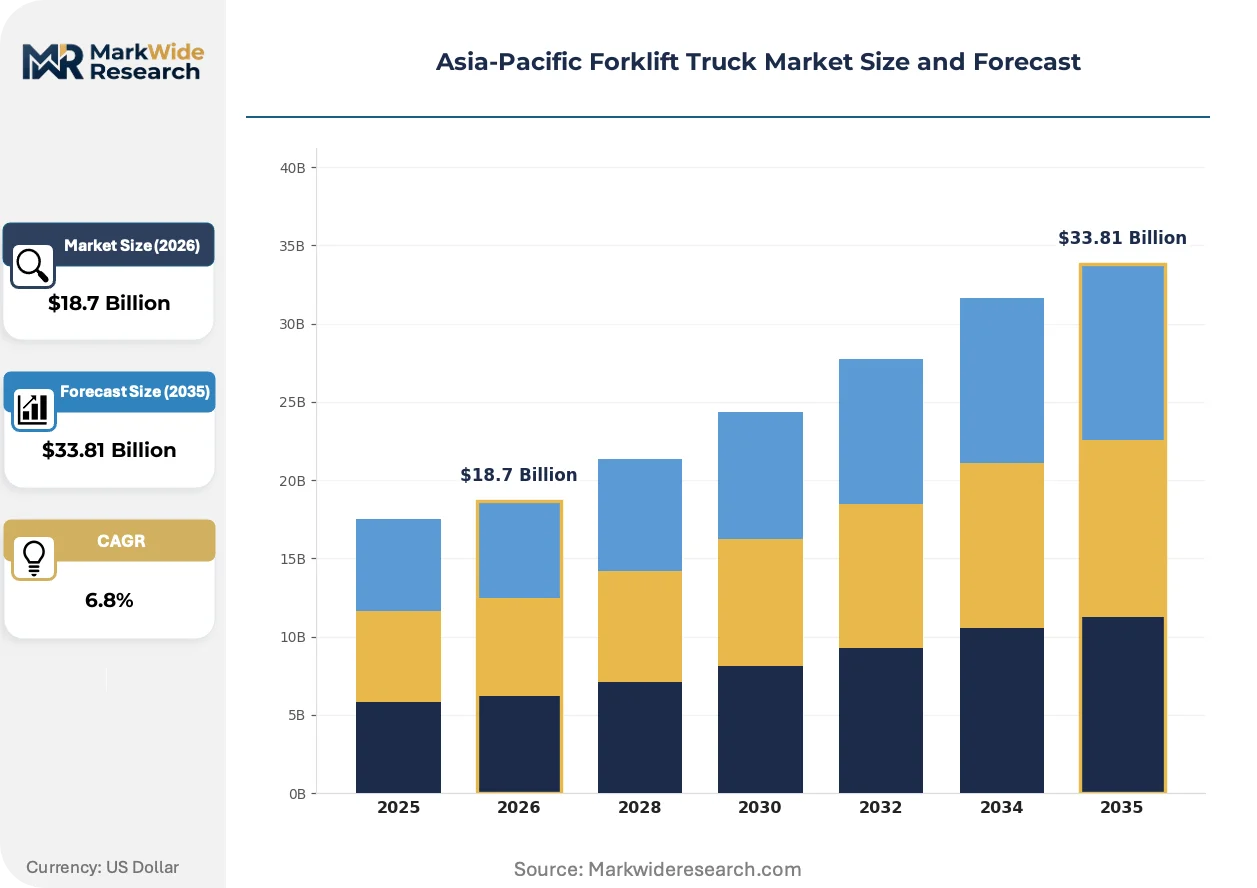
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Internal Combustion Forklifts, Automated Guided Vehicles, Pallet Jacks End User: Warehousing, Manufacturing, Retail, Distribution Centers Capacity: 1-3 Tons, 3-5 Tons, 5-10 Tons, Above 10 Tons Technology: Li-ion Batteries, Hydrogen Fuel Cells, Telemetry Systems, Automated Systems |
| Companies Covered | Toyota Industries Corporation, KION Group AG, Jungheinrich AG, Mitsubishi Logisnext Co Ltd, Hyster-Yale Materials Handling Inc, Crown Equipment Corporation, Komatsu Ltd, Hangcha Group, Doosan Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Forklift Truck Market Evolving Landscape
Material handling equipment is converging with autonomous navigation and energy storage technologies, compressing the boundary between manually operated trucks and fully automated mobile robots in warehouse environments.
Automated Guided Vehicles with LiDAR-based navigation and dynamic path planning are expanding into mid-tier distribution centers previously served by conventional rider trucks. Third-party logistics operators in China's Yangtze River Delta are deploying mixed fleets where AGVs handle repetitive horizontal transport while human operators manage variable-lift tasks. This hybrid architecture is expanding into the 3-5 ton capacity segment where manufacturing and distribution procurement overlaps, compressing margins for basic electric counterbalance models.
Japan's METI has tightened JIS B 8962 safety benchmarks for autonomous industrial vehicles, requiring redundant braking systems and pedestrian detection validation. Equipment suppliers must now certify navigation algorithms through designated testing facilities in Tsukuba before commercial deployment. Manufacturers serving Japanese automotive assembly plants are accelerating compliance investments to maintain preferred supplier status under keiretsu procurement frameworks.
Buyer preference is rotating toward total-cost-of-ownership contracting rather than unit purchase. Australian mining services and Singaporean port operators are negotiating power-by-the-hour agreements where vendors retain asset ownership and charge per pallet move. This consumption-based structure shifts balance sheet treatment and accelerates fleet refresh cycles beyond traditional depreciation schedules.
Asia-Pacific Forklift Truck Market Segmentation
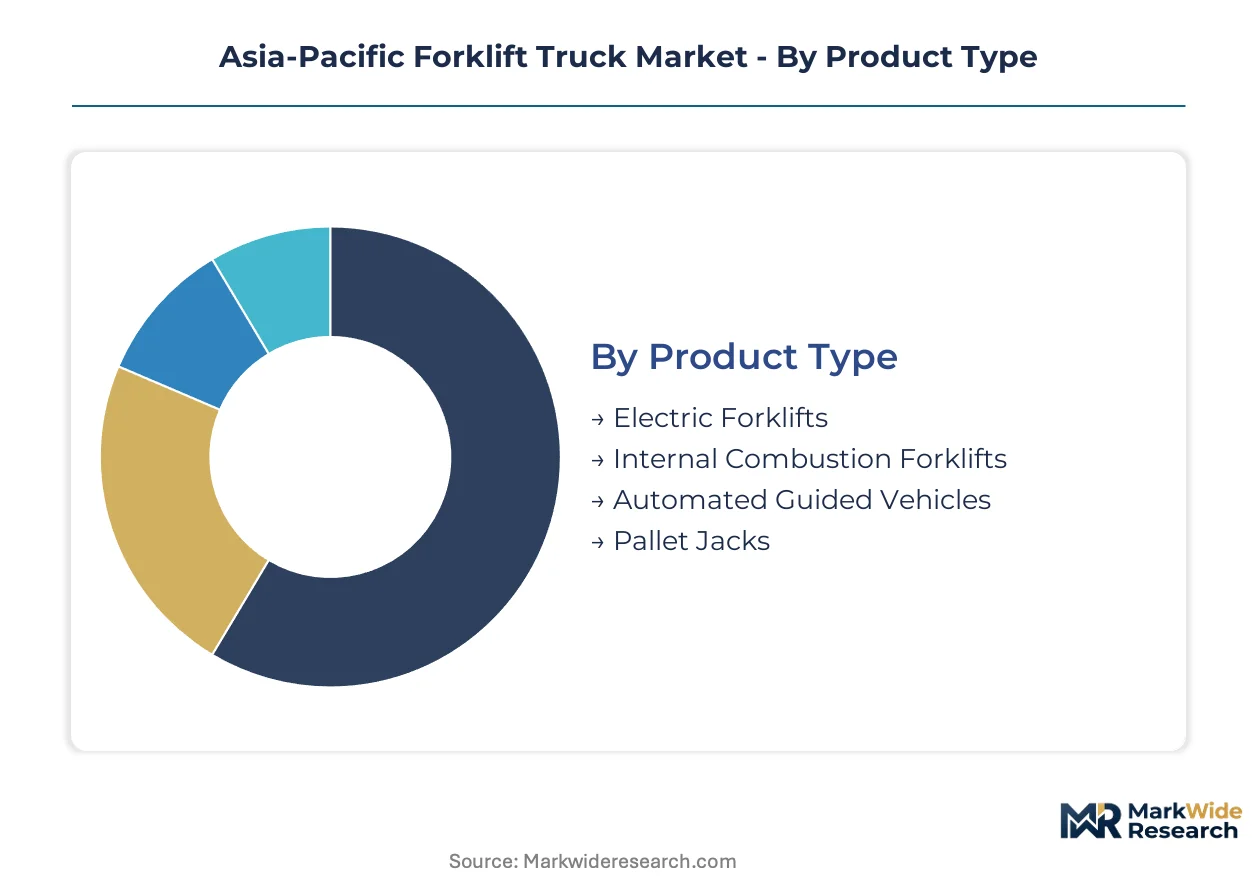
Segmentation in the Asia-Pacific forklift truck market reveals how capital deployment, operational intensity, and technology readiness diverge across buyer profiles. Procurement patterns in China's Yangtze River Delta manufacturing corridor differ sharply from Indonesian port logistics, forcing suppliers to architect modular product platforms.
Product Type:
Capital intensity varies dramatically across equipment categories, with automated systems demanding infrastructure investment multiples above conventional trucks.
- Electric Forklifts:These battery-powered units utilize AC motor drives and regenerative braking systems rated for 2,000-5,000 charge cycles. Demand concentrates in China's Jiangsu and Zhejiang provinces where MIIT emission enforcement prohibits new internal combustion registrations; the elimination of battery changeout downtime through Li-ion chemistry is accelerating fleet replacement ahead of depreciation schedules.
- Automated Guided Vehicles:AGVs integrate LiDAR navigation, warehouse management system middleware, and safety-rated controllers for autonomous horizontal transport. Southeast Asian third-party logistics operators in Singapore and Vietnam are deploying these in greenfield distribution centers where labor cost trajectories favor automation.
- Internal Combustion Forklifts:Diesel and LPG-powered trucks retain residual demand in heavy outdoor applications and Indonesian mining logistics where charging infrastructure remains underdeveloped.
- Pallet Jacks:Manual and electric walk-behind units serve last-meter material handling in retail backrooms and small warehousing operations across Thailand's manufacturing zones.
Electric forklifts absorb the bulk of installed capacity; Automated Guided Vehicles are expanding most quickly.
End User:
Application environment dictates equipment specification, with duty cycles and shift patterns creating distinct margin profiles for suppliers.
- Warehousing:High-rack storage operations in Australia's e-commerce fulfillment networks require reach trucks and order pickers with 12-meter lift heights and narrow aisle maneuverability.
- Manufacturing:Just-in-time assembly line feed operations in Japan's automotive keiretsu demand AGVs with synchronized production scheduling and millimeter positioning accuracy.
- Distribution Centers:Cross-dock facilities in Vietnam's northern industrial provinces are procuring 3-5 ton electric counterbalance trucks for container unloading and pallet redistribution.
- Retail:Big-box store operators in South Korea utilize compact electric pallet jacks and stackers for stockroom replenishment during overnight restocking windows.
Manufacturing commands the highest equipment specification density; Distribution Centers are climbing the fastest as ASEAN logistics networks expand.
Capacity:
Load rating determines component sizing, with hydraulic system and mast engineering costs scaling non-linearly above 5-ton thresholds.
- 3-5 Tons:This mid-range segment dominates procurement overlap between manufacturing and distribution applications, featuring dual-pump hydraulic systems and cushion or pneumatic tire options. China's Yangtze River Delta electronics assembly plants and Malaysian port logistics operators both standardize on this class, creating volume concentration that compresses margins for basic configurations.
- 1-3 Tons:Light-duty electric forklifts with three-wheel configurations serve narrow-aisle warehousing and retail distribution in Japan's dense urban logistics corridors.
- 5-10 Tons:Heavy electric and internal combustion trucks handle steel coil and container handling in Australian mining services and Indonesian bulk cargo terminals.
- Above 10 Tons:Specialized heavy-lift trucks with reinforced masts and dual drive motors serve port container handling and heavy machinery manufacturing in South Korea's shipbuilding clusters.
The 3-5 ton segment anchors procurement volume; Above 10 Tons carries the steepest expansion trajectory as port automation accelerates.
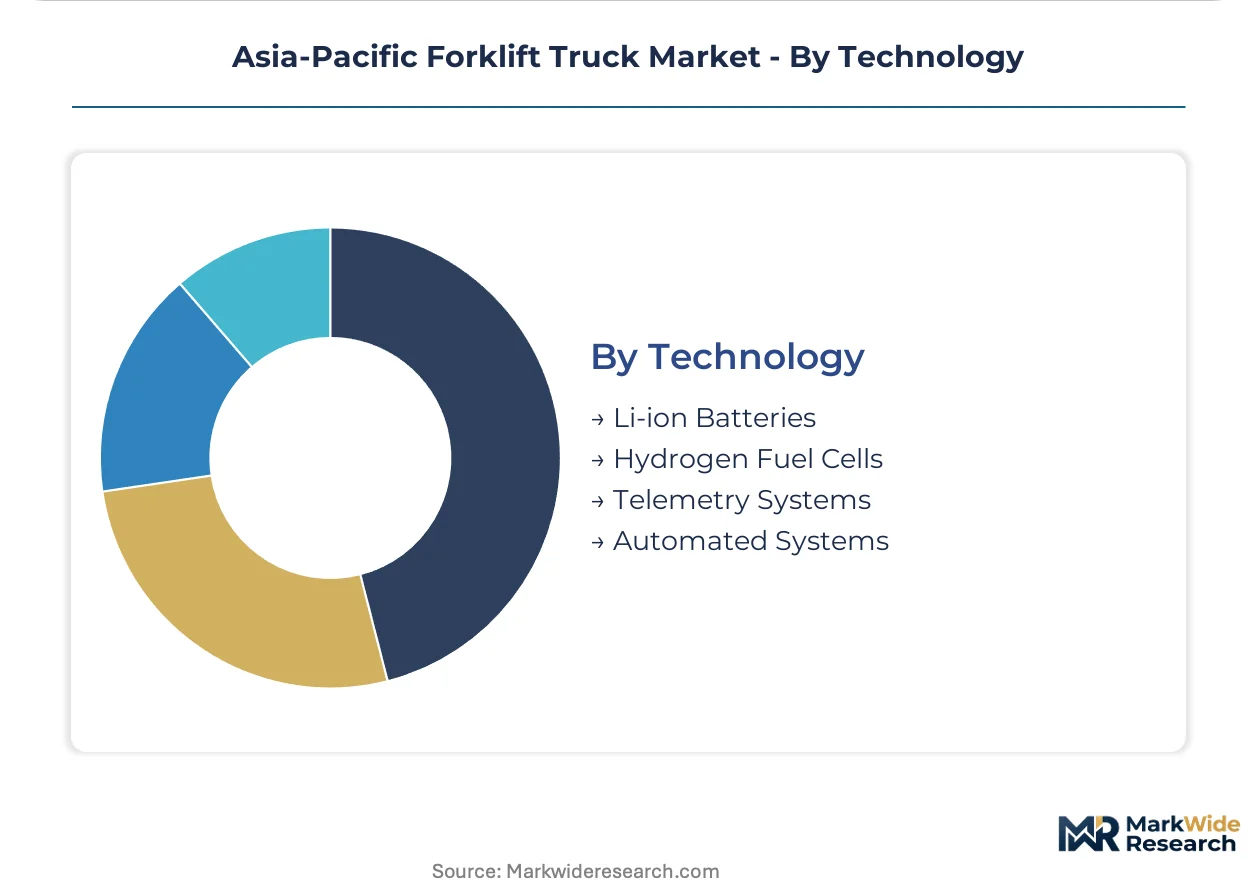
Technology:
Technology stack selection determines operating economics, with energy storage and data architecture decisions locking in decade-long cost structures.
- Li-ion Batteries:Lithium iron phosphate and NMC chemistries deliver 200+ Wh/kg energy density with opportunity charging capability. Japanese METI efficiency mandates and China's dual carbon goals are channeling procurement toward these systems, though cathode material refining concentration in Chinese corridors exposes supply risk during export quota periods.
- Telemetry Systems:Fleet management platforms with GPS tracking, utilization analytics, and predictive maintenance algorithms are displacing traditional service contracts. Australian mining services and Singaporean port operators are negotiating power-by-the-hour agreements where vendors retain asset ownership.
- Automated Systems:Navigation software, safety controllers, and warehouse integration middleware enable AGV deployment in existing facilities.
- Hydrogen Fuel Cells:Proton exchange membrane systems with 3-5 minute refueling are piloting in South Korean and Japanese port authorities with dedicated hydrogen supply chains.
Li-ion Batteries capture the dominant share of new energy storage deployments; Hydrogen Fuel Cells are gaining share fastest in heavy-duty port applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cathode active material refining corridors in China's Jiangxi and Hunan provinces anchor battery supply chains for electrified material handling equipment across the region.
China
E-commerce fulfillment networks and automotive assembly plants drive procurement volumes in Jiangsu and Zhejiang provinces. MIIT enforcement of GB emission standards for industrial vehicles prohibits new internal combustion forklift registrations in the Yangtze River Delta manufacturing corridor. Suzhou and Hangzhou logistics hubs are deploying mixed fleets of electric counterbalance trucks and automated guided vehicles for multi-shift operations.
Japan
Automotive keiretsu assembly lines and precision manufacturing facilities sustain demand for high-specification material handling equipment. METI administers JIS B 8962 safety benchmarks for autonomous industrial vehicles, requiring redundant braking systems and pedestrian detection validation. Nagoya's Chubu manufacturing belt is certifying navigation algorithms through designated Tsukuba testing facilities before commercial AGV deployment.
South Korea
Port automation and shipbuilding clusters generate heavy-lift equipment procurement for container handling operations. The country's national industrial regulator oversees hydrogen fuel cell certification timelines for pilot forklift fleets at Busan and Ulsan port authorities. Seoul Capital Area distribution centers are integrating telemetry-enabled fleet management platforms for uptime service contracts.
Vietnam
Manufacturing relocation from Chinese coastal zones and greenfield warehouse construction accelerate electric forklift adoption in northern industrial provinces. The country's national standards body tightens inspection protocols for industrial machinery safety at major port and logistics zones. Hai Phong and Bac Ninh logistics corridors are standardizing on 3-5 ton electric counterbalance trucks for container unloading operations.
Australia
Mining services and bulk commodity terminals sustain demand for heavy-duty material handling equipment in Western Australia and Queensland. The country's national industrial safety regulator enforces certification requirements for high-voltage battery service technicians. Perth and Brisbane port operators are negotiating power-by-the-hour agreements where vendors retain asset ownership and charge per pallet move.
Asia-Pacific Forklift Truck Market Competitive Landscape
Multi-source procurement for battery packs and drive systems dominates the current landscape, compressing traditional supply relationships and forcing equipment vendors to secure captive component production. The vendor base stratifies across three tiers: integrated manufacturers with in-house motor and controller fabrication, brand architecture specialists operating multiple marques across premium and value distribution channels, and regional fabricators serving price-sensitive procurement in emerging logistics corridors. Strategic archetypes include electrification-first specialists, automation-integrated platform providers, and scale-driven cost leaders. Portfolio diversification and geographic expansion constitute the dominant competitive moves, with particular emphasis on ASEAN manufacturing relocation zones.
Among Asia-Pacific-based manufacturers, Toyota Industries Corporation, Hangcha Group, and KION Group AG occupy distinct positioning within this structure. Toyota Industries Corporation exemplifies the electrification-first archetype through its captive battery technology investments. Hangcha Group anchors the integrated manufacturing tier with headquarters-based production of core drivetrain components. KION Group AG represents the multi-brand architecture approach, extending its portfolio across premium and value-tier distribution channels to navigate regional competition intensity.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| KION Group AG |
| Jungheinrich AG |
| Mitsubishi Logisnext Co Ltd |
| Hyster-Yale Materials Handling Inc |
| Crown Equipment Corporation |
| Komatsu Ltd |
| Hangcha Group |
| Doosan Corporation |
| Others |
Value Network & Pricing Analysis
Procurement mandates for GB-compliant electric forklifts in China's Yangtze River Delta are forcing non-Chinese OEMs to absorb cathode material premiums or surrender margin, restructuring supplier negotiations toward captive battery partnerships and regional fabrication commitments.
Pricing Analysis
Extended warranty bundling with telemetry-enabled uptime guarantees now separates premium-tier vendors from unbundled equipment sellers in Japanese and Australian procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales density, with MIIT emission enforcement compressing margins for legacy internal combustion inventory. Price erosion runs through the standard tier as Hangcha Group and regional fabricators compete on integrated motor-controller cost structures. Distribution centers in Vietnam and Indonesia exhibit highest price sensitivity; Japanese automotive keiretsu tolerate premium positioning for JIS-validated autonomous systems.
Supply Chain Analysis
Domestic-content thresholds in India's industrial machinery safety protocols and Vietnam's port logistics zones are redirecting component sourcing from pure Chinese supply toward ASEAN assembly partnerships. Cathode active material refining concentrates in China's Jiangxi and Hunan provinces, with South Korean and Japanese cell finishing feeding regional pack integration. Supply chain risk centers on export quota rationing during Chinese environmental inspection periods. Distribution runs through Linde and Baoli brand architecture across premium and value-tier channels, with direct OEM relationships dominating Australian mining services and Singaporean port operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance narrative where METI's JIS B 8962 autonomous vehicle benchmarks and MIIT's GB emission enforcement erect certification moats that favor incumbents with Tsukuba testing access and Yangtze River Delta service infrastructure.
For Market Incumbents: Deploy captive solid-state battery prototyping to secure early-mover positioning against hydrogen fuel cell corridor pilots in Busan and Ulsan. Consolidate channel control through telemetry-as-revenue subscriptions that displace third-party maintenance contracts. Deepen backward integration into Li-ion cell finishing to offset cathode material concentration risk during Chinese export quota windows.
For New Entrants and Emerging Players: Capture greenfield warehouse automation demand in Vietnam's Bac Ninh and Hai Phong corridors where procurement standards remain unsettled and local fabrication partnerships satisfy emerging domestic-content requirements. Target 3-5 ton electric counterbalance procurement in ASEAN manufacturing relocation zones through power-by-the-hour financing structures that shift balance sheet treatment for cost-constrained buyers.
For Investors and Strategic Acquirers: The window for entry favors integrated manufacturers with in-house motor-controller fabrication and established METI certification relationships over brand-assembly operations. Watch hydrogen fuel cell certification timelines in South Korea and Japan as the inflection signal determining whether battery-electric infrastructure investments face stranded asset risk in heavy-duty port applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Finishing | Captive supply of Li-ion packs insulates Hangcha and Toyota Industries from Jiangxi refining corridor quota volatility. |
| Telemetry Platform Subscription Launch | Fleet management software shifts KION Group revenue from unit sales toward recurring uptime guarantees in Australian mining. |
| JIS B 8962 Certification Investment | Tsukuba validation for autonomous navigation algorithms secures preferred supplier status in Nagoya automotive keiretsu. |
| Hydrogen Fuel Cell Pilot Partnership | Busan port authority deployments create first-mover positioning for equipment suppliers in South Korean heavy-lift segments. |
| ASEAN Manufacturing Footprint Expansion | Greenfield assembly in Vietnam and Thailand captures capacity relocation from China's coastal zones while satisfying local-content rules. |
Research Methodology
Multi-period observation of MIIT enforcement patterns, METI certification timelines, and ASEAN logistics procurement cycles anchored the trend analysis, supplemented by interviews with fleet maintenance directors, OEM procurement teams, aftermarket service heads, and warehouse automation engineers. Secondary validation drew from customs trade data, industrial vehicle registration databases, SEC filings of listed equipment manufacturers, and port authority capital expenditure disclosures. Bottom-up equipment shipment tracking and top-down manufacturing value-add estimates were triangulated against telemetry platform subscription revenue disclosures.
Input-output matrices modeled forklift procurement across product type, capacity class, end-use application, and technology stack dimensions over the projection horizon. CAGRs were derived from segmented demand elasticity analysis incorporating Li-ion energy density improvement curves and hydrogen fuel cell cost reduction trajectories. Forecast inputs included shift-pattern utilization rates in Yangtze River Delta electronics assembly and container throughput growth at Vietnamese northern industrial province ports.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cathode material export policy shifts and hydrogen infrastructure buildout pacing. Forecasts reflect documented assumptions regarding MIIT enforcement continuity and METI benchmark revision timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Ball Screw Support Unit Market