
 Load Balancing Software Market | 2026-2036
Load Balancing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Load Balancing Software Market Analysis
Container orchestration is rebalancing infrastructure economics as Kubernetes-native proxies replace proprietary hardware appliances. F5 leverages its BIG-IP platform heritage to sustain enterprise loyalty through hybrid cloud portability. AWS anchors public cloud load balancing with tightly integrated auto-scaling services across its global edge network. Microsoft competes through Azure Front Door and Application Gateway convergence with Entra identity services.
Load balancing software distributes network or application traffic across multiple servers to prevent overload and ensure continuity, operating through algorithms such as round-robin, least-connections, and weighted response-time routing with health-check intervals typically set below 30 seconds. Cloud deployment leads segment momentum as enterprises abandon capital-intensive hardware refresh cycles, while application delivery controllers retain the deepest margin pools due to integrated security and analytics bundling. Software-based technology outpaces hardware-based alternatives as ARM-based commodity servers achieve throughput parity at lower unit economics.
The EU AI Act and NIS2 Directive impose strict operational resilience requirements on critical infrastructure operators, compelling European enterprises to adopt redundant software-defined traffic management. In the United States, NIST zero-trust architecture mandates and FedRAMP authorization requirements shape federal procurement specifications for load balancing platforms. Stakeholders must monitor how sovereign cloud regulations fragment vendor certification requirements across national boundaries.
Market Dynamics
Container orchestration platforms are compressing infrastructure refresh cycles as enterprises abandon proprietary hardware appliances for software-defined traffic management. Kubernetes-native service meshes now handle east-west traffic patterns that previously required dedicated load balancing hardware.
Growth Catalysts
- EU AI Act:The EU AI Act mandates operational resilience for high-risk AI systems, compelling financial services and healthcare operators to deploy redundant software-defined traffic management across multi-zone architectures.
- Hyperscaler edge expansion:AWS, Microsoft Azure, and Google Cloud are extending their load balancing services into 5G edge zones, creating pull-through demand for hybrid cloud management tools in telecommunications infrastructure.
- eBPF kernel technology:Extended Berkeley Packet Filter implementations enable traffic inspection at line rate without kernel bypass overhead, allowing commodity x86 servers to match proprietary ASIC throughput.
Market Restraints
- Specialized engineering talent scarcity:Deep expertise in Layer 4-7 traffic engineering and cryptographic offload configuration commands salary premiums exceeding 40% above general DevOps compensation bands.
- Certificate lifecycle complexity:mTLS everywhere mandates impose operational burdens as enterprises manage thousands of rotating certificates across distributed service meshes with sub-24-hour revocation windows.
- Hyperscaler lock-in risk:Native cloud load balancing services embed proprietary APIs that complicate multi-cloud failover strategies and inflate exit costs for regulated enterprises.
Strategic Opportunities
- India PLI scheme:The Indian government's Production Linked Incentive scheme for data center infrastructure is attracting hyperscaler investment, creating demand for localized load balancing software with domestic data residency compliance.
- Zero-trust architecture convergence:Integration of identity-aware proxying with continuous authorization verification opens bundling opportunities with identity providers like Okta and Microsoft Entra.
- FinOps tooling integration:Embedding real-time traffic cost allocation into load balancing consoles addresses cloud cost visibility gaps that plague platform engineering teams.
Industry Challenges
- Legacy appliance retirement friction:Enterprises maintaining decade-old F5 and Citrix hardware deployments face skill attrition as veteran engineers exit without knowledge transfer protocols.
- Multi-cloud policy synchronization:Maintaining consistent traffic routing rules across AWS, Azure, and private Kubernetes clusters requires abstraction layers that introduce latency and debugging complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Load Balancing Software Market |
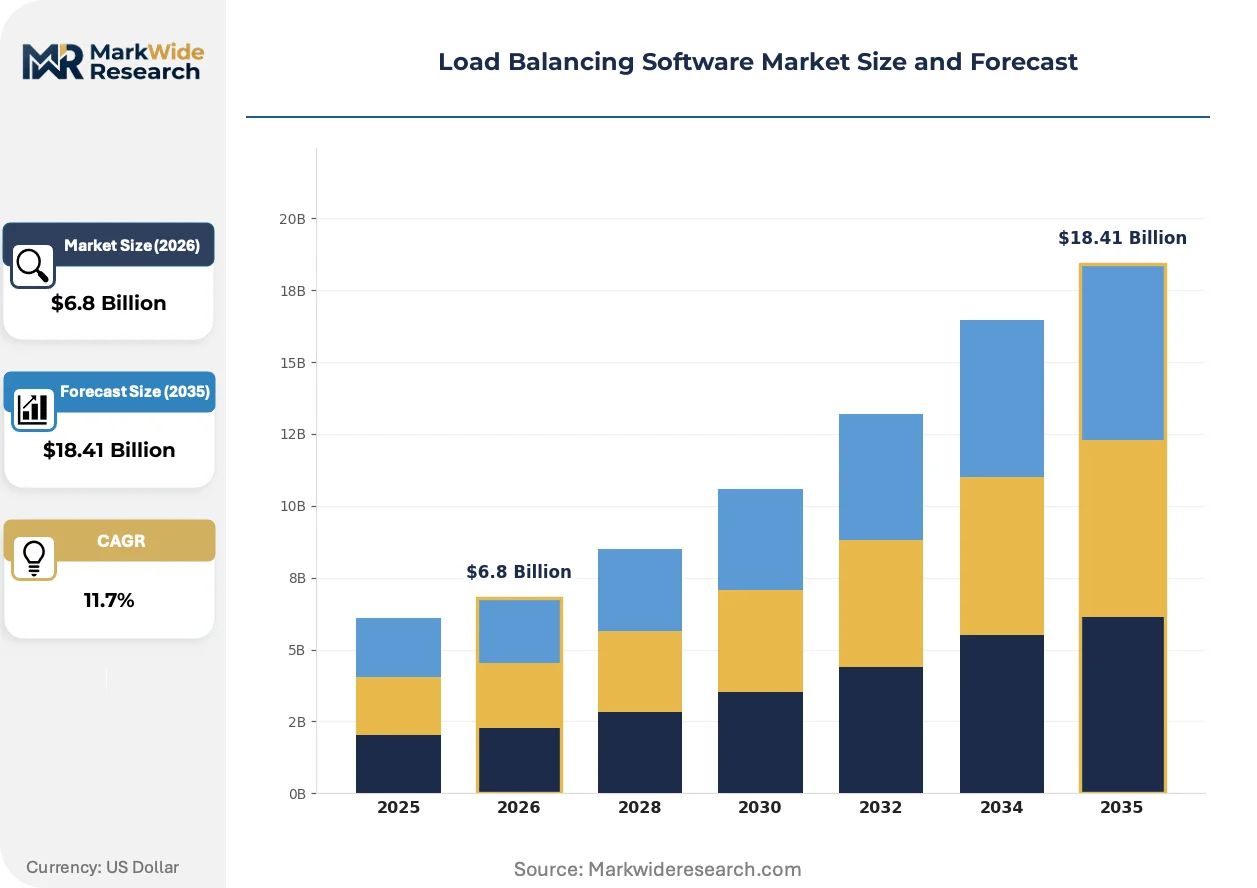
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $18.41 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Multi-Cloud Product Type: Local Traffic, Global Traffic, DNS Load Balancer, Application Delivery Controller End User: Enterprises, Service Providers, Government, Educational Institutions Technology: Software-Based, Hardware-Based, Multi-Protocol, Virtual Appliance |
| Companies Covered | F5, A10 Networks, Citrix Systems, NGINX, HAProxy Technologies, IBM, Microsoft, AWS, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Load Balancing Software Market Emerging Trajectories
Traffic management architectures are converging with security and observability stacks as enterprises reject point solutions in favor of unified control planes. This consolidation is compressing vendor margins while elevating platform engineering skill requirements.
Envoy Proxy is unifying ingress and service mesh traffic handling through a single data plane implementation. Platform engineering teams at Fortune 500 retailers and payment processors are standardizing on Envoy as the universal proxy layer. This consolidation is unifying previously separate procurement streams for edge gateways and internal microservices communication into single vendor relationships.
NIST zero-trust architecture mandates are reshaping federal procurement specifications for civilian agencies and defense contractors. Continuous verification requirements now extend to traffic routing decisions, not just authentication events. Federal system integrators are responding by embedding identity-aware load balancing into classified and unclassified network boundaries.
Consumption patterns are tilting toward usage-based licensing as buyers reject perpetual seat models that mismatch actual traffic volumes. SaaS delivery of load balancing control planes is displacing self-managed software deployments in mid-market enterprises. This shift is most pronounced in North American technology and media verticals where platform engineering headcount constraints favor managed service abstractions.
Load Balancing Software Market Segmentation
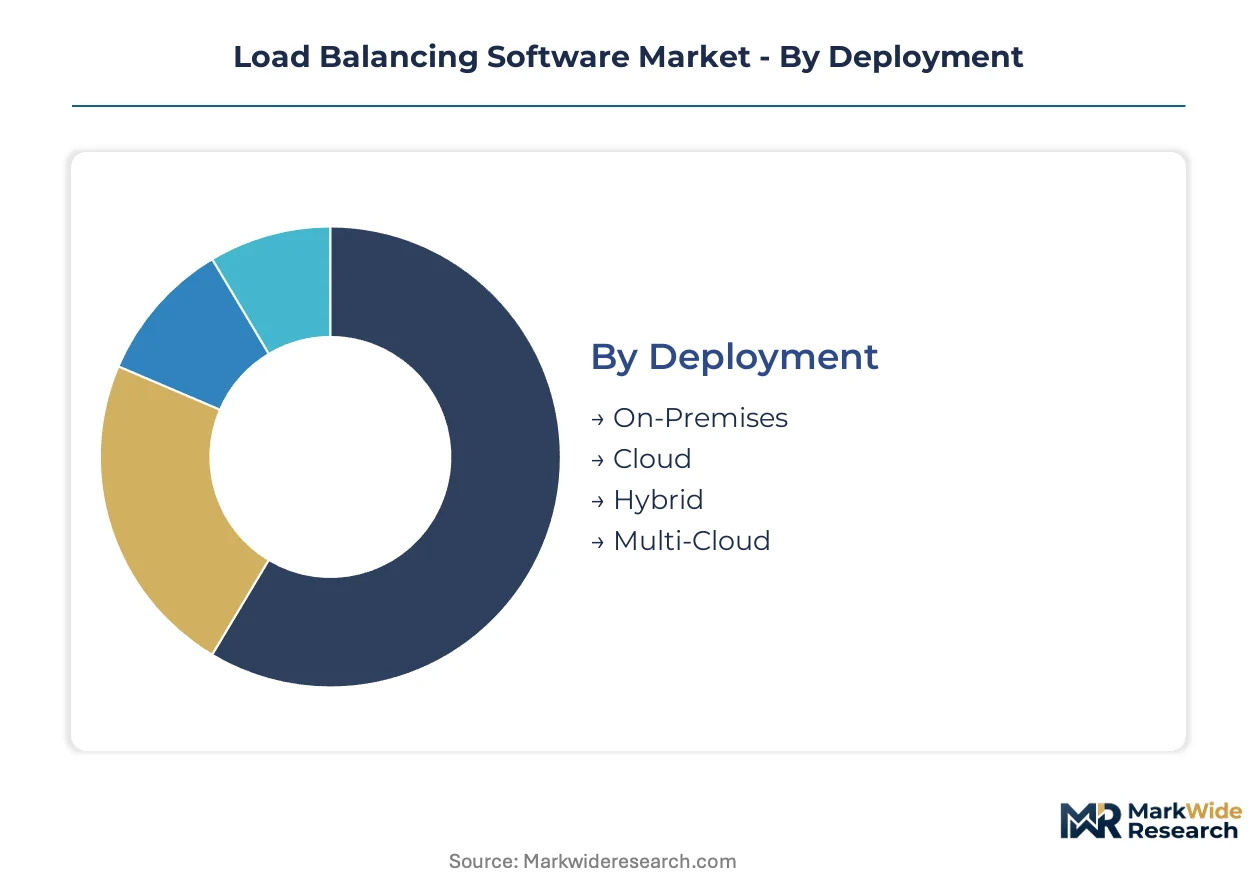
Load balancing software procurement follows distinct technical and operational logic across deployment modes, product architectures, and buyer categories. Segmentation reveals where infrastructure budgets concentrate and which technology transitions command premium pricing.
Deployment:
Customization intensity varies sharply across deployment modes, with cloud-native implementations offering API-driven configurability while on-premises retains deep hardware integration requirements.
- Cloud:Fully managed control planes eliminate infrastructure ownership, with consumption scaling to traffic volume. Financial services operators in the United States favor this model for FedRAMP-authorized environments where shared responsibility frameworks reduce compliance overhead.
- On-Premises:Self-managed software deployed on owned or leased hardware maintains data sovereignty and deterministic latency. Defense contractors and classified network operators require this mode for air-gapped environments where external connectivity is prohibited.
- Hybrid:Split traffic management across owned data centers and public cloud zones. Enterprises with decade-old data center investments use this bridge architecture during multi-year cloud migration programs.
- Multi-Cloud:Abstraction layers normalize routing policies across AWS, Azure, and Google Cloud. Platform engineering teams at technology companies adopt this to prevent vendor lock-in and enable failover across provider boundaries.
Most installed capacity flows through Cloud deployments. Expansion is steepest in Multi-Cloud configurations.
Product Type:
Margin profiles diverge based on feature integration depth, with traffic management converging toward security and analytics bundling at the premium tier.
- Application Delivery Controller:Integrated platforms combining load balancing with web application firewall, SSL offloading, and traffic analytics. Banking and payment processors deploy these for PCI-DSS compliance and transaction latency optimization.
- Local Traffic:Data center-centric distribution across server pools within single geographic zones. Manufacturing and logistics enterprises rely on this for ERP system resilience where global distribution is unnecessary.
- Global Traffic:Geographic routing decisions based on user proximity, data residency requirements, and real-time health status. Streaming media platforms use this to direct viewers to optimal origin servers.
- DNS Load Balancer:Authoritative DNS responses steering requests before connection establishment. Content delivery networks deploy this for sub-50ms failover when origin data centers become unreachable.
Application Delivery Controller captures the deepest margin pools. DNS Load Balancer is climbing the fastest as edge computing architectures proliferate.
End User:
Procurement sophistication scales with internal platform engineering headcount and regulatory exposure.
- Enterprises:Fortune 500 corporations with dedicated infrastructure teams managing hybrid estates. Retail and healthcare verticals drive demand for identity-aware traffic routing integrated with zero-trust architectures.
- Service Providers:Telecommunications carriers and managed service providers delivering load balancing as a resale or bundled offering. These buyers prioritize API programmability and multi-tenant isolation capabilities.
- Government:Civilian agencies and defense departments with NIST SP 800-207 zero-trust mandates. FedRAMP authorization and FIPS 140-2 cryptographic certification are non-negotiable procurement filters.
- Educational Institutions:Universities and research consortia with variable traffic patterns tied to academic calendars. These buyers favor open-source proxies and community-supported implementations to stretch limited IT budgets.
Enterprises account for the largest installed base. Government procurement is gaining share fastest as federal zero-trust deadlines approach.
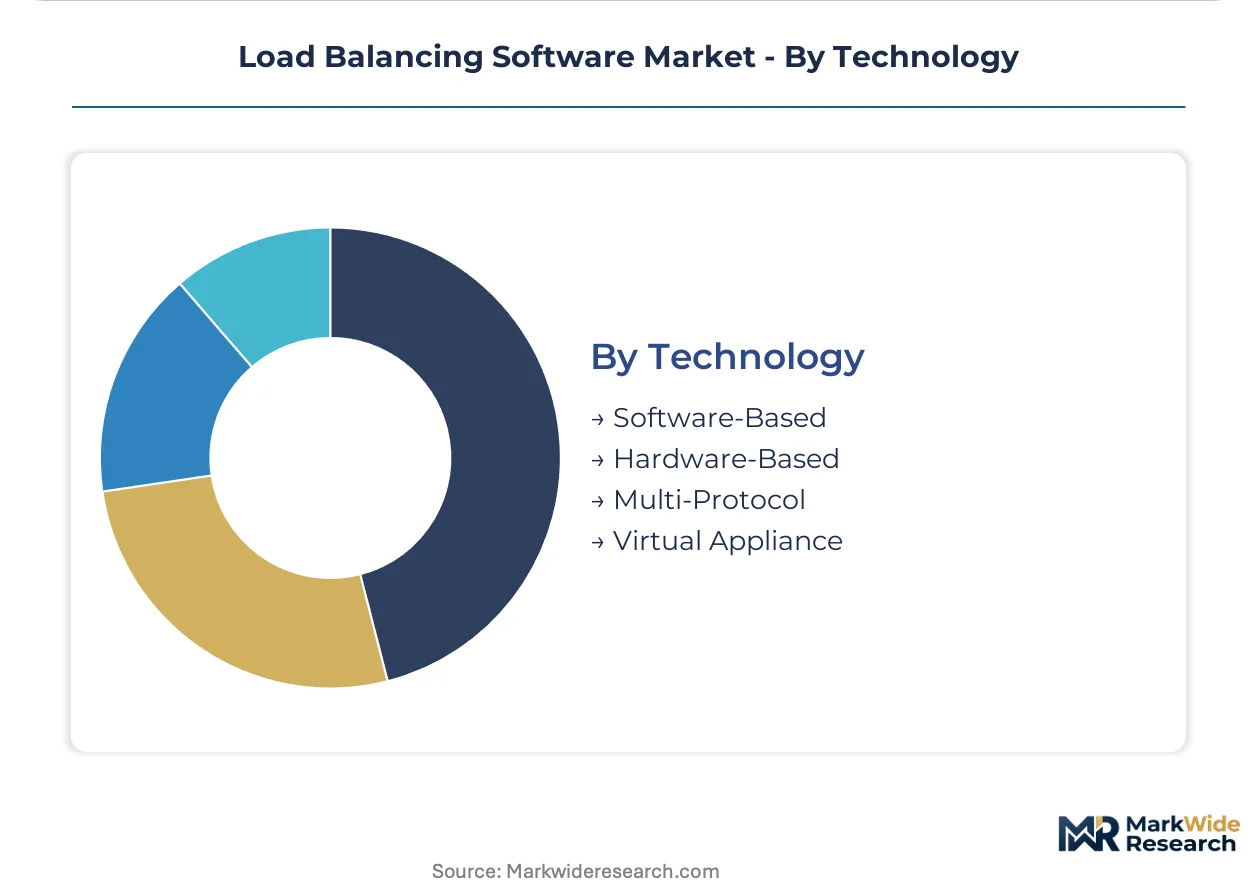
Technology:
Hardware abstraction levels determine capital efficiency and operational velocity.
- Software-Based:Disaggregated code running on commodity x86 or ARM servers. Kubernetes-native implementations using Envoy or NGINX dominate new deployments at technology companies prioritizing infrastructure-as-code workflows.
- Hardware-Based:Proprietary appliances with custom ASICs for cryptographic and packet processing acceleration. Regulated utilities and telecommunications incumbents maintain these for deterministic throughput in legacy operational environments.
- Multi-Protocol:Unified handling of Layer 4 TCP/UDP and Layer 7 HTTP/HTTPS/gRPC traffic within single policy frameworks. Microservices architectures require this for service mesh east-west communication patterns.
- Virtual Appliance:Pre-packaged software images certified for VMware, KVM, or Hyper-V hypervisors. Enterprises with existing virtualization estates use this for rapid deployment without bare-metal provisioning cycles.
Software-Based technology holds the majority position. Multi-Protocol implementations are expanding most quickly as container orchestration standardizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors worldwide load balancing software procurement through hyperscaler headquarters density and venture-backed infrastructure startups. Federal zero-trust mandates and EU operational resilience directives are redrawing procurement specifications across major economies. Cloud-native adoption rates diverge sharply between established data center markets and emerging digital infrastructure zones.
United States
NIST zero-trust architecture deadlines and FedRAMP authorization requirements drive federal agency procurement of identity-aware traffic management platforms. The Cybersecurity and Infrastructure Security Agency mandates continuous verification for civilian network boundaries. Seattle hosts AWS's global edge networking division, where load balancing services integrate with 5G distributed cloud zones.
Germany
Industrial automation conglomerates in Baden-Württemberg deploy redundant software-defined traffic management for smart manufacturing resilience. The EU NIS2 Directive imposes strict operational continuity requirements on critical infrastructure operators. Frankfurt's financial services cluster anchors continental demand for low-latency application delivery controllers.
India
The PLI scheme for data center infrastructure attracts hyperscaler investment, creating localized demand for domestic data residency compliance. TRAI regulations on data localization shape enterprise procurement specifications for traffic management software. Bengaluru's technology corridor hosts platform engineering teams standardizing on Kubernetes-native service mesh architectures.
United Kingdom
Financial services regulators in London mandate operational resilience testing for payment system operators under PRA supervision. The National Cyber Security Centre publishes zero-trust implementation guidance for critical national infrastructure. The Thames Valley enterprise cluster drives hybrid cloud load balancing adoption during multi-year data center consolidation programs.
Japan
METI's digital infrastructure investment programs accelerate cloud migration among manufacturing keiretsu networks. The country's national cybersecurity regulator enforces traffic segmentation standards for critical industrial control systems. Tokyo's financial district hosts domestic payment processors deploying multi-protocol load balancing for real-time settlement systems.
Load Balancing Software Market Vendor Landscape
Global majors compete with regional champions across cloud-native specialization and legacy enterprise retention. The vendor base stratifies between hyperscaler-integrated platforms, open-source proxy distributors, and hardware heritage players pivoting to software subscriptions. Three archetypes dominate: cloud-native specialists, legacy appliance incumbents with hybrid portfolios, and hyperscaler-captive service divisions. Consolidation pressure intensifies through strategic partnerships between identity providers and traffic management vendors, plus technology licensing arrangements that embed proxy capabilities into broader platform suites.
Within the open-source-native tier, NGINX and HAProxy Technologies exemplify community-driven distribution models that platform engineering teams adopt for infrastructure-as-code workflows. F5 anchors the legacy-transition archetype through its BIG-IP platform heritage and enterprise loyalty programs. AWS, Microsoft, and Google occupy the hyperscaler-captive tier, where load balancing services tighten integration with identity, compute, and edge networking stacks. These three groupings represent fundamentally different commercialization approaches rather than direct substitution competitors.
| Leading Market Players |
|---|
| F5 |
| A10 Networks |
| Citrix Systems |
| NGINX |
| HAProxy Technologies |
| IBM |
| Microsoft |
| AWS |
| Others |
Supply Flow & Price Mechanics
Specialized engineering talent costs cascade through load balancing software pricing tiers as platform engineering expertise commands salary premiums exceeding forty percent above general DevOps bands. This labor input concentrates in the United States and Germany, feeding into subscription pricing for managed control planes while compressing margins for self-managed software deployments.
Pricing Analysis
Input-cost pass-through from engineering talent scarcity shapes SaaS-tiered subscription models as the dominant pricing structure. Price differentiation rests on FedRAMP authorization tier and geographic data residency compliance. Pricing pressure stems from hyperscaler-native services embedding load balancing at marginal cost within compute bundles. Mid-market enterprises exhibit highest price sensitivity, while defense contractors and financial services operators accept premium tiers for deterministic compliance.
Supply Chain Analysis
Input dependency on ARM-based commodity server silicon rests on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity in Taiwan and South Korea. Software distribution draws from upstream kernel development in the United States and open-source proxy communities in Europe. Single-source vulnerability concentrates in advanced node fabrication for cryptographic acceleration hardware. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Load balancing software functions as a stable compounder where cloud-native infrastructure mandates drive steady procurement expansion across regulated industries and digital-native enterprises alike.
For Market Incumbents: Lock in enterprise loyalty through hybrid cloud portability certifications that bridge decade-old hardware estates to Kubernetes-native control planes. Deepen API programmability investments to counter hyperscaler lock-in risks that threaten multi-cloud customer retention. Prioritize FedRAMP authorization maintenance as federal zero-trust deadlines concentrate government procurement authority. For New Entrants and Emerging Players: Launch via open-source distribution models targeting platform engineering teams at Fortune 500 retailers and payment processors standardizing on Envoy Proxy. White-space concentrates in FinOps tooling integration for real-time traffic cost allocation. India PLI scheme incentives create penetrable entry points for domestic data residency compliance offerings. For Investors and Strategic Acquirers: Consolidation pressure builds where identity-aware proxying converges with continuous authorization verification, bundling opportunities with Okta and Microsoft Entra. Long-term viability favors vendors with Kubernetes-native service mesh architectures over hardware heritage transitions. Watch hyperscaler edge expansion into 5G zones as inflection indicator for hybrid cloud management tool demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Envoy Proxy unification of ingress and service mesh traffic consolidates previously separate procurement streams. |
| Strategic Partnership | Identity provider alliances embed continuous verification into traffic routing decisions for zero-trust compliance. |
| Geographic Expansion | India PLI scheme localization addresses TRAI data residency mandates for hyperscaler investment attraction. |
| Product Launch | eBPF kernel implementations enable line-rate traffic inspection on commodity x86 without ASIC dependency. |
| Acquisition of Specialist Firm | FinOps tooling targets address cloud cost visibility gaps plaguing platform engineering headcount-constrained teams. |
Methodological Framework
Direct dialogue with platform engineering directors, cloud infrastructure procurement officers, federal system integrators, and open-source community maintainers grounds qualitative findings. Secondary validation draws from hyperscaler capex disclosures, SEC 10-K infrastructure software segments, NIST zero-trust implementation guidance, and EU NIS2 Directive compliance documentation. Bottom-up deployment estimates triangulate against top-down infrastructure spending projections.
Segment-level outputs across deployment mode, product architecture, organization size, and regional regulatory cluster feed aggregate market sizing. CAGRs derive from infrastructure refresh cycle compression rates and container orchestration adoption curves. Modeled inputs include Kubernetes cluster growth trajectories, federal procurement authorization timelines, and hyperscaler edge zone expansion announcements.
Several conditions sit outside the modeled scope, including sovereign cloud fragmentation beyond documented national certification requirements and quantum-resistant cryptographic standard transitions. Forecasts reflect assumptions about engineering talent availability and hyperscaler pricing discipline. A small set of named triggers warrants ongoing watch: eBPF mainstream adoption velocity, EU AI Act enforcement precedence, and ARM server throughput parity milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Tag Management Software Market
Software & Services
Business Productivity Software Market
Software & Services
Storyboarding Software Market
Software & Services
Courier Software Market
Software & Services
Video Communications Software Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Global Technical Illustration Software Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Embedded Software Market
Software & Services
Yacht Management Software Market
Software & Services
Specification Management Software Market
Software & Services
Collaboration Tools Market
Software & Services
Category Management Software Market
Software & Services
Marketing Automation Software Market
Software & Services
United Kingdom HR Payroll Software Market