
 Cloud Load Balancers Market | 2026-2036
Cloud Load Balancers Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Load Balancers Market Outlook
Software-defined networking silicon is restructuring cloud load balancer economics as merchant NICs and SmartNICs displace proprietary ASICs in hyperscale data centers. AWS leverages its Nitro architecture to sustain hardware-level traffic offloading at commodity cost points. Google Cloud competes through custom TPU-linked load balancing for AI inference workloads. F5 Networks anchors enterprise demand with appliance-to-software transitions that preserve existing policy frameworks.
Cloud load balancers distribute incoming application traffic across multiple compute instances to prevent single points of failure and optimize resource utilization, typically operating at Layer 4 (transport) or Layer 7 (application) of the OSI model with throughput ratings from 1 Gbps to 100+ Tbps in hyperscale configurations. Their primary commercial purpose is ensuring service availability and responsive user experiences for mission-critical web applications, APIs, and streaming services. Public cloud deployment dominates volume, though hybrid cloud configurations capture disproportionate margin as enterprises maintain on-premises sovereignty for regulated workloads. Web traffic management leads application segments by installed base, while API management represents the fastest-expanding category driven by microservices architecture proliferation.
FCC net neutrality rulings in the United States shape how cloud providers structure interconnection and traffic prioritization services, while GDPR and the EU AI Act in Europe mandate data residency controls that localize load balancer placement. ISO 27001 and SOC 2 Type II certifications function as de facto market access requirements for vendors serving financial services and healthcare verticals. Stakeholders must monitor how NIST post-quantum cryptography standards will force TLS termination hardware upgrades across existing load balancer fleets.
Market Dynamics
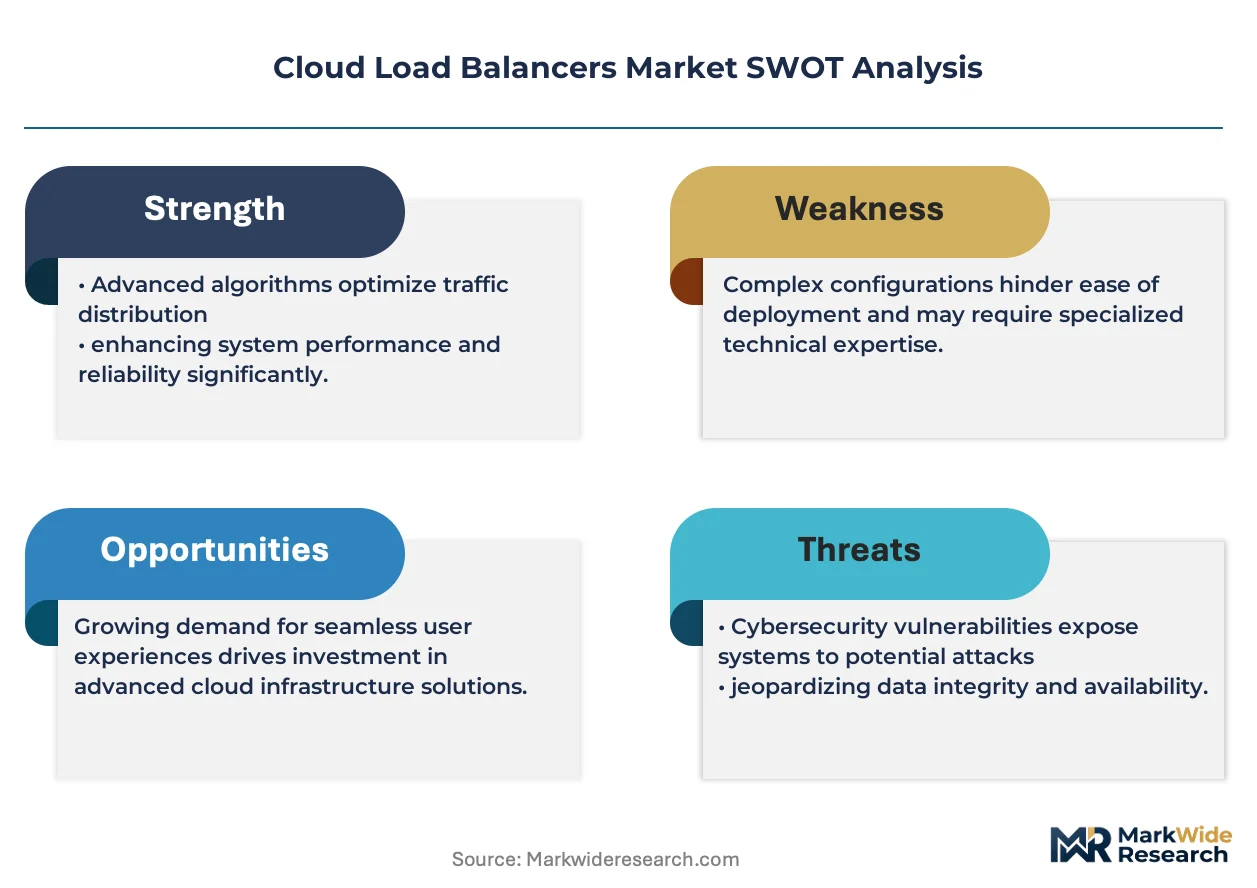
Merchant silicon commoditization is compressing hardware margins and forcing vendors toward software-defined load balancing architectures that decouple control planes from data plane acceleration.
Growth Catalysts
- EU AI Act compliance mandates:Enterprises across Germany, France, and the Netherlands are deploying sovereign cloud load balancers to localize traffic management and satisfy data residency requirements for AI inference workloads.
- High-frequency trading infrastructure:Financial services firms in London and Frankfurt are adopting sub-millisecond latency load balancing to support algorithmic execution platforms.
- SmartNIC hardware acceleration:Merchant NICs with programmable data planes are displacing proprietary ASICs in hyperscale data centers, reducing capital intensity for traffic management infrastructure.
Market Restraints
- TLS certificate complexity:NIST post-quantum cryptography standards will force hardware refresh cycles across existing load balancer fleets, straining enterprise IT budgets.
- Hyperscale cloud concentration:AWS, Google Cloud, and Microsoft Azure control the majority of public cloud load balancer deployments, limiting vendor diversification options.
- Skills gap in service mesh integration:Enterprise IT teams lack proficiency in Kubernetes-native ingress controllers and Istio-based traffic management.
Strategic Opportunities
- Industrial automation in Germany:Automotive and manufacturing cloud workloads require localized load balancing with deterministic latency guarantees.
- API management convergence:Microservices architecture proliferation is creating demand for Layer 7 load balancers with integrated rate limiting and authentication.
- Hybrid cloud sovereignty:GDPR and sector-specific regulations are driving margin-rich deployments that maintain on-premises control planes with cloud burst capacity.
Industry Challenges
- Legacy appliance migration:Enterprises with F5 and Citrix hardware estates face complex policy translation to cloud-native equivalents.
- Multi-cloud orchestration:Consistent traffic management across AWS, Azure, and Google Cloud requires abstraction layers that introduce operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Load Balancers Market |
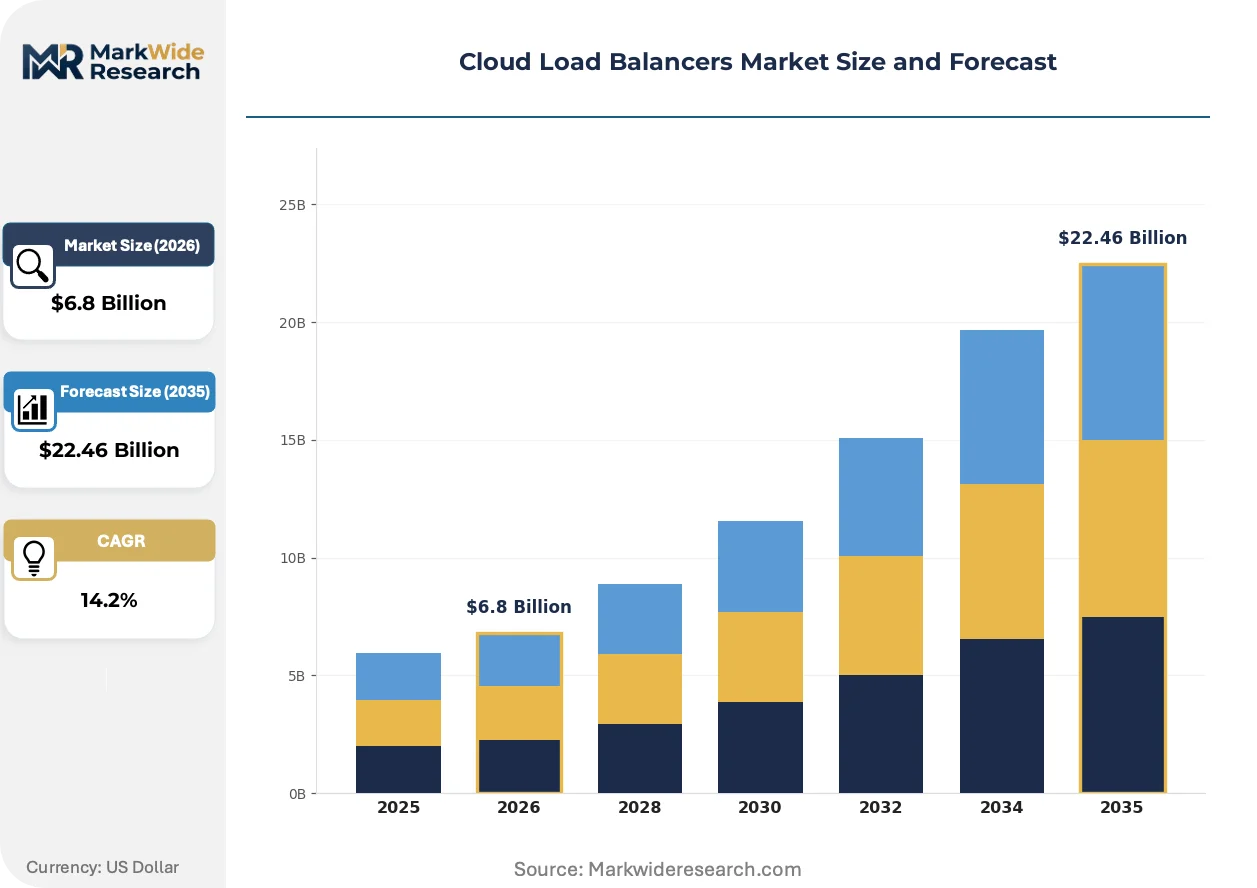
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Application: Web Traffic Management, API Management, Content Delivery, Data Streaming Service Type: Traffic Distribution, SSL Offloading, Health Monitoring, Auto-Scaling End User: SMEs, Large Enterprises, Government, E-Commerce |
| Companies Covered | Citrix, Radware, AWS, VMware, Loadbalancer.org, Microsoft Azure, A10 Networks, F5 Networks, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Load Balancers Market Strategic Shifts
Software-defined networking silicon is restructuring how traffic management functions are packaged and priced, with programmable hardware enabling new consumption models.
eBPF-based data plane acceleration is expanding into cloud-native load balancing stacks. Kubernetes platform teams at SaaS providers and fintechs are adopting Cilium and similar projects for kernel-level traffic routing. This technology is expanding into observability and security adjacencies, compressing the addressable market for standalone appliance vendors.
The EU AI Act and GDPR are mandating data residency controls that localize load balancer placement. European enterprises must maintain traffic processing within jurisdictional boundaries. Financial services and healthcare verticals in Germany and France are responding with sovereign cloud deployments that prioritize on-premises control planes.
Consumption-based pricing is displacing perpetual licensing for enterprise load balancing. Infrastructure teams are shifting from capital-intensive hardware procurement to metered cloud services. This pattern is most visible among mid-market SaaS providers in the United States and digital-native enterprises in India.
Cloud Load Balancers Market Segmentation
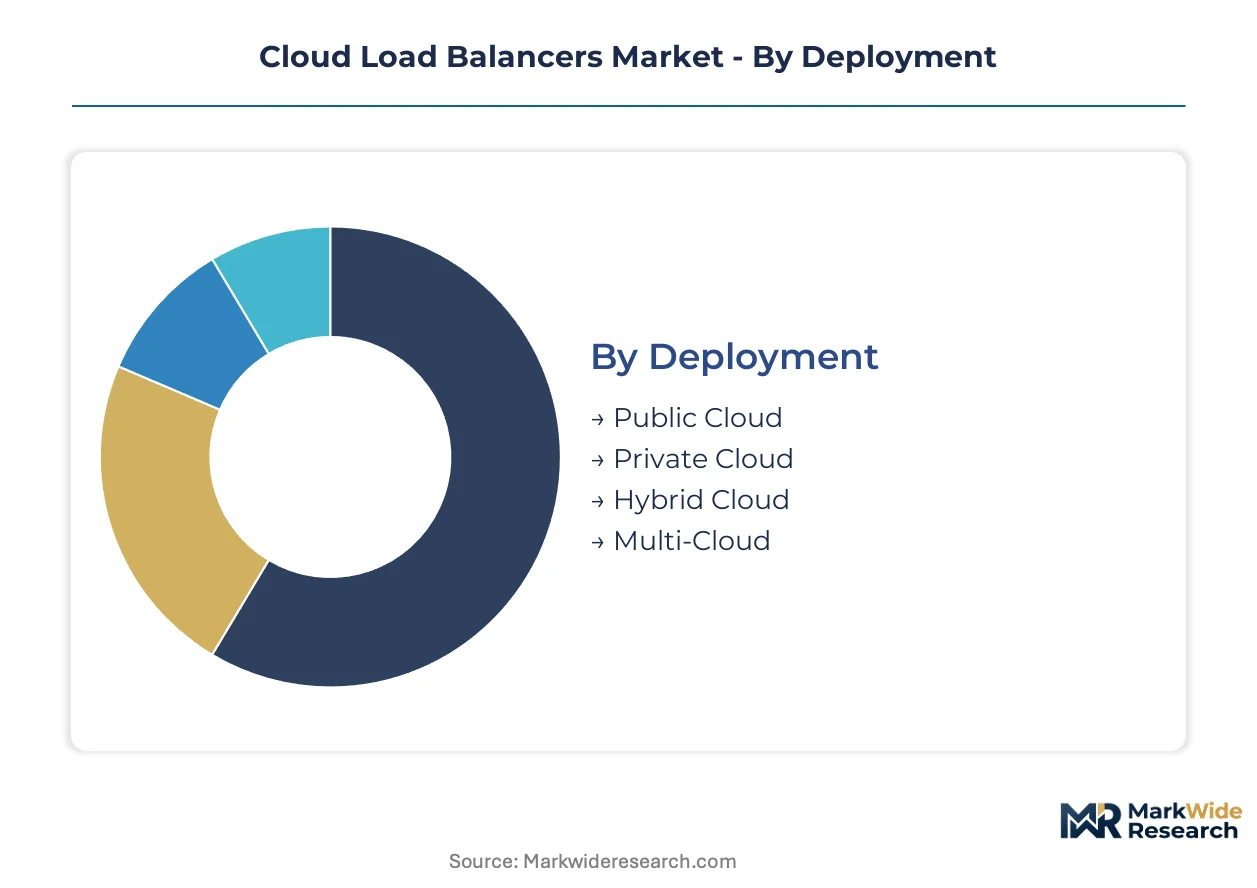
Cloud load balancer procurement patterns diverge sharply between cost-optimized volume deployments and premium sovereignty configurations. Understanding these splits reveals where vendor margins concentrate and which architectural choices enterprises prioritize under regulatory pressure.
Deployment:
Public cloud captures volume throughput while hybrid and multi-cloud deployments command premium pricing through sovereignty guarantees.
- Public Cloud:Hyperscale providers operate Layer 4 and Layer 7 load balancing at commodity cost points through merchant silicon architectures. Demand concentrates among SaaS providers in the United States and digital-native enterprises in India seeking elastic burst capacity without capital expenditure.
- Hybrid Cloud:Enterprises maintain on-premises control planes for regulated workloads while bursting to public cloud during traffic spikes. Financial services firms in Germany and healthcare providers in France prioritize this architecture to satisfy GDPR data residency mandates while preserving operational flexibility.
- Private Cloud:Dedicated infrastructure serves classified government workloads and defense-adjacent applications with air-gapped traffic management.
- Multi-Cloud:Distributed architectures spanning AWS, Azure, and Google Cloud require abstraction layers that introduce operational complexity but prevent vendor lock-in.
Mature deployment sits with Public Cloud. Newer deployment is concentrated in Hybrid Cloud.
Application:
Web traffic management dominates installed base while API management expands fastest through microservices proliferation.
- Web Traffic Management:Traditional Layer 7 load balancing for e-commerce portals and media streaming platforms. Retailers in Germany and broadcasters in the United Kingdom drive sustained demand for sub-second failover guarantees during peak traffic events.
- API Management:Ingress controllers and service mesh integration for containerized microservices architectures. Fintechs in Singapore and logistics platforms in the Netherlands are expanding deployments to handle millions of concurrent API calls with integrated rate limiting and authentication.
- Content Delivery:Geographic distribution of static assets through edge-integrated load balancing reduces latency for video streaming and software downloads.
- Data Streaming:Real-time traffic distribution for IoT telemetry and financial market data feeds requiring deterministic latency bounds.
Established revenue sits with Web Traffic Management. Steepest expansion trajectory belongs to API Management.
Service Type:
Traffic distribution functions commoditize while SSL offloading and auto-scaling retain differentiation through hardware acceleration requirements.
- Traffic Distribution:Core Layer 4 round-robin and least-connections algorithms. Basic functionality is now native to Kubernetes ingress controllers and hyperscale managed services, compressing standalone vendor pricing.
- SSL Offloading:TLS termination at the load balancer layer to preserve compute instance resources. Financial exchanges in Frankfurt and healthcare data platforms in Switzerland require hardware-accelerated cryptographic processing to handle post-quantum cryptography transitions without latency degradation.
- Health Monitoring:Continuous endpoint availability checking with automated failover orchestration. Manufacturing IoT deployments in Stuttgart and autonomous vehicle simulation platforms in Munich demand deterministic failure detection intervals.
- Auto-Scaling:Dynamic backend pool expansion based on real-time throughput metrics and predictive traffic forecasting.
Commoditized service delivery sits with Traffic Distribution. Premium differentiation concentrates in SSL Offloading.
End User:
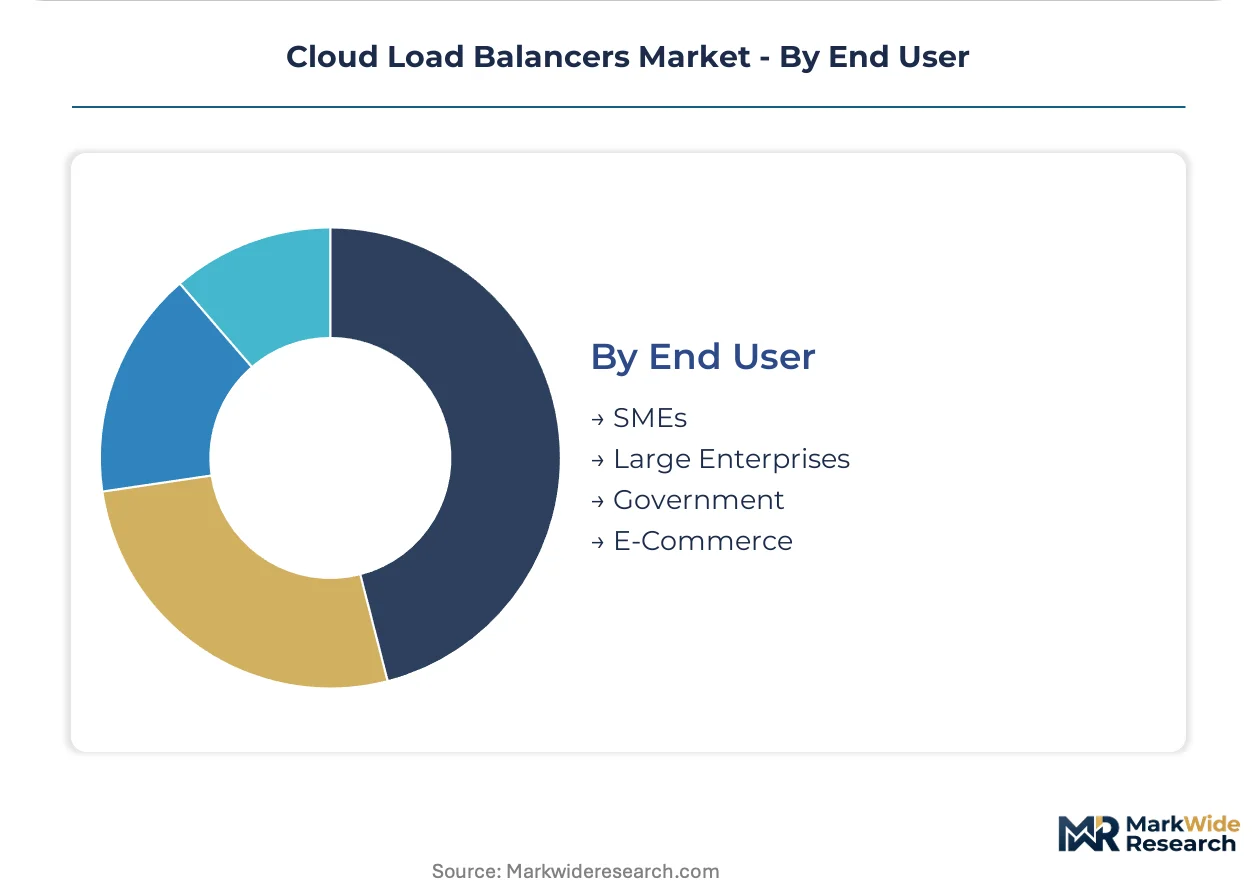
Large enterprises anchor revenue through complex multi-site deployments while SMEs shift fastest to consumption-based models.
- Large Enterprises:Global financial institutions and automotive manufacturers operating distributed application estates across multiple jurisdictions. German automotive OEMs require synchronized load balancing across production facilities in Wolfsburg, Ingolstadt, and Stuttgart with unified policy enforcement.
- SMEs:Mid-market SaaS providers and regional e-commerce platforms adopting metered cloud load balancing to avoid hardware procurement cycles. Indian software vendors and Brazilian fintechs are expanding managed service consumption fastest.
- Government:Sovereign cloud mandates drive classified workload deployments with air-gapped traffic management and domestic encryption key custody.
- E-Commerce:Seasonal traffic volatility requires elastic load balancing with pre-positioned capacity for promotional events.
Complex legacy integration sits with Large Enterprises. Cloud-native adoption is expanding fastest among SMEs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Mainhattan financial district concentrates European cloud infrastructure investment through tax-advantaged data center zones. German sovereign cloud deployments anchor regional demand for localized traffic management. The EU AI Act accelerates jurisdictional load balancer placement across member states.
Germany
Automotive cloud workloads from BMW and Volkswagen drive demand for sub-millisecond latency guarantees in production facilities. The EU AI Act mandates data residency controls that localize AI inference traffic processing. Stuttgart's manufacturing IoT clusters require deterministic load balancing for autonomous vehicle simulation platforms.
United States
SaaS providers in Silicon Valley and Seattle seek elastic burst capacity without capital expenditure for seasonal traffic spikes. FCC net neutrality rulings shape how AWS and Google Cloud structure interconnection services. New York's high-frequency trading firms deploy hardware-accelerated TLS termination for algorithmic execution platforms.
United Kingdom
London's financial services sector adopts cloud-native load balancing for high-frequency trading infrastructure. GDPR compliance requirements push enterprises toward sovereign cloud deployments with localized traffic management. Broadcasters in Manchester and Bristol demand sub-second failover guarantees during peak streaming events.
France
Healthcare data platforms in Paris and Lyon require hardware-accelerated cryptographic processing for patient record systems. The EU AI Act and GDPR mandate traffic processing within French jurisdictional boundaries. Sophia Antipolis technology park anchors fintech API management deployments with integrated rate limiting.
India
Digital-native enterprises in Bangalore and Hyderabad expand managed service consumption fastest among mid-market SaaS providers. The country's central bank guidelines shape financial services cloud adoption patterns. Mumbai's fintech clusters drive API management expansion for millions of concurrent microservices calls.
Cloud Load Balancers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing volume throughput while enterprise appliance vendors defend premium sovereignty configurations. The vendor base concentrates around three strategic tiers: hyperscale platforms with merchant silicon architectures, legacy appliance vendors managing hardware-to-software transitions, and cloud-native specialists leveraging eBPF-based data plane acceleration. Dominant competitive moves include strategic partnerships between hardware acceleration vendors and Kubernetes platform providers, plus geographic expansion into Frankfurt and Singapore financial zones.
Among hyperscale cloud providers, AWS, Google Cloud, and Microsoft Azure exemplify the merchant silicon architecture tier that commoditizes basic traffic distribution. F5 Networks anchors the enterprise transition archetype, preserving existing policy frameworks as customers migrate from hardware appliances to software-defined deployments.
| Leading Market Players |
|---|
| Citrix |
| Radware |
| AWS |
| VMware |
| Loadbalancer.org |
| Microsoft Azure |
| A10 Networks |
| F5 Networks |
| Google Cloud |
| Others |
Value Chain & Pricing Dynamics
Merchant silicon vertical integration anchors both supply positioning and pricing power in cloud load balancing, as AWS Nitro and Google Cloud TPU-linked architectures displace proprietary ASICs and compress hardware margins across the vendor base.
Pricing Analysis
Volume throughput commoditizes while sovereignty configurations retain premium pricing. Public cloud providers deploy Layer 4 and Layer 7 load balancing through merchant NIC architectures at economy tiers, whereas hybrid cloud deployments with GDPR-compliant data residency command standard-to-premium spreads based on certification level and jurisdictional guarantee. Pricing pressure stems from SmartNIC hardware acceleration reducing capital intensity for hyperscale traffic management. Mid-market SaaS providers in India exhibit highest price sensitivity, while German automotive OEMs prioritize deterministic latency over cost optimization.
Supply Chain Analysis
Specialized engineering talent availability in Taiwan, South Korea, and the United States constrains programmable data plane silicon production for cloud-native load balancing. Supply chains draw from merchant semiconductor foundries, FPGA programmable logic suppliers, and TLS acceleration chip vendors. Single-source vulnerability concentrates in advanced node fabrication for SmartNIC controllers. Distribution runs through hyperscale cloud direct procurement, enterprise VAR channels, and managed service provider aggregations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud load balancer supply remains constrained by qualified SmartNIC engineering capacity, with merchant silicon fabrication bottlenecks propping pricing for hardware-accelerated sovereignty configurations.
For Market Incumbents: Hedge against eBPF-based data plane displacement by deepening Kubernetes platform partnerships and securing ISO 27001 certifications for financial services verticals. Prioritize policy translation tools that preserve F5 Networks customer configurations during appliance-to-software migrations. Capacity addition in Frankfurt and Singapore financial zones defends margin position against hyperscale cloud commoditization. For New Entrants and Emerging Players: Sovereign cloud providers in Germany and France represent underserved buyer archetypes seeking localized traffic management with EU AI Act compliance guarantees. Target mid-market manufacturing IoT deployments in Stuttgart and Munich requiring deterministic latency bounds. Pursue channel partnerships with industrial automation systems integrators as primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale cloud platform acquisitions of eBPF-native traffic management specialists. Long-term viability favors vendors with hybrid cloud orchestration capabilities spanning AWS, Azure, and Google Cloud abstraction layers. Watch NIST post-quantum cryptography standard implementation timelines as inflection indicator for TLS termination hardware refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| SmartNIC Hardware Partnership | AWS Nitro architecture integration secures commodity cost positioning for hyperscale deployments. |
| Sovereign Cloud Certification | GDPR and EU AI Act compliance enables premium pricing in German automotive and French healthcare verticals. |
| Kubernetes Platform Integration | Cilium eBPF adoption compresses addressable market for standalone appliance vendors. |
| Post-Quantum Cryptography Readiness | Hardware-accelerated TLS termination preserves latency performance through NIST transition period. |
| Industrial Automation Channel Expansion | Stuttgart manufacturing IoT clusters require deterministic load balancing with sub-millisecond failover guarantees. |
Study Parameters
Independent corroboration across hyperscaler capex disclosures, enterprise IT procurement surveys, and SmartNIC vendor technical specifications underwrites the qualitative findings. Primary interviews with cloud platform engineers, enterprise network architects, and financial services infrastructure leads combined with secondary validation from SEC 10-K filings, EU regulatory impact assessments, and Kubernetes ecosystem documentation. Bottom-up deployment volume estimates and top-down vendor revenue analysis triangulate market sizing.
Rate-of-change decomposition across the analysis window separates volume expansion in public cloud from value concentration in hybrid sovereignty configurations. Segmentation dimensions modeled include deployment architecture, application workload type, service tier, and end-user scale category. CAGRs derive from installed base growth rates, replacement cycle timing, and pricing trajectory assumptions. Forecast inputs incorporate EU AI Act implementation schedules and NIST post-quantum cryptography standard adoption curves.
Revisions become necessary when merchant silicon supply disruptions, hyperscale cloud pricing warfare, or regulatory enforcement delays materialize. Forecasts reflect documented assumptions regarding SmartNIC engineering capacity expansion and sovereign cloud procurement timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Distributed Cloud System Market
Cloud Computing
Global Cloud Business Email Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Cloud Identity Management Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
Cloud Microservices Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Brazil Cloud Computing Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Cloud Continuum Market