
 Decision Support System Market | 2026-2036
Decision Support System Market Size, Share, and Industry Trends Forecast 2026-2036
Decision Support System Market Intelligence
GDPR and the EU AI Act are recalibrating how vendors architect audit trails and explainability layers into decision support platforms. InRule Technology leverages its rules-engine heritage to anchor compliance-centric deployments in regulated European industries. Sparkling Logic sustains differentiation through visual decision-modeling interfaces that reduce time-to-deployment for business analysts. Tegus competes by extending expert-network data into quantitative decision workflows for investment and corporate strategy teams.
A decision support system integrates data repositories, analytical models, and user-facing interfaces to transform structured and unstructured information into actionable recommendations, typically operating through rule-based engines, optimization algorithms, or simulation frameworks that process inputs against predefined constraints and objectives. Healthcare Decision Making represents a structurally expanding segment as clinical protocols and patient-outcome targets tighten reimbursement incentives for evidence-based care choices. Artificial Intelligence commands the technology dimension where margin pools concentrate, though Cloud Computing sustains the broadest addressable base by lowering infrastructure barriers for mid-market adopters. Predictive Analytics leads the solution category in growth velocity as organizations prioritize forward-looking scenario evaluation over retrospective reporting.
FDA guidance on clinical decision support software shapes product classification and premarket pathways for healthcare-facing platforms in the United States. EMA and GDPR collectively determine how European vendors handle patient data and algorithmic transparency in life-sciences applications. The EU AI Act introduces risk-tiered conformity obligations that will filter market access for automated decision systems deployed in high-stakes domains. Stakeholders must monitor how rapidly diverging regulatory timelines across Washington, Brussels, and Beijing reshape development roadmaps and geographic prioritization for platform rollouts.
Market Dynamics
The EU AI Act's risk-tiered conformity framework is restructuring how vendors architect algorithmic transparency layers, forcing platform redesigns ahead of enforcement deadlines and recalibrating competitive positioning across European deployments.
Growth Catalysts
- Clinical protocol tightening:Reimbursement incentives for evidence-based care choices in the United States are expanding healthcare provider demand for diagnostic decision support tools. FDA guidance on clinical decision support software classification accelerates premarket pathway clarity.
- Industrial digitization mandates:Germany's manufacturing data integration programs are accelerating platform deployments among automotive and precision engineering clusters. Federal Ministry for Economic Affairs funding streams reduce adoption friction for mid-market producers.
- Cloud infrastructure maturation:Lowering compute barriers enables predictive analytics adoption among resource-constrained organizations. Managed service models displace on-premise capital expenditure requirements.
Market Restraints
- Algorithmic audit infrastructure costs:GDPR-mandated data lineage systems and explainability layer development impose sustained engineering overhead on European vendors.
- Specialized talent scarcity:Shortage of clinical informaticists and regulatory technologists capable of bridging healthcare workflows with compliance architecture limits deployment velocity.
- Legacy system entrenchment:Deep integration of incumbent electronic health record systems creates switching friction and extends sales cycles for replacement platforms.
Strategic Opportunities
- Explainable AI convergence:Integration of rule-engine heritage with neural interpretability techniques opens differentiated positioning for vendors serving regulated European industries under EU AI Act obligations.
- Simulation-as-a-service models:Cloud-native scenario evaluation tools penetrate mid-market manufacturing segments previously excluded by on-premise licensing economics.
- Expert network data monetization:Qualitative primary research workflows are being quantified and embedded into investment decision platforms, creating new revenue streams adjacent to traditional software licensing.
Industry Challenges
- Cross-border compliance fragmentation:Divergent regulatory timelines across Washington, Brussels, and Beijing force parallel development tracks and strain product management bandwidth.
- Interoperability standard delays:Incomplete FHIR implementation specifications and vendor-specific data formats impede seamless information exchange between healthcare decision support and source clinical systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decision Support System Market |
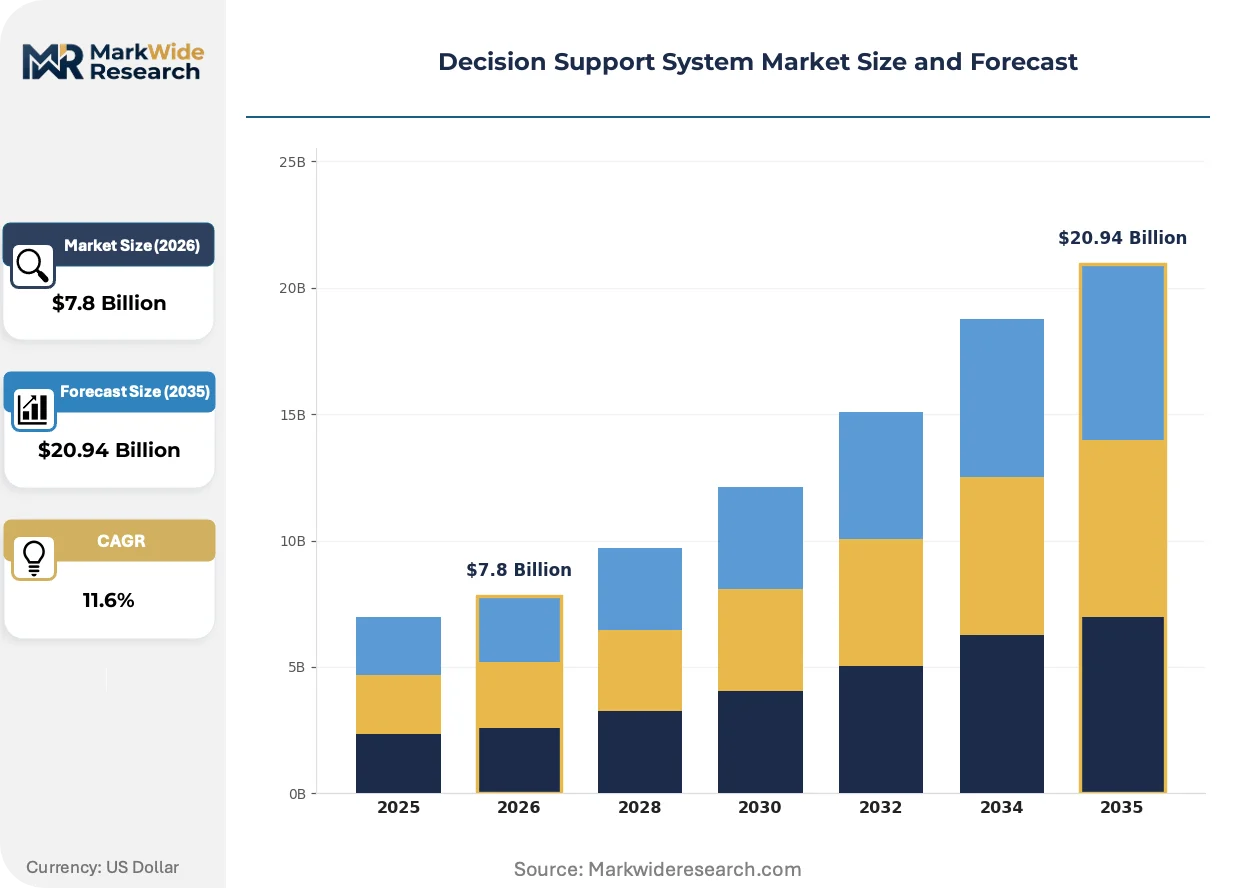
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.94 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Financial Planning, Risk Management, Supply Chain Optimization, Healthcare Decision Making Technology: Artificial Intelligence, Cloud Computing, Big Data Analytics, Machine Learning End User: Government Agencies, Corporate Enterprises, Healthcare Providers, Educational Institutions Solution: Business Intelligence, Predictive Analytics, Data Visualization, Reporting Tools |
| Companies Covered | Draup, 1000minds, InRule Technology, Visyond, GoldSim Technology Group, Tegus, Sparkling Logic, Paramount Decisions, Strata Decision Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decision Support System Market Strategic Shifts & Innovations
Federated learning architectures and edge-deployed inference engines are redistributing computational load away from centralized cloud infrastructure, enabling real-time decision support in latency-sensitive operational environments.
Edge computing is decentralizing analytical processing for manufacturing quality control and clinical point-of-care diagnostics. German automotive suppliers and Nordic hospital networks are deploying localized inference nodes at scale. This topology reduces data transmission costs and enables sub-second recommendation generation for time-critical decisions.
The EU AI Act's conformity assessment procedures are mandating documented risk management systems and post-market monitoring protocols for high-risk automated decision systems. Life-sciences platform vendors are restructuring quality management systems to accommodate notified body involvement. European healthcare deployments face the steepest compliance trajectory as classification criteria clarify through implementing acts.
Subscription pricing for decision support capabilities is displacing perpetual licensing in corporate finance and strategy functions. Chief financial officers are demanding operational expenditure treatment for analytics investments rather than capital allocation. This preference shift is most pronounced in United States private equity and consulting sectors where technology budgets face heightened scrutiny.
Decision Support System Market Segmentation
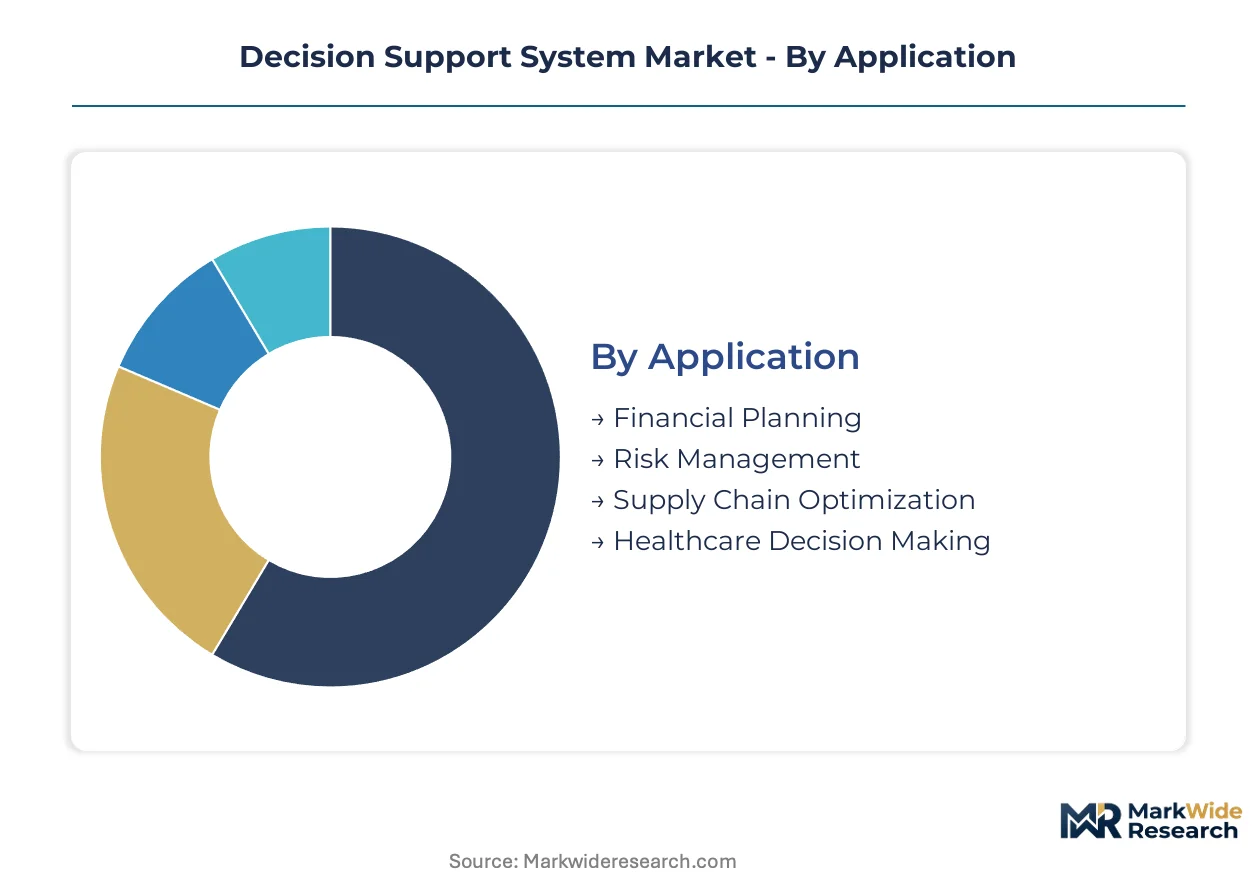
Decision support system architectures vary sharply across deployment contexts, with compliance requirements and data complexity dictating technology choices. Application-specific workflows drive divergent functional specifications, while end-user procurement sophistication determines pricing tolerance and service model preferences.
Application:
Volume concentrates in operational optimization use cases, while premium pricing attaches to regulated diagnostic environments where liability exposure elevates vendor qualification thresholds.
- Healthcare Decision Making:Clinical protocols and patient-outcome targets tighten reimbursement incentives for evidence-based care choices. FDA guidance on software classification accelerates premarket pathway clarity for diagnostic platforms in United States hospital systems.
- Supply Chain Optimization:Manufacturing data integration programs in Germany's automotive clusters accelerate deployment velocity. Federal Ministry for Economic Affairs funding streams reduce adoption friction for mid-market producers seeking real-time inventory and logistics orchestration.
- Financial Planning:Corporate finance functions demand operational expenditure treatment for analytics investments rather than capital allocation.
- Risk Management:Basel III operational risk frameworks and Solvency II requirements drive procurement in banking and insurance verticals.
Today's leader: Healthcare Decision Making. Tomorrow's challenger: Supply Chain Optimization.
Technology:
Cloud infrastructure sustains the broadest addressable base by lowering capital barriers, while artificial intelligence commands margin concentration through specialized talent requirements and differentiation potential.
- Artificial Intelligence:Neural interpretability techniques and rule-engine heritage converge to address EU AI Act transparency mandates. European life-sciences vendors restructure quality management systems for notified body involvement in high-risk automated decision systems.
- Cloud Computing:Managed service models displace on-premise capital expenditure requirements for resource-constrained organizations. Lower compute barriers enable predictive analytics adoption among mid-market adopters previously excluded by infrastructure economics.
- Big Data Analytics:Federated learning architectures redistribute computational load away from centralized infrastructure for latency-sensitive environments.
- Machine Learning:Edge-deployed inference engines enable sub-second recommendation generation for time-critical manufacturing quality control decisions.
Cloud Computing anchors current deployment scale. Artificial Intelligence captures the steepest expansion trajectory as explainability mandates reshape vendor roadmaps.
End User:
Procurement sophistication stratifies sharply, with government agencies demanding extensive compliance documentation and corporate enterprises prioritizing integration speed.
- Healthcare Providers:Deep integration of incumbent electronic health record systems creates switching friction and extends sales cycles for replacement platforms. Clinical informaticist scarcity limits deployment velocity for workflow-compliant architectures.
- Corporate Enterprises:Chief financial officers demand operational expenditure treatment for analytics investments. Subscription pricing displaces perpetual licensing in private equity and consulting sectors where technology budgets face heightened scrutiny.
- Government Agencies:GDPR-mandated data lineage systems and algorithmic audit infrastructure impose sustained engineering overhead on European vendors.
- Educational Institutions:Budget constraints favor open-source analytical frameworks over commercial platform licensing.
Healthcare Providers dominate current revenue concentration. Corporate Enterprises are gaining share fastest as subscription economics penetrate finance and strategy functions.
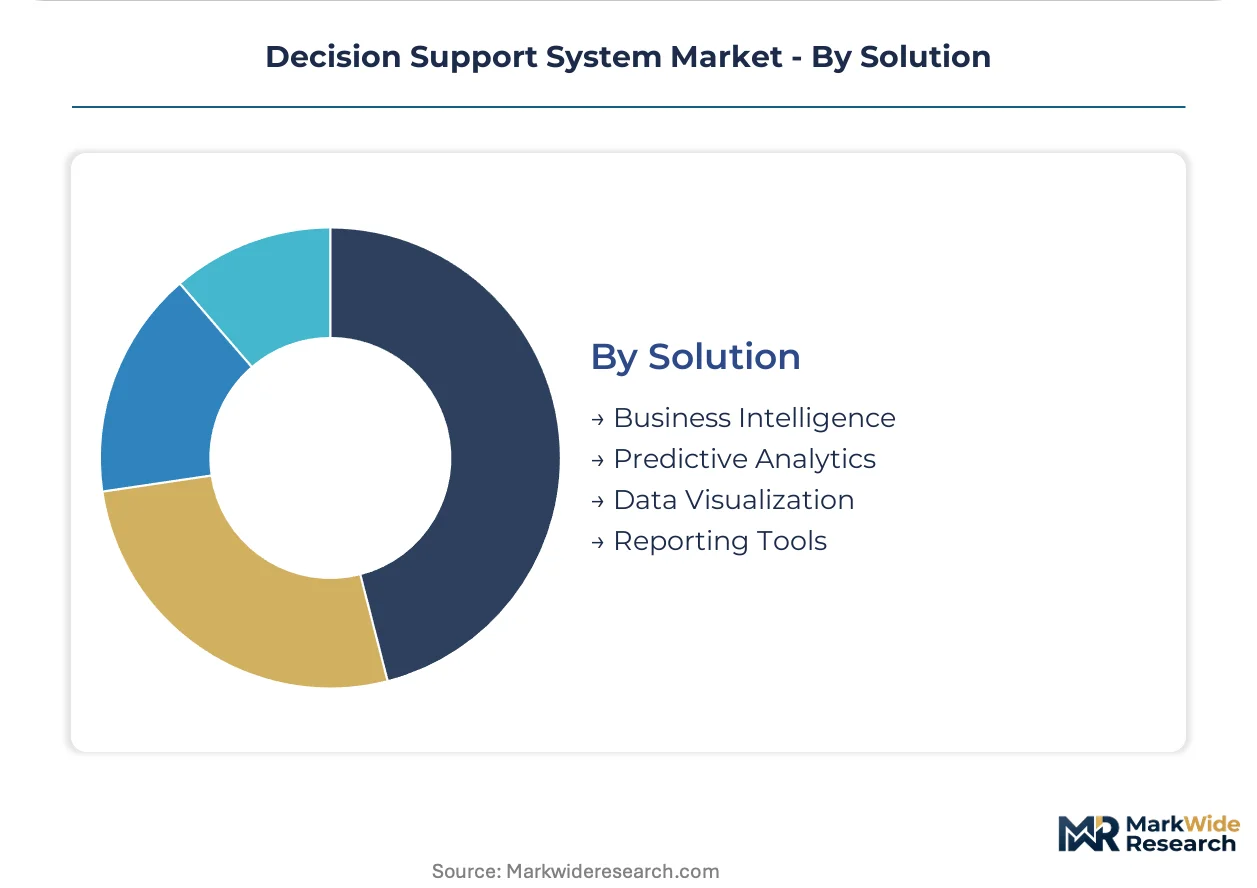
Solution:
Retrospective reporting capabilities represent mature, price-commoditized functionality, while forward-looking scenario evaluation commands premium positioning.
- Predictive Analytics:Forward-looking scenario evaluation prioritizes anticipatory decision frameworks over retrospective reporting. Organizations in United States private equity sectors embed quantitative expert-network data into investment workflows.
- Business Intelligence:Dashboard and reporting standardization across enterprise functions enables operational visibility. Incomplete FHIR implementation specifications impede seamless information exchange with source clinical systems in healthcare deployments.
- Data Visualization:Visual decision-modeling interfaces reduce time-to-deployment for business analysts without specialized programming expertise.
- Reporting Tools:Regulatory submission documentation and audit trail generation satisfy EMA and GDPR requirements for European life-sciences applications.
Business Intelligence holds installed base dominance. Predictive Analytics is climbing the fastest as simulation-as-a-service models penetrate manufacturing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical informaticists and regulatory technologists concentrate in jurisdictions with dense healthcare infrastructure and stringent algorithmic governance frameworks. Their geographic clustering shapes where decision support platforms achieve fastest deployment velocity and deepest compliance integration.
United States
Hospital systems in the United States are expanding procurement of diagnostic decision support tools as FDA guidance clarifies premarket pathways for clinical software. The FDA's risk-based classification framework for clinical decision support software accelerates product entry for lower-risk applications. Boston and San Francisco metropolitan areas host dense concentrations of health-tech startups building workflow-compliant architectures for academic medical centers.
Germany
Federal Ministry for Economic Affairs funding streams are reducing adoption friction for mid-market automotive and precision engineering producers seeking manufacturing data integration. The EU AI Act's risk-tiered conformity obligations are forcing platform redesigns ahead of enforcement deadlines. Stuttgart and Munich industrial clusters are deploying localized inference nodes for sub-second quality control decisions in automotive supply chains.
United Kingdom
Private equity and consulting sectors in London are driving subscription pricing displacement of perpetual licensing for analytics investments. Chief financial officers are demanding operational expenditure treatment for decision support capabilities under heightened technology budget scrutiny. The Financial Conduct Authority's operational resilience requirements are shaping procurement criteria for risk management platforms in banking and insurance verticals.
Japan
Manufacturing quality control workflows are accelerating edge-deployed inference engine adoption among automotive and electronics producers. METI's Society 5.0 digitization roadmap is channeling public-private investment into predictive maintenance and supply chain optimization platforms. Nagoya's Chubu industrial corridor and Osaka's Kansai manufacturing belt are prioritizing latency-sensitive decision support for time-critical production environments.
India
Budget-constrained healthcare providers and educational institutions are favoring open-source analytical frameworks over commercial platform licensing. The Ministry of Electronics and Information Technology's National Programme on Artificial Intelligence is seeding domestic capability in decision automation tools. Bangalore and Hyderabad technology corridors are incubating cost-optimized deployment models for resource-constrained mid-market adopters.
Decision Support System Market Key Industry Players
The competitive structure tilts toward specialized rules-engine heritage vendors and visual modeling interface providers rather than consolidated platform giants. Fragmentation persists across regulatory compliance, manufacturing optimization, and investment research verticals with limited cross-sector overlap. Two strategic archetypes dominate: compliance-centric European specialists architecting audit-ready transparency layers, and workflow-agnostic cloud-native tools penetrating mid-market segments through subscription economics. Dominant competitive moves include strategic partnerships with expert data networks and geographic expansion through notified body relationships for EU AI Act conformity.
Within the compliance-centric tier, InRule Technology and Sparkling Logic exemplify divergent architectural approaches to regulated European industries. InRule Technology, a U.S.-based vendor, anchors deployments where rules-engine heritage meets GDPR-mandated data lineage requirements. Sparkling Logic, also U.S.-based, occupies a position emphasizing visual decision-modeling interfaces that compress time-to-deployment for business analysts without specialized programming expertise. Tegus, another U.S.-based entity, represents the expert-network data monetization archetype, embedding qualitative primary research into quantitative investment workflows.
| Leading Market Players |
|---|
| Draup |
| 1000minds |
| InRule Technology |
| Visyond |
| GoldSim Technology Group |
| Tegus |
| Sparkling Logic |
| Paramount Decisions |
| Strata Decision Technology |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs cascade through decision support system pricing tiers, with hyperscaler compute fees compressing margins for SaaS vendors serving mid-market healthcare providers while enterprise deployments absorb premium transparency-layer engineering overhead.
Pricing Analysis
Subscription bundling separates fully managed decision support platforms from self-hosted licensing arrangements. Three-tier pricing structure across premium, standard, and economy levels differentiates by compliance certification depth and explainability layer sophistication. Price differentiation hinges on EU AI Act conformity documentation and FDA premarket pathway completion status. Cost compression in the standard tier is intensifying because cloud infrastructure commoditization erodes hardware-based margin protection. Corporate finance functions demonstrate highest price sensitivity, while government agencies tolerate premium positioning for audit-ready transparency architectures.
Supply Chain Analysis
Reverse-logistics flows for on-premise hardware refreshes are minimal in this software-dominant market, though edge-deployed inference node refurbishment cycles are emerging in German automotive clusters. Component sourcing concentrates in the United States, Ireland, and Singapore for cloud infrastructure. The supply chain draws from specialized GPU foundries, clinical informaticist labor pools, and regulatory technologist networks. Single-source vulnerability in neural interpretability talent constrains platform development velocity. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and system integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The decision support system market functions as a regulatory compounder where compliance architecture investments compound competitive moats. The EU AI Act's enforcement timeline is accelerating procurement cycles for audit-ready platforms.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by deepening rules-engine heritage differentiation and accelerating notified body relationships for high-risk system classification. Incumbents should anchor defensive positioning through vertical integration into clinical workflow compliance and channel control via EHR system partnerships. The emerging threat of simulation-as-a-service models demands preemption through platform unification. For New Entrants and Emerging Players: Capture white-space in mid-market manufacturing segments where Federal Ministry for Economic Affairs funding reduces adoption friction for predictive analytics platforms. The most penetrable geography is India, where budget-constrained healthcare providers favor open-source frameworks lacking commercial explainability layers. A direct-to-CFO subscription positioning bypasses IT procurement bottlenecks. For Investors and Strategic Acquirers: Roll-up economics work for compliance-centric European specialists because GDPR-mandated data lineage systems create sticky switching costs and recurring audit revenue streams. Long-term viability centers on vendors bridging rules-engine transparency with neural interpretability techniques. The signal to watch is notified body appointment velocity for EU AI Act high-risk system classification.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying rules-engine heritage with neural interpretability addresses EMA transparency mandates for life-sciences deployments. |
| Strategic Partnership | Expert-network data alliances embed qualitative research into quantitative investment workflows for private equity clients. |
| Geographic Expansion | Notified body relationships in Germany unlock EU AI Act conformity certification for high-risk automated decision systems. |
| Product Launch | Edge-deployed inference engines enable sub-second quality control recommendations in Stuttgart automotive supply chains. |
| Acquisition of Specialist Firm | Clinical informaticist teams accelerate FDA premarket pathway navigation for diagnostic decision support platforms. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with healthcare CIOs, clinical informaticists, regulatory affairs directors, and platform engineering leads with secondary validation against FDA guidance documents, EMA implementing acts, EU AI Act conformity assessment procedures, and hospital procurement databases. Bottom-up deployment estimates and top-down market sizing triangulated across cloud infrastructure spend disclosures and enterprise software licensing records.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning application context, technology architecture, deployment model, organization size, and regional regulatory cluster. CAGRs derived from adoption curve analysis and compliance deadline proximity effects. Forecast inputs incorporated EU AI Act enforcement trajectory and cloud infrastructure cost elasticity assumptions.
Regulatory timeline slippage, interoperability standard completion delays, and clinical informaticist supply constraints are the dominant revision risks for forecast assumptions. Practitioners should monitor EMA implementing act clarifications and FHIR specification finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Trade Management Software Market
Digital Solutions
Game Engines Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Product Prototyping Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Morocco ICT Market
Digital Solutions
Smart Government Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Business Information Market
Digital Solutions
Global Network Monitoring Software Market
Digital Solutions
Legal Technology Market
Digital Solutions
Barcode Software Market
Digital Solutions
Mobile Ticketing Market