
 Manufacturing Operations Management Solutions Market | 2026-2036
Manufacturing Operations Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing Operations Management Solutions Market Foresight
Mid-sized discrete manufacturers is rotating toward integrated MES-ERP suites as large automotive OEMs tighten supplier compliance requirements. Siemens dominates European heavy-industry deployments with its Opcenter platform, leveraging deep PLC integration to sustain switching-cost advantages. Rockwell Automation competes aggressively in North American automotive through its FactoryTalk portfolio, while SAP anchors enterprise-scale ERP-MES convergence for process industries seeking unified data architectures.
Manufacturing Operations Management Solutions encompass software systems that orchestrate production workflows, resource allocation, and quality assurance across factory floors and supply networks. These platforms integrate real-time machine data, inventory states, and labor schedules through ISA-95 compliant architectures to synchronize physical operations with enterprise planning systems. MES deployments within the Product Type segment command the deepest margin pools where shop-floor execution meets regulatory traceability, while Cloud-Based technology is displacing on-premise installations fastest among electronics contract manufacturers seeking elastic capacity. Quality Control applications in pharmaceuticals carry the highest compliance premium, though Production Planning modules generate the broadest cross-industry attach rates.
The US FDA enforces 21 CFR Part 11 electronic records standards that compel pharmaceutical and medical device manufacturers to validate MES audit trails, while the EU MDR intensifies batch-level traceability mandates across European production sites. Germany's BSI and France's ANSM coordinate national interpretations of harmonized standards, creating fragmented compliance costs for vendors serving multiple member states. Buyers must evaluate whether platform architectures can absorb pending EU AI Act risk-classification rules for automated quality-inspection modules without core-system replacement.
Market Dynamics
Cloud-native MES architectures are compressing deployment cycles from 18 months to under 90 days, forcing incumbent vendors to reengineer pricing models and implementation methodologies around subscription economics rather than perpetual licenses.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers across Germany, France, and Italy must implement serialized batch tracking, driving replacement of paper-based quality systems with validated electronic platforms.
- Automotive supplier compliance tiers:Tier-1 electronics manufacturers serving German OEMs face accelerated audit schedules that demand real-time production data feeds and automated non-conformance reporting.
- Edge computing integration:Semiconductor fabs in Taiwan and South Korea are deploying AI-enabled defect detection at the machine level, requiring MES platforms to ingest sub-millisecond sensor streams without cloud latency.
Market Restraints
- Semiconductor component volatility:Industrial IoT gateway shortages extend lead times for brownfield connectivity projects, delaying ROI realization for manufacturers with aging PLC infrastructures.
- EU AI Act risk classification:Automated visual inspection modules face pending conformity assessment requirements that could force architecture redesigns for quality-critical pharmaceutical deployments.
- Skills concentration:ISA-95 integration specialists cluster in southern Germany and Detroit metro areas, creating 40% wage premiums for remote implementations in secondary manufacturing zones.
Strategic Opportunities
- Indian pharmaceutical export compliance:CDSCO harmonization with FDA 21 CFR Part 11 creates first-mover advantage for cloud-MES vendors offering pre-validated electronic batch record templates.
- Digital twin convergence:Physics-based simulation layers merging with live MES data streams enable predictive bottleneck modeling for high-mix, low-volume contract electronics manufacturers.
- Subscription pricing penetration:Mid-sized discrete manufacturers in Poland and Czech Republic bypass capital approval barriers through operational expenditure models that bundle software, infrastructure, and managed services.
Industry Challenges
- Ontology mapping complexity:Harmonizing ISA-95 equipment hierarchies with proprietary PLC tag structures consumes 30-40% of implementation hours, particularly in facilities with 20+ year-old DCS installations.
- Cyber-physical security certification:IEC 62443 compliance for connected manufacturing systems requires specialized assessor availability that lags deployment demand by 8-12 months in most industrial regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing Operations Management Solutions Market |
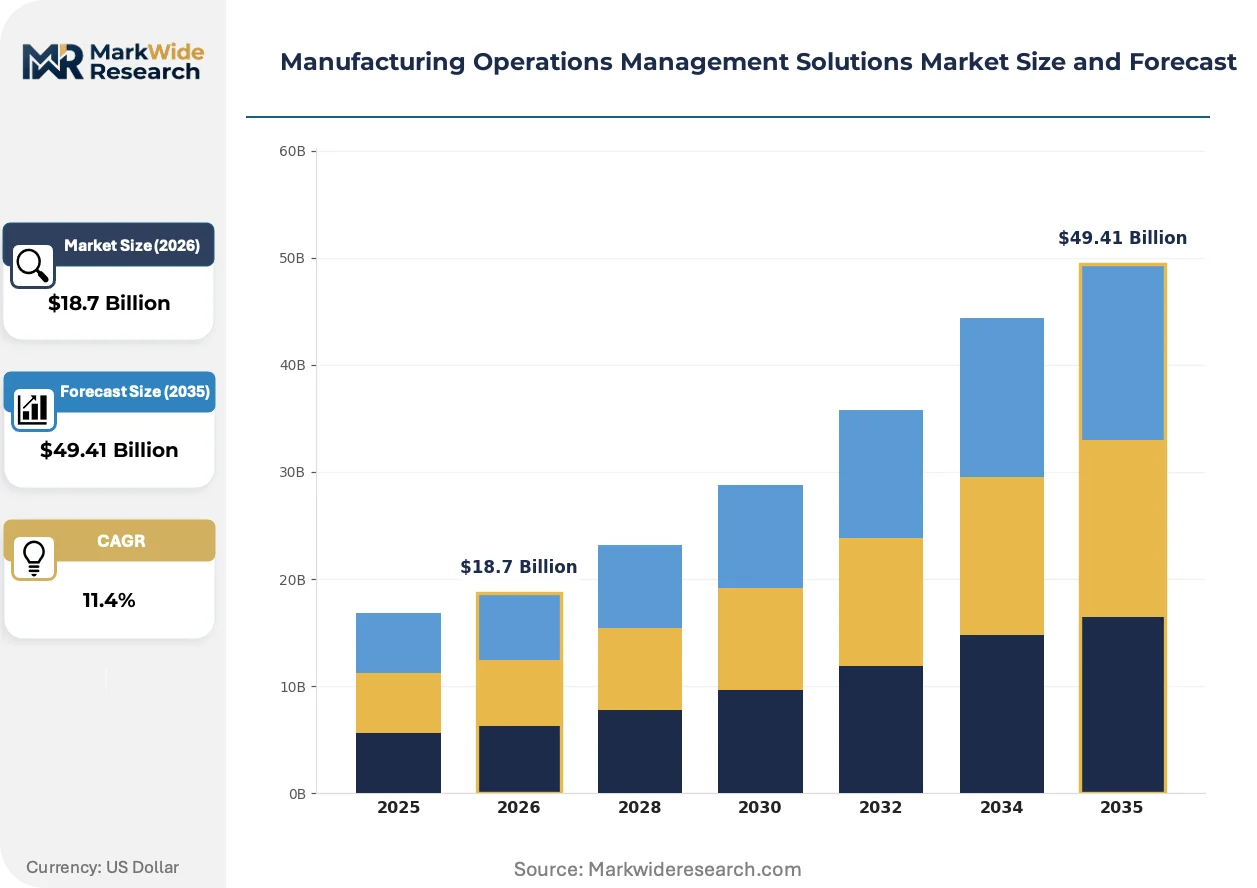
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ERP, MES, PLM, SCM Technology: Cloud-Based, On-Premise, Hybrid, Big Data End User: Aerospace, Automotive, Electronics, Pharmaceuticals Application: Workflow Management, Production Planning, Quality Control, Inventory Tracking |
| Companies Covered | Siemens, Rockwell Automation, SAP, Honeywell International, Dassault Systèmes, ABB, Schneider Electric, Oracle, AVEVA Solutions Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing Operations Management Solutions Market Shifts & Advancements
Artificial intelligence inference engines are migrating from centralized cloud clusters to programmable logic controllers, collapsing the architectural boundary between enterprise planning and shop-floor execution.
Microservice-based MES platforms are miniaturizing functional modules into containerized units that deploy independently across heterogeneous machine populations. Electronics contract manufacturers in Malaysia and Mexico adopt these architectures fastest, drawn by elastic capacity scaling during seasonal demand spikes. This modularity is compressing vendor lock-in effects and enabling multi-supplier orchestration layers that aggregate best-of-breed quality, scheduling, and maintenance functions.
The EU AI Act's risk-based classification framework is mandating conformity assessments for automated decision systems in pharmaceutical quality control. German and French notified bodies are developing sector-specific guidance that extends validation timelines by 4-6 months for vision-based defect classification modules. Medical device manufacturers are responding by segregating AI-enabled inspection steps into standalone subsystems with human-in-the-loop overrides to preserve regulatory flexibility.
Outcome-based contracting is displacing traditional software license sales in North American automotive supplier relationships. Tier-2 manufacturers now pay per validated electronic batch record rather than per user seat, transferring implementation risk to platform vendors. This shift concentrates in Michigan and Ohio supplier corridors where OEMs enforce unified data formats across their supply bases, compressing vendor negotiation leverage and accelerating consolidation around interoperable standards.
Manufacturing Operations Management Solutions Market Segmentation
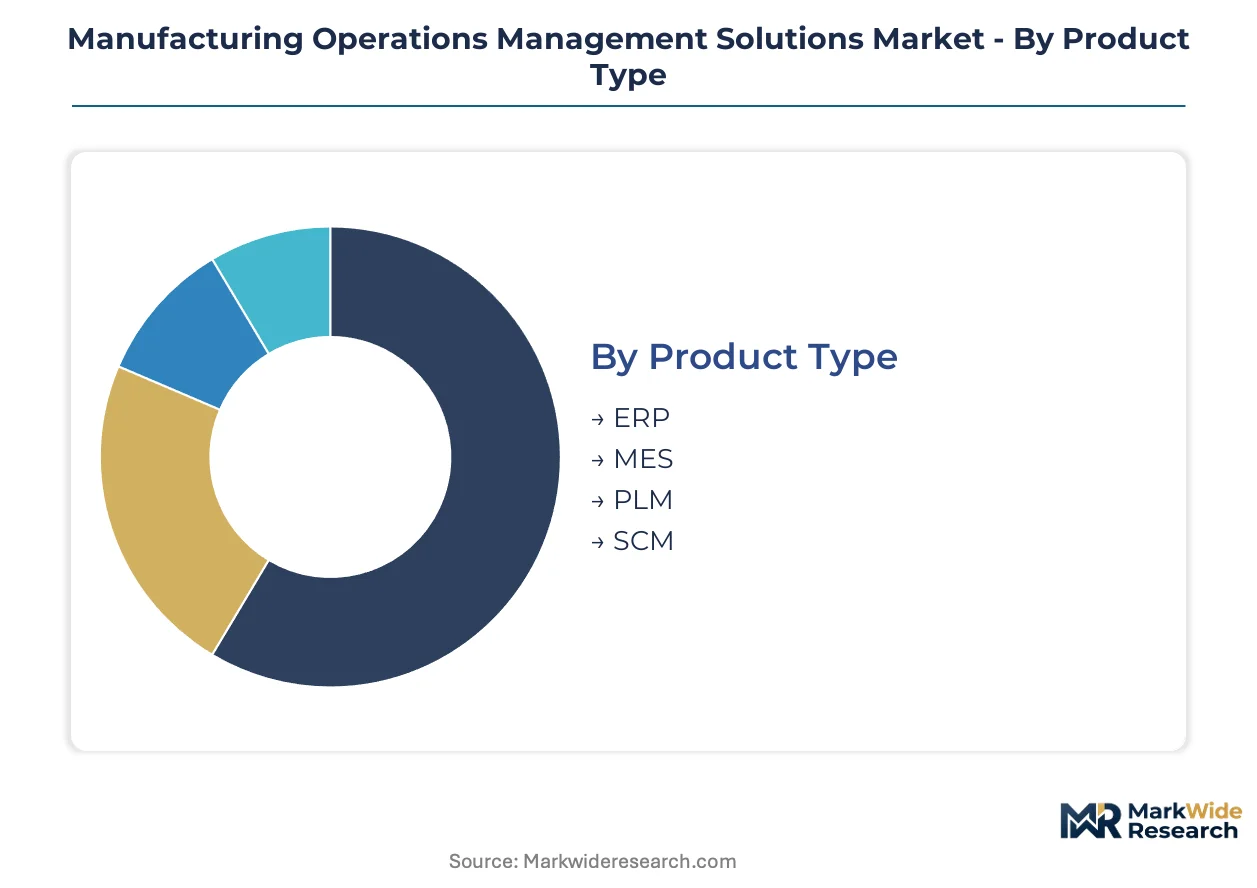
Segmentation in manufacturing operations management reveals where software substitution pressures reshape procurement patterns. Buyers increasingly bundle adjacent functions, eroding standalone category boundaries as platforms converge.
Product Type:
Substitution pressure runs strongest against standalone PLM and SCM modules as ERP vendors absorb their core functions into integrated suites.
- MES:Shop-floor execution systems coordinate real-time machine data, labor scheduling, and work-in-progress tracking through ISA-95 compliant architectures. Demand concentrates in German automotive and electronics facilities where OEM supplier audits mandate electronic batch records and serialized traceability. Siemens Opcenter and Rockwell FactoryTalk dominate deployments where PLC integration creates switching-cost barriers.
- ERP:Enterprise resource planning modules synchronize financial, procurement, and production planning across multi-site operations. Process manufacturers in pharmaceuticals and chemicals drive adoption as SAP S/4HANA and Oracle Fusion unify MES data streams with corporate reporting hierarchies.
- PLM:Product lifecycle management platforms manage engineering change orders and bill-of-materials versioning across distributed design teams.
- SCM:Supply chain management modules optimize logistics, demand forecasting, and supplier collaboration networks.
MES anchors the volume base while ERP gains share at the steepest rate through bundled suite procurement.
Technology:
Cost-tier stratification separates capital-intensive on-premise deployments from operational-expenditure cloud subscriptions favored by mid-sized manufacturers.
- Cloud-Based:SaaS architectures compress implementation cycles through pre-configured industry templates and managed infrastructure. Electronics contract manufacturers in Malaysia and Mexico adopt fastest, drawn by elastic capacity scaling during seasonal demand spikes without data center capital.
- Hybrid:Split architectures retain sensitive quality data on-premise while pushing analytics workloads to cloud instances. Pharmaceutical manufacturers facing FDA 21 CFR Part 11 validation requirements favor this model to segregate electronic records from computational layers.
- On-Premise:Perpetual-license installations persist in defense and aerospace facilities with air-gapped security mandates.
- Big Data:Industrial data lake platforms aggregate heterogeneous sensor streams for predictive maintenance and quality forecasting.
On-premise retains the installed base while cloud-based climbs the fastest as subscription economics penetrate mid-market procurement.
End User:
Application maturity varies sharply by sector, with pharmaceuticals carrying the highest compliance premium and electronics the fastest deployment velocity.
- Pharmaceuticals:Batch-oriented manufacturers face FDA and EU MDR traceability mandates requiring validated electronic records. Serialization requirements for medical devices drive replacement of paper-based quality systems across German, French, and Italian production sites.
- Automotive:Tier-1 suppliers serving German OEMs face compressed audit schedules demanding real-time production data feeds. Michigan and Ohio supplier corridors enforce unified data formats that accelerate platform consolidation.
- Electronics:High-mix, low-volume contract manufacturers prioritize rapid reconfiguration and multi-site orchestration.
- Aerospace:Defense contractors maintain legacy AS9100 quality systems with extended validation timelines.
Automotive anchors the volume base while pharmaceuticals gains share at the steepest rate through regulatory-driven replacement cycles.
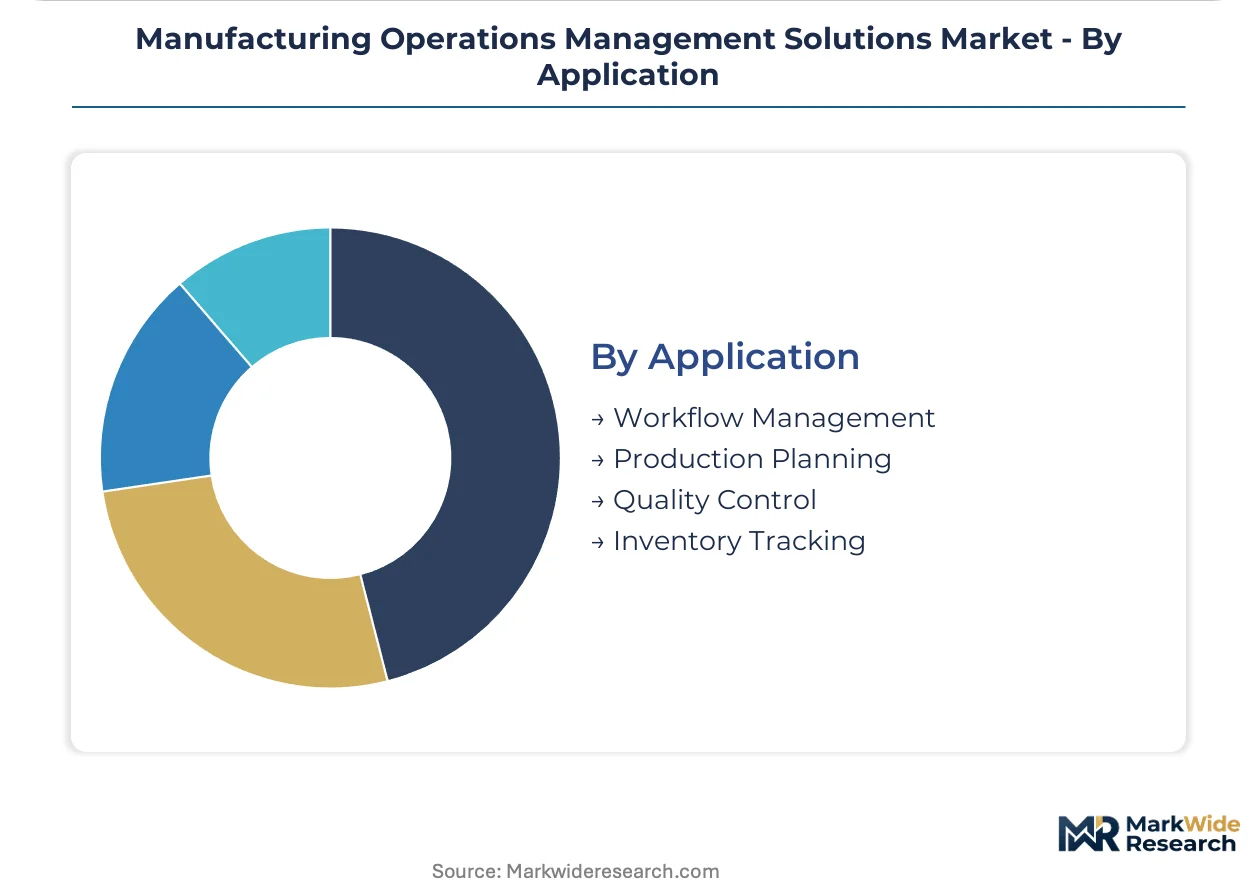
Application:
Functional breadth determines attach rates, with production planning achieving universal deployment while quality control commands premium pricing.
- Quality Control:Automated inspection and non-conformance management modules face EU AI Act risk classification for vision-based defect detection. German and French notified bodies extend validation timelines, prompting segregation into human-in-the-loop subsystems.
- Production Planning:Advanced planning and scheduling algorithms optimize resource allocation across constrained work centers. Electronics and automotive manufacturers deploy universally as foundational capabilities with lower per-module pricing.
- Workflow Management:Digital work instructions and electronic procedures guide operator execution on complex assembly lines.
- Inventory Tracking:Real-time material location and consumption monitoring synchronizes supply with production pacing.
Production planning anchors the volume base while quality control gains share at the steepest rate through compliance-driven premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive and pharmaceutical buyers concentrate procurement authority in Germany, the United States, and China, with electronics contract manufacturers distributing demand across Taiwan, South Korea, and Mexico. Regulatory divergence between FDA 21 CFR Part 11 and EU MDR traceability mandates fragments vendor certification requirements. Industrial clusters in southern Germany, Michigan, and the Yangtze River Delta anchor deployment volumes for integrated MES-ERP suites.
United States
Automotive suppliers in Michigan and Ohio enforce unified data formats across Tier-2 networks, compelling MES upgrades for real-time production feeds. FDA 21 CFR Part 11 mandates validated electronic batch records for pharmaceutical manufacturers in New Jersey and North Carolina. Boston-area medical device producers face compressed audit schedules that demand automated non-conformance reporting.
Germany
Industrie 4.0 deployments across Bavarian automotive plants and Baden-Württemberg machinery builders drive demand for ISA-95 compliant architectures. EU MDR traceability requirements from BSI and notified bodies extend validation timelines for vision-based quality systems. Siemens anchors a dense supplier ecosystem in Munich and Nuremberg serving chemical and electronics facilities with deep PLC integration.
China
Electronics contract manufacturers in Shenzhen and Dongguan prioritize cloud-native MES architectures for elastic capacity scaling during seasonal demand spikes. NMPA harmonization with international pharmaceutical standards accelerates electronic batch record adoption in Jiangsu and Zhejiang facilities. MIIT industrial internet initiatives subsidize edge computing deployments for semiconductor fabs in Shanghai.
India
Pharmaceutical exporters in Hyderabad and Ahmedabad face CDSCO alignment with FDA 21 CFR Part 11, creating demand for pre-validated cloud-MES templates. PLI scheme incentives for electronics manufacturing in Tamil Nadu and Karnataka attract contract manufacturers seeking rapid deployment cycles. Domestic automotive suppliers in Pune and Chennai upgrade quality systems to meet German OEM audit requirements.
South Korea
Semiconductor fabs in Gyeonggi Province deploy AI-enabled defect detection at the machine level, requiring MES platforms to ingest sub-millisecond sensor streams. MFDS pharmaceutical traceability mandates drive replacement of paper-based batch records in Incheon and Osong bioclusters. Samsung and SK Hynix supplier networks in Suwon accelerate edge computing integration for predictive maintenance modules.
Manufacturing Operations Management Solutions Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive automation portfolios, creating tiered competition between full-stack platform vendors and specialized execution-layer providers. Siemens and Rockwell Automation anchor the premium tier through deep PLC integration and automotive supplier relationships, while SAP and Oracle occupy the enterprise convergence segment unifying ERP hierarchies with shop-floor data. Strategic moves concentrate on M&A for edge computing capabilities and subscription pricing reengineering to capture mid-market procurement shifts.
Among diversified industrial technology groups, Siemens, ABB, and Schneider Electric represent the archetype of hardware-software convergence, leveraging captive automation portfolios to sustain switching-cost advantages in brownfield deployments. These conglomerates occupy positions where PLC integration depth determines competitive viability. SAP and Oracle exemplify enterprise software incumbents extending planning hierarchies into execution layers through acquired or natively developed MES modules. AVEVA Solutions Limited and Dassault Systèmes anchor the engineering-centric tier, where digital twin convergence and physics-based simulation differentiate positioning for high-mix manufacturing environments.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| SAP |
| Honeywell International |
| Dassault Systèmes |
| ABB |
| Schneider Electric |
| Oracle |
| AVEVA Solutions Limited |
| Others |
Supply & Pricing Matrix
Capacity utilization at cloud data centers in Frankfurt and Virginia shapes margin structures across subscription tiers, concentrating pricing power with hyperscaler-backed MES vendors while squeezing standalone providers on infrastructure costs. Scale economies in edge computing hardware production in Taiwan and South Korea feed through to deployment cost floors, forcing mid-market vendors toward managed service wrappers to preserve attach rates.
Pricing Analysis
Cost-plus contracts with semiconductor component indexation dominate brownfield connectivity projects, insulating systems integrators from raw material volatility while capping margin expansion. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical deployments from rapid electronics contract manufacturer rollouts, with FDA 21 CFR Part 11 compliance carrying the steepest premium. Pricing pressure stems from compressed automotive supplier audit cycles demanding faster implementation without proportional budget expansion. Mid-sized discrete manufacturers in Eastern Europe exhibit highest price sensitivity, while German automotive OEMs prioritize integration depth over per-seat economics.
Supply Chain Analysis
Strait of Malacca transit underwrites logistics costs for industrial IoT gateway shipments from Malaysian contract manufacturers to European deployment sites, creating seasonal bottlenecks during Q3 electronics demand spikes. Semiconductor fabs in Taiwan, South Korea, and China anchor component supply for edge computing modules, with memory and sensor packages drawing from concentrated wafer production. Single-source vulnerability runs through programmable logic controller firmware licensing from German and American automation conglomerates. Distribution runs through certified systems integrator networks in southern Germany, Michigan, and the Yangtze River Delta, with value-added resellers handling last-mile configuration for validated pharmaceutical installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in manufacturing operations management are crossing an inflection where ISA-95 interoperability standards enable multi-vendor orchestration layers, eroding captive ecosystem lock-in that sustained incumbent margins for two decades.
For Market Incumbents: Compound switching-cost advantages through deeper PLC firmware integration and pre-certified edge computing bundles that accelerate validation timelines for pharmaceutical buyers. Acquire specialist firms in AI-enabled defect detection to preempt EU AI Act conformity assessment delays. Threat substitution from cloud-native microservice architectures demands defensive moves before subscription pricing fully commoditizes execution-layer margins. For New Entrants and Emerging Players: Differentiate on rapid-deployment cloud-native architectures targeting mid-sized electronics contract manufacturers in Malaysia and Mexico, where elastic capacity scaling commands premium positioning. White-space concentration sits with pre-validated electronic batch record templates for Indian pharmaceutical exporters facing CDSCO-FDA harmonization. Go-to-market through outcome-based contracting per validated record transfers implementation risk and accelerates reference customer acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among verticalized MES vendors with captive automation hardware portfolios, where subscription attach rates on installed equipment bases generate durable cash flows. Long-term viability favors targets with deep ISA-95 integration expertise and established notified body relationships for EU MDR compliance. Signal to watch is consolidation velocity among Tier-2 automotive suppliers in Michigan and Ohio, where unified data format mandates are compressing vendor counts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies MES data streams with SAP S/4HANA hierarchies for pharmaceutical batch traceability. |
| Acquisition of Specialist Firm | Absorbs AI-enabled defect detection capabilities ahead of EU AI Act risk classification deadlines. |
| Geographic Expansion | Establishes edge computing delivery centers in Tamil Nadu to serve PLI-subsidized electronics manufacturers. |
| Strategic Partnership | Links cloud-MES vendors with German notified bodies to compress EU MDR validation timelines. |
| Product Launch | Introduces containerized microservice modules for high-mix contract manufacturers in Mexico. |
Research Methodology
Desk research of regulatory filings from FDA, EMA, and BSI, trade association reports from VDMA and MESA International, and vendor technical documentation preceded structured interviews with MES implementation leads, pharmaceutical quality directors, automotive supplier procurement officers, and industrial systems integrators. Primary fieldwork across Bavarian automotive plants, New Jersey pharmaceutical facilities, and Shenzhen electronics clusters validated secondary demand estimates. Bottom-up deployment counts triangulated against top-down software spending allocations from corporate IT budget disclosures.
Variance decomposition across technology adoption curves, regulatory compliance timelines, and vertical investment cycles anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include deployment architecture, organization scale tier, industry vertical, integration complexity level, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns in comparable enterprise software categories. Forecast inputs incorporated edge computing hardware cost trajectories and pharmaceutical serialization mandate enforcement schedules.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply normalization or accelerated EU AI Act implementation would require recalibration. Forecasts reflect documented assumptions regarding cloud infrastructure cost curves and regulatory harmonization progress. Practitioners should keep alternative scenarios live as industrial IoT gateway availability and notified body capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
System Integration Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
Workflow Content Automation (WCA) Market