
 AI Infrastructure Solutions Market | 2026-2036
AI Infrastructure Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
AI Infrastructure Solutions Market Insights
Cloud service provider procurement is fragmenting across specialized silicon vendors and vertically integrated stack providers. NVIDIA Corporation dominates GPU-based training clusters through its CUDA ecosystem lock-in. Microsoft Azure leverages its OpenAI partnership to anchor enterprise generative AI workloads. Amazon Web Services competes through custom Trainium and Inferentia chip development.
AI infrastructure solutions encompass the integrated hardware, software, and networking systems engineered to train, deploy, and scale artificial intelligence models, typically incorporating high-bandwidth memory subsystems, liquid-cooled accelerator racks, and terabit-scale interconnect fabrics. These systems serve commercial and scientific purposes ranging from large language model fine-tuning to real-time inference serving at the network edge. Cloud Services represent the largest revenue pool, though Edge Computing captures disproportionate margin expansion as latency-sensitive applications multiply. AI Accelerators within the Technology dimension lead capital deployment, while Hybrid Systems adoption grows fastest among enterprises seeking data sovereignty compliance.
The US Department of Commerce's Bureau of Industry and Security export controls restrict advanced AI accelerator shipments to designated countries, forcing geographic supply chain bifurcation. The EU AI Act imposes risk-tiered compliance obligations on high-capability general-purpose AI systems, redirecting European enterprise procurement toward auditable infrastructure stacks. China's MIIT dual carbon goals constrain data center power density approvals, accelerating liquid cooling retrofit demand. Stakeholders must monitor divergent national semiconductor subsidy regimes and their cascading effects on foundry allocation priority.
Market Dynamics
Hyperscale cloud operators are consolidating procurement around vertically integrated AI infrastructure stacks, forcing specialized hardware vendors to defend position through ecosystem lock-in rather than discrete component sales. This concentration dynamic is compressing margins for modular suppliers while rewarding full-stack providers with multi-year enterprise anchor contracts.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises are redirecting capital toward auditable infrastructure stacks with embedded governance tooling, creating premium demand for certified systems.
- Generative AI inference at the edge:Financial services and autonomous vehicle developers are deploying low-latency accelerator clusters in metropolitan colocation facilities to serve real-time model serving.
- China:MIIT dual carbon goals are constraining traditional air-cooled data center approvals, accelerating retrofit demand for liquid-cooled rack architectures.
Market Restraints
- Advanced packaging substrate shortage:CoWoS and HBM interposer capacity constraints at TSMC and Samsung Foundry are throttling GPU and AI accelerator output regardless of silicon wafer availability.
- US export controls:Bureau of Industry and Security restrictions on advanced accelerator shipments to designated countries are bifurcating supply chains and fragmenting R&D investment pools.
- Power density physics:Training cluster thermal design power exceeding 100 kilowatts per rack is outpacing legacy facility power distribution and cooling infrastructure upgrade cycles.
Strategic Opportunities
- Germany:Industrial automation conglomerates are piloting sovereign AI infrastructure for predictive maintenance and quality control, creating demand for on-premise training systems.
- Photonic interconnect convergence:Co-packaged optics and silicon photonics are enabling terabit-scale node-to-node bandwidth with 70% lower power draw than electrical SerDes.
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting modular data center assembly investments serving Middle East and Southeast Asian demand.
Industry Challenges
- Systems software talent scarcity:Kernel-level optimization for heterogeneous compute fabrics requires expertise across CUDA, ROCm, and proprietary SDKs that remains concentrated at a handful of institutions.
- Intergenerational hardware migration:Enterprises with depreciated CPU-centric infrastructure face forklift upgrade costs and application refactoring timelines that delay AI workload migration.
- Supply chain reconfiguration:Foundry allocation priority disputes between cloud self-build programs and merchant silicon vendors are extending lead times for secondary buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Infrastructure Solutions Market |
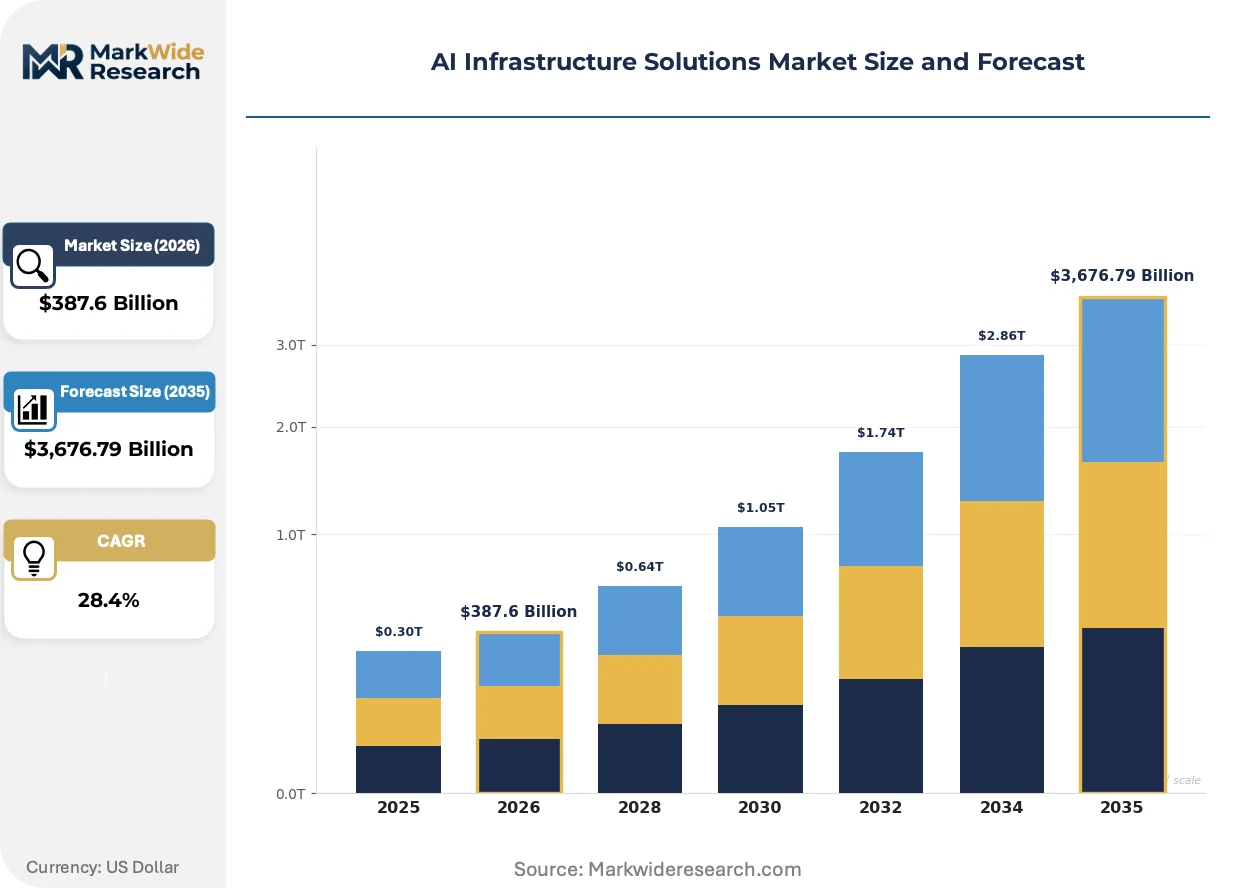
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $3,676.79 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Services, On-Premises Solutions, Hybrid Systems, Edge Computing Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Bare Metal End User: Enterprises, Startups, Research Institutions, Government Agencies Technology: Machine Learning Frameworks, Data Processing Platforms, AI Accelerators, Workflow Automation Tools |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices, Intel Corporation, Samsung Electronics, Micron Technology, Amazon Web Services, Microsoft Azure, Google Cloud, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Infrastructure Solutions Market Trends and Innovations
Compute architectures are fragmenting across training-optimized and inference-optimized designs, with memory subsystem configurations diverging based on workload access patterns rather than universal platform standardization.
Liquid cooling is migrating from niche high-performance computing installations to mainstream cloud data centers as training cluster power densities exceed air-cooling thresholds. Microsoft Azure and Amazon Web Services are specifying direct-to-chip and immersion systems for new hyperscale builds. This technology shift is compressing mechanical infrastructure vendor margins while elevating coolant chemistry and leak-detection specialists.
The EU AI Act is imposing risk-tiered documentation and audit requirements on general-purpose AI systems above specified compute thresholds. European enterprises are now requiring infrastructure vendors to provide model cards, data provenance logs, and energy consumption attestations. German automotive and French pharmaceutical buyers are prioritizing European-based facility deployments to satisfy data residency and audit access requirements.
Enterprise buyers are consolidating vendor relationships around full-stack providers capable of delivering hardware, orchestration software, and optimization services under unified contracts. Discrete component procurement through systems integrators is losing share to direct engagements with NVIDIA, AMD, and cloud-first silicon vendors. This pattern is most visible in United States financial services and healthcare verticals where internal AI platform teams prefer single-throat accountability.
AI Infrastructure Solutions Market Segmentation
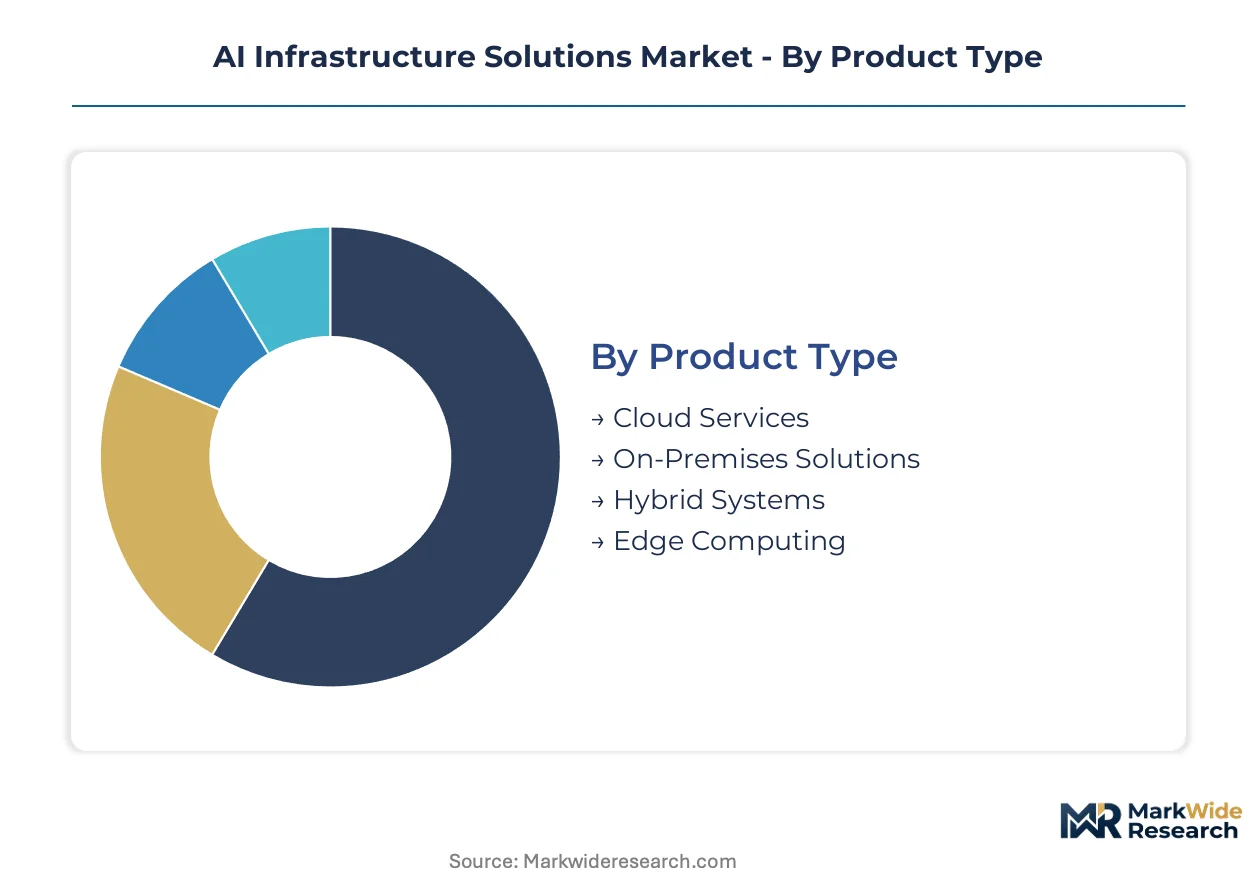
AI infrastructure procurement patterns diverge sharply across deployment modes and end-user profiles. Understanding these segment boundaries reveals where capital cycles accelerate and where legacy lock-in persists.
Product Type:
Cloud Services turn over fastest as hyperscalers refresh accelerator generations annually, while On-Premises Solutions depreciate over five-to-seven year cycles.
- Cloud Services:Multi-tenant GPU clusters with API-accessible training and inference endpoints. Financial services firms in the United States are consolidating procurement here to avoid capital intensity, though egress fees and vendor lock-in create switching friction.
- Edge Computing:Distributed inference nodes deployed in metropolitan colocation facilities with sub-10 millisecond latency targets. Autonomous vehicle developers in Germany and China are driving demand for liquid-cooled compact racks that fit constrained real estate footprints.
- On-Premises Solutions:Enterprise-owned training clusters in captive data centers.
- Hybrid Systems:Workload-orchestrated deployments spanning cloud burst capacity and on-premise base load.
Cloud Services dominates installed base. Edge Computing is where expansion concentrates.
Deployment Model:
Cost tiers separate these segments: Public Cloud minimizes upfront commitment, Bare Metal demands full capital deployment, with Private Cloud and Multi-Cloud occupying intermediate positions.
- Public Cloud:Shared infrastructure with consumption-based pricing and managed Kubernetes orchestration. Startups across India and Southeast Asia are defaulting here to bypass hardware procurement lead times.
- Multi-Cloud:Workload portability across AWS, Azure, and GCP with abstraction layers like Kubernetes and Terraform. European enterprises facing EU AI Act audit requirements are adopting this model to maintain vendor leverage and geographic redundancy.
- Private Cloud:Single-tenant infrastructure with dedicated physical isolation.
- Bare Metal:Unvirtualized accelerator access for maximum performance per watt.
Public Cloud captures the volume base. Multi-Cloud is climbing the fastest as sovereignty concerns mount.
End User:
Application maturity varies: Enterprises run production inference at scale, Research Institutions push frontier training, Startups iterate rapidly, Government Agencies move slowest with procurement rigidity.
- Enterprises:Fortune 500 deployments spanning predictive maintenance, fraud detection, and code generation. Healthcare and financial services verticals in the United States are demanding HIPAA and SOC-2 compliant infrastructure stacks with embedded governance tooling.
- Government Agencies:Classified and civilian AI workloads with stringent supply chain provenance requirements. The US Department of Defense and China's MIIT are both directing procurement toward domestically sourced silicon and assembly.
- Startups:Venture-funded model training with cloud-native architectures and minimal legacy burden.
- Research Institutions:Academic and national laboratory access to exascale-class systems for scientific discovery.
Enterprises dominate installed base. Government Agencies are where expansion concentrates as sovereign AI programs accelerate.
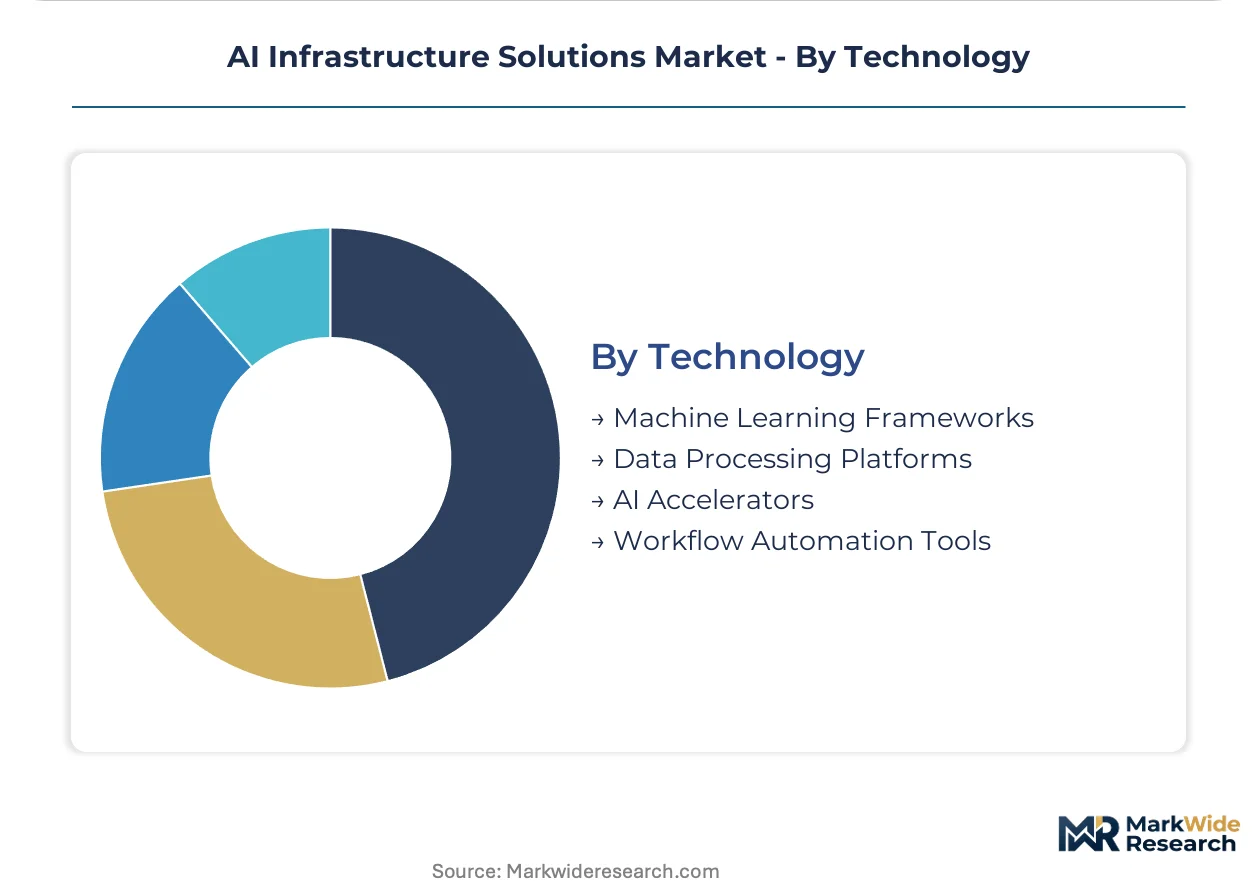
Technology:
Supply concentration distinguishes these segments: AI Accelerators depend on TSMC CoWoS capacity, Machine Learning Frameworks fragment across open-source ecosystems, Data Processing Platforms consolidate around Spark and Ray, Workflow Automation Tools remain fragmented.
- AI Accelerators:GPUs, TPUs, and custom ASICs with high-bandwidth memory subsystems and terabit-scale interconnects. NVIDIA's CUDA ecosystem lock-in has created switching costs that hyperscalers are attempting to break through in-house silicon programs at Google, Amazon, and Microsoft.
- Machine Learning Frameworks:PyTorch, TensorFlow, and JAX with distributed training abstractions. China's research community is coalescing around PaddlePaddle and MindSpore amid US export control constraints on NVIDIA's latest architectures.
- Data Processing Platforms:Distributed storage and compute fabrics for training data pipelines.
- Workflow Automation Tools:MLOps pipelines for model versioning, deployment, and monitoring.
AI Accelerators dominates installed base. Machine Learning Frameworks is where expansion concentrates as open-source alternatives to CUDA mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for AI accelerator procurement concentrates in United States hyperscalers, while Chinese buyers face cost premiums from Bureau of Industry and Security export controls and constrained supply access.
United States
Financial services firms and cloud operators drive hyperscale data center expansion across Northern Virginia and Dallas-Fort Worth. The Department of Commerce's Bureau of Industry and Security maintains export restrictions on advanced semiconductors to designated countries. Austin and Phoenix anchor GPU cluster deployments where liquid-cooled facilities exceed 100 kilowatts per rack density.
China
Domestic cloud providers and AI labs accelerate procurement of locally fabricated accelerators amid restricted NVIDIA access. MIIT dual carbon goals constrain traditional air-cooled data center approvals nationwide. Beijing and Shanghai house retrofit demand for liquid-cooled architectures serving large language model training.
Germany
Industrial automation conglomerates pilot sovereign AI infrastructure for predictive maintenance and quality control applications. The EU AI Act imposes risk-tiered compliance obligations on high-capability general-purpose AI systems. Bavaria and Baden-Württemberg concentrate demand for on-premise training systems with embedded governance tooling.
India
Startups and enterprise IT departments default to public cloud deployments to bypass hardware procurement lead times. The Production-Linked Incentive scheme attracts modular data center assembly investments. Mumbai and Bangalore serve as assembly hubs for Middle East and Southeast Asian demand.
Japan
Automotive and electronics manufacturers deploy edge inference clusters for quality inspection and robotics applications. METI directs procurement toward domestically sourced components where feasible. Tokyo-Osaka corridor facilities prioritize low-latency accelerator deployment for manufacturing integration.
AI Infrastructure Solutions Market Competitive Landscape
Full-stack platform providers and specialized silicon vendors split the market along integration depth. Hyperscale cloud operators consolidate procurement around vertically integrated stacks, compressing margins for modular component suppliers. Three archetypes dominate: CUDA-ecosystem incumbents, custom ASIC cloud builders, and modular accelerator challengers. Competitive moves center on multi-year enterprise anchor contracts and in-house silicon program expansion.
Within the full-stack tier, NVIDIA Corporation represents the CUDA-ecosystem incumbent with established training cluster deployments, while Amazon Web Services and Microsoft Azure exemplify cloud-first custom silicon strategies. AMD occupies a position among modular accelerator challengers attempting ecosystem diversification. These three anchors illustrate the strategic divergence between software-locked incumbents and vertically integrated hyperscale operators.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices |
| Intel Corporation |
| Samsung Electronics |
| Micron Technology |
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
CoWoS capacity utilization at TSMC exceeding 90 percent has compressed lead times for NVIDIA H100 clusters while elevating price premiums for expedited delivery slots, forcing hyperscalers to commit multi-year offtake agreements and secondary buyers to absorb markups or defer procurement.
Pricing Analysis
Configured-to-order pricing for liquid-cooled training clusters commands 35-50 percent premiums over standard air-cooled configurations due to coolant chemistry engineering and leak-detection integration. Pricing stratifies across premium certified systems with EU AI Act audit tooling, standard enterprise deployments, and economy-tier cloud spot instances. Cost compression in the economy tier is intensifying because hyperscalers are internalizing accelerator production through custom ASIC programs. Startups and research institutions exhibit highest price sensitivity, while financial services firms in the United States demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for advanced packaging substrates and HBM memory modules. Manufacturing concentrates in Taiwan, South Korea, and the United States for leading-edge silicon fabrication. The supply chain draws from high-bandwidth memory stacks, CoWoS interposers, and liquid cooling manifolds as critical inputs. Single-source vulnerability at TSMC for advanced packaging creates chokepoint exposure. Distribution runs through direct hyperscale contracts, systems integrators, and modular component distributors serving enterprise and government buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI infrastructure solutions occupy an early-cycle expansion phase as sovereign AI programs and generative AI inference workloads drive penetration beyond hyperscale cloud operators into industrial automation and financial services verticals.
For Market Incumbents: Harden ecosystem lock-in through CUDA optimization tooling and multi-year enterprise anchor contracts with embedded governance features. Expand in-house silicon programs to reduce dependency on merchant GPU supply. Prioritize certification investment for EU AI Act compliance to capture premium procurement from European automotive and pharmaceutical buyers. For New Entrants and Emerging Players: Sovereign AI infrastructure deployments in Germany and India represent the most penetrable entry points given procurement fragmentation and domestic content requirements. Edge computing inference clusters for autonomous vehicle developers in metropolitan colocation facilities offer white-space expansion. Pursue channel partnerships with systems integrators serving government agencies to bypass direct hyperscale competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-stack platform providers with multi-year managed infrastructure contracts. Long-term viability over the next decade favors vertically integrated operators with captive silicon supply and software-defined orchestration layers. Monitor Bureau of Industry and Security export control expansion as the critical inflection signal for geographic supply chain reconfiguration and valuation multiple divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Custom ASIC Development | Hyperscalers at Amazon Web Services and Google Cloud reduce NVIDIA dependency through Trainium and TPU programs. |
| Liquid Cooling Retrofit | MIIT dual carbon goals in China accelerate rack architecture upgrades for data center power density compliance. |
| EU AI Act Certification | German automotive buyers prioritize auditable infrastructure stacks with embedded governance tooling and energy attestations. |
| Photonic Interconnect Integration | Co-packaged optics enable terabit-scale bandwidth with 70 percent lower power draw than electrical SerDes. |
| India PLI Manufacturing | Production-linked incentives attract modular data center assembly serving Middle East and Southeast Asian demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hyperscale procurement officers, enterprise IT directors, and semiconductor supply chain managers; and secondary validation through hyperscaler capex disclosures, SEC 10-K filings, and foundry capacity reports. The research combined bottom-up shipment tracking of AI accelerator units with top-down cloud infrastructure spending analysis. Triangulation across these approaches anchored volume and value estimates.
Forecast inputs considered deployment model segmentation across public cloud, multi-cloud, private cloud, and bare metal; end-user profiles spanning enterprises, government agencies, and research institutions; and technology categories including AI accelerators, machine learning frameworks, and data processing platforms. CAGRs were derived from regression analysis of historical hyperscaler infrastructure spending against projected generative AI workload penetration. Foundry allocation priority disputes and export control policy evolution served as scenario-weighting variables.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting hyperscaler capital expenditure cycles or semiconductor equipment investment would shift the trajectory. Forecasts reflect documented assumptions regarding foundry capacity expansion timelines and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Data Extraction Market
Digital Solutions
Workflow Content Automation (WCA) Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Microservices Architecture Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Warranty Management System Market