
 Global Cloud POS Market | 2026-2036
Global Cloud POS Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud POS Market Foresight
GDPR data-localization rules is realigning the cost-of-entry calculus for vendors serving European merchants. Square Inc leverages its integrated hardware-software stack to dominate the North American small-business channel. Shopify anchors its cloud POS growth within its broader commerce ecosystem, extending reach to franchises. Toast Inc specializes in hospitality-specific workflows, competing on vertical depth rather than horizontal breadth.
Cloud POS denotes a point-of-sale architecture where transaction processing, inventory synchronization, and analytics execute on remote servers accessed via internet-connected terminals, typically requiring sub-100-millisecond latency for card authorization. The primary commercial purpose is to unify sales channels, reduce on-premise IT overhead, and enable real-time data access across distributed locations. Public cloud deployments lead in adoption among quick-service restaurants seeking elastic capacity during peak hours, while hybrid cloud configurations capture margin pools from large retail chains demanding workload segregation between payment processing and customer analytics. Small businesses represent the fastest-expanding customer type as subscription pricing displaces capital-intensive legacy licensing.
The PCI Security Standards Council mandates encryption protocols for cardholder data environments, directly shaping product certification requirements and vendor R&D allocation. EMA-aligned data governance in Europe and India's RBI digital payment guidelines further fragment compliance obligations across jurisdictions. Stakeholders must monitor how central bank digital currency integrations and open-banking API mandates redefine transaction routing economics before committing to platform architecture decisions.
Market Dynamics
PCI DSS encryption mandates and RBI digital payment guidelines are fragmenting compliance obligations, forcing vendors to architect region-specific data environments rather than unified global platforms. This regulatory divergence is compressing vendor margins while accelerating hardware refresh cycles among legacy terminal operators.
Growth Catalysts
- SMB digitization programs:Government-backed initiatives in India and the United Kingdom subsidize cloud POS adoption among micro-merchants, converting cash-based operations to digital transaction infrastructure.
- GDPR data-localization:European merchants must store cardholder data within jurisdictional boundaries, creating demand for region-housed cloud instances and edge-computing terminals.
- Quick-service restaurant elasticity:Peak-hour transaction surges drive adoption of public cloud architectures that auto-scale processing capacity without on-premise server investment.
Market Restraints
- Sub-100-millisecond latency requirements:Card authorization protocols demand fiber-grade connectivity unavailable in rural India and secondary US markets, excluding peripheral geographies.
- Input cost concentration:Semiconductor shortages for payment terminal chipsets concentrate supply risk among Taiwanese foundries, extending hardware delivery timelines.
- Subscription fatigue:Small merchants facing multiple SaaS fees resist adding cloud POS recurring charges atop existing accounting and e-commerce subscriptions.
Strategic Opportunities
- Central bank digital currency integration:RBI pilot programs and US Federal Reserve exploration of CBDCs create first-mover advantage for platforms enabling direct digital currency settlement.
- Open-banking API mandates:European PSD2 and UK Open Banking regulations force traditional banks to expose transaction data, allowing cloud POS providers to embed lending and reconciliation services.
- Hospitality workflow depth:Kitchen display systems, table management, and tip-pooling modules remain underpenetrated by horizontal platforms, rewarding vertical specialization.
Industry Challenges
- Legacy terminal integration:Decades-old on-premise systems in US restaurant chains require costly middleware development to synchronize with cloud inventory and analytics layers.
- Certification timeline compression:PCI DSS 4.0 transition and regional payment scheme approvals extend product launch cycles, delaying revenue recognition for new feature rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud POS Market |
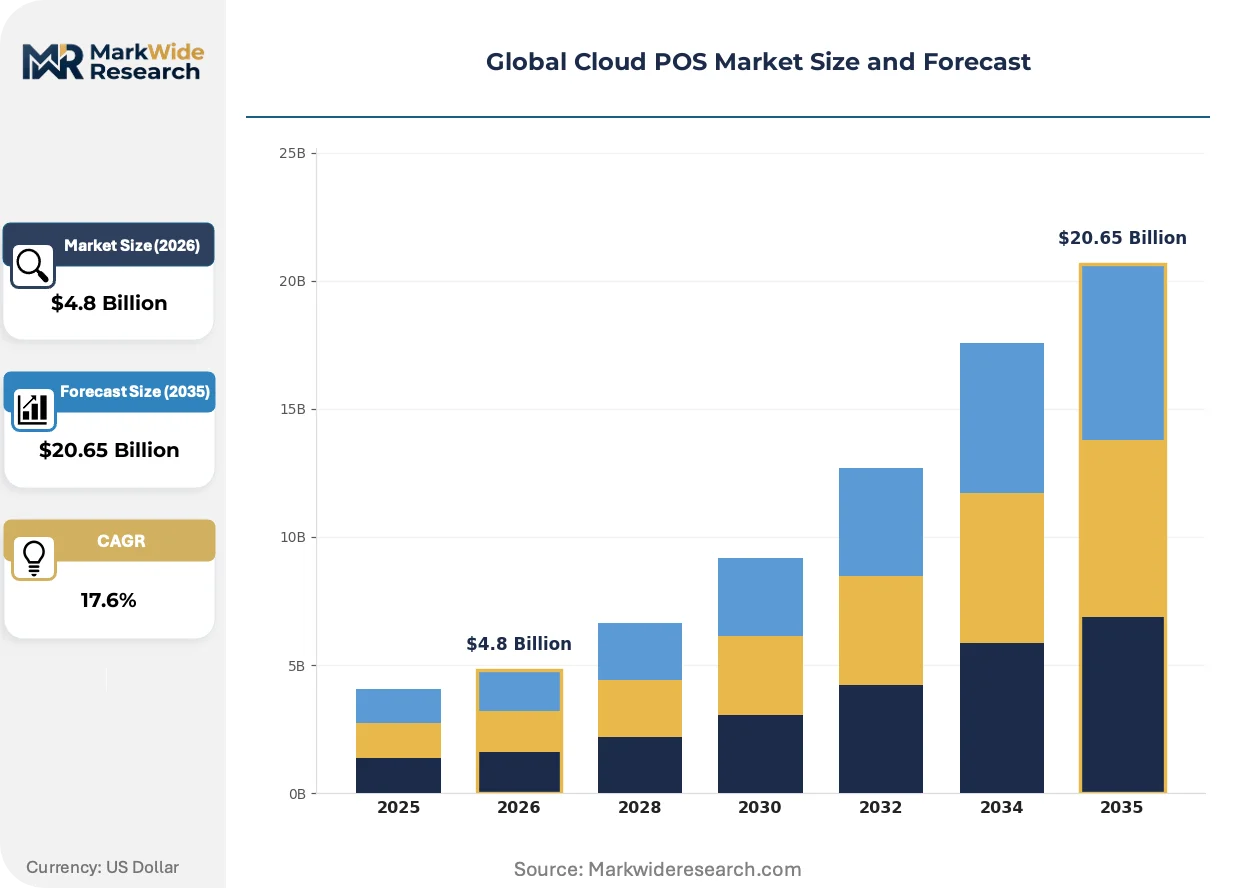
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Payment Processing, Inventory Management, Customer Relationship Management, Sales Analytics, Employee Management Application: Hospitality, Retail Chains, Quick Service Restaurants, Specialty Stores, Entertainment Venues Customer Type: Small Businesses, Medium Enterprises, Large Enterprises, Franchises, Independent Operators |
| Companies Covered | Square Inc, Shopify, Oracle Corporation, Lightspeed Commerce Inc, Clover Network Inc, NCR Voyix Corporation, Toast Inc, Cegid Group, TouchBistro Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud POS Market Shifts & Advancements
Software-defined payment terminals are decoupling hardware from processing logic, enabling merchants to swap functionality without forklift upgrades. This architectural shift compresses replacement cycles and opens margin pools for firmware-subscription vendors.
Edge-computing payment terminals with localized tokenization is modularizing the traditional POS stack. Quick-service restaurants in the United States deploy these devices to maintain transaction continuity during internet outages. The technology is modularizing vendor competitive sets, separating hardware manufacturers from payment processors and allowing merchants to mix components.
GDPR Article 44 cross-border data transfer restrictions are forcing architectural redesigns. Cloud POS providers now provision EU-sovereign instances to avoid Standard Contractual Clause complexity. Large retail chains with transatlantic operations bear the highest compliance burden, segmenting their deployments by geography rather than consolidating on single global platforms.
Merchant acquisition is fragmenting from bundled ISO relationships toward direct API-driven onboarding. Small US restaurants now provision accounts through self-service portals rather than field sales consultations. This channel compression is most visible in the United Kingdom, where digital-native merchants reject traditional reseller networks entirely.
Global Cloud POS Market Segmentation
Cloud POS architectures fragment across deployment models, solution stacks, and merchant scale tiers. Each segmentation axis reveals distinct procurement patterns, compliance burdens, and vendor competitive sets that determine platform selection.
Deployment:
IT governance maturity and data sovereignty obligations differentiate buyers across deployment architectures.
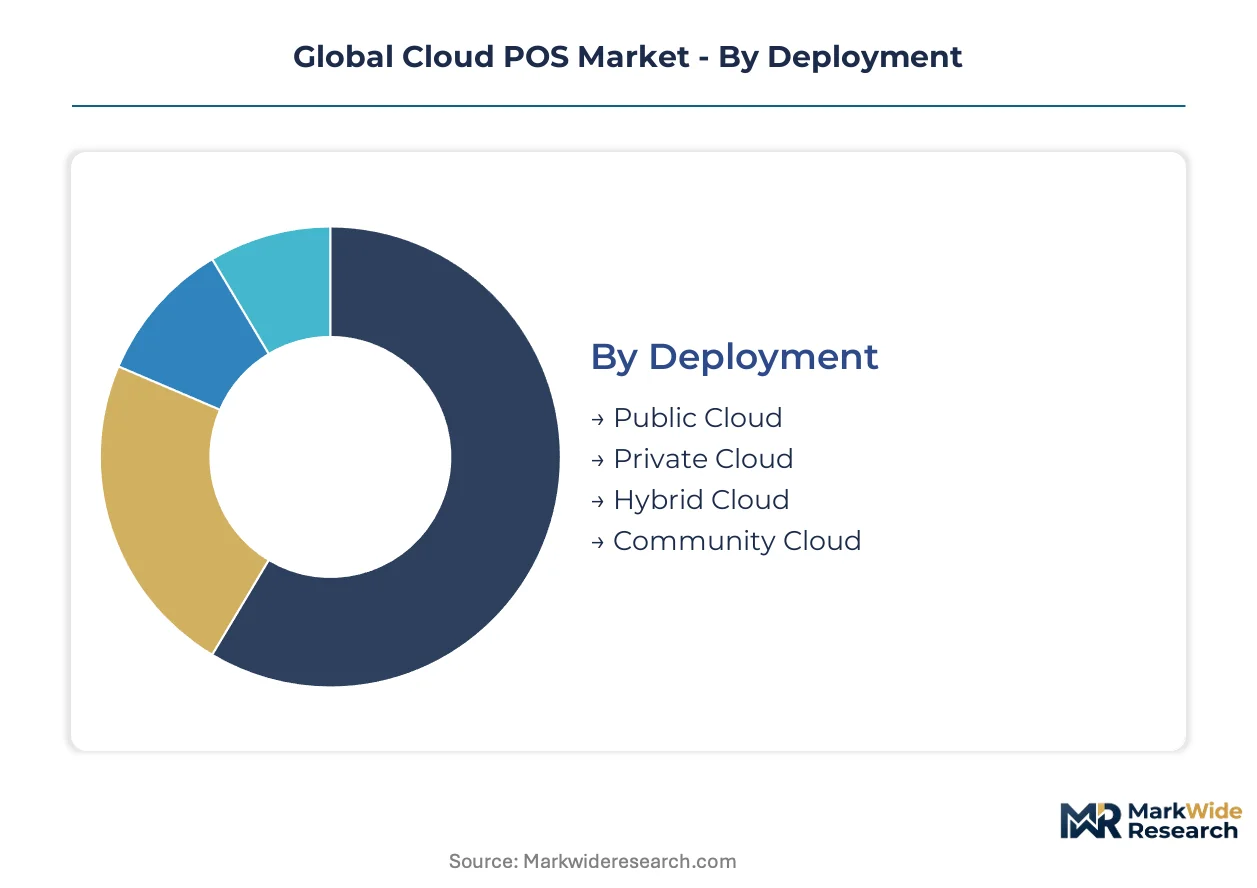
- Public Cloud:Multi-tenant infrastructure pools compute resources across merchants, delivering elastic capacity during transaction spikes. Quick-service restaurants in the United States deploy these environments to handle lunch-hour volume surges without capital-intensive server investments.
- Private Cloud:Single-tenant dedicated instances isolate cardholder data environments, satisfying PCI DSS segmentation requirements for large retail chains. European merchants facing GDPR Article 44 cross-border restrictions favor these deployments to maintain jurisdictional control over customer records.
- Hybrid Cloud:Workload segregation splits payment processing on-premise from analytics in cloud instances. Large hospitality groups use this architecture to keep authorization systems local while centralizing reporting across distributed properties.
- Community Cloud:Shared infrastructure serving vertical-specific merchant associations with standardized compliance frameworks. Franchise networks deploy these environments to harmonize data governance across operator locations.
Public Cloud leads volumes today; Hybrid Cloud is gaining share fastest.
Solution Type:
Functional depth requirements separate horizontal platforms from specialized modules.
- Payment Processing:Card authorization, tokenization, and settlement routing form the core transaction layer. RBI digital payment guidelines in India and PSD2 mandates in Europe are reshaping integration requirements for this foundational component.
- Inventory Management:Real-time stock synchronization across channels demands sub-second latency for distributed SKU databases. Retail chains in the United Kingdom prioritize these capabilities to unify online and in-store availability.
- Customer Relationship Management:Loyalty program administration and purchase history analytics. Specialty stores leverage these tools for personalized promotion targeting.
- Sales Analytics:Dashboard visualization of transaction patterns, basket composition, and hourly velocity. Independent operators in India adopt these modules through government-subsidized digitization programs.
- Employee Management:Shift scheduling, tip distribution, and performance tracking. Hospitality venues in the United States deploy these features to streamline labor compliance across tipped wage environments.
Payment Processing anchors revenue today; Inventory Management shows steepest expansion trajectory.
Application:
Operational workflow complexity determines whether merchants prioritize speed, depth, or flexibility.
- Hospitality:Table management, kitchen display integration, and split-check handling dominate requirements. Full-service restaurants demand these specialized workflows that horizontal platforms struggle to replicate.
- Quick Service Restaurants:High-velocity counter service with minimal customization drives throughput optimization. Drive-thru operators in the United States prioritize sub-100-millisecond authorization speeds to prevent queue abandonment.
- Retail Chains:Omnichannel inventory visibility and returns processing across distributed locations. Large enterprises in Europe segment these deployments by country to satisfy data-localization mandates.
- Specialty Stores:Niche product categories with complex variant management and appointment scheduling. Independent bookstores and pharmacies favor modular solutions over integrated suites.
- Entertainment Venues:Seasonal capacity spikes and concession integration with ticketing systems. Stadium operators deploy elastic public cloud resources for event-day transaction surges.
Hospitality commands premium pricing today; Quick Service Restaurants are climbing the fastest.
Customer Type:
Procurement sophistication and integration legacy separate buyer tiers.
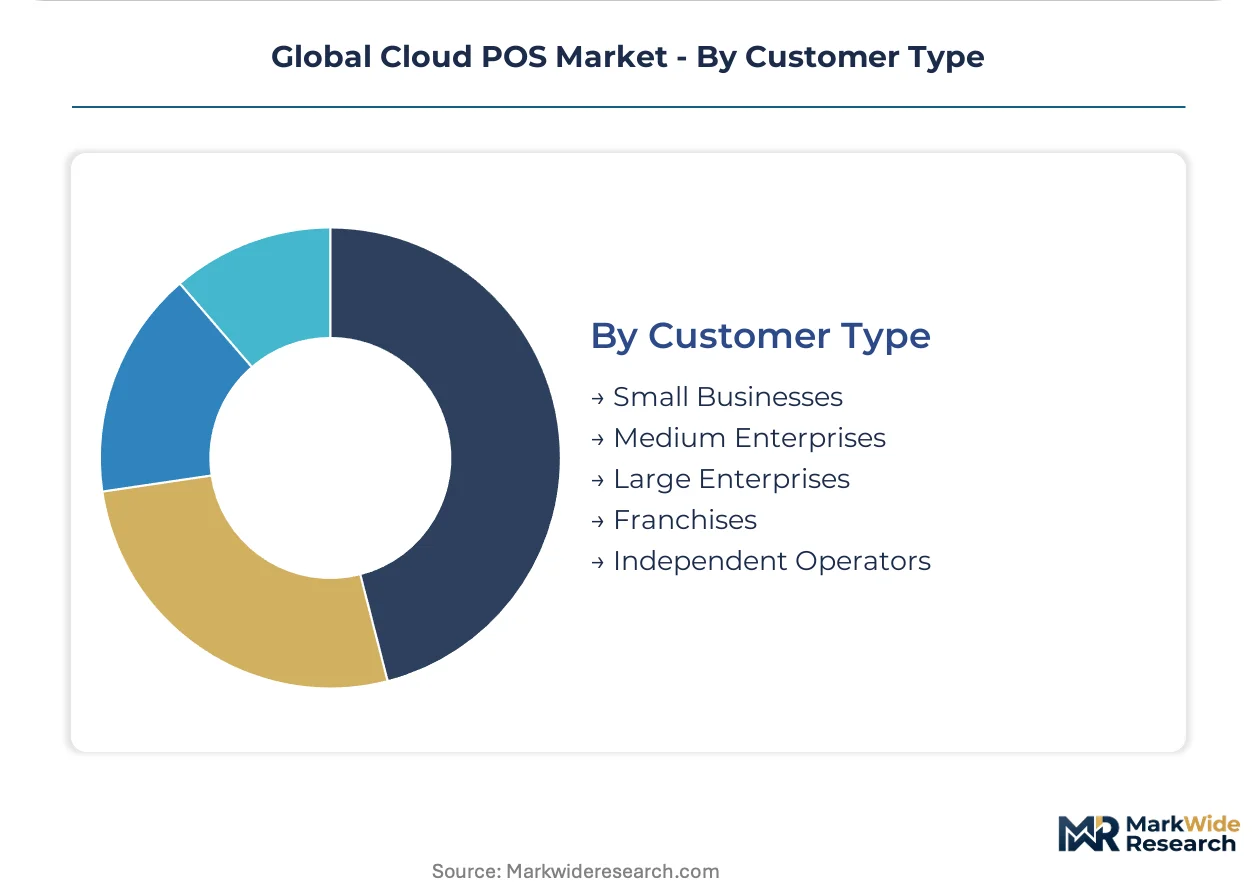
- Small Businesses:Subscription pricing and self-service onboarding eliminate upfront capital requirements. Micro-merchants in India access these platforms through subsidized government initiatives.
- Medium Enterprises:Multi-location coordination with standardized reporting across 5-50 outlets. Regional restaurant groups in the United Kingdom favor these solutions for franchise-ready scalability.
- Large Enterprises:Custom integration with ERP systems and dedicated account management. Transatlantic retailers bear the highest compliance burden from segmented geographic deployments.
- Franchises:Corporate oversight with operator autonomy creates tension between standardization and local adaptation. Quick-service networks deploy community cloud instances to balance these requirements.
- Independent Operators:Single-location merchants with minimal IT staff and straightforward workflows. Family-owned restaurants in the United States dominate this segment's self-service adoption curves.
Small Businesses generate transaction volume today; Franchises are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Silicon Valley, London, and Bangalore anchor cloud POS platform development. These concentrations attract venture capital and enterprise R&D investment. Regulatory divergence across jurisdictions fragments deployment architectures.
United States
Quick-service restaurant chains and SMB digitization drive demand concentration. PCI DSS mandates from the PCI Security Standards Council enforce encryption protocols for cardholder data. The San Francisco Bay Area hosts Square Inc and Toast Inc headquarters, where hospitality-specific workflows dominate product roadmaps.
United Kingdom
Government-backed SMB digitization programs subsidize micro-merchant adoption. PSD2 open-banking regulations force traditional banks to expose transaction APIs. London fintech clusters embed lending services into cloud POS platforms through these regulatory openings.
India
RBI digital payment guidelines reshape integration requirements for payment processors. Government-subsidized digitization programs convert cash-based operations to digital infrastructure. Bangalore and Mumbai technology corridors concentrate vendor development centers serving domestic merchant acquisition.
Germany
GDPR Article 44 data-localization rules mandate EU-sovereign cloud instances. Large retail chains segment deployments by geography rather than consolidating globally. Berlin and Munich host compliance-focused platform operations serving transatlantic enterprises.
Japan
METI industrial digitization initiatives accelerate SMB software adoption. Quick-service elasticity requirements drive public cloud deployment for transaction surge capacity. Tokyo metropolitan merchant clusters prioritize sub-100-millisecond authorization speeds for high-velocity retail.
Global Cloud POS Market Competitive Landscape
The competitive structure tilts toward integrated hardware-software stacks over pure software plays. Horizontal platforms compete on ecosystem breadth while vertical specialists capture hospitality workflow premiums. Two archetypes dominate: commerce-ecosystem anchors and vertical-specific module developers. Strategic moves concentrate on API-driven merchant onboarding and edge-computing terminal partnerships.
Within the integrated-stack tier, Square Inc and Toast Inc exemplify divergent positioning strategies. Square anchors small-business channel dominance through hardware-software cohesion. Toast occupies hospitality-specific workflow depth rather than horizontal expansion. Shopify represents the commerce-ecosystem archetype, embedding POS within broader merchant infrastructure. Oracle Corporation and NCR Voyix Corporation sit within legacy-transition segments serving large enterprise refresh cycles.
| Leading Market Players |
|---|
| Square Inc |
| Shopify |
| Oracle Corporation |
| Lightspeed Commerce Inc |
| Clover Network Inc |
| NCR Voyix Corporation |
| Toast Inc |
| Cegid Group |
| TouchBistro Inc |
| Others |
Supply & Pricing Matrix
Semiconductor foundry capacity for payment terminal chipsets flows from Taiwanese and South Korean fabrication plants through tiered hardware-software bundles, with subscription SaaS models absorbing upfront component costs for small merchants while enterprise buyers negotiate perpetual licensing anchored to dedicated private cloud instances.
Pricing Analysis
Payment processing logic and hardware terminal sales are unbundling into separate subscription tiers. Three-tier pricing structure across premium, standard, and economy levels separates PCI DSS Level 1 certified deployments from basic encryption configurations. Price differentiation rests on vertical workflow depth and API integration complexity. Pricing pressure stems from government-subsidized digitization programs in India compressing entry-level margins. Small businesses exhibit highest price sensitivity, while large hospitality groups absorb premium tiers for kitchen display system integration.
Supply Chain Analysis
India's phased manufacturing program and local-content mandates for government-subsidized POS terminals are reshaping sourcing patterns for terminal assembly. Hardware manufacturing concentrates in China, Taiwan, and Vietnam, with chipset fabrication drawing from TSMC and Samsung foundries. Supply chain risk centers on single-source vulnerability for secure element chips. Distribution runs through direct API-driven onboarding portals displacing traditional ISO reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchant procurement is shifting toward integrated commerce stacks with embedded lending and loyalty modules, favoring vendors with full-stack certification depth over point-solution providers.
For Market Incumbents: Acquire edge-computing terminal firmware capabilities to defend against modular hardware-software decoupling. Consolidate middleware expertise for legacy system integration. Channel control through self-service onboarding portals counters ISO disintermediation threats. For New Entrants and Emerging Players: Channel partners in the United Kingdom's open-banking ecosystem offer lowest-friction entry paths. White-space concentrates in hospitality-specific workflow modules—kitchen display systems, table management, and tip-pooling automation remain underpenetrated by horizontal platforms. Direct API-driven merchant acquisition bypasses traditional field sales overhead. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance certification timelines extend product launch cycles beyond venture-scale runway tolerance. Long-term viability favors platforms with sovereign cloud instance provisioning for GDPR Article 44 adherence. Acquisition targets display vertical workflow depth in quick-service restaurant elasticity management. The signal to watch is central bank digital currency pilot program participation reshaping settlement infrastructure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding POS within broader commerce ecosystems captures merchant lifetime value across Shopify's franchise expansion. |
| Edge-Computing Terminal Partnership | Localized tokenization partnerships with hardware manufacturers ensure transaction continuity during internet outages for US quick-service operators. |
| Regulatory Certification Investment | PCI DSS 4.0 and RBI guideline compliance accelerates product launch velocity for vendors serving Indian government digitization programs. |
| Vertical Workflow Acquisition | Specialized hospitality module development deepens competitive moats against horizontal platform encroachment in full-service restaurant segments. |
| Geographic Expansion | EU-sovereign cloud instance provisioning captures GDPR-mandated data localization demand from transatlantic retail chains. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with payment platform CTOs, hospitality IT procurement officers, channel integration specialists, and regulatory compliance directors informed demand-side assumptions. Secondary sources include PCI Security Standards Council certification databases, RBI circulars on digital payment infrastructure, SEC filings from publicly traded POS vendors, and EU GDPR implementation guidance documents. Bottom-up merchant adoption modeling triangulated against top-down cloud infrastructure spend forecasts.
Rate-of-change decomposition separates hardware refresh cycles from SaaS subscription expansion across the analysis window. Segmentation dimensions modeled include deployment architecture, solution stack depth, merchant scale tier, and vertical application complexity. CAGR derivation weighted government subsidy program trajectories against semiconductor supply constraint resolution timelines. Forecast inputs incorporated central bank digital currency pilot participation rates and open-banking API mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence in data-localization requirements and chipset supply concentration risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Recruitment Market
Digital Solutions
Construction Design App Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Global Multichannel Campaign Management Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
Contactless Ticketing Solutions Market
Digital Solutions
Legaltech Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Car Wash Management System Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Device As a Service (Daas) Market