
 Virtual Desktop Infrastructure (VDI) Market | 2026-2036
Virtual Desktop Infrastructure (VDI) Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Desktop Infrastructure (VDI) Market Analysis
The EU Green Deal is shifting enterprise IT procurement standards across Europe, pushing organizations toward energy-efficient virtualization platforms. VMware sustains technology leadership through its established hypervisor ecosystem and broad channel partnerships. Citrix competes through specialized application virtualization capabilities that reduce endpoint hardware dependency. Microsoft Azure Virtual Desktop leverages its native cloud integration to dominate public-sector and education deployments.
Virtual Desktop Infrastructure (VDI) is a centralized computing architecture that hosts desktop environments on servers or cloud infrastructure, delivering screen pixels and input signals over networks using protocols such as HDX, PCoIP, or RDP with latency thresholds typically below 150 milliseconds for acceptable user experience. Its primary purpose is to decouple physical hardware from software layers, enabling secure remote work, simplified endpoint management, and centralized data governance across distributed organizations. Cloud deployment models are capturing the fastest expansion as enterprises abandon capital-intensive on-premises data centers, while managed services segments attract margin concentration by bundling infrastructure operations with security monitoring and compliance reporting. Healthcare and finance end-user industries generate premium pricing power due to stringent data residency requirements and zero-trust security mandates.
The EU AI Act and GDPR frameworks impose algorithmic transparency and cross-border data transfer restrictions that directly shape VDI architecture decisions for multinational enterprises operating in Europe. The US HIPAA Security Rule and state-level privacy laws such as California's CCPA compel healthcare and financial services buyers to prioritize VDI solutions with built-in encryption, audit logging, and granular access controls. Stakeholders must evaluate whether their current virtualization stacks can absorb emerging quantum-resistant encryption standards and evolving jurisdictional data-localization requirements without forklift infrastructure replacements.
Market Dynamics
Cloud-native delivery architectures are compressing capital deployment cycles for enterprise desktop virtualization, forcing incumbent vendors to restructure licensing models around consumption-based billing rather than perpetual software agreements.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare and financial services enterprises across Germany, France, and Italy are procuring VDI stacks with embedded algorithmic audit trails to satisfy cross-border data governance requirements.
- Zero-trust security frameworks:Federal agencies and defense contractors in the United States are mandating endpoint isolation through virtualized desktop sessions to reduce lateral movement attack surfaces.
- GPU virtualization advances:Engineering and media production studios are deploying virtual workstations with fractional GPU allocation to enable remote rendering without dedicated physical hardware.
Market Restraints
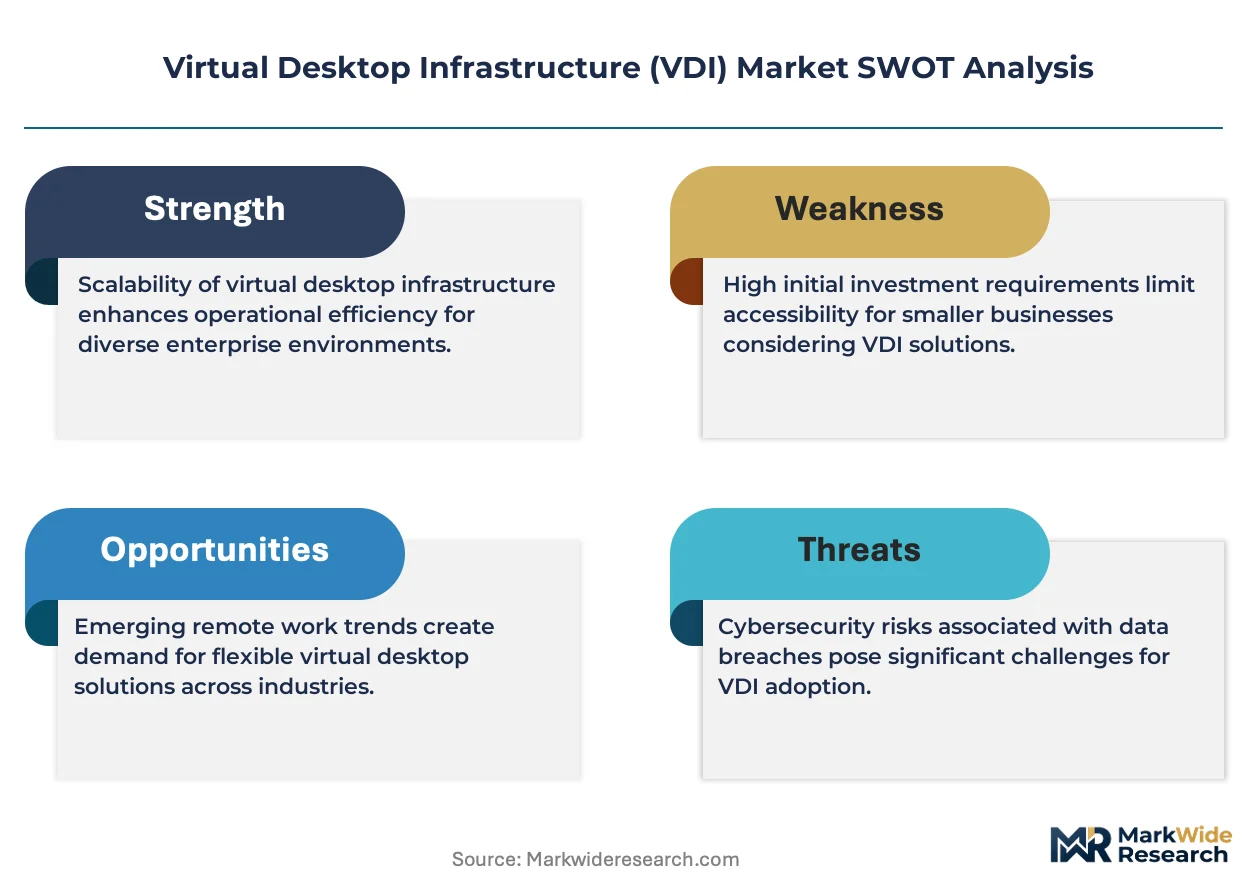
- Bandwidth infrastructure asymmetry:Rural enterprises and developing municipalities lack fiber backhaul capacity to sustain sub-150 millisecond latency thresholds required for acceptable user experience.
- Hypervisor licensing concentration:Enterprise agreements with dominant virtualization platform vendors lock buyers into multi-year commitments that delay migration to alternative architectures.
- Specialized endpoint hardware requirements:Thin client procurement costs and supply chain lead times for cryptographic processing modules offset projected operational savings.
Strategic Opportunities
- Edge computing convergence:Telecom operators are deploying micro-datacenter VDI nodes at 5G base stations to deliver sub-20 millisecond desktop sessions for autonomous vehicle simulation and industrial control.
- Healthcare credentialing modernization:Hospital systems are consolidating physician workstation access through single-sign-on VDI portals that integrate with DEA-controlled substance prescribing workflows.
- EU Green Deal procurement incentives:Public-sector tenders in Spain, Netherlands, and Poland now award technical evaluation points for virtualization platforms with verified power usage effectiveness below 1.3.
Industry Challenges
- Legacy application compatibility gaps:Manufacturing and logistics enterprises running 16-bit industrial control software cannot containerize workloads for modern VDI hosts without expensive emulation layers.
- Multi-cloud orchestration complexity:IT operations teams lack standardized tooling to manage desktop pools spanning AWS, Azure, and private VMware environments with consistent policy enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Desktop Infrastructure (VDI) Market |
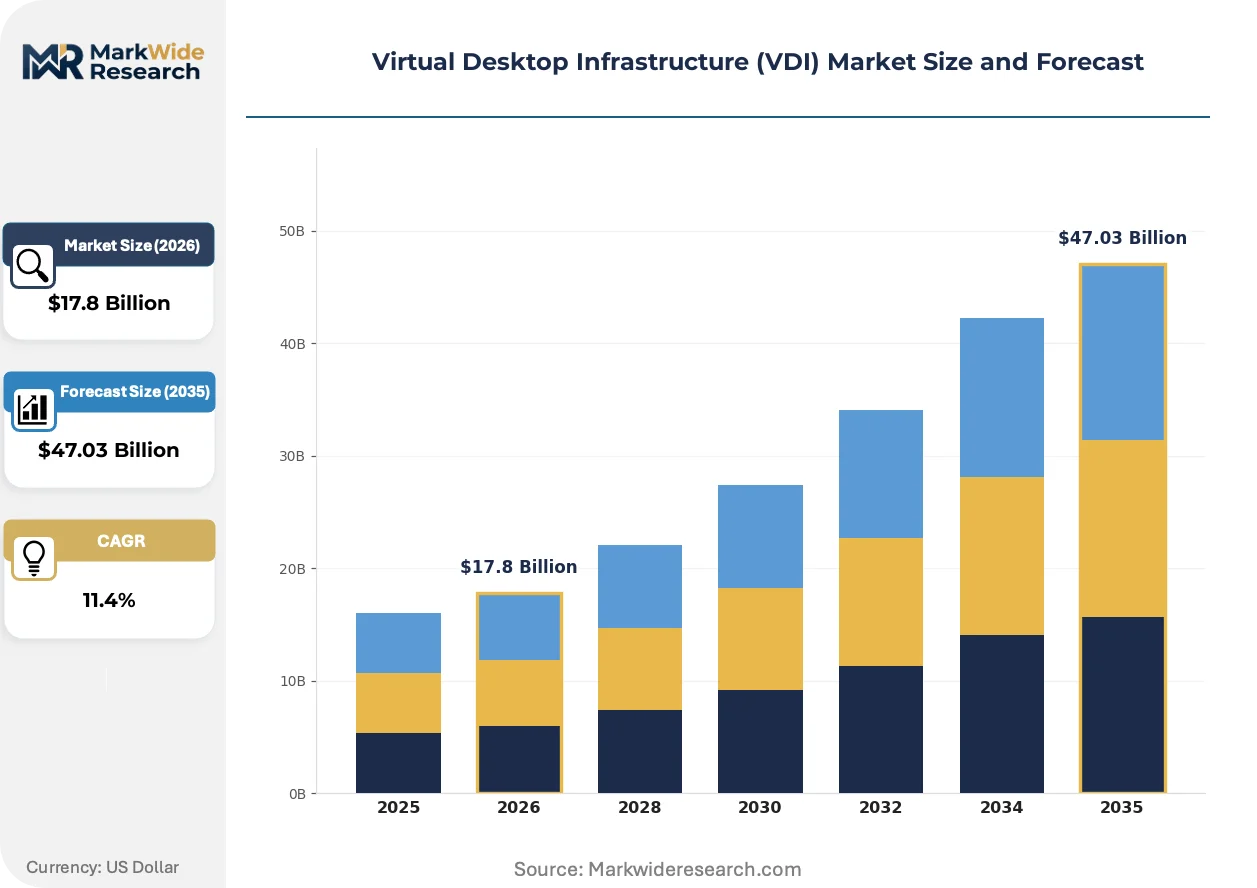
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $47.03 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Managed Services User Type: Small Businesses, Enterprises, Education Sector, Government Agencies End User Industry: Healthcare, Finance, Retail, Technology Solution Type: Hosted VDI, Desktop as a Service, Application Streaming, Virtual Apps |
| Companies Covered | Amazon WorkSpaces, IBM, VMware, Inuvika, Ace Cloud Hosting, Citrix, Omnissa Horizon, vDeskWorks, Microsoft Azure Virtual Desktop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Desktop Infrastructure (VDI) Market Emerging Trajectories
Protocol-level innovation and sovereign data requirements are fragmenting previously standardized virtualization stacks into specialized offerings optimized for specific latency tolerances, compliance regimes, and workload types.
WebRTC-based display protocols are overtaking traditional binary streaming methods in browser-first enterprise environments. SaaS-native organizations with minimal legacy Windows dependencies are adopting HTML5-delivered desktops to eliminate client software distribution overhead. This compression of endpoint requirements is overtaking established thin client hardware refresh cycles and redirecting infrastructure investment toward edge network capacity.
The EU AI Act's algorithmic transparency mandates are compelling VDI architects to deploy session recording and keystroke logging capabilities that satisfy CNIL and BfDI audit standards. Financial services firms operating across Frankfurt, Dublin, and Luxembourg are restructuring data residency zones to ensure model training logs remain within jurisdictional boundaries. Healthcare providers are responding by segmenting patient record access through nationality-specific virtual desktop pools.
Consumption-based licensing is displacing perpetual enterprise agreements across mid-market buyers. Managed service providers are unbundling infrastructure monitoring, security operations, and helpdesk functions into separately contracted service tiers. This decomposition is most visible in United States state government and K-12 education verticals, where procurement officers lack capital authorization for multi-year software commitments.
Virtual Desktop Infrastructure (VDI) Market Segmentation
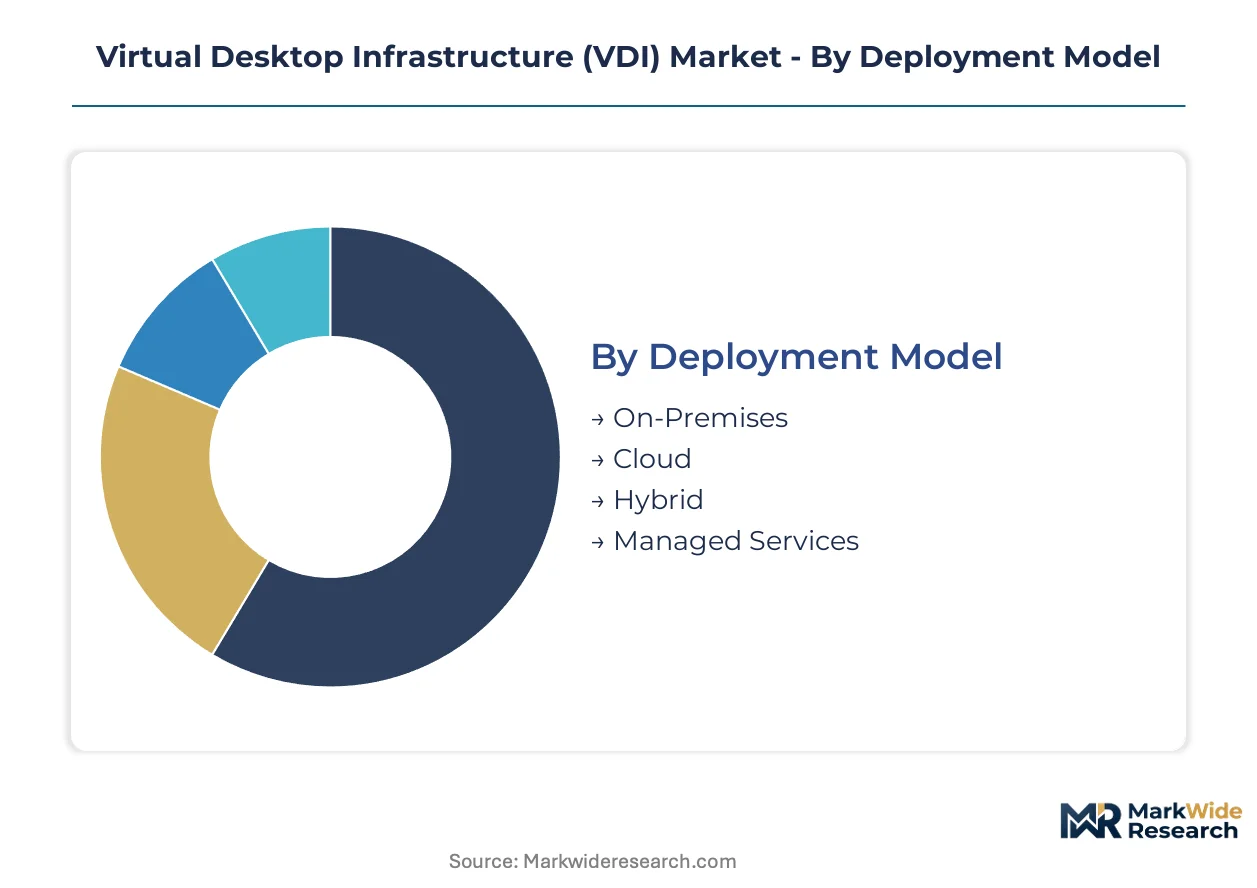
VDI procurement patterns diverge sharply across deployment architectures and organizational scale, with compliance mandates and latency requirements dictating technology selection. Understanding these fault lines reveals where vendor consolidation and margin compression concentrate.
Deployment Model:
Supply concentration tilts toward cloud-native platforms as hyperscalers absorb infrastructure buildout costs that on-premises vendors cannot match.
- Cloud:Multi-tenant architectures deliver desktop sessions from geographically distributed availability zones with automatic failover. Healthcare systems in Germany and financial services firms in Ireland are migrating here to satisfy GDPR data residency requirements without capital expenditure.
- Managed Services:Third-party operators bundle infrastructure monitoring, patch management, and security operations into per-user monthly fees. United States state governments and K-12 districts lacking internal virtualization expertise are standardizing procurement around these contracts.
- On-Premises:Dedicated hardware stacks in enterprise data centers retain relevance for classified workloads and air-gapped manufacturing environments.
- Hybrid:Split architectures maintain sensitive data on local hosts while bursting graphical workloads to cloud GPU instances.
Cloud absorbs the bulk of installed capacity; Managed Services is expanding most quickly.
User Type:
Cost tier differentiation separates mass-market offerings from specialized compliance-grade deployments with audit documentation and dedicated support channels.
- Enterprises:Multi-thousand seat deployments with complex Active Directory integration and custom application packaging. These buyers negotiate enterprise licensing agreements with VMware and Microsoft that span three to five years.
- Government Agencies:Federal and defense contractors mandate FedRAMP authorization and zero-trust architecture compliance. United States Department of Defense components require endpoint isolation through virtualized sessions to reduce attack surfaces.
- Small Businesses:Sub-hundred user implementations favoring pay-as-you-grow consumption models over perpetual licenses.
- Education Sector:Seasonal enrollment fluctuations drive demand for elastic desktop pools that contract during summer breaks.
Enterprises command the largest aggregate seat count; Government Agencies are climbing the fastest as zero-trust mandates proliferate.
End User Industry:
Application-specific workload requirements fragment standardization, with HIPAA and PCI-DSS frameworks imposing non-negotiable architectural constraints.
- Healthcare:Electronic health record access with DEA-controlled substance prescribing integration and patient data encryption. Hospital systems across France and Italy are consolidating physician workstation access through single-sign-on VDI portals.
- Finance:Trading floor latency sensitivity and cross-border transaction audit trails. Frankfurt and Luxembourg institutions are restructuring data residency zones to ensure model training logs remain within jurisdictional boundaries.
- Retail:Seasonal workforce scaling and point-of-sale system isolation across distributed store locations.
- Technology:Software development environments with containerized build pipelines and GPU-accelerated testing.
Healthcare absorbs the bulk of compliance-driven premium pricing; Finance is gaining share fastest as algorithmic trading demands sub-20 millisecond desktop sessions.
Solution Type:
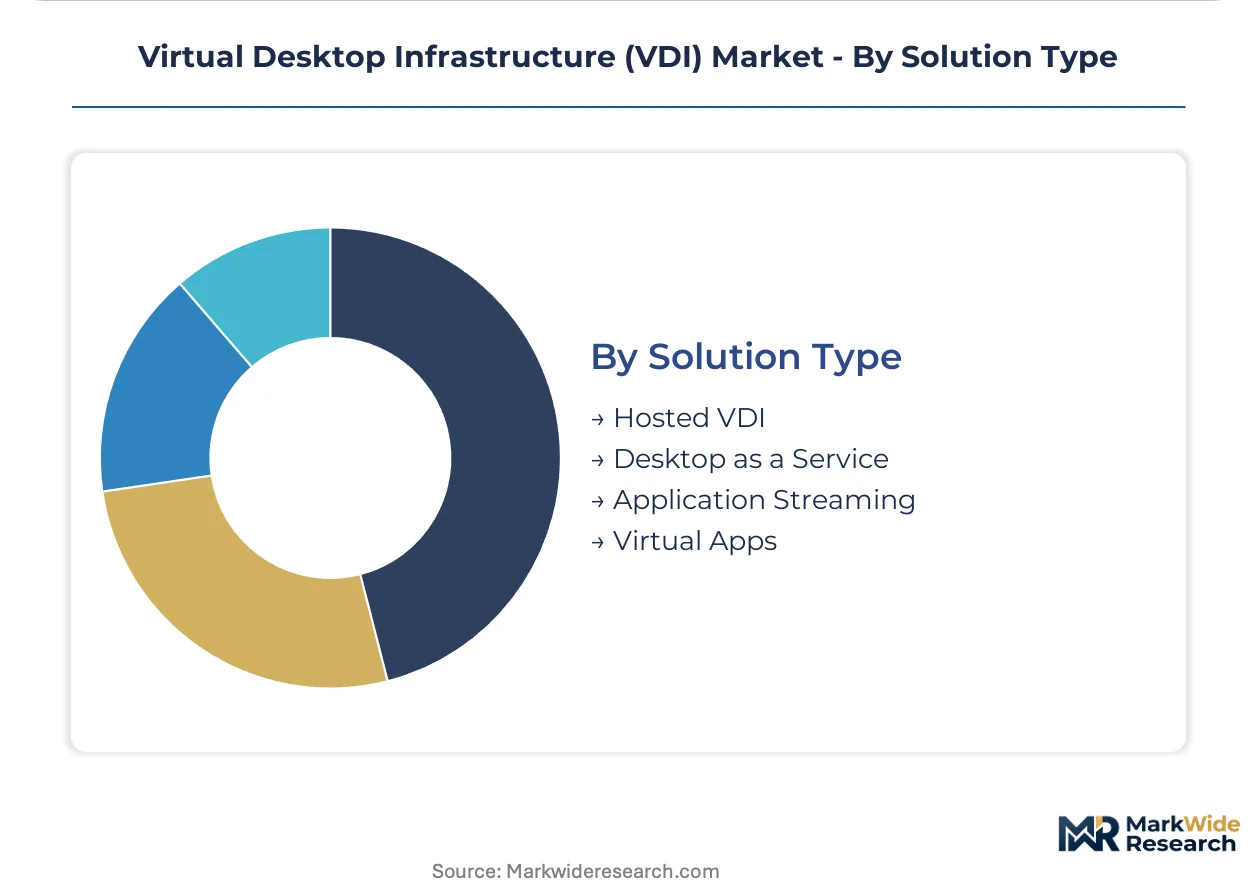
Technology maturity separates established hosted platforms from emerging application streaming protocols that eliminate persistent desktop overhead.
- Desktop as a Service:Fully managed cloud desktops with automated patching and backup. SaaS-native organizations with minimal legacy Windows dependencies are adopting HTML5-delivered sessions to eliminate client software distribution.
- Hosted VDI:Persistent and non-persistent virtual machines running on dedicated or shared infrastructure. Engineering studios in Japan and media production houses in California deploy these with fractional GPU allocation for remote rendering.
- Virtual Apps:Individual application publishing without full desktop presentation, reducing resource consumption.
- Application Streaming:Just-in-time delivery of software packages to local execution environments with centralized license management.
Hosted VDI retains the largest installed base; Desktop as a Service is expanding most quickly as browser-first enterprise environments displace traditional thin client hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's financial district drives continental Europe's densest concentration of latency-sensitive virtual desktop deployments, with trading floors demanding sub-20 millisecond response times for algorithmic execution platforms.
United States
Federal zero-trust mandates and defense contractor requirements propel government agency adoption. The Department of Defense and HIPAA Security Rule compel healthcare systems toward encrypted, audit-logged virtual sessions. Northern Virginia's data center corridor hosts the largest cloud VDI capacity for federal and intelligence community workloads.
Germany
Automotive engineering and precision manufacturing demand GPU-accelerated virtual workstations for remote CAD rendering. BfDI and GDPR frameworks enforce strict data residency for cross-border desktop sessions. Stuttgart's industrial cluster deploys fractional GPU allocation for distributed powertrain design teams.
United Kingdom
Financial services firms in the City of London restructure data residency zones for algorithmic trading compliance. The Financial Conduct Authority's operational resilience rules mandate business continuity through virtualized desktop redundancy. Canary Wharf institutions pilot edge-computing VDI nodes for sub-10 millisecond derivatives pricing.
France
Hospital systems consolidate physician workstation access through single-sign-on VDI portals with DEA-controlled substance integration. CNIL audit standards under the EU AI Act compel session recording capabilities. Paris-Saclay's research cluster deploys sovereign cloud desktops for sensitive genomic data processing.
Japan
Media production houses and gaming studios adopt fractional GPU virtualization for remote rendering pipelines. METI's data localization guidelines shape enterprise architecture decisions. Tokyo's Shibuya content creation district leads Asia-Pacific adoption of browser-first HTML5 desktop delivery.
Virtual Desktop Infrastructure (VDI) Market Vendor Landscape
The competitive structure tilts toward hyperscale cloud platforms with native virtualization stacks. VMware sustains technology leadership through established hypervisor ecosystems and broad channel partnerships, while Citrix competes through specialized application virtualization capabilities. Microsoft Azure Virtual Desktop leverages native cloud integration for public-sector dominance. Strategic moves concentrate on consumption-based licensing restructuring and edge computing micro-datacenter partnerships with telecom operators.
Within the cloud-native tier, Amazon WorkSpaces and Microsoft Azure Virtual Desktop exemplify hyperscale platform strategies, while VMware represents the established on-premises-to-cloud migration archetype. Citrix occupies a position bridging legacy enterprise virtualization with modern application streaming protocols. IBM anchors the managed services and hybrid cloud integration segment for regulated industries requiring sovereign data controls.
| Leading Market Players |
|---|
| Amazon WorkSpaces |
| IBM |
| VMware |
| Inuvika |
| Ace Cloud Hosting |
| Citrix |
| Omnissa Horizon |
| vDeskWorks |
| Microsoft Azure Virtual Desktop |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up managed service providers now dominate mid-market VDI distribution, consolidating regional operators into national platforms that enforce standardized per-seat pricing while squeezing thin-client hardware margins through volume procurement leverage.
Pricing Analysis
Per-user monthly uptime guarantees anchor enterprise VDI contracts, with hyperscalers commanding premium tiers for sub-50 millisecond latency SLAs while mid-market providers compete on bundled security operations. Price differentiation separates FedRAMP-authorized deployments from standard commercial tiers, with healthcare systems in the United States paying substantial premiums for HIPAA audit documentation. Pricing pressure stems from hyperscalers absorbing infrastructure costs that on-premises vendors cannot match, compressing margins for perpetual-license incumbents. Small businesses and K-12 districts exhibit highest price sensitivity, gravitating toward consumption-based models without long-term capital commitments.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for customized Active Directory integration, while managed service providers aggregate fragmented small-business demand through white-label platforms. Supply concentrates in the United States, Germany, and Japan for cryptographic processing modules and GPU virtualization hardware. Component dependencies include fractional GPU allocation chipsets, zero-trust endpoint security modules, and low-latency network interface cards. Single-source vulnerability runs through Taiwan-based semiconductor foundries producing encryption accelerators. Distribution runs through channel partners for on-premises deployments and direct billing for cloud-native consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VDI market has become a vertical-integration race, with hyperscalers pursuing backward control over edge datacenter real estate while incumbents defend through hypervisor software lock-in.
For Market Incumbents: Cement technology leadership by deepening proprietary protocol development around WebRTC and HTML5 delivery standards that eliminate client-side dependencies. Acquire specialized GPU virtualization firms to block hyperscaler encroachment into engineering workstation segments. VMware and Citrix must defend against Microsoft Azure Virtual Desktop's native cloud integration by reinforcing channel partner exclusivity in regulated European healthcare markets. For New Entrants and Emerging Players: Managed service providers in the United States education vertical represent the most penetrable channel partner type, with seasonal enrollment fluctuations creating demand for elastic desktop pools without internal IT expertise. Target rural healthcare systems lacking fiber backhaul capacity by deploying edge-computing micro-datacenter nodes at 5G base stations. Lead with sovereign cloud positioning for EU public-sector tenders awarding technical evaluation points for verified power usage effectiveness. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional managed service providers in Germany and France facing margin compression from hyperscaler competition but holding sticky healthcare compliance relationships. Long-term viability hinges on ownership of edge infrastructure assets rather than software licensing revenue. Watch for inflection where EU AI Act enforcement triggers mandatory session recording upgrades that obsolete legacy virtualization stacks.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Micro-Datacenter Partnership | Telecom operators deploying 5G base station nodes achieve sub-20 millisecond latency for autonomous vehicle simulation workloads. |
| GPU Virtualization Specialist Acquisition | Engineering studios in Japan and California gain fractional allocation for remote rendering without dedicated physical hardware. |
| Sovereign Cloud Certification Investment | CNIL and BfDI audit standards under EU AI Act compel session recording capabilities for cross-border data governance. |
| Consumption-Based Licensing Restructuring | United States state governments and K-12 districts lacking capital authorization adopt pay-as-you-grow procurement models. |
| Zero-Trust Architecture Integration | Department of Defense contractors mandate endpoint isolation through virtualized sessions to reduce lateral movement attack surfaces. |
Methodological Framework
Multi-period observation of hyperscaler capex disclosures and enterprise seat migration patterns anchored the trend analysis, supplemented by interviews with CTOs at healthcare systems, IT procurement officers in financial services, channel partners distributing thin-client hardware, and platform engineers at managed service providers. Secondary validation drew from SEC filings, hyperscaler infrastructure investment reports, hospital procurement databases, and GPO contracts. Bottom-up triangulation across deployment model, user type, and end-user industry segments converged with top-down macroeconomic scenario testing.
Segment-weighting approaches distributed projected growth across cloud, managed services, on-premises, and hybrid deployment architectures, with additional modeling of healthcare, finance, government, and education verticals. CAGRs were derived through regression analysis of historical seat expansion correlated with regulatory mandate timelines and workforce decentralization indices. Forecast inputs included fiber backhaul penetration rates, GPU virtualization adoption curves, and EU AI Act implementation enforcement intensity across member states.
Caveats apply where bandwidth infrastructure asymmetry in rural municipalities or quantum-resistant encryption standard adoption could materially shift the outlook. Forecasts reflect assumptions about hyperscaler pricing discipline and enterprise cloud migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Application Performance Management Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Business Transcription Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Legaltech Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Canada ICT Market
Digital Solutions
Customer Experience As a Service (Cxaas) Market
Digital Solutions
Product Prototyping Market