
 Messaging Platform Market | 2026-2036
Messaging Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Messaging Platform Market Outlook
Mid-market retailers is collapsing the legacy dominance of large enterprises in messaging platform procurement. Twilio leverages its API-first architecture to sustain developer loyalty across programmable messaging stacks. Sinch anchors European carrier relationships to dominate verified SMS and rich communication services.
A messaging platform constitutes software infrastructure enabling real-time, asynchronous, or scheduled digital communication across devices, typically integrating encryption protocols, message queuing systems, and interoperability APIs to support enterprise workflow automation, customer engagement, and internal collaboration. Enterprise messaging leads technology spending as organizations replace fragmented email chains with threaded, searchable conversation records, while cloud messaging represents the fastest-expanding deployment mode as vendors eliminate on-premises maintenance burdens through multi-tenant SaaS architectures.
The EU AI Act and GDPR impose algorithmic transparency and data residency mandates that force platform vendors to localize processing or forfeit European public-sector contracts. The FCC in the US enforces STIR/SHAKEN anti-spoofing protocols that elevate authentication costs for SMS-based business messaging providers. Stakeholders must monitor whether sovereign data requirements fragment interoperability standards or create compliance moats for regionally anchored vendors.
Market Dynamics
Healthcare providers are accelerating secure messaging infrastructure deployment as patient data privacy mandates tighten across multiple jurisdictions, forcing vendors to re-architect cloud stacks for sovereign data residency.
Growth Catalysts
- GDPR data-localization mandates:European public-sector contracts now require in-region processing, creating procurement preference for EU-anchored vendors with certified sovereign cloud architectures.
- Rich Communication Services (RCS) protocol adoption:Mobile carriers are upgrading legacy SMS infrastructure to support verified business messaging with multimedia capabilities and read receipts.
- API-first developer ecosystems:Mid-market retailers are bypassing traditional enterprise sales cycles by embedding programmable messaging directly into e-commerce checkout flows.
Market Restraints
- STIR/SHAKEN compliance costs:FCC authentication protocols for US business messaging elevate operational overhead for SMS-based providers serving North American enterprises.
- Carrier relationship concentration:Verified SMS and RCS capabilities depend on direct operator agreements, creating gatekeeper risk in European and Asian markets.
- End-to-end encryption technical limitations:Lawful intercept requirements in several jurisdictions force architectural trade-offs between security claims and regulatory compliance.
Strategic Opportunities
- German sovereign cloud demand:Enterprises in Germany are prioritizing messaging stacks with domestic data residency, creating white space for regionally certified vendors.
- Healthcare workflow automation:HIPAA-compliant messaging integration with electronic health record systems represents an underpenetrated application segment.
- AI Act algorithmic transparency:EU regulatory tailwinds favor vendors offering explainable routing and content moderation for public-sector deployments.
Industry Challenges
- Legacy system integration complexity:Enterprises maintaining decades-old patient record or inventory management systems face costly middleware development for real-time messaging connectivity.
- Cross-border interoperability certification:Vendors must navigate divergent national encryption export controls and telecommunications licensing regimes simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Messaging Platform Market |
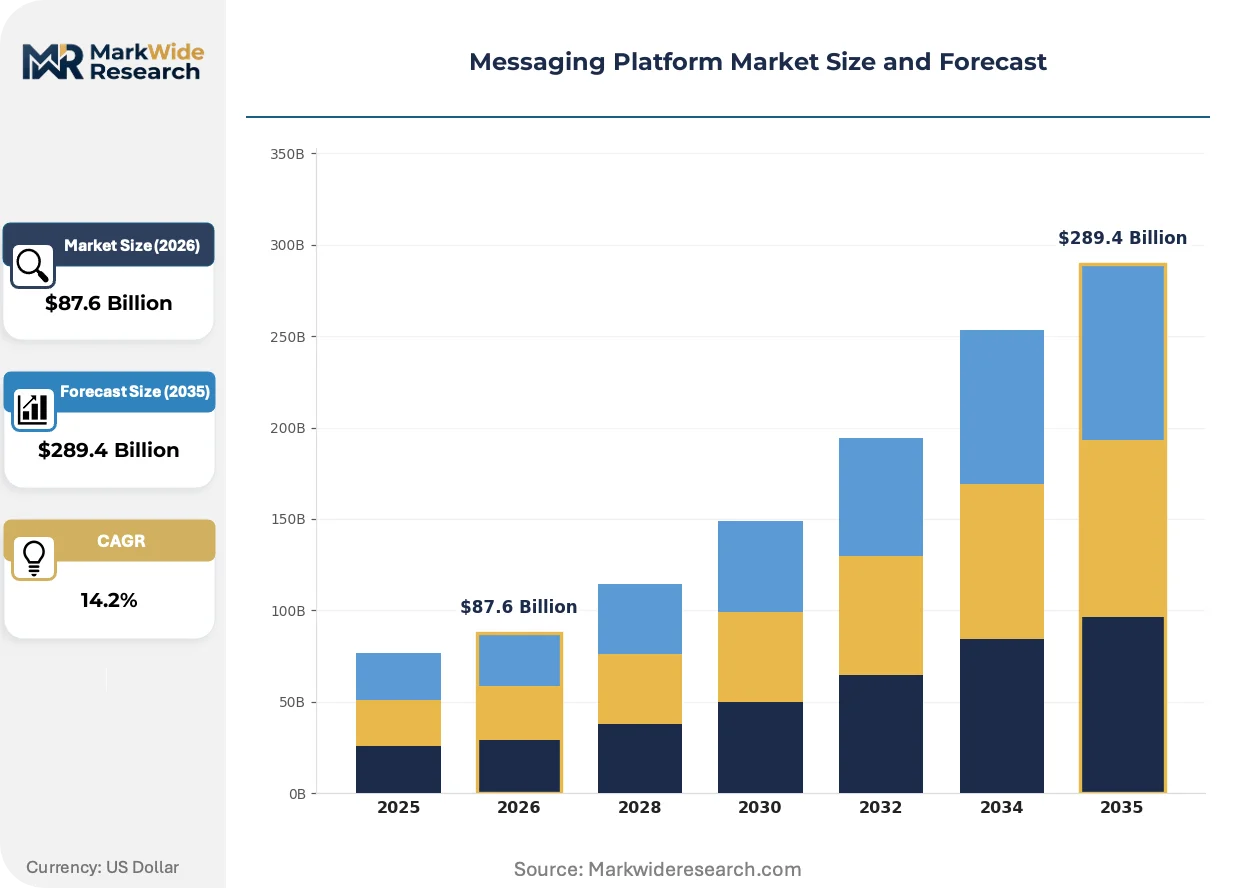
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Messaging, Consumer Messaging, Social Messaging, Cloud Messaging Technology: WebRTC, VoIP, SMS, Push Notifications End User: Businesses, Individual Users, Developers, Organizations Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | SimpleTexting, Sinch, Twilio, Microsoft Teams, Slack, Salesmsg, EZ Texting, Google Chat, Attentive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Messaging Platform Market Strategic Shifts
Real-time messaging infrastructure is undergoing architectural transformation as edge computing, sovereign data requirements, and programmable APIs converge to reshape vendor competitive positioning.
End-to-end encryption is fragmenting the messaging platform landscape as privacy-conscious enterprises demand zero-knowledge architectures for sensitive communications. Financial services firms and healthcare providers are adopting these protocols fastest, creating vendor tiering between security-certified and standard-cloud providers. This technology is fragmenting procurement patterns as buyers segment stacks by data sensitivity rather than consolidating on single platforms.
The EU AI Act imposes algorithmic transparency mandates on automated content routing and moderation systems used in business messaging platforms. Vendors must now document decision logic for message prioritization and spam filtering to retain European public-sector contracts. Healthcare and government verticals are responding by demanding audit trails that satisfy both GDPR and AI Act requirements simultaneously.
Mid-market buyers are consolidating messaging procurement around embedded API solutions rather than standalone enterprise licenses. Retail and logistics segments are replacing multi-year software agreements with usage-based consumption models integrated directly into e-commerce and supply chain platforms. Germany and Nordic markets exhibit this behavioral shift most prominently as digital-native procurement teams gain influence over IT vendor selection.
Messaging Platform Market Segmentation
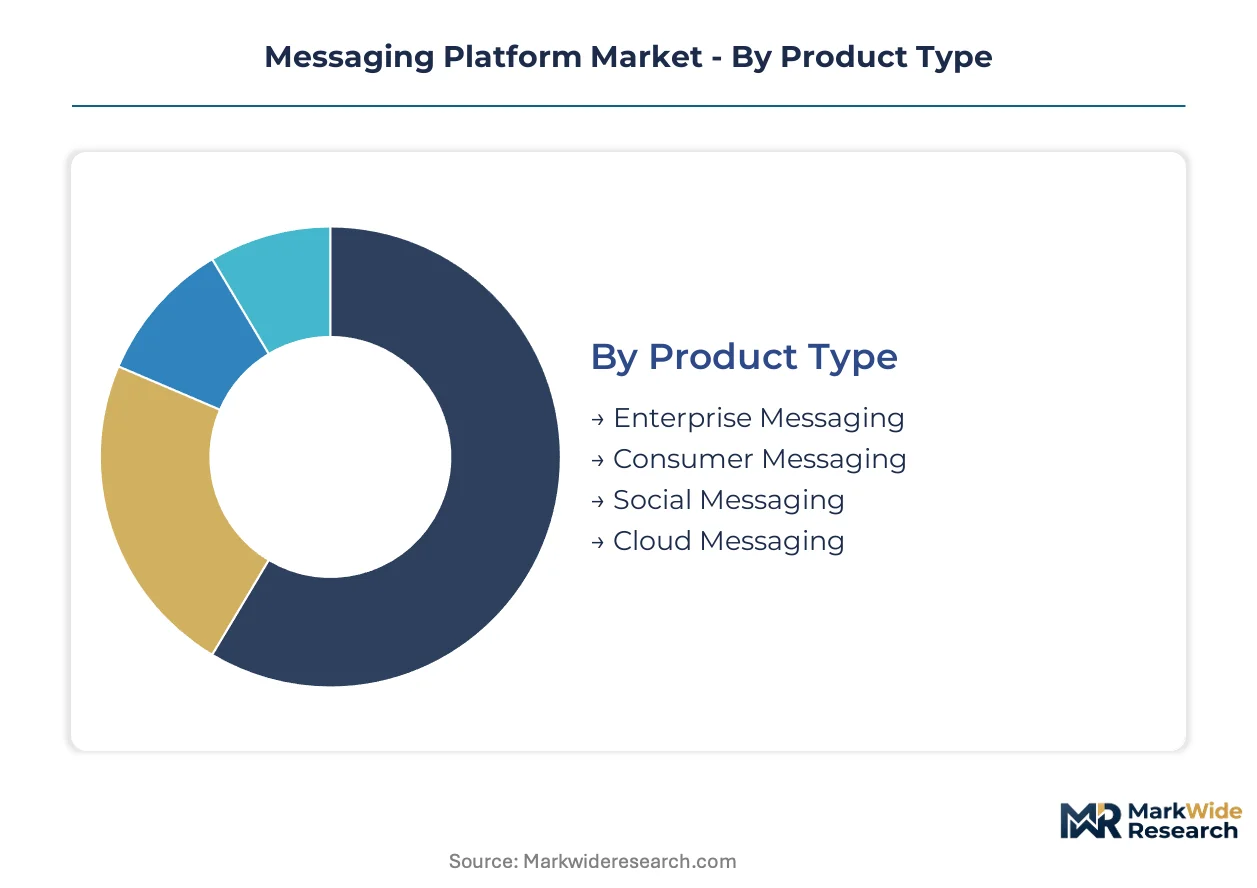
Messaging platform procurement splits sharply across technical architectures and compliance requirements. Buyers segment stacks by data sensitivity, deployment sovereignty, and integration complexity rather than consolidating on single-vendor solutions.
Product Type:
GDPR and HIPAA impose divergent certification burdens that reshape competitive positioning across product tiers. EU AI Act algorithmic transparency mandates favor vendors with documented routing logic for public-sector deployments.
- Enterprise Messaging:Threaded, searchable conversation records replace fragmented email chains in regulated industries. Healthcare providers in Germany and financial services firms in Switzerland drive procurement for HIPAA-compliant and FINMA-aligned stacks with sovereign data residency.
- Cloud Messaging:Multi-tenant SaaS architectures eliminate on-premises maintenance overhead while introducing data localization complexity. German enterprises prioritize domestic sovereign cloud certifications under BSI C5 and ISO 27001 standards.
- Consumer Messaging:End-to-end encryption protocols dominate privacy-conscious user acquisition.
- Social Messaging:Network effects concentrate user bases on integrated platform ecosystems.
Established volume favors Enterprise Messaging; emerging adoption favors Cloud Messaging.
Technology:
Carrier relationship concentration determines market access costs across transmission protocols. Direct operator agreements gatekeep verified messaging capabilities in European and Asian markets.
- Push Notifications:Real-time delivery infrastructure embedded in mobile operating systems enables low-latency customer engagement. Mid-market retailers in Nordic countries integrate these APIs directly into e-commerce checkout flows, bypassing traditional enterprise sales cycles.
- VoIP:Packet-switched voice transmission reduces telecommunications expenditure for distributed workforces. German manufacturing clusters deploy these stacks for plant-floor coordination with centralized quality assurance.
- WebRTC:Browser-native real-time communication eliminates plugin dependencies for video-enabled messaging.
- SMS:Universal device compatibility persists despite RCS displacement pressure.
Legacy infrastructure anchors SMS; API-first developers favor Push Notifications.
End User:
Procurement authority is shifting from centralized IT departments to line-of-business units with platform-native fluency. Digital-native teams influence vendor selection in mid-market segments previously dominated by enterprise sales cycles.
- Businesses:Workflow automation demands integrate messaging with ERP and CRM systems. Healthcare providers in France accelerate secure infrastructure deployment as CNIL enforcement of GDPR patient data mandates tightens.
- Developers:Programmable API ecosystems enable embedded messaging without standalone licensing. Logistics platforms in the Netherlands consume usage-based models integrated directly into supply chain orchestration tools.
- Organizations:Non-commercial entities prioritize cost predictability over feature depth.
- Individual Users:Network effects and encryption claims drive platform selection.
Enterprise procurement concentrates on Businesses; embedded integration favors Developers.
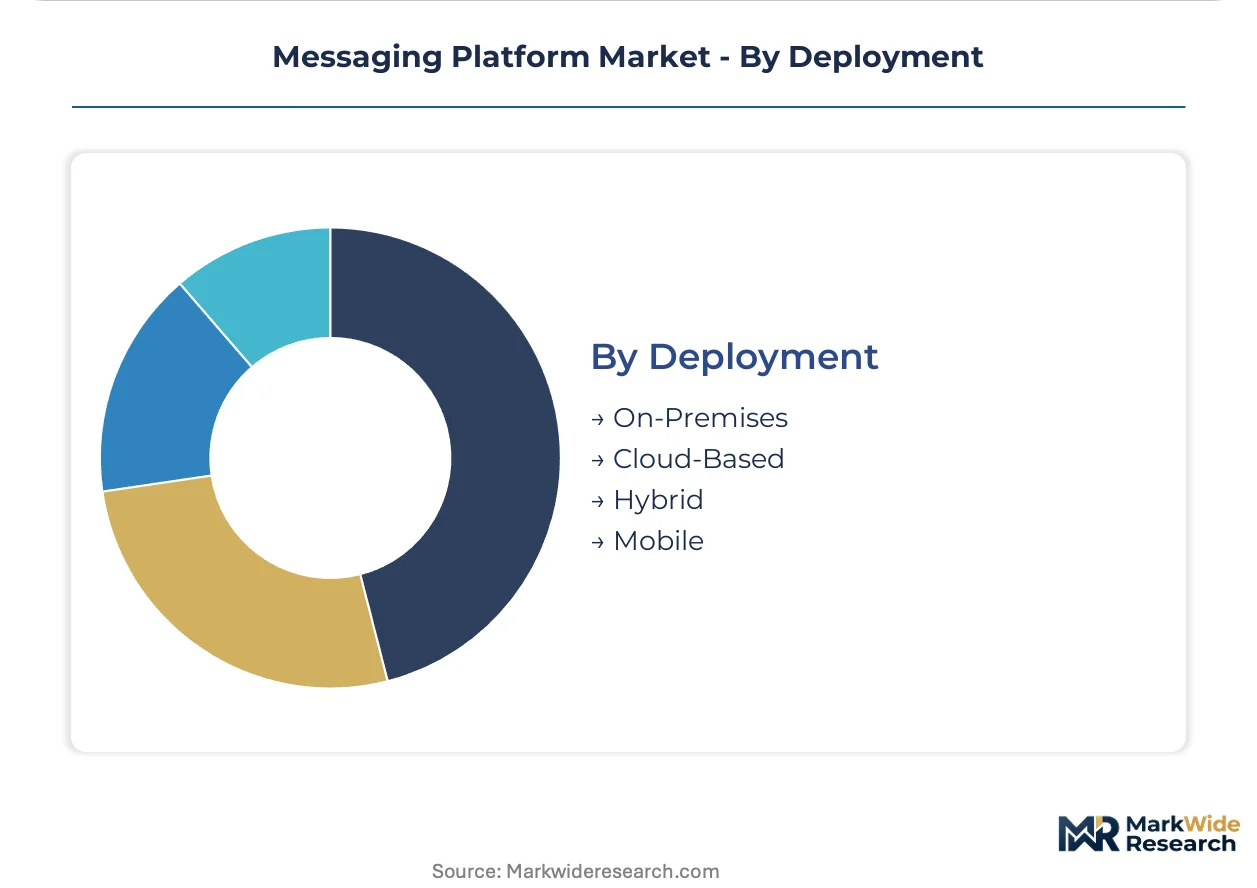
Deployment:
Data residency requirements fragment architectural choices across jurisdictional boundaries. Sovereign cloud mandates in Europe and lawful intercept obligations elsewhere force irreconcilable technical trade-offs.
- Cloud-Based:Vendor-managed infrastructure shifts operational burden to specialized providers. French public-sector contracts now require in-region processing under SecNumCloud certification, creating procurement preference for EU-anchored vendors.
- Hybrid:Split-stack architectures isolate sensitive workloads on-premises while leveraging cloud scalability for routine operations. Swiss banks deploy these configurations to satisfy FINMA outsourcing guidelines without sacrificing operational agility.
- On-Premises:Complete data control satisfies highest-sensitivity compliance requirements.
- Mobile:Native application distribution reaches field-based workforces without desktop dependency.
Compliance rigidity favors On-Premises; operational efficiency climbs fastest in Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany and mid-market retailers in the Netherlands are concentrating procurement around sovereign cloud messaging stacks and embedded API solutions respectively. Healthcare providers in France and financial institutions in Switzerland are driving demand for HIPAA-aligned and FINMA-certified platforms with domestic data residency.
United States
Healthcare systems and financial services firms are replacing fragmented email chains with threaded, searchable conversation records. The FCC enforces STIR/SHAKEN anti-spoofing protocols that elevate authentication costs for SMS-based business messaging providers. The Boston-Cambridge corridor hosts biotech clusters deploying secure messaging infrastructure for patient data coordination.
Germany
Industrial manufacturers and automotive suppliers are prioritizing messaging stacks with domestic data residency under BSI C5 and ISO 27001 standards. The EU AI Act and GDPR impose algorithmic transparency and data localization mandates that force vendors to localize processing or forfeit public-sector contracts. The Stuttgart manufacturing cluster deploys VoIP-enabled messaging for plant-floor coordination with centralized quality assurance.
France
Healthcare providers are accelerating secure infrastructure deployment as CNIL enforcement of GDPR patient data mandates tightens across hospital networks. The SecNumCloud certification requirement for public-sector contracts creates procurement preference for EU-anchored vendors with certified sovereign cloud architectures. The Paris-Saclay research cluster integrates messaging platforms with electronic health record systems for workflow automation.
Netherlands
Logistics platforms and mid-market retailers are consuming usage-based messaging models integrated directly into supply chain orchestration and e-commerce checkout flows. The country's national data protection authority aligns with GDPR enforcement patterns that favor vendors with documented routing logic. The Rotterdam logistics hub embeds programmable messaging APIs into container tracking and warehouse management systems.
Switzerland
Private banking and wealth management firms are adopting hybrid deployment configurations to satisfy FINMA outsourcing guidelines without sacrificing operational agility. The Swiss Federal Data Protection and Information Commissioner mandates strict data residency requirements for cross-border financial communications. The Zurich financial center deploys split-stack architectures isolating sensitive client communications on-premises while leveraging cloud scalability for routine operations.
Messaging Platform Market Competitive Environment
Player mix skews toward API-first developer platforms and carrier-anchored verified messaging specialists. The market exhibits moderate concentration with two dominant technology camps competing for enterprise procurement. Strategic archetypes include programmable infrastructure vendors leveraging developer ecosystems, operator-aligned specialists controlling verified SMS and RCS channels, and collaboration suite incumbents bundling messaging with productivity tools. Competitive moves center on sovereign cloud certification acquisition and direct carrier partnership expansion.
Within the API-first tier, Twilio and Sinch occupy distinct positioning vectors. Twilio exemplifies the developer-centric programmable messaging archetype with its infrastructure-as-code approach to enterprise communications. Sinch anchors the European carrier relationship model, representing the operator-aligned specialist path to verified messaging dominance. Microsoft Teams sits within the collaboration suite incumbent category, bundling messaging functionality with broader productivity ecosystems. These three patterns illustrate how vendor strategy fragments across technical architecture choices rather than converging on unified platform delivery.
| Leading Market Players |
|---|
| SimpleTexting |
| Sinch |
| Twilio |
| Microsoft Teams |
| Slack |
| Salesmsg |
| EZ Texting |
| Google Chat |
| Attentive |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with hyperscaler cloud providers lock in compute pricing visibility while securing sovereign data residency certifications for EU public-sector bids. German healthcare systems and French hospital networks favor these arrangements to satisfy CNIL and BSI C5 mandates without exposure to spot-market infrastructure volatility.
Pricing Analysis
Cost-plus contracts indexed to hyperscaler compute rates dominate enterprise messaging procurement. Three-tier pricing structure across premium sovereign-cloud, standard multi-tenant, and economy shared-infrastructure levels reflects certification grade and data residency guarantees. Pricing pressure stems from mid-market retailers adopting usage-based API consumption over traditional seat licensing. Developer-led procurement teams exhibit lowest price sensitivity due to integration switching costs, while healthcare procurement committees negotiate hardest on per-message transactional rates.
Supply Chain Analysis
Inbound logistics costs for specialized encryption hardware from Taiwan and South Korea fluctuate with container availability on Asia-Europe trade lanes. Core infrastructure draws from US hyperscaler regions, Irish data centers, and Singapore carrier hotels for latency optimization. Single-source vulnerability concentrates in RCS gateway providers with exclusive mobile operator agreements. Distribution runs through direct enterprise sales, systems integrator channels, and self-serve API marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent messaging platform vendors face substitution pressure from embedded collaboration suites bundling communications functionality at marginal cost. Defense requires reinforcing differentiation through sovereign certification moats and carrier relationship exclusivity.
For Market Incumbents: Compound carrier partnership depth to gatekeep verified SMS and RCS channels against collaboration suite encroachment. Secure BSI C5 and SecNumCloud certifications ahead of EU public-sector procurement waves. Prioritize backward integration into edge computing infrastructure to reduce hyperscaler dependency and improve margin control on sovereign cloud deployments.
For New Entrants and Emerging Players: Lead with AI Act-compliant algorithmic transparency tooling for French and German public-sector bids where incumbents lack documented routing logic. Target healthcare workflow automation in the Paris-Saclay research cluster with HIPAA-aligned EHR integration. Pursue developer-first land-and-expand through usage-based API pricing embedded in logistics platforms.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-first platforms with embedded integration into e-commerce and supply chain orchestration tools. Long-term viability hinges on sovereign cloud certification portfolios rather than feature velocity. Watch for inflection when German industrial manufacturers consolidate vendor selection around BSI C5-anchored shortlists.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BSI C5 and SecNumCloud credentials unlock German and French public-sector procurement preference. |
| Carrier Partnership Expansion | Direct RCS operator agreements gatekeep verified business messaging capabilities in European markets. |
| API-First Developer Ecosystem | Programmable messaging embedded in e-commerce flows bypasses traditional enterprise sales cycles. |
| Healthcare EHR Integration | HIPAA-compliant workflow automation with hospital systems penetrates underexploited vertical demand. |
| AI Act Compliance Tooling | Documented algorithmic transparency for routing logic satisfies EU public-sector contract requirements. |
Study Parameters
A standing panel of platform engineering directors, healthcare CIOs, carrier partnership executives, and mid-market retail CTOs provided ongoing calibration throughout data collection. Primary fieldwork combined structured interviews with secondary validation against SEC filings of publicly traded vendors, hyperscaler capex disclosures, and carrier infrastructure deployment announcements. Bottom-up segmentation modeling triangulated against top-down market sizing from regulatory procurement databases.
Consistency checks validated volume and value outputs against external benchmarks including cloud messaging traffic disclosures and enterprise software spending surveys. The analytical framework modeled deployment mode, organization size, vertical industry, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro technology spending patterns, incorporating sovereign cloud adoption curves and API-first procurement behavioral shifts.
Underlying assumptions cover sustained GDPR enforcement intensity, stable hyperscaler pricing indices, and continued RCS carrier rollout timelines, with deviation risk concentrated in EU AI Act implementation pacing and lawful intercept regulatory fragmentation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
System Integration Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Supplier Contract Management Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Inventory Management Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Electronic Discovery Market
Digital Solutions
Beacons Management Software Market
Digital Solutions
Super Apps Market
Digital Solutions
United States ICT Market
Digital Solutions
Desktop Virtualization in Manufacturing Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Thin Client Market
Digital Solutions
Customer-To-Customer (C2C) Community Market