
 Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market | 2026-2036
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market Insights
Platform licensing revenue is fragmenting across the drug development value chain as vendors compete for recurring subscriptions tied to molecule progression milestones. Amazon Web Services anchors infrastructure scale through specialized life sciences compliance programs, while Dassault Systèmes specializes in virtual twin environments for process simulation. IBM competes via hybrid cloud architectures that sustain on-premises regulatory workloads alongside elastic compute bursts for genomic analysis.
Cloud-based solutions for drug discovery, development and manufacturing encompass software platforms delivered through remote server infrastructure that enable distributed data storage, computational modeling, and collaborative workflow management across geographically dispersed research teams. These systems integrate machine learning pipelines with electronic data capture protocols to accelerate target identification, optimize clinical protocol design, and monitor manufacturing deviations in real time. Clinical trials and data management services within the Service Type dimension capture the deepest margin pools due to lengthy validation cycles and stickiness from regulatory audit trails. The Application segment shows biomarker discovery and drug repurposing attracting accelerated investment as sponsors seek to de-risk portfolios by mining existing compound libraries against new indications.
FDA enforces 21 CFR Part 11 compliance for electronic signatures and audit trails, while EMA's GxP guidance demands IQ/OQ/PQ qualification for cloud systems handling patient data across European multi-site trials. India's CDSCO has begun aligning data localization requirements with cloud deployment architectures for domestic clinical research. Stakeholders must monitor how divergence between FDA, EMA, and CDSCO validation standards shapes total cost of ownership for unified global platforms.
Market Dynamics
Cloud-native platforms are fragmenting enterprise procurement across the drug development value chain as biopharmaceutical sponsors demand modular subscriptions tied to molecule progression milestones rather than monolithic perpetual licenses.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail mandates accelerate validation spending on compliant cloud infrastructure for clinical data management.
- Genomic analysis workloads:Elastic compute bursts for CRISPR screening and variant calling pull hyperscale infrastructure into regulated pharmaceutical environments.
- United States research concentration:NIH-funded institutions and large pharma headquarters in Boston and San Francisco drive enterprise SaaS procurement for distributed trial networks.
Market Restraints
- Cross-border data residency:India's CDSCO localization requirements and EMA GDPR constraints fragment unified platform architectures, inflating compliance engineering costs.
- Legacy system entrenchment:On-premises LIMS and CTMS installations at established sponsors create switching friction that extends sales cycles.
- Specialized talent scarcity:Shortage of professionals holding both cloud architecture certifications and GxP validation expertise restricts implementation velocity.
Strategic Opportunities
- Drug repurposing applications:Cloud-based mining of existing compound libraries against new disease indications attracts portfolio de-risking investment from mid-cap sponsors.
- Brazil's ANVISA harmonization:Emerging alignment with FDA electronic submission standards creates first-mover advantage for validated platform providers.
- Federated learning architectures:Convergence of edge computing with privacy-preserving analytics enables multi-site biomarker discovery without raw data centralization.
Industry Challenges
- IQ/OQ/PQ qualification timelines:EMA GxP validation protocols for cloud systems handling patient data extend deployment schedules across European multi-site trials.
- Hybrid integration complexity:Sustaining regulatory workloads on-premises while bursting genomic analysis to elastic cloud environments demands specialized orchestration engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market |
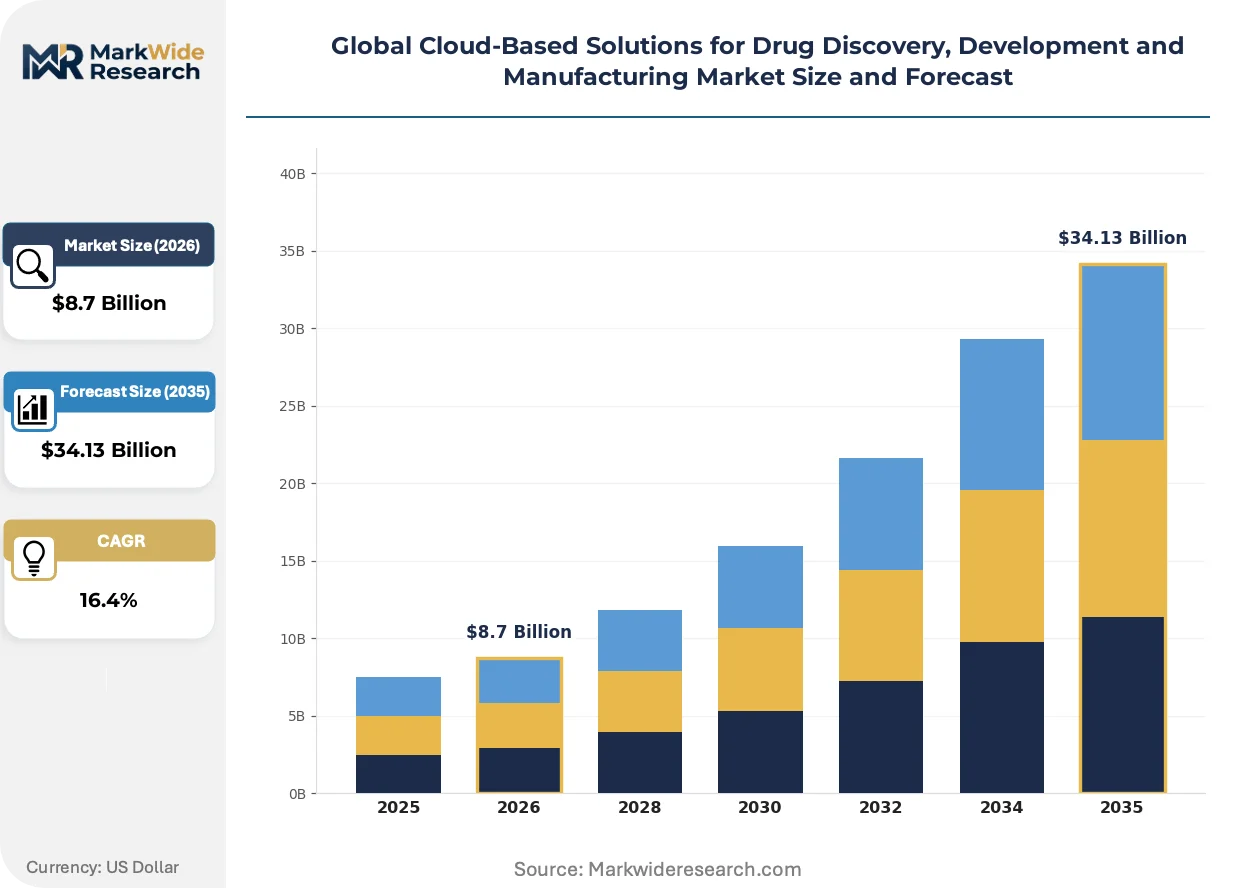
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Trials, Data Management, Software Development, Regulatory Compliance Technology: Machine Learning, Big Data Analytics, API Integration, Cloud Computing Application: Biomarker Discovery, Patient Recruitment, Drug Repurposing, Toxicology Studies End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Research Organizations |
| Companies Covered | Amazon Web Services, International Business Machines (IBM), Accenture, Oracle, Tata Consultancy Services, Dassault Systèmes, WuXi AppTec, Google, Alibaba Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market Trends and Innovations
Machine learning pipelines are compressing traditional discovery timelines while regulatory frameworks force architectural decisions that separate compliant core systems from experimental compute layers.
Digital twin environments for process simulation are collapsing the distinction between development and manufacturing phases. Biopharmaceutical sponsors in Switzerland and Germany deploy these virtual replicas to predict scale-up failures before physical batch production. Dassault Systèmes and specialized vendors capture recurring revenue by embedding physics-based models within cloud-native manufacturing execution systems.
EMA's GxP guidance on computer system validation is tightening qualification requirements for software-as-a-service handling clinical trial data across European multi-site studies. Sponsors must now demonstrate infrastructure control equivalence to on-premises deployments, forcing vendors to offer single-tenant configurations with dedicated encryption key management. This regulatory pressure favors established platform providers with existing qualified installations over newer entrants.
Subscription pricing tied to molecule progression milestones is displacing traditional seat-based licensing across mid-cap biopharmaceutical procurement. Sponsors in the United Kingdom and Netherlands increasingly demand usage models that align cloud spending with compound advancement through Phase I, II, and III gates. This consumption pattern compresses vendor revenue recognition cycles while reducing buyer risk on failed programs.
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market Segmentation
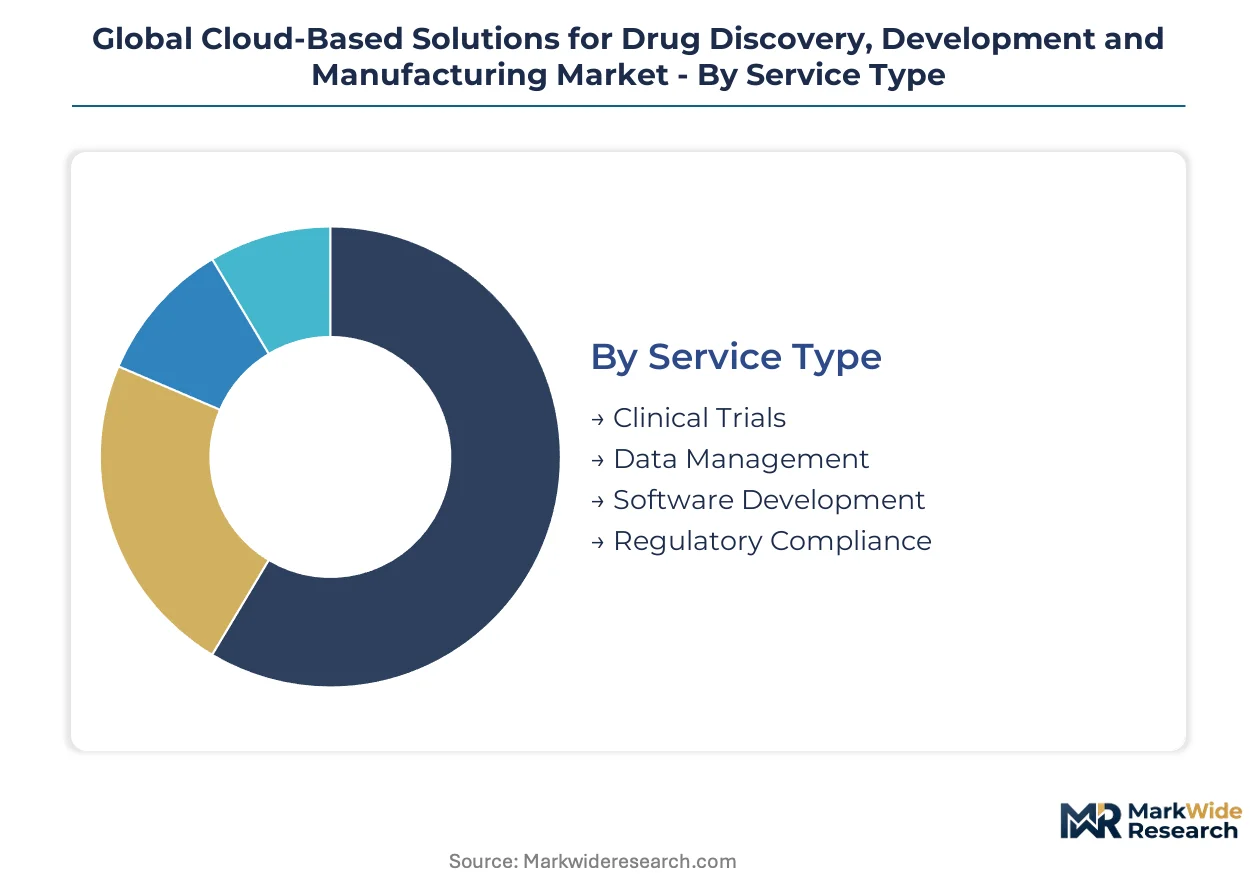
Cloud-based platforms fragment across the drug development value chain through specialized modules targeting discrete workflow stages. Procurement patterns diverge sharply between validated core systems and experimental compute layers, creating tiered vendor positioning across service, technology, application, and end-user dimensions.
Service Type:
Use-case spectrum spans regulated data handling through exploratory software engineering, with validation burden determining margin capture.
- Clinical Trials:Real-time orchestration platforms manage protocol deviations, site monitoring, and patient safety across distributed networks. NIH-funded institutions in the United States and large pharma headquarters in Boston drive enterprise-scale procurement for multi-site studies. FDA 21 CFR Part 11 compliance requirements extend sales cycles but lock in recurring revenue through audit trail dependencies.
- Data Management:Electronic data capture systems with elastic storage architectures handle genomic datasets and imaging repositories. Demand concentrates at biopharmaceutical sponsors running CRISPR screening campaigns requiring burst compute capacity. EMA GxP guidance on infrastructure control equivalence favors single-tenant configurations with dedicated encryption key management.
- Software Development:Custom pipeline engineering for laboratory information management and manufacturing execution integration.
- Regulatory Compliance:Validation documentation and qualification protocols for IQ/OQ/PQ adherence across multi-jurisdictional submissions.
The dominant share belongs to Clinical Trials, while Data Management is closing the gap fastest.
Technology:
Cost tier separates commodity infrastructure from premium algorithmic capabilities, with integration complexity acting as the pricing fulcrum.
- Machine Learning:Predictive models compress target identification timelines by mining compound libraries against disease pathways. Biotech firms in the United Kingdom and Netherlands deploy these tools for portfolio de-risking through drug repurposing applications. Talent scarcity restricts implementation velocity.
- Big Data Analytics:Federated architectures enable multi-site biomarker discovery without raw data centralization. Research institutions in Switzerland and Germany prioritize privacy-preserving analytics for cross-border collaboration. GDPR constraints fragment platform architectures.
- API Integration:Standardized connectors linking electronic health records, laboratory instruments, and regulatory submission portals.
- Cloud Computing:Hyperscale infrastructure delivering elastic compute bursts for variant calling and molecular dynamics simulation.
Machine Learning commands premium pricing, though Big Data Analytics expands most quickly among privacy-conscious European sponsors.
Application:
Customer type stratification shows large pharma prioritizing de-risking applications while mid-cap sponsors chase speed-to-clinic.
- Biomarker Discovery:Cloud-native platforms integrate multi-omics datasets to stratify patient populations for targeted therapy development. Contract research organizations in India leverage these capabilities to support domestic clinical research for global sponsors. CDSCO data localization requirements shape deployment architectures.
- Drug Repurposing:Computational screening of approved compounds against new indications reduces development risk and capital requirements. Biotech firms in the United States mine existing libraries to extend patent lifecycles. Subscription pricing tied to molecule progression milestones aligns vendor revenue with compound advancement.
- Patient Recruitment:Digital targeting and site feasibility analytics accelerating enrollment in underrepresented populations.
- Toxicology Studies:Predictive safety modeling and adverse event signal detection for preclinical and post-market surveillance.
Biomarker Discovery holds the largest installed base, with Drug Repurposing gaining share fastest among capital-constrained sponsors.
End User:
Volume concentration tracks R&D spending intensity, with procurement sophistication scaling by organizational maturity.
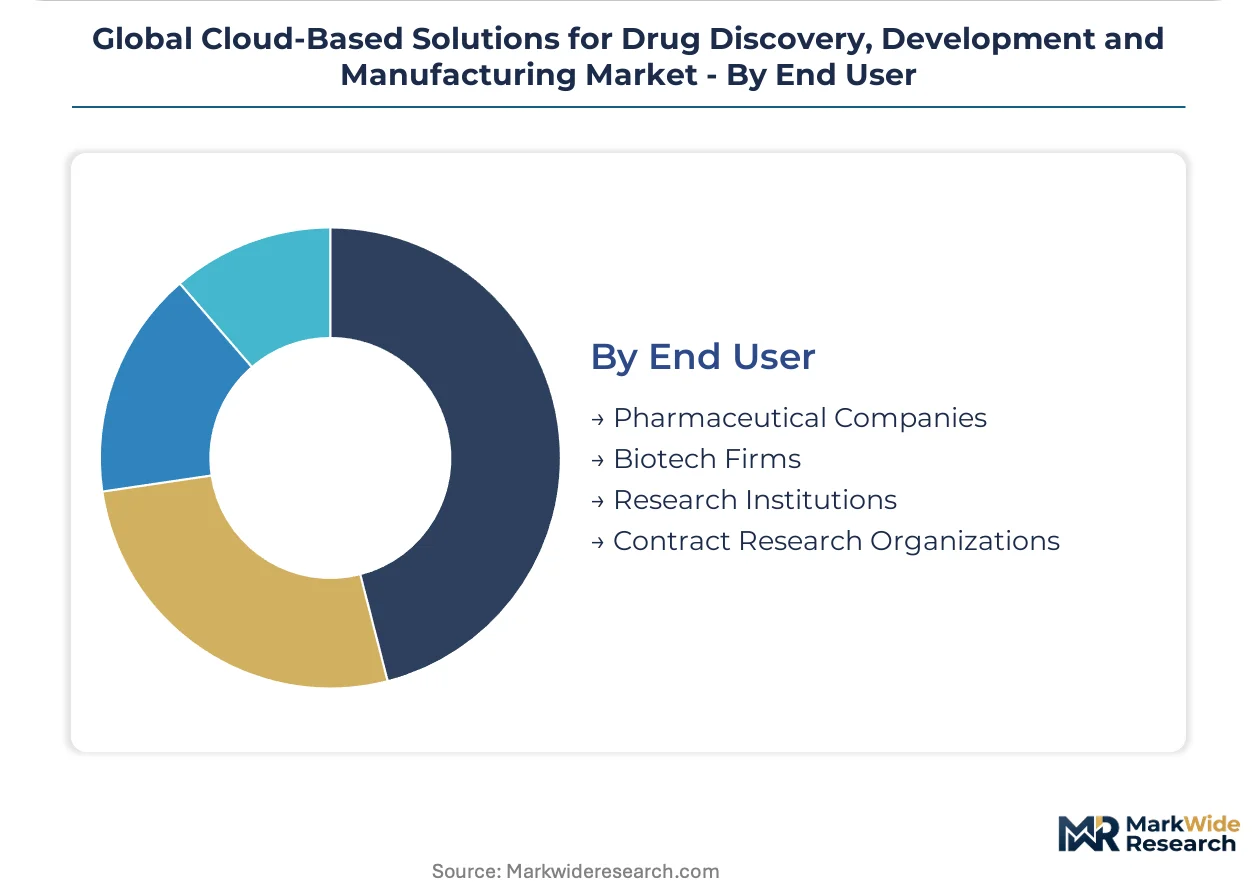
- Pharmaceutical Companies:Enterprise SaaS procurement spans discovery through commercial manufacturing, with hybrid cloud architectures sustaining on-premises regulatory workloads alongside elastic compute bursts. Headquarters in San Francisco and Boston anchor global deployment decisions.
- Biotech Firms:Modular subscriptions tied to financing rounds and clinical milestones dominate purchasing patterns. Mid-cap sponsors in the United Kingdom and Netherlands demand usage models that reduce risk on failed programs.
- Research Institutions:NIH-funded academic medical centers driving federated learning pilots and open-source tool development.
- Contract Research Organizations:Multi-sponsor platform access requiring segregated data environments and client-specific validation documentation.
Pharmaceutical Companies retain the deepest platform commitments, while Biotech Firms represent the steepest expansion trajectory as financing flows into cloud-native discovery tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States sponsors prioritize elastic compute for genomic screening, while European institutions emphasize privacy-preserving federated architectures, and Indian contract research organizations navigate data localization mandates for global trial support.
United States
NIH-funded academic medical centers and large pharma headquarters in Boston and San Francisco drive enterprise SaaS procurement for distributed clinical trial networks. FDA 21 CFR Part 11 compliance requirements for electronic signatures and audit trails extend sales cycles but lock in recurring revenue through regulatory dependencies. The Greater Boston cluster anchors global deployment decisions for multi-site oncology studies.
Germany
Biopharmaceutical sponsors deploy virtual twin environments for process simulation to predict scale-up failures before physical batch production. EMA GxP guidance on infrastructure control equivalence demands single-tenant configurations with dedicated encryption key management. The Rhine-Main region concentrates manufacturing execution system integration for export-oriented pharma supply chains.
India
Contract research organizations leverage cloud-native platforms to support domestic clinical research for global sponsors while managing cost-sensitive procurement. CDSCO data localization requirements shape deployment architectures and fragment unified platform designs. Hyderabad and Bangalore clusters specialize in biomarker discovery services for Western pharmaceutical clients.
Switzerland
Mid-cap biotech firms demand subscription pricing tied to molecule progression milestones through Phase I, II, and III gates. Swissmedic alignment with EMA validation standards simplifies multi-jurisdictional trial submissions for Basel-area headquarters. The Lake Geneva region anchors precision medicine platforms integrating multi-omics datasets.
United Kingdom
Biotech firms in Cambridge and London mine existing compound libraries for drug repurposing applications to extend patent lifecycles and de-risk portfolios. MHRA post-Brexit regulatory autonomy creates divergence from EMA validation timelines for cloud-based clinical data systems. The Cambridge cluster leads federated learning pilots for privacy-preserving biomarker discovery.
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market Competitive Landscape
Capability concentration sits with specialized platform vendors; scale advantage sits with hyperscale infrastructure providers. The vendor landscape organizes into three tiers: compliance-validated specialists commanding premium pricing, modular SaaS providers capturing mid-market subscriptions, and infrastructure giants anchoring elastic compute capacity. Dominant competitive moves include vertical integration into adjacent workflow stages and geographic expansion through regulatory qualification partnerships.
Within the hyperscale infrastructure tier, Amazon Web Services and Google exemplify scale-driven positioning through life sciences compliance programs. IBM occupies a hybrid architecture position sustaining on-premises regulatory workloads alongside cloud bursts. Dassault Systèmes represents the specialized simulation segment embedding physics-based models within manufacturing execution systems.
| Leading Market Players |
|---|
| Amazon Web Services |
| International Business Machines (IBM) |
| Accenture |
| Oracle |
| Tata Consultancy Services |
| Dassault Systèmes |
| WuXi AppTec |
| Alibaba Cloud |
| Others |
Pricing and Supply Chain Analysis
Elastic compute underutilization in European data centers is compressing infrastructure pricing while simultaneously accelerating vendor consolidation around compliance-validated platforms. This utilization asymmetry between hyperscale regions and regulated pharmaceutical workloads reshapes both supplier investment priorities and buyer procurement leverage across the drug development value chain.
Pricing Analysis
Project-based validation contracts dominate clinical data management procurement, with sponsors purchasing IQ/OQ/PQ qualification packages as discrete milestones rather than perpetual licenses. Price differentiation rests on FDA 21 CFR Part 11 certification tier and single-tenant encryption key management capabilities. Cost compression in mid-market SaaS tiers is intensifying because modular subscription models fragment revenue recognition cycles. Contract research organizations in India exhibit highest price sensitivity, while large pharma headquarters in Boston and San Francisco prioritize compliance assurance over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China in semiconductor components dominates infrastructure procurement risk for cloud-native pharmaceutical platforms. Supply concentration centers on the United States, Ireland, and Singapore for hyperscale data center capacity, while specialized GxP validation engineering draws from Germany and Switzerland. Raw material dependencies include advanced GPUs for genomic analysis, dedicated encryption hardware for patient data isolation, and qualified server components for EMA audit trail compliance. Single-source vulnerability in NVIDIA's AI chip architecture threatens burst compute availability. Distribution runs through direct enterprise sales teams with embedded regulatory consultants rather than channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 11 enforcement acceleration represents the decisive regulatory inflection converting compliance-validated platforms into non-discretionary infrastructure spend.
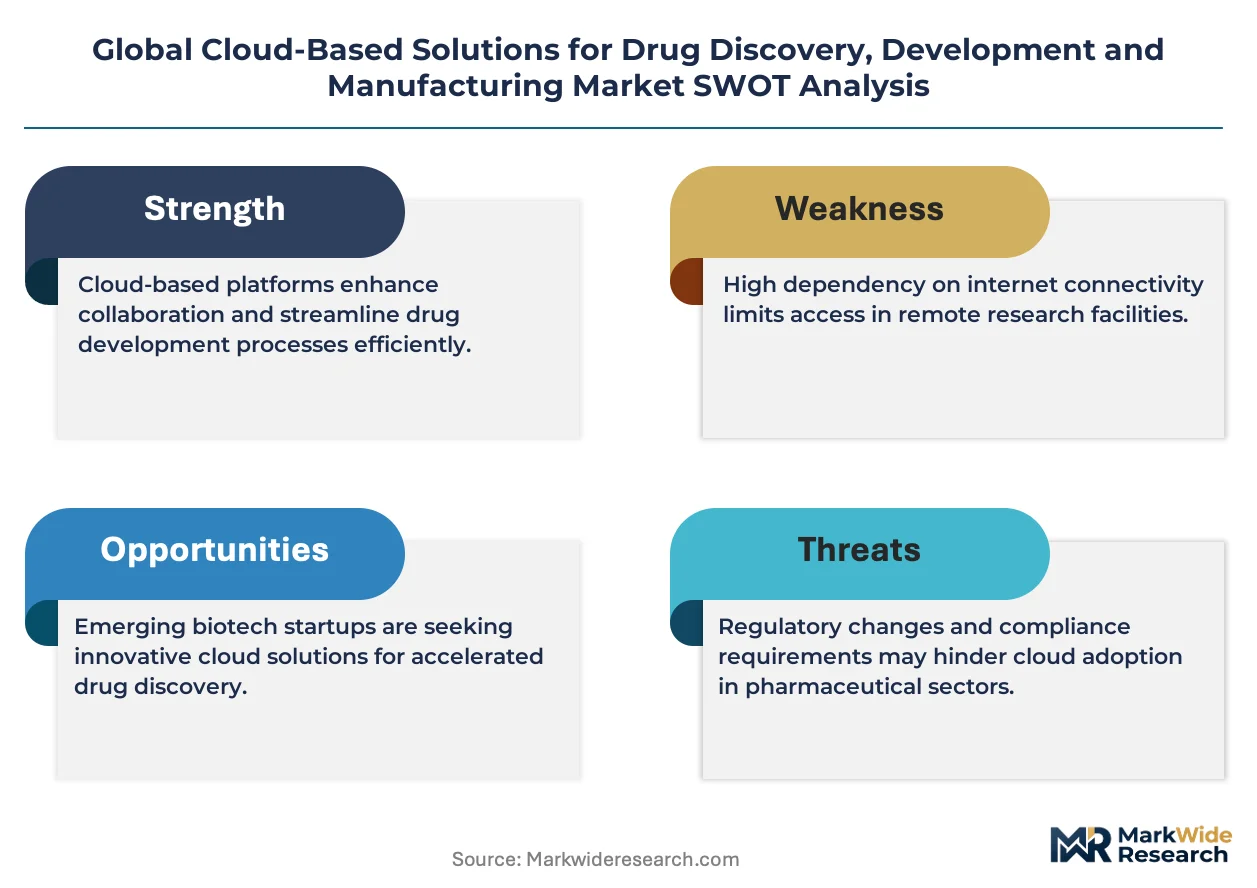
For Market Incumbents: Build switching-cost moats through embedded audit trail dependencies that extend beyond contract expiration. Deepen regulatory qualification partnerships with EMA and Swissmedic to preempt single-tenant configuration mandates. Acquire specialized GxP validation engineering teams in Basel and Boston to compress IQ/OQ/PQ timelines against mid-market challengers. The threat of federated learning architectures enabling multi-site collaboration without platform centralization demands preemptive API standardization investment. For New Entrants and Emerging Players: Biomarker discovery services for Indian contract research organizations represent the most penetrable entry point given CDSCO localization requirements fragmenting incumbent platform architectures. Drug repurposing applications for capital-constrained biotech firms in the United Kingdom and Netherlands offer second-mover subscription pricing disruption. Go-to-market execution should anchor on usage-based models tied to Phase I progression milestones rather than seat-based licensing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among clinical trial orchestration platforms with FDA-validated installations at NIH-funded institutions. Long-term viability across the analysis window favors vendors with demonstrated infrastructure control equivalence to on-premises deployments per EMA GxP guidance. Acquisition target archetype: specialized simulation vendors embedding physics-based models within cloud-native manufacturing execution systems. The signal to watch is ANVISA harmonization with FDA electronic submission standards creating first-mover certification premiums in Brazil.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Partnership | EMA single-tenant mandates favor vendors with existing qualified installations over newer entrants. |
| Federated Learning Architecture Deployment | Privacy-preserving multi-site biomarker discovery reduces raw data centralization compliance burden. |
| Hybrid Cloud Orchestration Engineering | Sustaining on-premises regulatory workloads alongside elastic genomic compute bursts addresses pharmaceutical buyer requirements. |
| Milestone-Linked Subscription Pricing | Usage models aligned to Phase I, II, and III gates reduce buyer risk on failed programs. |
| Validation Documentation Automation | IQ/OQ/PQ protocol generation accelerates deployment schedules across European multi-site trials. |
Research Methodology
The analysis maps clinical trial orchestration, data management services, machine learning platforms, and regulatory compliance modules, each validated through primary interviews with drug development executives, regulatory affairs leads, cloud platform engineers, and contract research organization procurement managers. Secondary sources include FDA 21 CFR Part 11 guidance documents, EMA GxP computer system validation frameworks, ClinicalTrials.gov protocol registries, and hyperscaler life sciences compliance program disclosures. Bottom-up and top-down triangulation reconciles vendor-reported subscription metrics with sponsor-reported cloud infrastructure spending.
Assumptions around FDA enforcement consistency, EMA infrastructure control equivalence interpretation, and CDSCO data localization implementation timelines were held fixed across base-case scenarios while varying genomic analysis workload growth rates and federated learning adoption curves in sensitivity testing. Segmentation dimensions modeled include service type, technology tier, application focus, and end-user organizational maturity alongside regional regulatory cluster differentiation. CAGRs were derived from compound progression milestone velocity and validated platform installation trajectories.
Practitioners should monitor ANVISA harmonization progress, CDSCO localization enforcement intensity, and federated learning standardization initiatives for early signals of architectural preference shifts. Forecasts reflect assumptions about regulatory framework stability and elastic compute cost trajectories; macroeconomic contraction affecting biotech financing flows, abrupt regulatory divergence between FDA and EMA validation timelines, or breakthrough edge computing capabilities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Game Engines Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Global Machine Translation (MT) Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Product As a Service Market
Digital Solutions
Global Website Builders Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Media Asset Management (MAM) Solutions Market