
 OSS/BSS Market | 2026-2036
OSS/BSS Market Size, Share, and Industry Trends Forecast 2026-2036
OSS/BSS Market Analysis
Buyer concentration among telecom operators is shifting as tier-one carriers consolidate vendor relationships while mid-tier operators fragment procurement across specialized SaaS providers. Amdocs leverages its managed services heritage to anchor multi-year transformation contracts with North American carriers. Ericsson competes through cloud-native portfolio depth in network management and orchestration layers. Huawei Technologies sustains significant installed-base presence across emerging market operator ecosystems despite geopolitical headwinds.
OSS/BSS denotes the integrated software architecture that telecom operators deploy to manage network operations, customer relationships, service fulfillment, and revenue assurance, encompassing real-time mediation engines that process billions of transaction records daily and policy control functions that enforce quality-of-service rules across 5G slices. Cloud-based deployment models are capturing disproportionate growth momentum as operators retire legacy on-premises stacks in favor of containerized microservices architectures. Billing systems retain the largest installed value base but face margin compression from modular API-first competitors, while service provisioning segments exhibit the fastest expansion trajectory driven by zero-touch network automation mandates.
The Federal Communications Commission shapes OSS/BSS procurement through network reliability reporting requirements and outage disclosure rules that demand granular service assurance telemetry. GDPR and the EU AI Act impose cross-border data governance constraints on customer analytics modules embedded within European operator deployments. Stakeholders must monitor how open-source network automation frameworks from the Linux Foundation and TM Forum interoperability standards reshape vendor lock-in dynamics and platform integration economics.
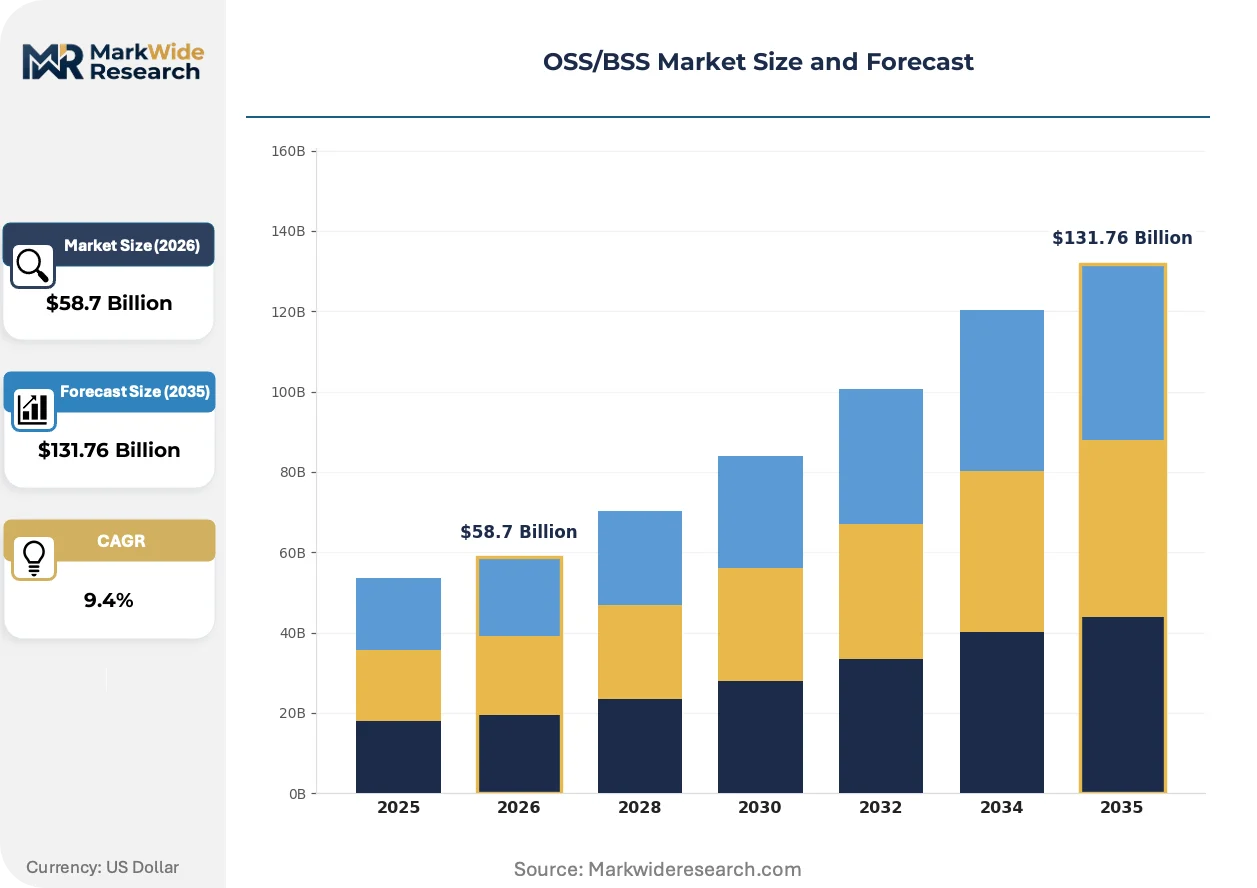
Market Dynamics
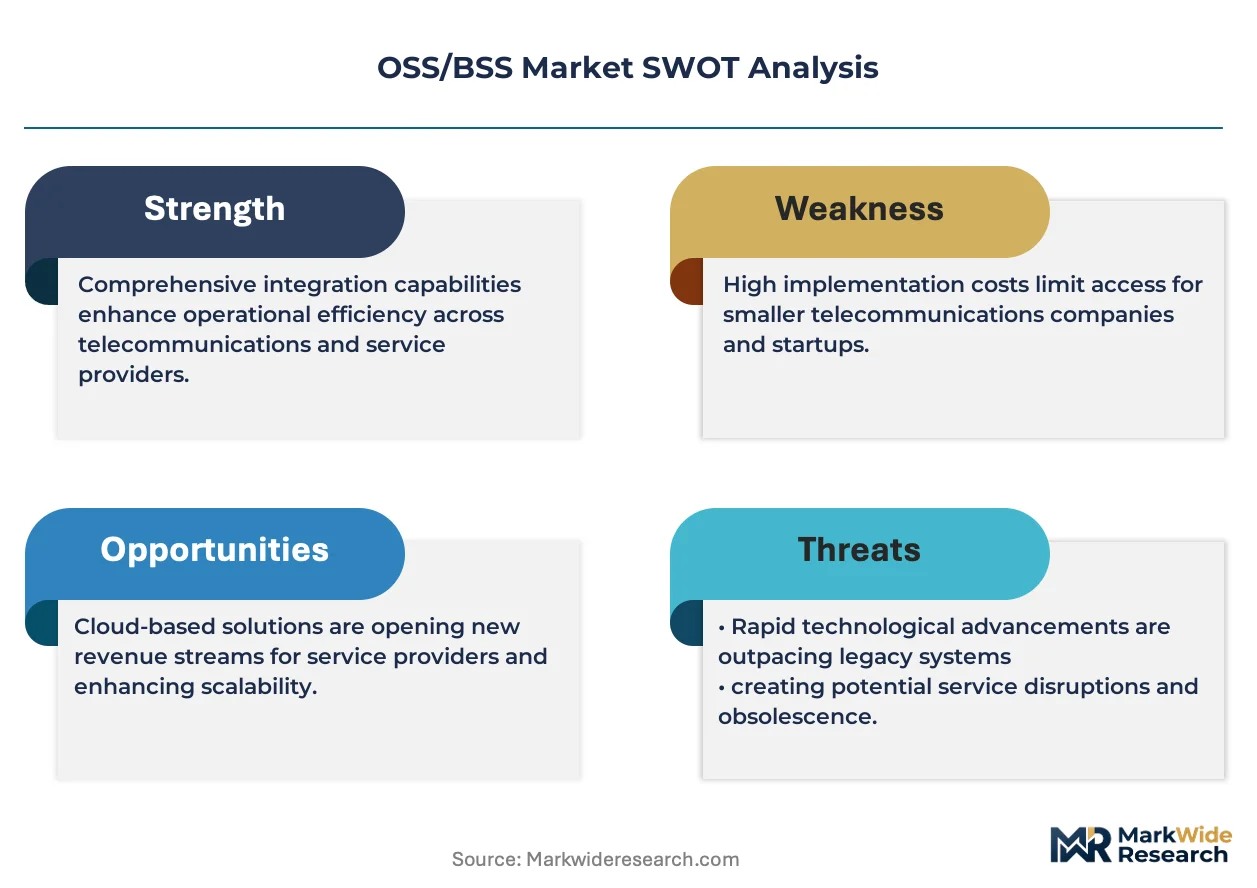
Cloud-native architecture migration is compressing vendor consolidation timelines as telecom operators retire monolithic stacks for containerized microservices, forcing incumbent suppliers to rearchitect portfolios or cede ground to API-first challengers.
Growth Catalysts
- 5G Standalone Core Deployment:Operators in South Korea and Japan are mandating zero-touch service orchestration, pulling real-time policy control investments into billing and provisioning layers.
- GDPR Article 30 Compliance:European carriers must maintain granular subscriber data lineage, accelerating demand for automated revenue assurance and mediation engines with embedded audit trails.
- TM Forum Open APIs:The Open Digital Architecture framework is standardizing interoperability, reducing integration friction for modular BSS components across multi-vendor environments.
Market Restraints
- Legacy Stack Sunk Costs:North American tier-one carriers face $200M-plus write-downs from decade-old Amdocs and Oracle installations, delaying full-cloud transitions.
- Semiconductor Supply Concentration:Taiwan-based foundry constraints are extending lead times for telco-grade server hardware, bottlenecking edge-computing OSS rollouts.
- Geopolitical Vendor Exclusion:FCC supply chain security rules are blocking Huawei equipment from US 5G infrastructure, fragmenting procurement options for integrated OSS/BSS suites.
Strategic Opportunities
- India Digital Communications Bill:The proposed regulatory framework mandates local data centers for subscriber information, creating greenfield demand for indigenous cloud-native billing platforms.
- AI/ML Convergence with Network Automation:Predictive fault management combining machine learning with streaming telemetry is opening premium service tiers for managed OSS offerings.
- API Marketplace Channels:Hyperscale cloud distributors including AWS Marketplace and Google Cloud Partner Advantage are emerging as primary procurement channels for mid-tier operators seeking pre-integrated BSS modules.
Industry Challenges
- Cloud-Native Talent Scarcity:Kubernetes and Helm-chart expertise for telco-grade deployments remains concentrated among Silicon Valley specialists and Bangalore-based system integrators, inflating project costs.
- Multi-Generational Integration Complexity:Operators must maintain SOAP/XML interfaces for 3G-era prepaid systems while deploying REST/gRPC microservices for 5G network slicing, doubling integration test cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OSS/BSS Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Billing Systems, Mediation Solutions, Network Management, Service Provisioning Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Telecom Operators, Municipal Utilities, Internet Service Providers, Enterprises Service Type: Consulting Services, Integration Services, Support Services, Training Services |
| Companies Covered | Amdocs, Ericsson, Huawei Technologies, Nokia Corporation, Netcracker Technology Corporation, Oracle Corporation, NEC Corporation, Comarch SA, Salesforce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OSS/BSS Market Emerging Trajectories
Artificial intelligence is embedding into every layer of OSS/BSS architecture, from predictive churn models in customer management to autonomous incident remediation in service assurance, compressing the gap between data generation and actionable insight.
Intent-based networking software is decentralizing operational decision-making across distributed 5G infrastructures. The technology translates high-level service objectives into automated configuration changes. Tier-one carriers in Germany and Verizon in the United States are deploying IBN for dynamic network slicing. This shift is decentralizing control plane functions from centralized network operations centers toward edge-orchestrated autonomous domains.
The EU AI Act's risk classification framework is imposing algorithmic transparency mandates on automated credit-scoring and fraud-detection modules within European BSS deployments. Carriers must maintain human-in-the-loop oversight for high-risk AI decisions affecting subscriber billing disputes. Nordic operators including Telia and Telenor are restructuring their analytics stacks to embed explainable AI pipelines, prioritizing interpretability over raw predictive accuracy.
Subscription model unbundling is fragmenting traditional multi-year enterprise contracts into modular SaaS consumption. Mid-tier operators in Brazil and Southeast Asia are procuring standalone charging engines and policy managers through metered cloud marketplaces rather than integrated suite purchases. This pattern is most visible among mobile virtual network operators lacking capital for full-stack transformation, who instead stitch together best-of-breed components via TM Forum-standardized APIs.
OSS/BSS Market Segmentation
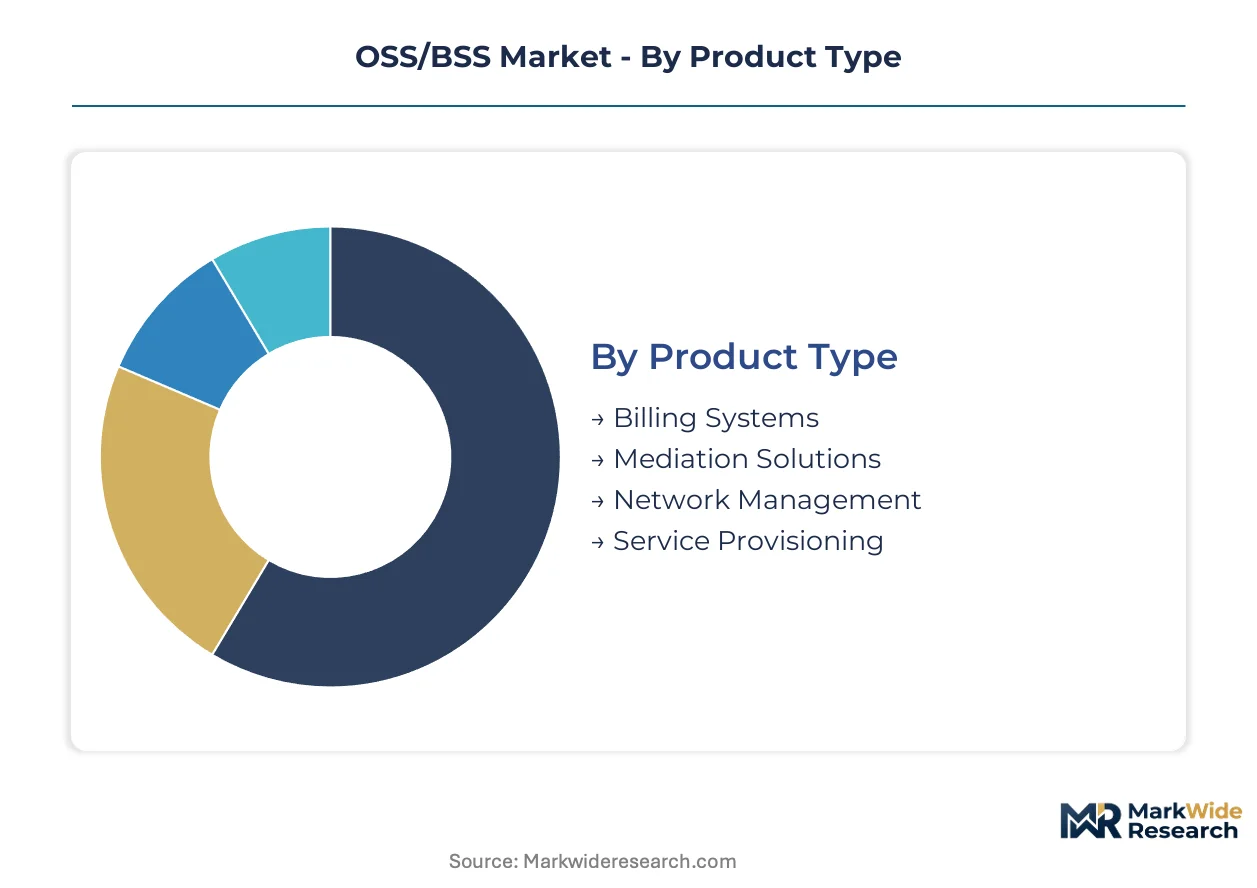
Telecom operators fragment procurement across specialized OSS/BSS modules based on legacy infrastructure maturity, cloud migration timelines, and regulatory compliance mandates. Segmentation reveals how vendor consolidation pressures and API-first challengers reshape competitive positioning across product, deployment, and service dimensions.
Product Type:
Upgrade cycles vary dramatically by product layer, with billing systems carrying decade-old sunk costs while orchestration layers refresh on 18-month cloud-native cycles.
- Billing Systems:Monolithic revenue management platforms process subscriber charging, invoicing, and payment reconciliation across prepaid and postpaid bases. North American tier-one carriers delay full replacements due to $200M-plus write-down exposure, sustaining incumbent Amdocs and Oracle footprints despite margin compression from modular API-first competitors.
- Service Provisioning:Zero-touch network automation engines translate service orders into automated resource allocation across 5G slices. South Korean and Japanese operators mandate intent-based configuration, pulling real-time orchestration investments ahead of billing modernization in procurement priority.
- Mediation Solutions:Real-time transaction processing engines normalize usage records from network elements into billable events.
- Network Management:Fault, configuration, and performance monitoring systems spanning physical and virtualized infrastructure layers.
Volume placements concentrate in Billing Systems; the faster expansion belongs to Service Provisioning.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises estates from operational-expense cloud consumption favored by mid-tier operators and MVNOs.
- Cloud-Based:Containerized microservices architectures deployed across hyperscale infrastructure enable elastic scaling and rapid feature iteration. European carriers accelerate migrations under GDPR Article 30 compliance pressure, demanding granular subscriber data lineage with embedded audit trails.
- Managed Services:Third-party operational control spanning infrastructure, application management, and transformation program delivery. Amdocs leverages multi-year contracts with Verizon and AT&T, anchoring revenue through outcome-based SLAs rather than perpetual license transfers.
- On-Premises:Legacy dedicated hardware and software stacks retained for security-sensitive or latency-critical workloads.
- Hybrid:Mixed estates combining retained on-premises cores with cloud-native edge extensions.
Revenue concentration sits with Managed Services; Cloud-Based deployments are gaining share fastest among new procurements.
End User:
Customer type determines integration complexity, with telecom operators demanding full-stack coherence while enterprises accept modular point solutions.
- Telecom Operators:Mobile, fixed, and converged carriers requiring unified OSS/BSS across network and customer-facing functions. Tier-one consolidation of vendor relationships contrasts with mid-tier fragmentation across specialized SaaS providers, reshaping procurement channel economics.
- Internet Service Providers:Broadband-focused operators with lighter regulatory burdens and simpler service catalogs than full-service carriers.
- Enterprises:Large organizations deploying private 5G networks and internal service management platforms.
- Municipal Utilities:City-owned fiber and smart grid operators with constrained capital budgets and simplified operational requirements.
Demand gravity centers on Telecom Operators; Enterprises show the steepest expansion trajectory as private 5G adoption accelerates.
Service Type:
Margin structure favors recurring support and managed integration over one-time consulting engagements, particularly as multi-generational technology stacks complicate deployment.
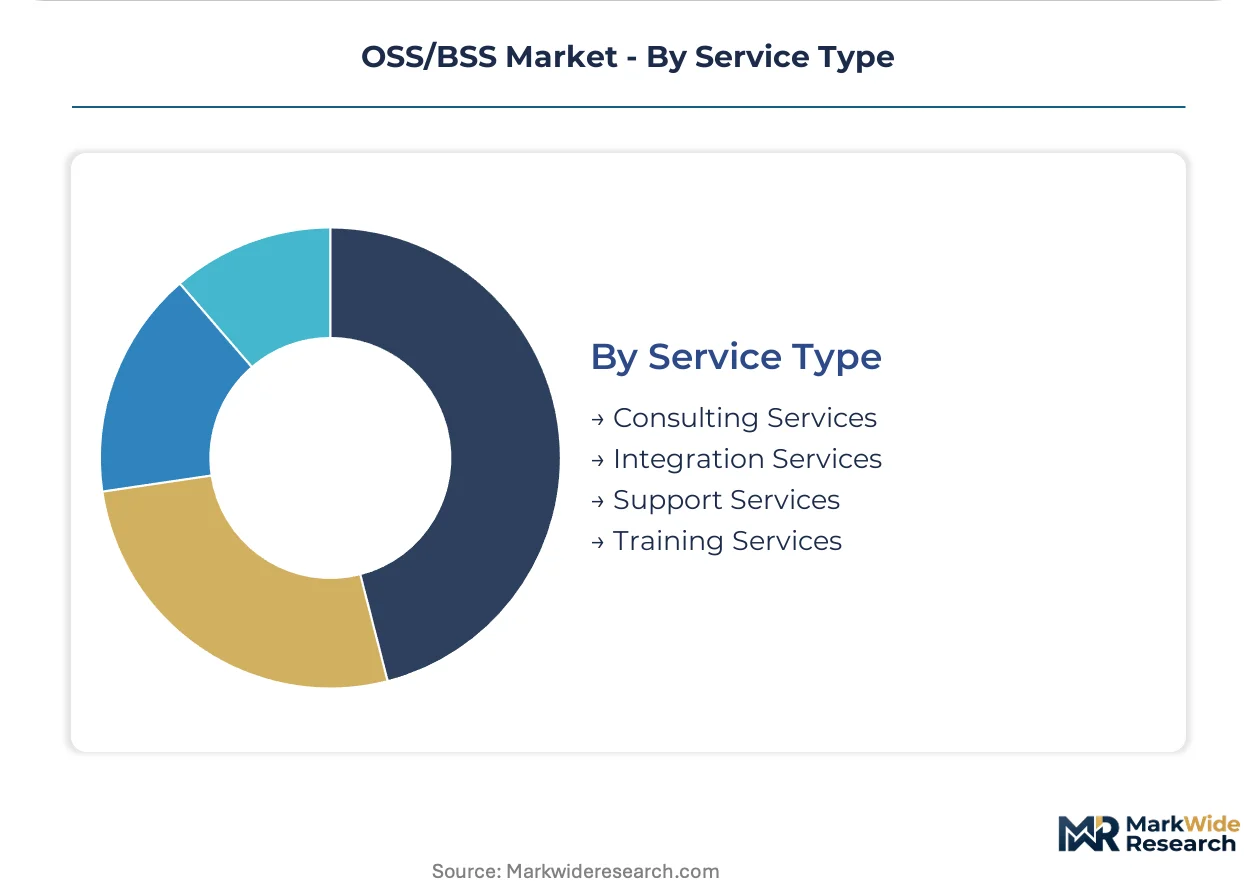
- Integration Services:Multi-vendor platform stitching, data migration, and API harmonization across TM Forum Open Digital Architecture standards. Kubernetes and Helm-chart expertise scarcity concentrates among Silicon Valley specialists and Bangalore-based system integrators, inflating project costs and extending delivery timelines.
- Support Services:Ongoing operational maintenance, incident management, and version upgrade administration. AWS Marketplace and Google Cloud Partner Advantage emerge as primary procurement channels for pre-integrated BSS modules, displacing traditional direct vendor relationships.
- Consulting Services:Transformation strategy, vendor selection, and roadmap development engagements.
- Training Services:Certification programs and knowledge transfer for cloud-native operations competencies.
Revenue stability concentrates in Support Services; Integration Services carry the highest growth slope as migration complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators in the United States concentrate procurement for subscriber management automation and real-time billing infrastructure, while carriers in South Korea and Japan accelerate zero-touch orchestration investments ahead of billing modernization.
United States
Verizon and AT&T anchor multi-year transformation contracts through outcome-based managed services arrangements, prioritizing cloud-native migration over legacy stack replacement. The Federal Communications Commission shapes procurement through network reliability reporting requirements and outage disclosure rules demanding granular service assurance telemetry. Dallas and Atlanta host concentrated vendor delivery centers supporting North American carrier modernization programs.
South Korea
SK Telecom and KT Corporation mandate intent-based networking for dynamic 5G network slicing, pulling real-time policy control investments ahead of billing layer upgrades. The national regulator enforces zero-touch service orchestration standards for standalone core deployments. Seoul anchors the domestic vendor ecosystem, with Pangyo Techno Valley hosting specialized system integrators focused on containerized microservices deployment.
Germany
Deutsche Telekom and Vodafone Germany deploy intent-based networking software for autonomous network management, decentralizing control plane functions toward edge-orchestrated domains. The EU AI Act imposes algorithmic transparency mandates on automated decision-making modules within billing systems. Munich and Düsseldorf concentrate vendor engineering resources supporting European operator cloud migrations.
Japan
NTT Docomo and SoftBank prioritize real-time mediation engines processing billions of transaction records daily across 5G standalone cores. METI guidelines accelerate cloud-native architecture adoption for network automation layers. Tokyo hosts the regional headquarters of major international vendors, with Osaka serving as a secondary cluster for systems integration expertise.
India
Reliance Jio and Bharti Airtel drive demand for indigenous cloud-native billing platforms as the Digital Communications Bill mandates local data centers for subscriber information. TRAI regulations shape data localization requirements for customer analytics modules. Bangalore concentrates Kubernetes and Helm-chart expertise for telco-grade deployments, while Mumbai anchors carrier procurement decision-making.
OSS/BSS Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue API-first modularization and hyperscale cloud marketplace distribution. The vendor base concentrates around three maturity tiers: legacy suite providers with decade-long installed bases, cloud-native specialists capturing mid-tier operator fragmentation, and hyperscale distributors emerging as procurement channels. Strategic archetypes include managed services anchors, orchestration layer specialists, and API-first challengers. Consolidation pressures intensify through multi-year transformation contracts and outcome-based SLA structures.
Within the managed services tier, Amdocs leverages multi-year relationships with North American carriers to anchor revenue through operational control arrangements. Ericsson occupies a position exemplifying cloud-native portfolio depth in network management and orchestration layers. Huawei Technologies sustains significant presence across emerging market operator ecosystems despite geopolitical constraints on integrated suite procurement. These three anchors represent distinct competitive vectors: services heritage, cloud-native technical depth, and emerging market installed-base scale.
| Leading Market Players |
|---|
| Amdocs |
| Ericsson |
| Huawei Technologies |
| Nokia Corporation |
| Netcracker Technology Corporation |
| Oracle Corporation |
| NEC Corporation |
| Comarch SA |
| Salesforce |
| Others |
Supply Flow & Price Mechanics
Tier-one carrier consolidation of vendor relationships into multi-year managed services contracts is compressing pricing flexibility for modular API-first challengers and forcing legacy suite providers toward outcome-based SLA structures that tie revenue to operational metrics rather than perpetual license transfers.
Pricing Analysis
Volume placements concentrate in legacy billing systems with compressed margins, while premium pricing attaches to cloud-native orchestration layers and AI-embedded service assurance modules. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale-managed Kubernetes deployments from self-hosted container estates and retained on-premises cores. Cost compression in standard-tier SaaS subscriptions is intensifying because AWS Marketplace and Google Cloud Partner Advantage disintermediate direct vendor relationships. Mid-tier operators and mobile virtual network operators exhibit highest price sensitivity, while North American tier-one carriers prioritize transformation outcomes over unit cost.
Supply Chain Analysis
Semiconductor supply for telco-grade edge servers rests on Taiwan-based foundry capacity, with secondary sourcing from South Korean memory fabricators and US-based CPU designers. Cloud-native OSS/BSS software draws from container orchestration tools, streaming telemetry pipelines, and machine learning inference engines. Single-source vulnerability in advanced node fabrication extends hardware lead times and bottlenecks edge-computing rollouts. Distribution runs through hyperscale cloud marketplaces, systems integrators in Bangalore and Silicon Valley, and direct vendor relationships for managed services contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in OSS/BSS is becoming a vertical-integration race, with players pursuing downstream control over managed services delivery to capture recurring revenue streams and lock in multi-year transformation engagements.
For Market Incumbents: Anchor revenue through outcome-based SLAs with North American tier-one carriers, extending managed services contracts to cover cloud-native migration programs. Deepen API marketplace partnerships with AWS and Google Cloud to intercept mid-tier operator procurement fragmentation. Counter margin compression from modular challengers by embedding AI/ML capabilities into service assurance layers as premium upsells. For New Entrants and Emerging Players: Kubernetes-native orchestration tools offer a technology-first wedge into South Korean and Japanese zero-touch automation mandates, where incumbent suites lag cloud-native refresh cycles. Target India's greenfield billing platform demand under Digital Communications Bill data localization requirements. Pursue metered consumption models through hyperscale marketplaces rather than direct enterprise sales to bypass incumbent relationship barriers. For Investors and Strategic Acquirers: The window for entry favors cloud-native specialists with proven 5G standalone core deployments and TM Forum Open API certification. Long-term viability hinges on capturing recurring integration services revenue as multi-generational stack complexity deepens. Watch for TRAI and FCC supply chain security rule expansions as regulatory inflection indicators that reshape vendor eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Containerized microservices architectures enable elastic scaling for 5G network slicing deployments. |
| AI/ML Service Assurance Embedding | Predictive fault management modules command premium pricing from Deutsche Telekom and Verizon. |
| Hyperscale Marketplace Partnership | AWS Marketplace and Google Cloud Partner Advantage displace direct vendor channels for mid-tier operators. |
| Managed Services Expansion | Outcome-based SLAs with AT&T and Verizon anchor multi-year recurring revenue streams. |
| Regulatory Compliance Certification | GDPR Article 30 and EU AI Act alignment opens European carrier procurement to qualified vendors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with CTOs at tier-one carriers, IT procurement officers at mobile virtual network operators, platform engineers at systems integrators, and channel partners at hyperscale cloud distributors. SEC 10-K disclosures, TM Forum interoperability certification databases, FCC supply chain security filings, and ETSI standardization documents provided validation layers. Bottom-up deployment model estimates and top-down market sizing triangulated volume and value outputs.
Product type, deployment model, and end user dimensions were modeled at country-level granularity across the analysis window, with additional segmentation by integration complexity tier and regulatory compliance cluster. CAGRs were derived from fitted growth curves against historical deployment trajectories and announced transformation program timelines. Forecast inputs incorporated 5G standalone core rollout schedules, cloud migration capex disclosures, and GDPR enforcement patterns.
Several conditions sit outside the modeled scope, including geopolitical vendor exclusion rule expansions, semiconductor foundry capacity shocks, and open-source automation framework adoption rates that could accelerate or delay vendor consolidation timelines. Forecasts reflect documented assumptions regarding carrier cloud migration velocity and API standardization penetration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
France Digital Twin Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
South Korea Cloud OSS BSS Market
Digital Solutions
Web Performance Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Email Marketing Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Online Dating Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Computer Aided Design (CAD) Market