
 Czech Republic ICT Market | 2026-2036
Czech Republic ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic ICT Market Insights
Public sector agencies are redrawing procurement patterns across the Czech ICT landscape as sovereign cloud requirements displace legacy on-premises contracts. T-Mobile Czech Republic a.s. leverages its nationwide 5G infrastructure to anchor government connectivity tenders, while O2 Czech Republic a.s. competes through specialized cybersecurity bundles for financial institutions. CETIN a.s. sustains critical wholesale fiber backhaul that underpins retail service differentiation across the market.
Information and communications technology in the Czech Republic encompasses software systems, computing hardware, network infrastructure, and associated services governed by EU interoperability frameworks and national cybersecurity standards, primarily serving enterprise automation, public administration modernization, and consumer connectivity. Cloud Services within the Product Type dimension is capturing disproportionate margin expansion as hybrid architectures replace siloed legacy stacks, while Cybersecurity under Technology is attracting accelerated R&D allocation following transposition of the NIS2 Directive into Czech law. The SME segment within End User remains structurally underserved relative to Western European benchmarks, creating whitespace for managed service providers.
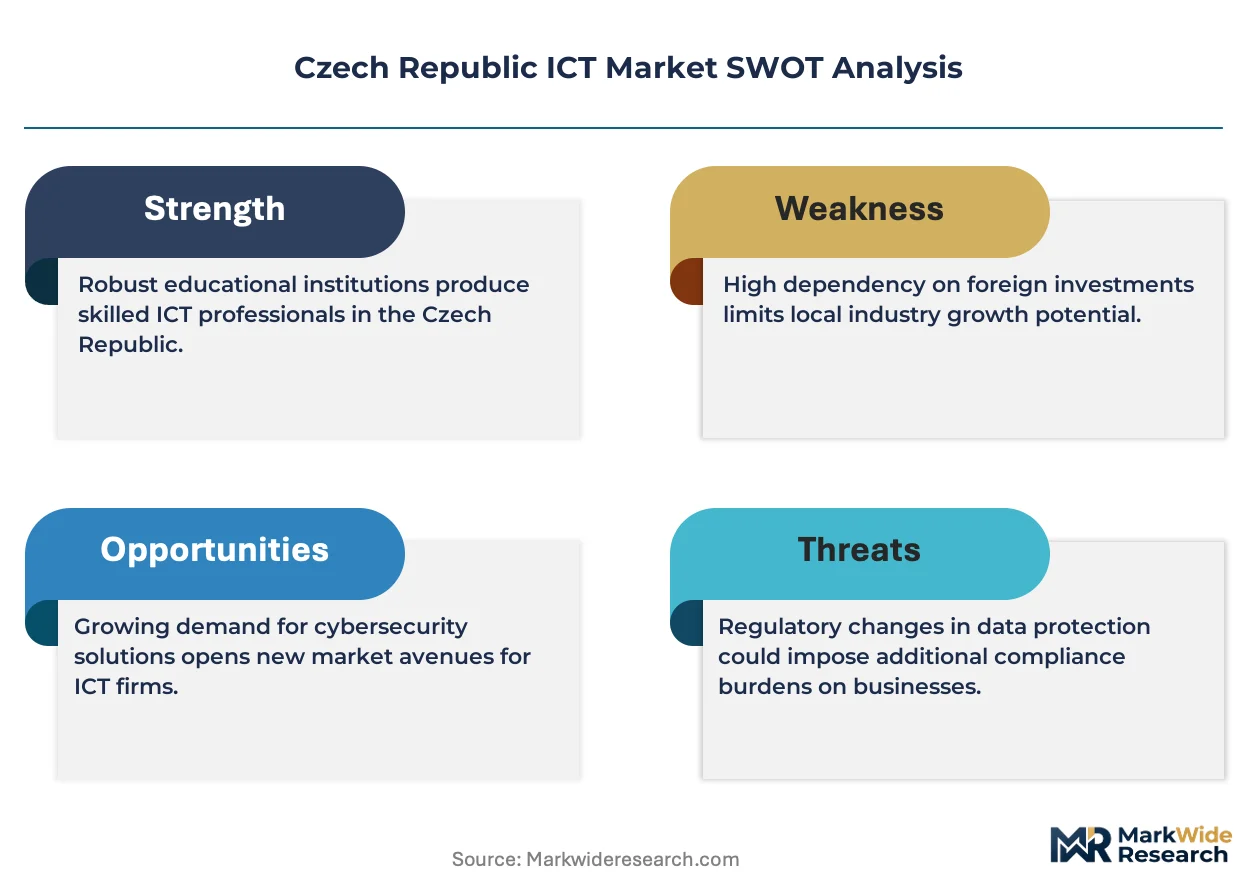
Czech ICT operators navigate oversight from the Czech Telecommunication Office (CTU) for spectrum and network access, the National Cyber and Information Security Agency (NUKIB) for critical infrastructure certification, and BSI-aligned standards for public procurement compliance. NUKIB's mandatory security audits for operators of essential services are reshaping vendor qualification criteria and shortening procurement cycles for pre-certified solutions. Stakeholders must monitor how forthcoming EU AI Act implementation through Czech market surveillance authorities alters liability frameworks for automated decision-making systems deployed in banking and healthcare.
Market Dynamics
Sovereign cloud mandates from Czech public sector procurement are compressing legacy on-premises infrastructure cycles and redirecting vendor qualification toward EU-certified hyperscale providers.
Growth Catalysts
- EU DORA compliance deadlines:Financial institutions in Prague are accelerating cybersecurity procurement to meet operational resilience requirements, creating immediate demand for managed detection and response services.
- NUKIB critical infrastructure audits:Mandatory security assessments for operators of essential services are shortening sales cycles for pre-certified vendors and elevating procurement priority of domestic security solutions.
- Central Bohemia enterprise clustering:Concentration of headquarters functions in Prague and surrounding districts is generating network infrastructure density that supports edge computing deployments.
Market Restraints
- Specialized cybersecurity talent scarcity:Domestic labor pool for cloud security architecture and NIS2 implementation remains shallow relative to Western European benchmarks, inflating project delivery costs.
- Fiber backhaul concentration:Wholesale fiber access depends on limited infrastructure owners, creating margin pressure for retail service providers seeking differentiation.
- Legacy system integration friction:Public administration modernization confronts decades of siled databases and incompatible protocols, extending deployment timelines.
Strategic Opportunities
- SME managed services whitespace:Mid-sized enterprises outside Prague exhibit structural underpenetration versus Western Europe, creating channel expansion potential for regional IT service providers.
- EU AI Act implementation preparation:Banking and healthcare automated decision-making systems require compliance architecture, opening advisory and technical implementation revenue streams.
- 5G private network convergence:Industrial manufacturing facilities in Moravia are piloting campus networks combining T-Mobile infrastructure with on-premise edge compute.
Industry Challenges
- NIS2 transposition complexity:Czech legal adaptation of the directive creates temporary uncertainty in liability allocation between vendors and system integrators.
- Interoperability certification bottlenecks:EU framework compliance testing for public procurement faces processing delays, extending vendor qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic ICT Market |
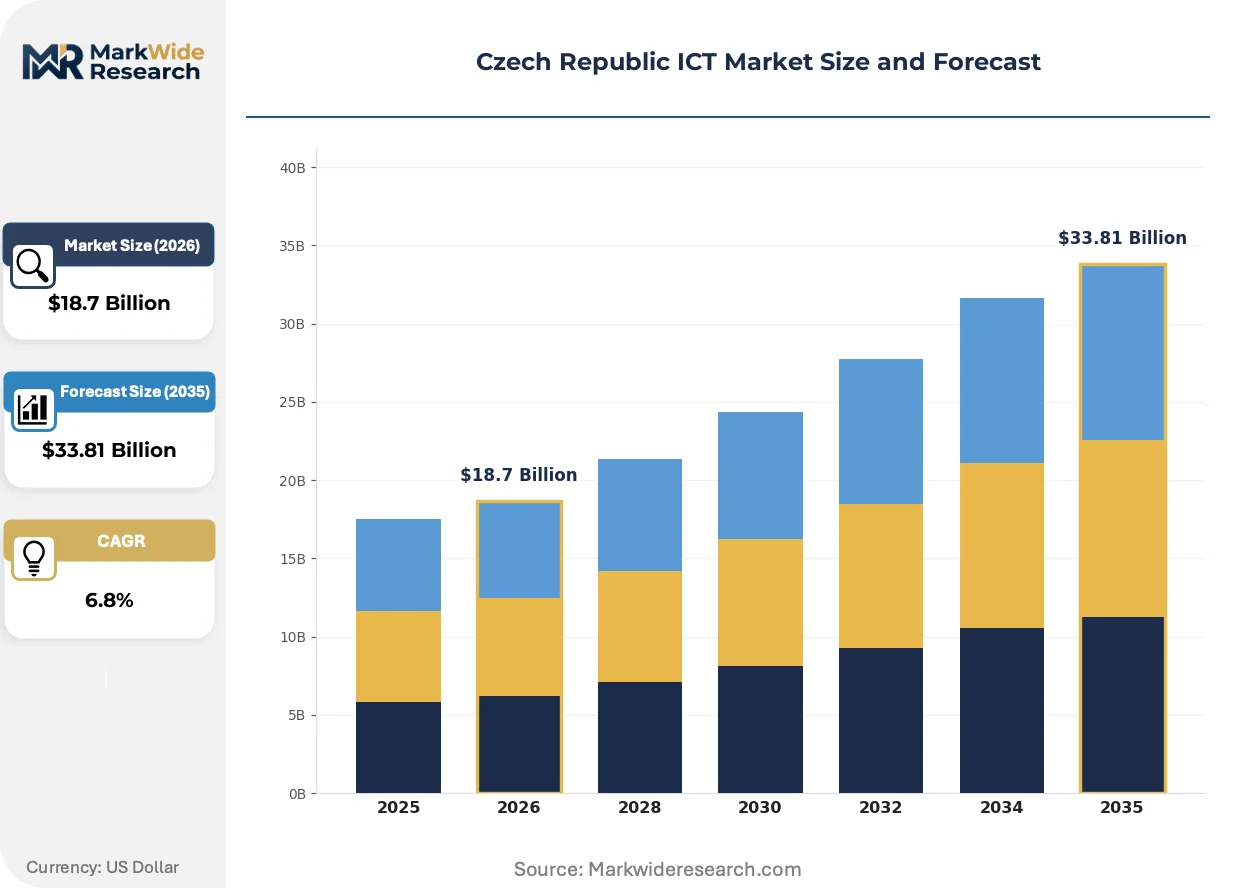
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking, Cloud Services End User: SMEs, Enterprises, Government, Education Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: AI, IoT, Blockchain, Cybersecurity |
| Companies Covered | T-Mobile Czech Republic a.s., Vodafone Czech Republic a.s., O2 Czech Republic a.s., Avast Software s.r.o., CETIN a.s., Seznam.cz, Unicorn, GoodData, Y Soft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic ICT Market Trends and Innovations
Hybrid cloud architectures are fragmenting traditional infrastructure procurement, while regulatory compliance automation and sovereign data requirements are reshaping vendor selection criteria across Czech enterprise and public sectors.
Microservices-based application delivery is decomposing monolithic enterprise software stacks into containerized components. Manufacturing and logistics firms in the Central Bohemia region are adopting Kubernetes-orchestrated workloads at accelerating pace. This architectural shift is decomposing legacy vendor lock-in and enabling multi-cloud portability that hyperscale providers must accommodate.
EU AI Act provisions are mandating risk classification and documentation requirements for automated decision systems. Czech market surveillance authorities will enforce conformity assessment procedures for banking credit scoring and diagnostic imaging algorithms. Healthcare IT departments are preemptively restructuring procurement specifications to incorporate algorithmic audit trails and human oversight mechanisms.
Subscription-based infrastructure consumption is displacing capital-intensive ownership models among mid-market enterprises. Systems integrators are replacing traditional hardware resale with managed service contracts bundling compute, storage, and compliance monitoring. This pattern is most pronounced in Brno's technology corridor, where software development firms prioritize operational expenditure predictability over asset control.
Czech Republic ICT Market Segmentation
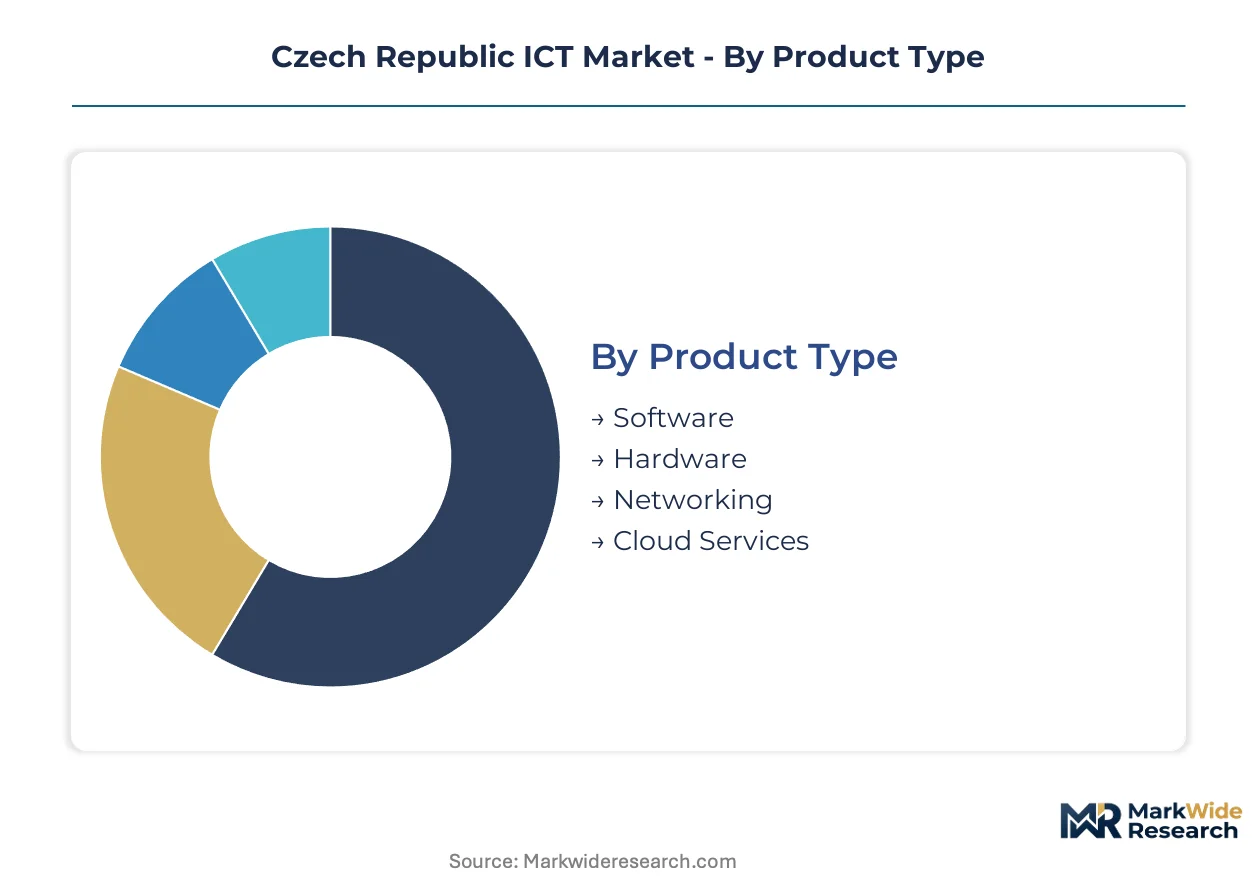
Segmentation patterns in the Czech Republic ICT market reveal distinct procurement rhythms across public and private sectors. Cloud migration timelines, regulatory compliance mandates, and geographic concentration of enterprise headquarters all reshape demand profiles within each category.
Product Type:
Software and hardware procurement concentrates heavily in Prague and Central Bohemia, while cloud services adoption spreads more evenly across regional enterprise clusters.
- Software:Enterprise resource planning and public administration systems dominate procurement volumes. Czech government agencies prioritize interoperability-certified solutions under EU framework compliance, compressing vendor qualification timelines for pre-approved suppliers.
- Hardware:Server infrastructure and endpoint computing equipment face sovereign cloud displacement pressures. Domestic demand centers on Prague's financial district and Brno's technology corridor, where data center expansion drives refresh cycles.
- Networking:5G radio access equipment and fiber termination hardware anchor carrier infrastructure investments.
- Cloud Services:Hybrid architectures combining EU-certified hyperscale capacity with domestic edge nodes attract public sector tenders.
Software commands the established base. The steepest expansion runs through Cloud Services.
End User:
Cost-tier stratification separates premium compliance-ready solutions for financial institutions from standardized offerings targeting mid-market manufacturing.
- SMEs:Managed service consumption displaces capital-intensive ownership across manufacturing and logistics sub-sectors. Regional providers outside Prague exploit structural underpenetration versus Western European benchmarks.
- Enterprises:Banking and automotive headquarters in Prague drive cybersecurity and AI procurement at scale. NIS2 implementation deadlines compress procurement cycles for pre-certified vendors.
- Government:Sovereign cloud mandates redirect legacy on-premises contracts toward EU-certified hyperscale providers.
- Education:University research clusters in Brno and Prague pilot edge computing deployments tied to innovation funding.
Enterprises anchor current revenue concentration. SMEs are climbing the fastest as subscription infrastructure models penetrate regional manufacturing hubs.
Deployment:
Application criticality determines architecture selection, with financial transaction systems favoring hybrid resilience and administrative workloads shifting cloud-native.
- On-Premises:Legacy core banking and manufacturing execution systems persist where data sovereignty requirements block full migration.
- Cloud-Based:Software development and collaboration platforms dominate this tier. Prague-based fintech startups prioritize operational expenditure predictability over asset control.
- Hybrid:Sensitive workloads split between domestic private infrastructure and EU-certified public capacity. Czech critical infrastructure operators favor this model under NUKIB audit requirements.
- Managed Services:Cybersecurity monitoring and compliance automation bundle hardware, software, and specialist labor into subscription contracts.
On-Premises retains the installed base. Managed Services posts the steepest trajectory as talent scarcity pushes mid-market buyers toward outsourced operations.
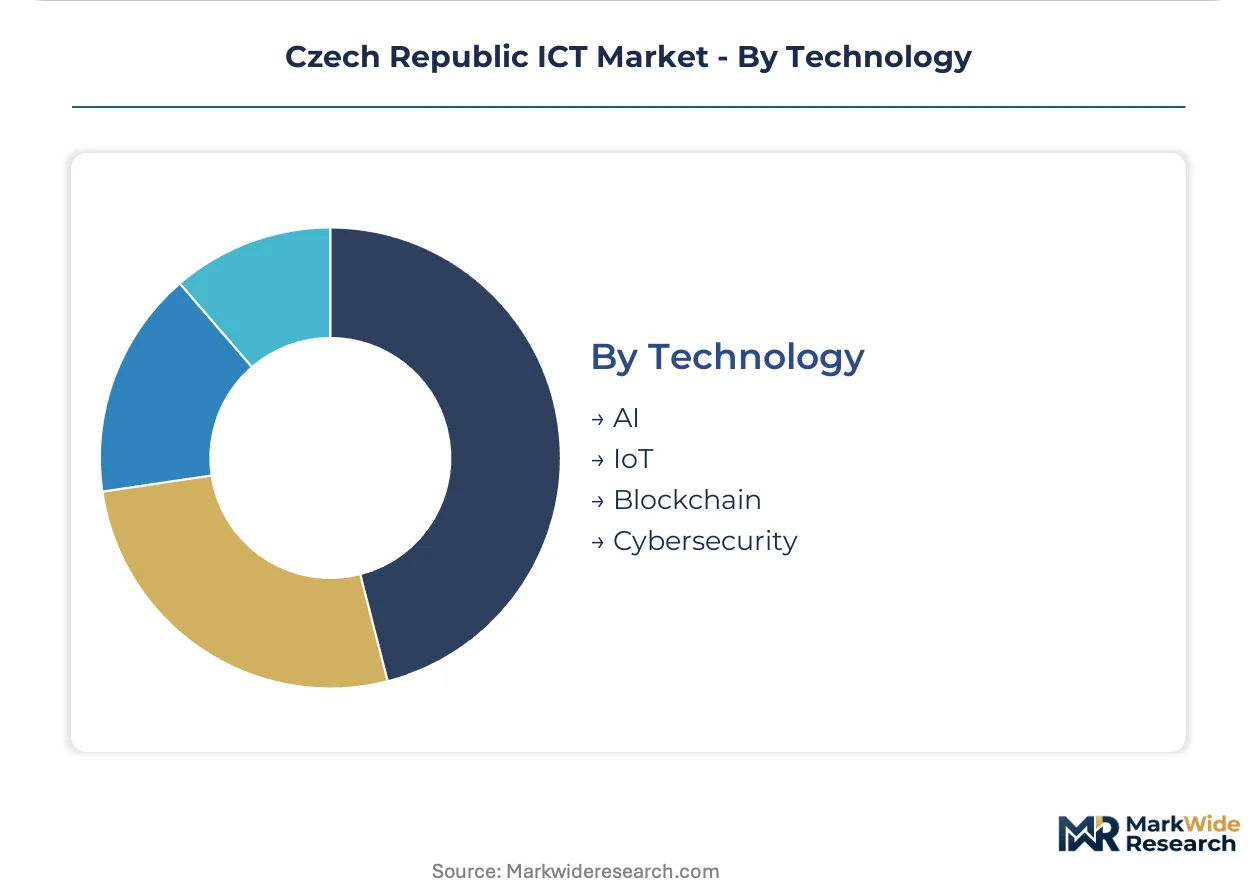
Technology:
Regulatory pressure intensity separates compliance-mandated cybersecurity investments from exploratory AI and blockchain pilots.
- AI:Automated credit scoring and diagnostic imaging algorithms face impending EU AI Act conformity assessments. Czech healthcare IT departments preemptively restructure procurement specifications to incorporate audit trails.
- IoT:Industrial sensor networks and predictive maintenance systems concentrate in Moravian manufacturing facilities. T-Mobile's 5G private network pilots enable campus-scale deployments.
- Blockchain:Supply chain traceability and digital identity proofs remain experimental across Czech enterprise pilots.
- Cybersecurity:Managed detection and response services attract accelerated procurement from Prague financial institutions facing DORA compliance deadlines.
Cybersecurity dominates current spending. AI is expanding most quickly as banking and healthcare automated systems require compliance architecture ahead of enforcement activation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The D8 motorway corridor linking Prague to Germany anchors Central Bohemia's dominance in Czech ICT infrastructure deployment. This transport backbone supports fiber backhaul density and data center clustering that concentrates enterprise demand in the capital region.
Prague
Financial institutions headquartered in Prague accelerate cybersecurity procurement ahead of EU DORA compliance deadlines. The Czech National Bank supervises operational resilience requirements for banking groups. Prague's fintech corridor along Vltava River banks drives hybrid cloud adoption among payment processors and digital lenders.
Central Bohemia
Manufacturing execution systems and industrial IoT networks concentrate in automotive supplier parks surrounding the capital. NUKIB mandates security audits for critical infrastructure operators headquartered in this region. Mladá Boleslav and Kladno industrial zones pilot private 5G campus networks combining T-Mobile infrastructure with edge compute nodes.
Brno
Software development firms and university research clusters generate subscription-based infrastructure demand across South Moravia. EU structural funds support innovation hubs at Brno University of Technology. The Technology Park Brno hosts Kubernetes-orchestrated workloads for mid-market enterprises prioritizing operational expenditure predictability.
Ostrava
Legacy industrial facilities in this Moravian-Silesian hub confront decades of siloed database integration challenges during modernization. Czech Ministry of Industry and Trade programs fund digital transformation of heavy manufacturing. The Lower Vítkovice area redevelops former steelworks into data center and cloud service facilities.
Plzeň
West Bohemian engineering SMEs exhibit structural underpenetration in managed services versus Western European benchmarks. Regional development agencies channel EU cohesion policy funds toward SME digitization. The Plzeň-Tachov industrial zone attracts automotive electronics suppliers requiring localized IT service delivery.
Czech Republic ICT Market Competitive Landscape
Listed leaders compete with private specialists across infrastructure ownership and service delivery dimensions. The Czech ICT market structures around carrier incumbents with nationwide 5G spectrum, wholesale fiber owners controlling backhaul access, and software vendors pivoting toward subscription revenue. Three archetypes dominate: infrastructure-heavy telecom operators, security-centric software houses, and cloud-native platform developers. Competitive moves concentrate on sovereign cloud certification procurement and NIS2-compliant service bundling.
Within the carrier-incumbent tier, T-Mobile Czech Republic a.s., O2 Czech Republic a.s., and CETIN a.s. occupy positions that exemplify divergent strategic orientations. T-Mobile leverages nationwide 5G infrastructure to anchor government connectivity tenders. O2 competes through specialized cybersecurity bundles targeting financial institutions. CETIN sustains critical wholesale fiber backhaul that underpins retail service differentiation across the broader market, representing the infrastructure-gatekeeper archetype that shapes margin distribution downstream.
| Leading Market Players |
|---|
| T-Mobile Czech Republic a.s. |
| Vodafone Czech Republic a.s. |
| O2 Czech Republic a.s. |
| Avast Software s.r.o. |
| CETIN a.s. |
| Seznam.cz |
| Unicorn |
| GoodData |
| Y Soft |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud capacity substitution for legacy on-premises infrastructure simultaneously concentrates procurement leverage among Prague-based financial institutions and compresses margin structures for hardware-centric system integrators. This displacement dynamic redirects value capture toward EU-certified hyperscalers while fragmenting downstream service provider economics.
Pricing Analysis
Volume-discount tiering structures separate enterprise-scale banking contracts from mid-market manufacturing subscriptions. Premium-mid-economy pricing differentiation hinges on NUKIB certification grade and bundled managed detection response service levels. Pricing pressure stems from CETIN's wholesale fiber concentration, which constrains retail ISP margin expansion. SME segments exhibit acute price sensitivity, while government agencies prioritize sovereign compliance over unit cost.
Supply Chain Analysis
CETIN's fiber backhaul chokepoint in Central Bohemia underwrites national connectivity economics and shapes competitive positioning across retail service tiers. Hardware sourcing draws from Germany, Taiwan, and China for server infrastructure and 5G radio equipment. Supply chain risk centers on single-source dependency for advanced semiconductor components amid EU export control expansion. Distribution runs through Prague-headquartered systems integrators with NIS2 pre-certification status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Prague financial institutions consolidating cybersecurity procurement ahead of DORA deadlines, compressing vendor qualification timelines and elevating pre-certified solution premiums.
For Market Incumbents: Fortify NUKIB certification portfolios to defend against emerging cloud-native security vendors. CETIN should deepen upstream control over fiber termination hardware to offset margin compression from retail service commoditization. T-Mobile must accelerate 5G private network deployment in Moravian manufacturing zones before O2 replicates its cybersecurity bundling model.
For New Entrants and Emerging Players: Anchor in Brno's SME technology corridor where managed service penetration lags Western European benchmarks by structural margin. Target subscription-based infrastructure consumption among software development firms prioritizing operational expenditure predictability. Pursue channel partnerships with regional development agencies distributing EU cohesion digitization funds.
For Investors and Strategic Acquirers: The market sits at a regulatory-compliance acceleration phase that favors pre-certified managed service specialists over hardware-resale incumbents. Five-to-ten-year viability favors NIS2-compliant security vendors with established NUKIB audit relationships. Monitor EU AI Act implementation timing through Czech market surveillance authority staffing levels as inflection signal for healthcare IT automation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | NUKIB pre-approval unlocks public sector procurement priority and shortens sales cycles. |
| 5G Private Network Deployment | T-Mobile infrastructure anchors industrial campus contracts in Moravian manufacturing zones. |
| Managed Detection Service Launch | DORA compliance deadlines compress procurement windows for Prague financial institutions. |
| Channel Partnership Expansion | Regional development agency relationships access EU-funded SME digitization programs. |
| AI Compliance Architecture Development | EU AI Act risk classification creates advisory revenue streams in banking and healthcare. |
Research Methodology
A spread of perspectives from CTOs at Prague financial institutions, NUKIB certification officers, CETIN network engineers, and Brno software firm procurement leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with hyperscaler account executives and channel partner principals. Secondary validation drew from CTU spectrum allocation records, NUKIB security audit disclosures, EU DORA implementation guidance, and hyperscaler regional capex filings. Bottom-up service provider revenue estimates triangulated against top-down ICT expenditure benchmarks from national statistical authorities.
Segmentation dimensions modeled span deployment architecture, end-user organization scale, technology category, and geographic adoption cluster across the projection horizon. CAGRs were derived from regression analysis against public sector digitalization budget trajectories and enterprise cloud migration velocity indicators. Forecast inputs incorporated NIS2 transposition timeline assumptions and EU AI Act enforcement activation patterns.
Material uncertainties — NIS2 liability allocation rulings, EU AI Act conformity assessment processing delays, and hyperscaler sovereign cloud certification timelines — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as Czech market surveillance authority staffing and NUKIB audit queue depth evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Anticipatory Commerce Infrastructure Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Big Data Technology Market
Digital Solutions
US Customer Communication Management (CCM) Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
Global Tag Management System Market
Digital Solutions
Global Referral Management Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Data Analytics in the Smart Home Market