
 LNG Metering Skids Market | 2026-2036
LNG Metering Skids Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Metering Skids Market Insights
Multi-source procurement of cryogenic flow-measurement packages is expanding as terminal operators diversify supplier risk across metering technologies. Emerson Electric leverages its ultrasonic and Coriolis portfolio to anchor long-term service contracts with major LNG offloading facilities. Baker Hughes competes through integrated subsea-to-shore measurement chains that extend its reach into floating installations. Siemens specializes in SIL-certified automation architectures that dominate European utility specifications.
LNG metering skids are engineered flow-measurement stations comprising cryogenic-rated instruments, piping manifolds, and control enclosures designed to quantify natural gas in liquid phase at temperatures below minus 160 degrees Celsius for custody transfer and process monitoring. Coriolis mass-flow technology leads in high-accuracy trade settlement while ultrasonic systems capture share in large-bore pipeline applications where pressure drop minimization matters. Modular skid configurations attract investment from operators seeking phased terminal expansion, whereas fixed installations retain dominance in baseload regasification plants where permanent infrastructure amortizes over decades.
FERC pipeline-safety standards and the EPA greenhouse-gas reporting mandates in the United States shape equipment specification and leak-detection integration, while IEC 61508 and OIML R117 international metrology frameworks define accuracy classes that determine market-access eligibility across jurisdictions. Stakeholders must monitor evolving carbon-border-adjustment mechanisms and hydrogen-readiness requirements that will redefine flow-meter calibration protocols and skid material specifications in coming investment cycles.
Market Dynamics
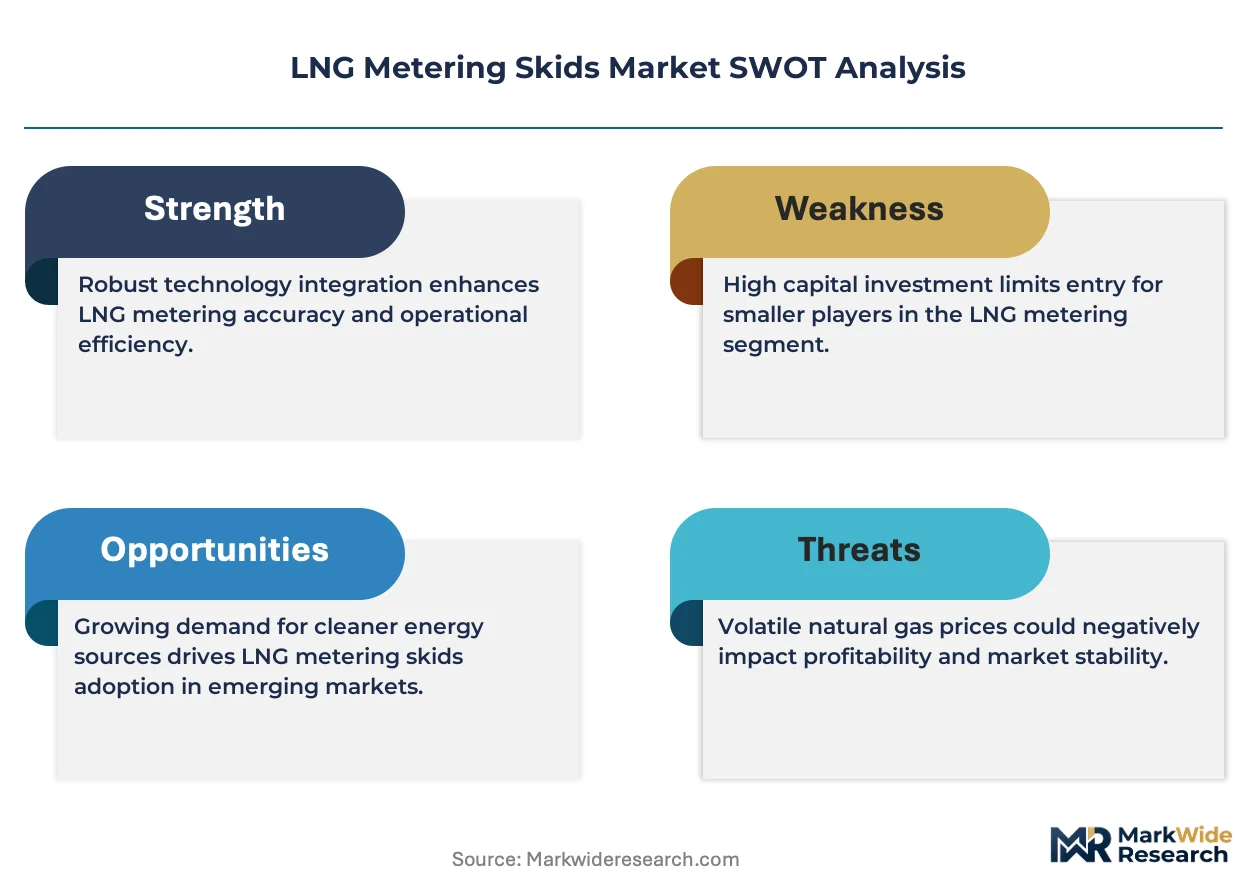
The LNG metering skids sector faces intensifying pressure from functional-safety certification mandates that are compressing vendor qualification timelines and elevating engineering costs for market entry.
Growth Catalysts
- EU F-Gas Regulation:Tightened metrology requirements for custody-transfer systems are forcing terminal upgrades across Germany, France, and the Netherlands, creating replacement demand for SIL-certified skids.
- Floating LNG infrastructure:Japan and Qatar are expanding FSRU deployments that require compact, modular metering packages suited to marine loading conditions.
- Coriolis technology maturation:Improved cryogenic-rated sensors are extending operational envelopes below minus 160 degrees Celsius, enabling trade-settlement applications previously reserved for ultrasonic systems.
Market Restraints
- Specialized alloy costs:Inconel and 316L stainless steel price volatility directly impacts skid fabrication economics, with cryogenic-rated piping consuming 35-45% of bill-of-materials value.
- Supplier concentration:Ultrasonic transducer manufacturing concentrates among German and Japanese component houses, exposing procurement to single-source risk.
- Calibration infrastructure gaps:Few facilities worldwide can perform traceable cryogenic flow calibration, extending lead times for custody-transfer-grade systems.
Strategic Opportunities
- India LNG terminal buildout:Dahej and Kochi expansion projects present greenfield demand for integrated metering skids with local assembly requirements.
- Hydrogen-readiness retrofit:Germany's hydrogen pipeline conversion timeline creates demand for skids with dual-calibration capability for methane-hydrogen blends.
- Digital twin integration:Real-time virtual commissioning is converging with physical skid delivery, enabling remote acceptance testing and reducing site installation duration.
Industry Challenges
- Cryogenic instrumentation expertise:Shortage of engineers qualified in sub-minus 150 degrees Celsius sensor integration is extending project staffing timelines.
- IEC 61508 SIL certification:Third-party functional-safety assessments require 12-18 month validation cycles that delay revenue recognition for new product variants.
- Legacy DCS integration:Brownfield terminal automation retrofits demand custom protocol gateways to marry modern skid controllers with 1990s-era distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Metering Skids Market |
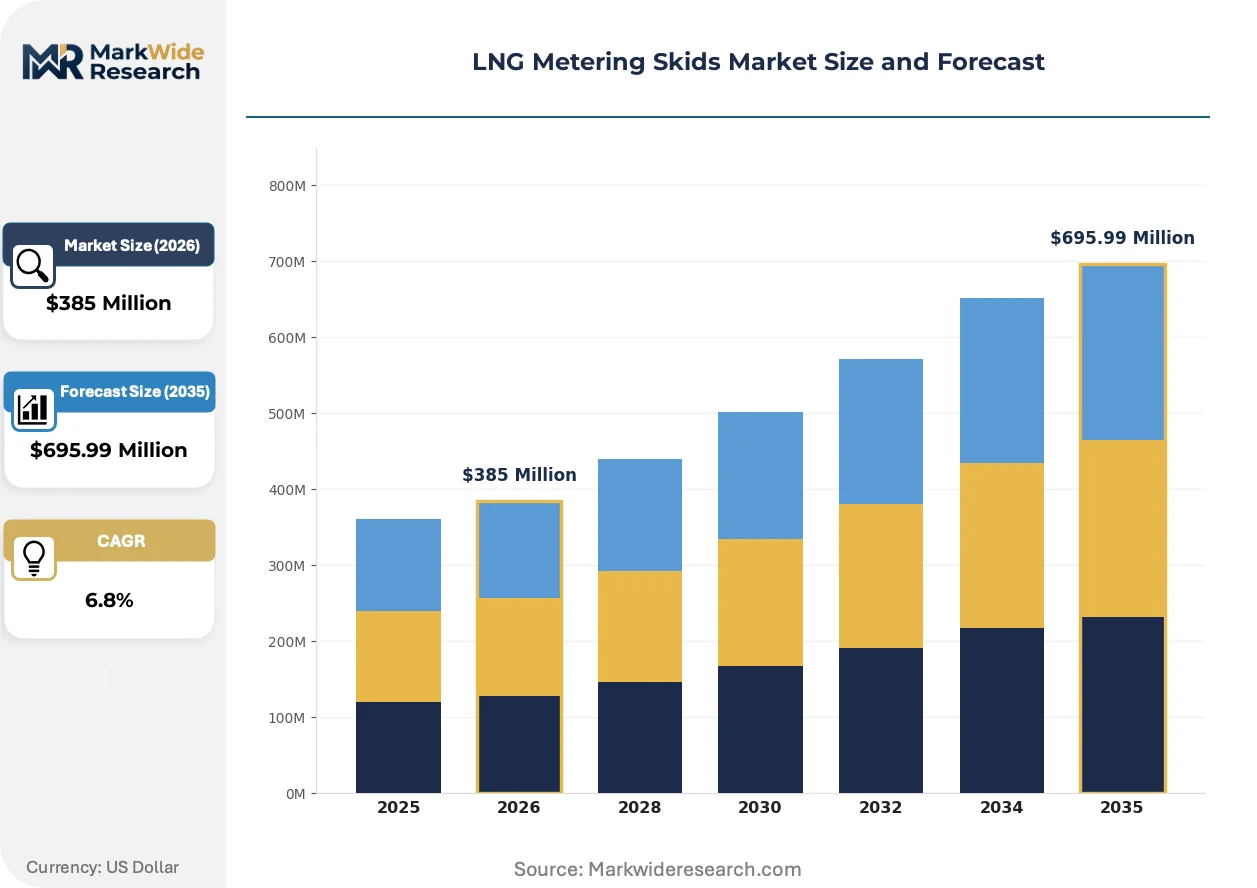
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $695.99 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Modular, Mobile, Fixed Technology: Coriolis, Ultrasonic, Differential Pressure, Turbine End User: Utilities, Industrial Plants, LNG Terminals, Shipping Companies Installation: Onshore, Offshore, Floating, Permanent |
| Companies Covered | Yokogawa Electric, Denso, Emerson Electric, Cummins, Continental, Honeywell International, Bosch, Baker Hughes, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Metering Skids Market Trends and Innovations
Ultrasonic and Coriolis measurement technologies are advancing in parallel while digitalization protocols rewrite how custody data is transmitted and verified across terminal boundaries.
Multi-path ultrasonic flowmeters with chordal measurement geometries are converging with edge-computing architectures to enable real-time diagnostic analytics at the skid level. Japanese FSRU operators are piloting these systems for LNG bunkering applications where space constraints favor compact instrumentation. The convergence is compressing the traditional separation between flow measurement and process control, allowing skid builders to displace separate PLC installations.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is reshaping insulation specifications for cryogenic piping enclosures. Terminal operators in Rotterdam and Hamburg must now specify vacuum-insulated or aerogel-based alternatives to conventional foam systems. German engineering contractors are responding with modular enclosure designs that accommodate material substitution without structural redesign.
Long-term service contracting is displacing transactional equipment procurement among major LNG terminal operators. Qatari and Japanese buyers now bundle 15-year calibration and spare-part agreements with initial skid purchases, compressing vendor margins upfront while locking in recurring revenue streams. This behavioral shift is most pronounced in baseload regasification facilities where operational continuity outweighs capital cost minimization.
LNG Metering Skids Market Segmentation
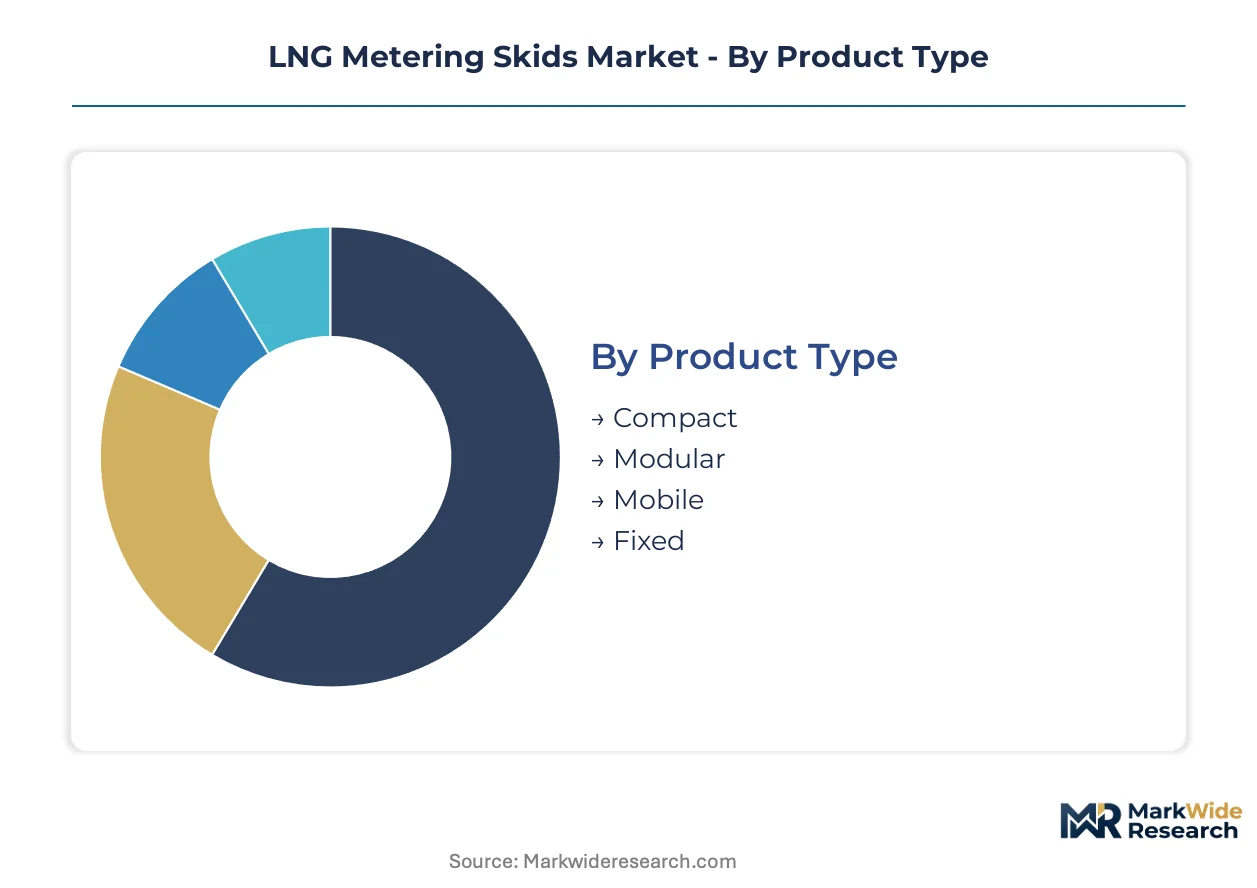
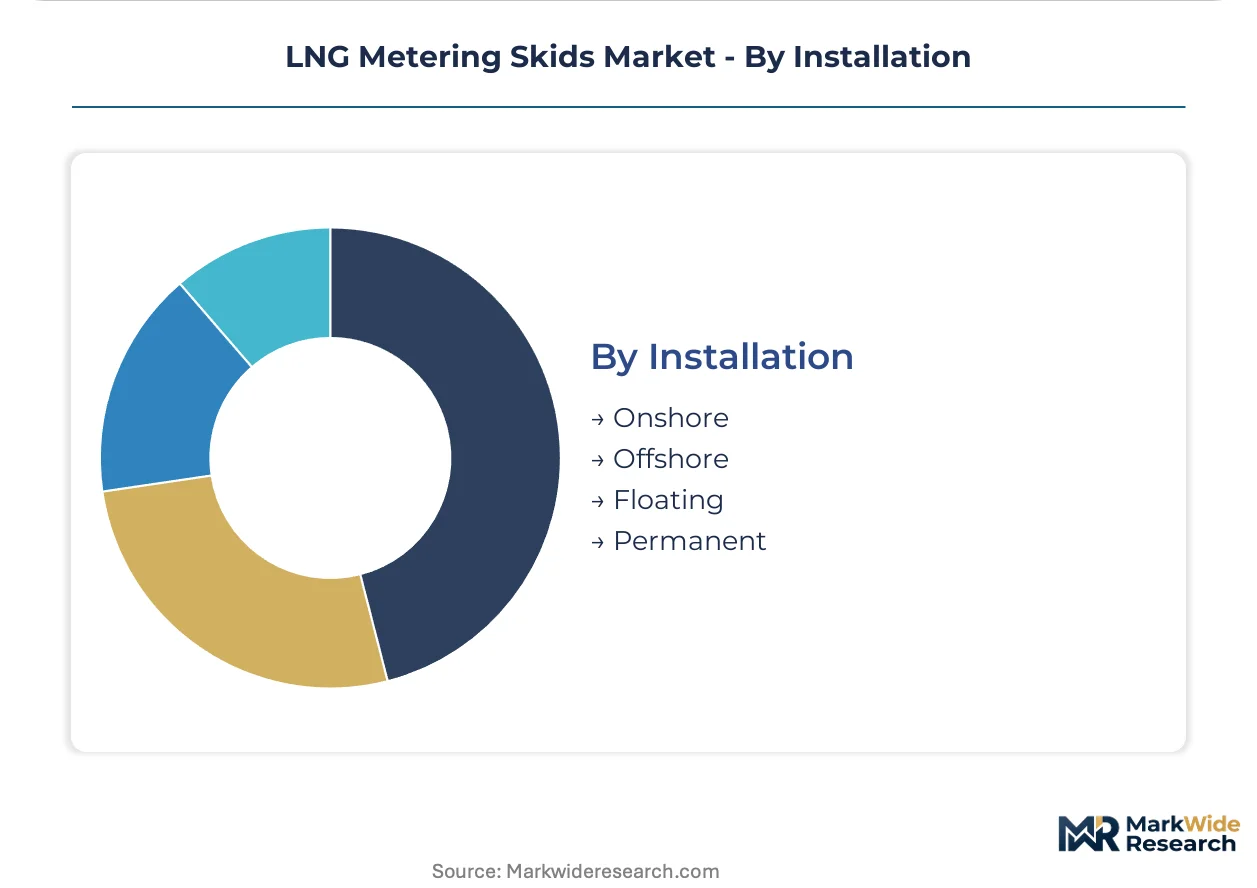
LNG metering skid configurations diverge sharply across deployment scenarios, from permanent baseload terminals requiring decades-long amortization to floating installations demanding rapid commissioning cycles. Technology selection and installation modality jointly determine capital intensity, calibration protocols, and service contracting structures for operators.
Product Type:
Cryogenic flow-measurement packages scale across four physical configurations that trade modularity against integration depth.
- Fixed:Permanent skid installations anchor baseload regasification plants in Qatar and Germany where infrastructure amortizes over multi-decade operational horizons. These systems command premium engineering for SIL-certified custody transfer but lock capital into immovable assets.
- Modular:Phased terminal expansion drives procurement of reconfigurable skid packages that permit capacity additions without process shutdown. Japanese FSRU operators favor these configurations for their adaptation to evolving marine loading schedules.
- Compact:Space-constrained bunkering stations and small-scale distribution hubs deploy reduced-footprint skids with integrated valve manifolds. These units sacrifice some maintenance accessibility for footprint minimization.
- Mobile:Trailer-mounted metering systems serve temporary pipeline tie-ins and emergency supply scenarios where permanent installation is uneconomical. Calibration traceability challenges limit their use in trade settlement applications.
Fixed installations dominate revenue scale; modular configurations gain share fastest as terminal operators prioritize capital flexibility.
Technology:
Flow-measurement principles differentiate on accuracy, pressure-drop characteristics, and cryogenic material compatibility.
- Coriolis:Mass-flow direct measurement achieves custody-transfer accuracy for LNG trade settlement at temperatures below minus 160 degrees Celsius. Improved cryogenic sensor designs are extending operational envelopes previously reserved for ultrasonic alternatives.
- Ultrasonic:Multi-path chordal geometries minimize pressure drop across large-bore pipelines, favoring applications where energy efficiency outweighs absolute mass-flow precision. Edge-computing integration now enables real-time diagnostic analytics at the skid level.
- Differential Pressure:Orifice-plate and venturi configurations persist in legacy terminal retrofits where existing piping infrastructure constrains technology substitution. These systems require more frequent calibration cycles than Coriolis or ultrasonic alternatives.
- Turbine:Mechanical flow measurement retains niche application in process monitoring and non-custody transfer duties where lower capital cost offsets reduced accuracy specifications.
Coriolis systems anchor high-value trade settlement; ultrasonic platforms are expanding most quickly through large-bore pipeline deployments.
End User:
Demand concentrates across four operator categories with divergent procurement behaviors and technical specifications.
- LNG Terminals:Import and export facilities in Germany, Japan, and Qatar drive the bulk of custody-transfer-grade skid demand. These operators now bundle 15-year calibration and spare-part agreements with initial purchases, compressing vendor margins upfront.
- Utilities:Gas distribution networks require metering skids for regasified LNG injection into national pipeline systems. European utilities specify SIL-certified automation architectures that dominate regional procurement standards.
- Industrial Plants:Petrochemical and power generation facilities deploy process-monitoring skids for feedstock measurement and emissions reporting. EPA greenhouse-gas mandates shape equipment specifications for US-based installations.
- Shipping Companies:LNG bunkering vessels and FSRU operators demand compact, marine-rated packages suited to loading-condition variability. Space constraints favor integrated instrumentation over distributed control architectures.
LNG terminals concentrate the highest-value procurement; shipping applications are climbing the fastest as marine fuel transition accelerates.
Installation:
Physical deployment environment dictates structural engineering, insulation specifications, and maintenance accessibility.
- Onshore:Ground-based installations at permanent import terminals permit conventional foundation designs and straightforward calibration access. FERC pipeline-safety standards govern equipment specification and leak-detection integration in US deployments.
- Floating:FSRU and LNG carrier applications require skid packages engineered for marine motion, vibration, and space constraints. Japanese operators are piloting integrated ultrasonic systems for bunkering duties.
- Offshore:Platform-based regasification demands corrosion-resistant enclosures and subsea-to-shore measurement chains. Baker Hughes competes through integrated offerings that extend into these floating installations.
- Permanent:Immovable infrastructure commitments at baseload plants favor fixed skid configurations with decades-long service contracting. Operational continuity priorities outweigh capital cost minimization in these procurement decisions.
Onshore installations retain volume leadership; floating deployments show steepest expansion trajectory as FSRU infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's Ras Laffan Industrial City anchors the global LNG metering skid procurement landscape, with terminal operators there bundling long-term service contracts with custody-transfer-grade installations. Demand concentrates across four additional national markets where import infrastructure expansion and regulatory tightening intersect.
Germany
Wilhelmshaven and Brunsbüttel terminal projects are driving procurement of SIL-certified skids as operators replace aging measurement infrastructure. The EU F-Gas Regulation mandates phasedown of fluorinated greenhouse gases in cryogenic insulation systems, forcing specification changes at Hamburg and Rotterdam-adjacent facilities. Engineering contractors in Lower Saxony are developing modular enclosure designs that accommodate vacuum-insulated alternatives without structural redesign.
Japan
FSRU deployments at Chita and Futtsu terminals require compact, marine-rated metering packages suited to loading-condition variability. METI's hydrogen pipeline conversion timeline creates demand for skids with dual-calibration capability for methane-hydrogen blends. Osaka-based shipping operators are piloting integrated ultrasonic systems for LNG bunkering applications where space constraints favor distributed instrumentation.
United States
Gulf Coast export terminals at Sabine Pass and Corpus Christi are expanding cryogenic flow-measurement capacity for custody transfer to Asian buyers. FERC pipeline-safety standards and EPA greenhouse-gas reporting mandates shape equipment specification and leak-detection integration requirements. Houston engineering clusters are developing digital twin integration protocols that enable remote acceptance testing and reduce site installation duration.
India
Dahej and Kochi LNG terminal expansion projects present greenfield demand for integrated metering skids with local assembly requirements. The Petroleum and Natural Gas Regulatory Board is tightening metrology standards for import facility commissioning. Gujarat-based engineering contractors are bidding for skid fabrication contracts that specify indigenous content thresholds and traceable cryogenic calibration protocols.
Netherlands
Rotterdam's Gate terminal is upgrading measurement infrastructure to accommodate larger LNG carrier vessels and expanded bunkering operations. The EU F-Gas Regulation's insulation specifications are forcing material substitution in cryogenic piping enclosures at Dutch import facilities. Engineering specialists in the Randstad region are supplying modular skid configurations to German and Belgian terminal operators seeking phased capacity expansion.
LNG Metering Skids Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital twin integration and hydrogen-readiness retrofit segments. The vendor base clusters around three archetypes: diversified industrial conglomerates with cryogenic instrumentation portfolios, specialized flow-measurement technology houses, and marine engineering contractors with offshore packaging expertise. Competitive dynamics center on long-term service contracting structures that displace transactional equipment procurement, alongside strategic partnerships that bundle calibration infrastructure with initial skid delivery.
Among diversified industrial conglomerates, Emerson Electric, Baker Hughes, and Siemens exemplify distinct competitive positioning within the custody-transfer ecosystem. Emerson leverages its ultrasonic and Coriolis portfolio to anchor extended service agreements with major LNG offloading facilities. Baker Hughes occupies a position in integrated subsea-to-shore measurement chains that extend into floating installations. Siemens sits within the SIL-certified automation architecture segment that dominates European utility procurement specifications. Each represents a different pathway to capturing recurring revenue streams as terminal operators prioritize operational continuity over upfront capital cost minimization.
| Leading Market Players |
|---|
| Yokogawa Electric |
| Denso |
| Emerson Electric |
| Cummins |
| Continental |
| Honeywell International |
| Bosch |
| Baker Hughes |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Inconel and 316L stainless steel price volatility feeds directly into skid fabrication economics, with cryogenic-rated piping consuming 35-45% of bill-of-materials value and forcing tiered pricing stratification across SIL-certified premium systems, standard custody-transfer configurations, and economy-grade process monitoring units.
Pricing Analysis
Input-cost pass-through from specialized alloys dominates pricing dynamics, with Inconel price swings compressing margins on fixed-installation skids destined for German and Qatari baseload terminals. Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified custody-transfer systems from process-monitoring alternatives, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier is intensifying because Indian and Southeast Asian terminal operators prioritize capital flexibility over long-term service contracts. Shipping companies and FSRU operators exhibit highest price sensitivity due to space-constrained procurement volumes, while German utilities show lowest sensitivity given operational continuity mandates under EU F-Gas Regulation compliance deadlines.
Supply Chain Analysis
IEC 61508 SIL certification and OIML R117 metrology qualification function as gating mechanisms that filter component suppliers, with ultrasonic transducer manufacturing concentrating among German and Japanese component houses. Cryogenic flowmeter assembly draws from stainless steel forging capacity in Germany, Japan, and the United States, while sensor electronics and edge-computing modules rest on semiconductor supply from Taiwan and South Korea. Single-source vulnerability concentrates in cryogenic-rated pressure transmitters and vacuum-insulated piping enclosures, with tariff exposure on Chinese-origin instrumentation amplifying procurement risk. Distribution runs through engineering-procurement-construction contractors at major LNG terminals, with direct OEM relationships reserved for aftermarket calibration and spare-part agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LNG metering skids market compounds steadily as LNG import infrastructure expansion across Germany, Japan, and Qatar generates replacement and greenfield demand cycles with limited demand destruction risk.
For Market Incumbents: Deploy long-term service contracting as the primary margin defense, bundling 15-year calibration agreements with initial skid sales to lock out emerging competitors and offset upfront price compression from Indian procurement tenders. Incumbents should deepen backward integration into cryogenic sensor manufacturing to reduce exposure to German and Japanese transducer supply concentration, while accelerating IEC 61508 SIL certification for Coriolis variants to preempt ultrasonic technology substitution in large-bore applications. For New Entrants and Emerging Players: Launch via digital twin integration partnerships with Houston and Rotterdam engineering clusters, targeting remote acceptance testing protocols that reduce site installation duration for floating LNG infrastructure. The most penetrable white space sits in hydrogen-readiness retrofit skids for German hydrogen pipeline conversion timelines, where dual-calibration capability for methane-hydrogen blends commands premium positioning without incumbent service contract lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration infrastructure scarcity intersects with terminal operator bundling behavior, favoring acquisition of specialized cryogenic flow calibration facilities over equipment manufacturers. The market reads as a 5-10 year compounder anchored by infrastructure replacement cycles and regulatory tightening, with acquisition target archetypes being mid-cap engineering houses possessing IEC 61508 certification capabilities and established relationships with Qatari or Japanese terminal operators. The signal to watch is FSRU deployment announcements in Southeast Asia and India, which would accelerate modular skid demand and strain existing calibration capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Contracting | 15-year calibration bundling locks recurring revenue with Qatari and Japanese terminal operators. |
| Backward Integration into Sensors | In-house cryogenic transducer production reduces single-source exposure to German component houses. |
| Hydrogen-readiness Certification | Dual-calibration skids capture German hydrogen pipeline conversion demand ahead of incumbents. |
| Digital Twin Integration | Remote acceptance testing protocols compress commissioning timelines for Japanese FSRU deployments. |
| Calibration Infrastructure Acquisition | Cryogenic flow calibration facilities become scarce assets as traceable capacity fails to match demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with LNG terminal procurement managers, EPC contractor project directors, cryogenic instrumentation engineers, and aftermarket service heads with secondary validation against FERC filings, IEC standards documentation, EU F-Gas Regulation implementation reports, and customs data on cryogenic flowmeter trade flows. Bottom-up project pipeline assessment across German, Japanese, Qatari, Indian, and US terminal developments triangulated against top-down market sizing from disclosed supplier contract values.
Comparable-period anchoring aligned the projection horizon against historical investment cycles in LNG import infrastructure, modeling volume and value trajectories across product type, technology principle, end-user category, and installation environment dimensions. CAGRs derived from segment-level growth rate convergence analysis, with industry-specific inputs including FSRU deployment schedules, EU F-Gas Regulation compliance timelines, and hydrogen pipeline conversion announcements feeding scenario weights.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged IEC 61508 certification delays or Inconel supply disruptions. Deviation in German terminal commissioning schedules or Japanese FSRU deployment acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
Power Metering Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
North America Gas Meter Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Europe Water Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
North America Smart Meters Market
Smart Meters
Power Monitoring System Market
Smart Meters
Smart Water Metering Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Smart Meter Battery Market
Smart Meters
United States Smart Meter Market