
 Smart Water Metering Market | 2026-2036
Smart Water Metering Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Metering Market Analysis
AMI-to-cloud integration is reconfiguring how utilities deploy meter networks, shifting from walk-by reads to always-on data pipelines. Xylem (Sensus) leverages its vertically integrated sensor-to-software stack to anchor large municipal contracts in North America. Kamstrup A/S competes through ultrasonic R&D intensity and Danish manufacturing scale. Badger Meter Inc. specializes in cellular endpoints for mid-size utilities seeking rapid deployment without gateway infrastructure.
Smart water metering encompasses automated measurement devices equipped with flow sensors, communication modules, and data analytics software that transmit consumption data in intervals as short as fifteen minutes to centralized utility platforms. These systems enable leak detection, demand response, and accurate billing across residential, commercial, and industrial water networks. Ultrasonic meters lead product type demand where precision and low maintenance outweigh higher unit costs, while NB-IoT technology segments gain fastest as telecom carriers expand dedicated IoT spectrum and utilities prioritize wide-area coverage without proprietary mesh investments. Municipal end users dominate deployment volumes, though commercial segments concentrate margin pools through sub-metering and cooling tower monitoring applications.
EPA lead and copper rules alongside state-level water loss mandates in California and Texas shape North American procurement standards, while EU Water Framework Directive and F-Gas Regulation indirectly accelerate utility digitalization budgets across Europe. France's national smart meter program and South Korea's K-water digital transformation initiative exemplify how regulatory targets convert into binding infrastructure procurement. Stakeholders must monitor spectrum allocation decisions by national telecom regulators and evolving cybersecurity certification requirements for critical infrastructure IoT devices.
Market Dynamics
AMI-to-cloud integration is compressing deployment timelines as utilities abandon walk-by reads for always-on data pipelines, forcing infrastructure vendors to bundle software subscriptions with hardware procurement.
Growth Catalysts
- NB-IoT protocol standardization:3GPP Release 13 specifications enable wide-area coverage without proprietary mesh gateway investments, accelerating utility adoption in Germany and South Korea.
- France's national smart meter program:Binding procurement mandates convert regulatory targets into infrastructure contracts, creating predictable demand visibility for equipment suppliers.
- Ultrasonic meter precision:Residential and commercial end users prioritize flow accuracy and maintenance-free operation over mechanical alternatives, driving product mix shifts.
Market Restraints
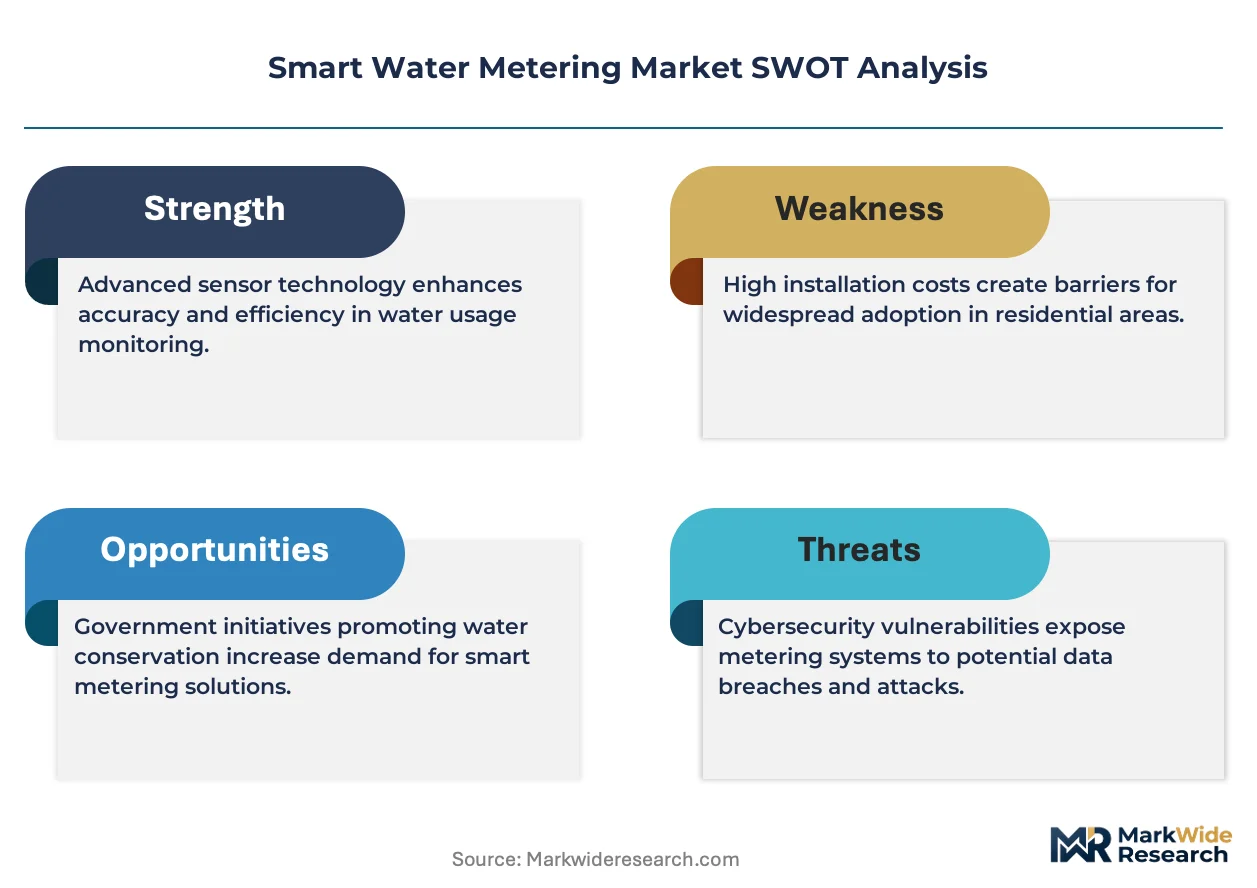
- Semiconductor supply concentration:Communication module production clusters in East Asian foundries expose AMI vendors to input volatility and extended lead times.
- Cellular spectrum licensing costs:National telecom regulators in multiple jurisdictions impose recurring connectivity fees that inflate total cost of ownership for municipal utilities.
- Mechanical meter residual stock:Existing installed base of magnetic and positive displacement units creates substitution friction and extends replacement cycles.
Strategic Opportunities
- Commercial sub-metering applications:Cooling tower monitoring and tenant billing systems represent underpenetrated margin pools beyond residential deployment volumes.
- EU Water Framework Directive alignment:Leakage reduction targets and digitalization budgets create procurement tailwinds for AMI vendors serving municipal utilities across member states.
- Edge analytics convergence:On-device processing of flow anomalies combined with cloud-based pattern recognition enables predictive maintenance service models.
Industry Challenges
- Cybersecurity certification complexity:Critical infrastructure IoT device standards vary by national regulator, fragmenting compliance engineering resources.
- Legacy billing system integration:Proprietary CIS platforms at incumbent utilities require custom API development, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Metering Market |
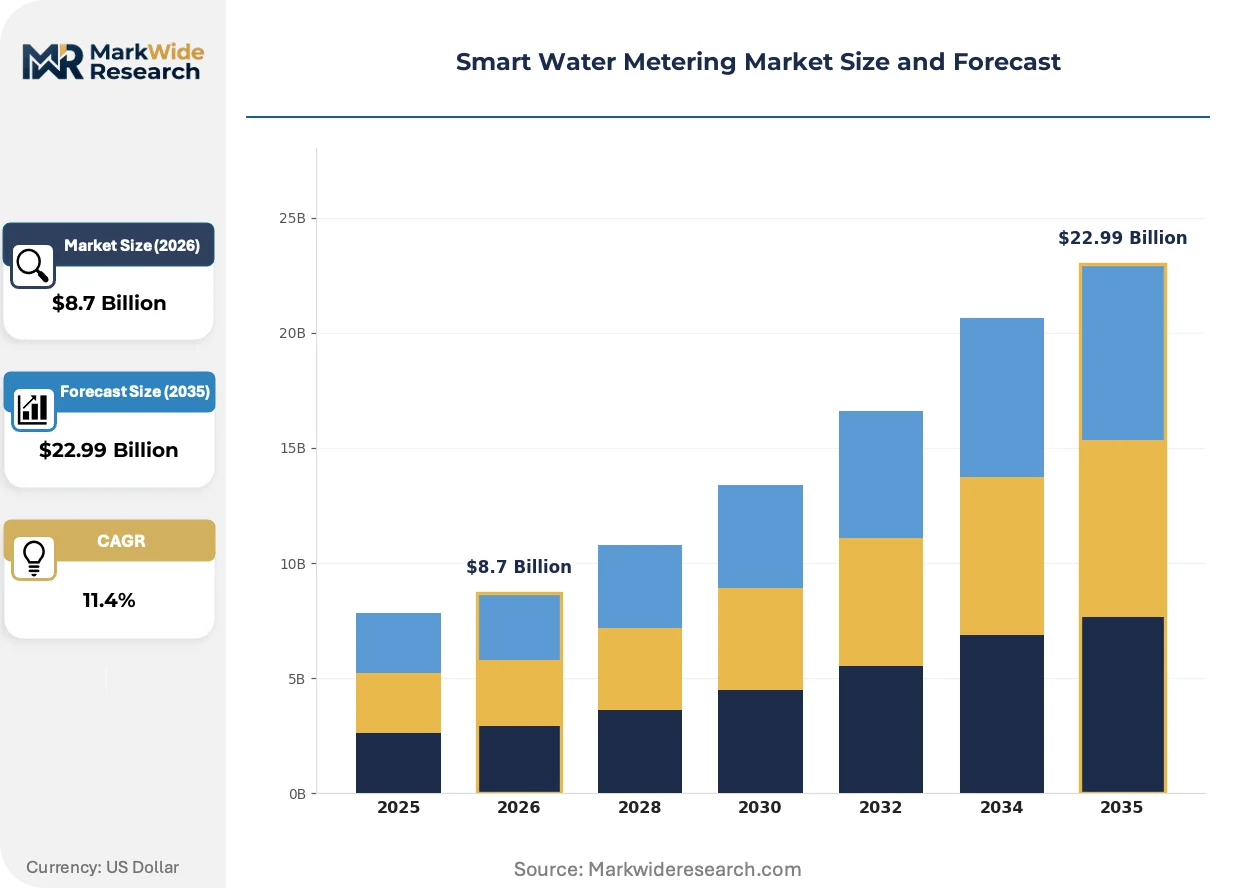
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Meters, Electromagnetic Meters, Mechanical Meters, Smart Meters Technology: LoRaWAN, NB-IoT, Zigbee, Cellular End User: Residential, Commercial, Industrial, Municipal Deployment: Cloud-Based, On-Premises, Hybrid, Remote |
| Companies Covered | Itron Inc., Xylem (Sensus), Badger Meter Inc., Kamstrup A/S, Diehl Stiftung & Co. KG, Neptune Technology Group Inc., Honeywell International Inc., Landis+Gyr, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Metering Market Emerging Trajectories
Data pipeline architectures are reconfiguring competitive advantage around software capabilities rather than meter hardware alone, compressing margins for pure equipment vendors while expanding recurring revenue pools.
Ultrasonic sensing technology measures flow through time-of-flight calculation without moving parts, eliminating wear and drift. Municipal utilities in California and Texas are specifying solid-state meters for new installations and accelerated replacement programs. This shift is rendering obsolete the fifteen-year replacement cycles and manual calibration requirements that sustained mechanical meter service revenues.
The EU F-Gas Regulation restricts fluorinated greenhouse gases in industrial cooling systems, indirectly accelerating utility digitalization budgets as commercial water users face intensified monitoring obligations. AMI data granularity enables compliance documentation for cooling tower operators. European commercial segments are responding by specifying meters with fifteen-minute interval logging and automated anomaly flagging.
Utility procurement committees now require outcome-based service level agreements rather than equipment-only contracts, unbundling hardware from data analytics and maintenance obligations. Mid-size municipal utilities in Germany and South Korea are adopting subscription models that shift capex to opex. This pattern is most visible in procurement tenders that specify guaranteed uptime percentages and predictive leak detection accuracy rather than meter specifications alone.
Smart Water Metering Market Segmentation
Smart water metering procurement splits across four distinct category hierarchies that govern vendor positioning and margin capture. Product type determines hardware replacement cadence, while technology selection locks in connectivity economics for fifteen-year operational lifecycles.
Product Type:
Replacement cycles vary dramatically—mechanical meters turn over every decade while solid-state alternatives extend service intervals past twenty years, compressing recurring revenue windows for service providers.
- Ultrasonic Meters:Time-of-flight sensors measure flow velocity through acoustic pulse transmission without mechanical wear. California and Texas utilities specify these for new installations where EPA lead rule compliance and water loss mandates demand precision measurement.
- Electromagnetic Meters:Faraday's law induction coils generate voltage proportional to flow velocity, excelling in high-conductivity industrial applications. Chemical processing plants and wastewater treatment facilities in Germany prioritize these for corrosive fluid handling where sensor durability outweighs unit cost premiums.
- Mechanical Meters:Positive displacement and turbine mechanisms dominate legacy installed bases across North American municipal networks. Extended replacement timelines and manual calibration requirements sustain incumbent vendor service revenues despite accuracy drift over operational life.
- Smart Meters:Integrated communication modules enable automated data transmission at fifteen-minute intervals to utility platforms. South Korea's K-water digital transformation initiative and France's national smart meter program anchor deployment volumes through binding procurement mandates.
Mechanical meters anchor the volume base while ultrasonic meters gain share at the steepest rate.
Technology:
Connectivity economics stratify sharply—licensed spectrum protocols carry recurring carrier fees while unlicensed alternatives demand proprietary gateway infrastructure investments.
- LoRaWAN:Unlicensed sub-gigahertz spectrum enables long-range transmission at minimal power draw, suiting rural distribution networks. German municipal utilities deploy these for village-scale systems where cellular density proves economically prohibitive.
- NB-IoT:3GPP-standardized narrowband protocol operates in licensed LTE spectrum with deep indoor penetration. Telecom carriers in South Korea and Germany have expanded dedicated IoT spectrum, accelerating utility adoption without mesh gateway capital expenditure.
- Zigbee:Mesh networking protocol clusters residential endpoints through repeater-hopping architectures. Sub-metering applications in multi-tenant commercial buildings leverage these for localized zone control without wide-area carrier dependencies.
- Cellular:Standard LTE and emerging 5G modules provide ubiquitous coverage for mobile workforce integration. Mid-size utilities in California specify cellular endpoints for rapid deployment without fixed infrastructure construction timelines.
Cellular technology commands the widest addressable market while NB-IoT demonstrates the most rapid adoption acceleration among newly specified systems.
End User:
Customer scale determines data granularity requirements and procurement authority concentration.
- Residential:Single-family and multi-family dwellings generate high-volume, low-margin deployments with standardized fifteen-minute interval logging. Tiered water pricing jurisdictions in California and France drive AMI penetration where consumption visibility enables behavioral demand response.
- Commercial:Office complexes, retail centers, and hospitality facilities concentrate margin pools through sub-metering for tenant billing and cooling tower monitoring. EU F-Gas Regulation compliance documentation requirements intensify data granularity specifications across European commercial segments.
- Industrial:Manufacturing and processing facilities demand explosion-proof housings and custody-transfer accuracy certifications. Chemical and food processing plants in Germany specify electromagnetic meters for process control integration.
- Municipal:City-scale water authorities dominate absolute deployment volumes through centralized procurement of ten-thousand-plus endpoint networks. EPA lead and copper rules alongside state-level water loss mandates shape North American municipal technical specifications.
Municipal end users dominate absolute shipment volumes while commercial segments deliver superior margin contribution per endpoint.
Deployment:
Architecture selection governs cybersecurity exposure profiles and total cost of ownership trajectories.
- Cloud-Based:Fully managed SaaS platforms shift capital expenditure to operational budgets with guaranteed uptime service level agreements. German and South Korean mid-size utilities increasingly specify these outcome-based contracts over equipment-only procurement.
- On-Premises:Dedicated data centers within utility facilities maintain air-gapped security for critical infrastructure protection. Large municipal authorities in Texas and California retain these for regulatory compliance with state cybersecurity certification requirements.
- Hybrid:Edge processing of flow anomalies combined with cloud-based pattern recognition balances latency and computational scale. Predictive maintenance service models leverage this architecture for leak detection accuracy guarantees.
- Remote:Satellite or cellular backhaul serves dispersed rural networks beyond fiber reach. Agricultural irrigation districts and isolated industrial facilities specify these where terrestrial connectivity infrastructure remains undeveloped.
Cloud-based deployment is expanding most quickly among new procurements while hybrid architectures capture premium positioning for predictive analytics integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utilities and commercial water operators concentrate procurement authority in jurisdictions with binding leakage reduction targets and tiered pricing structures. Germany, the United States, France, South Korea, and Australia anchor deployment volumes through distinct regulatory mechanisms and infrastructure investment cycles.
Germany
LoRaWAN networks serve rural municipalities where cellular density proves economically prohibitive, while NB-IoT adoption accelerates in urban centers. The EU Water Framework Directive and national water loss mandates compress procurement timelines for municipal utilities. Bavarian and North Rhine-Westphalian water authorities specify ultrasonic meters for new installations and accelerated replacement programs.
United States
EPA lead and copper rules alongside state-level mandates in California and Texas shape technical specifications for municipal procurement. California utilities specify solid-state meters for compliance with water loss reduction targets. Texas municipal authorities retain on-premises data architectures for state cybersecurity certification requirements.
France
Binding national smart meter program mandates convert regulatory targets into predictable infrastructure contracts. The EU F-Gas Regulation intensifies monitoring obligations for commercial cooling tower operators. Île-de-France water authorities lead deployment volumes through centralized procurement of ten-thousand-plus endpoint networks.
South Korea
K-water digital transformation initiative anchors municipal deployment volumes through binding procurement mandates. National telecom regulators have expanded dedicated IoT spectrum, accelerating NB-IoT adoption without mesh gateway capital expenditure. Seoul Capital Area utilities specify cloud-based subscription models with guaranteed uptime service level agreements.
Australia
Tiered water pricing jurisdictions in New South Wales and Victoria drive AMI penetration where consumption visibility enables behavioral demand response. State-level water loss mandates compress replacement cycles for legacy mechanical meters. Sydney and Melbourne municipal authorities specify fifteen-minute interval logging for leak detection accuracy.
Smart Water Metering Market Vendor Landscape
Channel-controlling players compete with product-specialist players across meter hardware, communication modules, and data analytics software. The vendor base stratifies into three tiers: vertically integrated sensor-to-software stacks, communication-focused endpoint specialists, and pure-play meter manufacturers. Dominant competitive moves include outcome-based service level agreements that unbundle hardware from data analytics, and strategic partnerships between AMI vendors and telecom carriers for licensed spectrum access.
Within the integrated-solution tier, Xylem (Sensus) and Kamstrup A/S exemplify archetypes of vertically stacked competition. Xylem anchors large municipal contracts through captive software capabilities, while Kamstrup occupies a position defined by manufacturing scale and ultrasonic R&D intensity. Badger Meter Inc. represents the cellular-specialist archetype, serving mid-size utilities seeking rapid deployment without gateway infrastructure construction timelines.
| Leading Market Players |
|---|
| Itron Inc. |
| Xylem (Sensus) |
| Badger Meter Inc. |
| Kamstrup A/S |
| Diehl Stiftung & Co. KG |
| Neptune Technology Group Inc. |
| Honeywell International Inc. |
| Landis+Gyr |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors connecting East Asian semiconductor foundries to North American utility distribution centers transmit input cost volatility directly into AMI hardware pricing tiers, compressing margins for communication module vendors while enabling premium capture by vertically integrated sensor-to-software stacks.
Pricing Analysis
Cost-plus contracts with quarterly aluminum and copper indexation dominate municipal procurement frameworks across Germany and California. Three-tier pricing structure across premium, standard, and economy levels separates ultrasonic solid-state meters with predictive analytics bundling from basic mechanical replacements and stripped cellular endpoints. Cost compression in mid-tier cellular modules is intensifying because telecom carriers impose recurring spectrum licensing fees that inflate total cost of ownership. Mid-size municipal utilities exhibit highest price sensitivity due to constrained capital budgets, while large water authorities with binding leakage reduction mandates show lowest sensitivity to unit premiums.
Supply Chain Analysis
Upstream feedstock for ultrasonic transducer ceramics and NB-IoT communication chipsets draws from concentrated manufacturing bases in Taiwan, South Korea, and Japan. Raw material dependencies center on rare-earth elements for sensor magnetics, copper for electromagnetic coils, and silicon wafers for semiconductor modules. Single-source vulnerability in advanced node foundry capacity exposes AMI vendors to allocation risk during demand surges. Distribution runs through authorized distributor networks serving municipal procurement committees, with direct OEM relationships commanding large-scale utility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of cybersecurity-certified firmware engineering talent constrains vendor capacity to meet tightening critical infrastructure IoT standards across multiple national regulatory regimes.
For Market Incumbents: Build switching-cost moats through captive software subscription bundling that embeds predictive leak detection algorithms within fifteen-year service agreements. Defensive moves require backward integration into ultrasonic transducer manufacturing to secure supply continuity against East Asian foundry allocation risk. Capacity addition in Danish and German assembly facilities addresses EU Water Framework Directive procurement acceleration. For New Entrants and Emerging Players: Establish a beachhead in commercial sub-metering for cooling tower monitoring applications where EU F-Gas Regulation compliance documentation creates underpenetrated demand. White-space targets include tenant billing systems in multi-tenant office complexes and hospitality facilities seeking granular consumption visibility. Go-to-market execution through HVAC service contractor channels bypasses entrenched utility procurement gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with stranded water metering divisions lacking cloud-native software capabilities. Long-term viability favors vendors with demonstrated NB-IoT carrier partnerships and certified cybersecurity engineering benches. Watch national telecom regulator spectrum allocation decisions as inflection indicators for connectivity economics shifts.| Strategic Initiative | Industry Significance |
|---|---|
| NB-IoT Carrier Partnership | Secures licensed spectrum access without proprietary mesh gateway capital expenditure for municipal utilities. |
| Ultrasonic R&D Scale-Up | Accelerates solid-state meter displacement of mechanical installed base in California and Texas replacement programs. |
| Predictive Analytics Platform Launch | Enables outcome-based service level agreements with guaranteed leak detection accuracy for German utilities. |
| Cybersecurity Certification Investment | Addresses fragmented national critical infrastructure IoT standards across EPA, EU, and South Korean MFDS regimes. |
| Commercial Sub-Metering Expansion | Captures margin pools in cooling tower monitoring where EU F-Gas Regulation intensifies data granularity requirements. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA enforcement actions, EU Water Framework Directive implementation reports, and 3GPP standardization documentation. Utility planning officers, AMI procurement managers at municipal water authorities, telecom carrier IoT product leads, and ultrasonic sensor R&D directors contributed structured interviews. Secondary validation drew from FERC filings on water infrastructure investment, SEC 10-K disclosures by listed meter manufacturers, and customs data on communication module trade flows. Bottom-up endpoint deployment estimates triangulate against top-down utility capital expenditure budgets.
Forecast inputs consider technology substitution curves between mechanical and solid-state meters, NB-IoT network coverage expansion timelines by national carriers, and regulatory procurement mandate binding dates. Segmentation dimensions span product type, connectivity protocol, end-user scale, and deployment architecture across the analysis window. CAGRs derive from utility replacement cycle acceleration rates and smart city infrastructure budget allocation patterns. Industry-specific inputs include state-level water loss mandate enforcement intensity and tiered water pricing jurisdiction expansion.
Sensitivities concentrate around semiconductor foundry capacity allocation, national telecom regulator spectrum licensing fee revisions, and cybersecurity certification timeline extensions. Forecasts reflect documented assumptions on carrier IoT network buildout pace and municipal procurement committee SaaS adoption willingness. Cross-checking against IEA water infrastructure investment benchmarks and national statistical office utility capex surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Gas Meters Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
Watt Meter Market