
 LNG Terminal Market | 2026-2036
LNG Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Terminal Market Foresight
Large-scale capacity specifications above ten million tonnes per annum is redrawing procurement criteria for EPC contracts. Cheniere Energy leverages its Gulf Coast liquefaction position to anchor long-term offtake structures. Bechtel Corporation dominates mega-project execution with proprietary modular construction methodologies. Technip Energies N.V. differentiates through integrated floating LNG solutions that reduce coastal land constraints.
An LNG terminal comprises engineered facilities for receiving, storing, and regasifying liquefied natural gas at temperatures near minus 162 degrees Celsius, with cryogenic storage tanks designed to maintain boil-off rates below 0.05 percent daily. These installations serve as critical infrastructure nodes connecting intercontinental gas trade to downstream distribution networks. Floating LNG technology captures expanding margin pools where coastal land scarcity or environmental permitting limits onshore development. Small and medium scale terminals represent the fastest-growing capacity tier, serving industrial clusters and power generation applications in markets lacking pipeline backbone density. Onshore regasification remains the mature baseline, though storage and peak-shaving functions now attract incremental investment alongside base-load import facilities.
The Federal Energy Regulatory Commission governs US terminal siting and environmental review, while the EU F-Gas Regulation constrains refrigerant selection for liquefaction cycles, directly shaping equipment specifications and project economics. China's Ministry of Ecology and Environment enforces emissions benchmarks that filter technology choices for new import terminals along its eastern seaboard. India's Petroleum and Natural Gas Regulatory Board mandates open-access regasification tariffs, altering how terminal operators structure capacity bookings. Stakeholders must weigh regulatory compliance timelines against contracting windows as carbon border adjustments and methane intensity standards redefine terminal competitiveness.
Market Dynamics
Asia-Pacific power utilities are driving a structural capacity expansion cycle as coal displacement mandates from regulators in China, India, and Japan force accelerated regasification investments. Floating LNG technology is compressing project timelines where coastal land scarcity previously blocked development.
Growth Catalysts
- IMO Carbon Intensity Regulations:The International Maritime Organization's bunker fuel standards are compelling port authorities across Singapore, Rotterdam, and Houston to install LNG bunkering infrastructure. Vessel operators face compliance deadlines that favor dual-fuel engine retrofits.
- Industrial Cluster Demand:Steel and fertilizer manufacturers in Gujarat and Odisha are contracting for direct LNG terminal connections. Pipeline bypass requirements from India's Petroleum and Natural Gas Regulatory Board accelerate small-scale terminal development.
- Modular Construction Methods:Standardized cryogenic tank fabrication in South Korean and Chinese yards is compressing EPC schedules. Pre-fabrication ratios above 70 percent reduce on-site labor requirements and weather risk.
Market Restraints
- Nickel Alloy Supply Concentration:Cryogenic storage tank construction depends on 9-percent nickel steel plate production concentrated in Japanese and Austrian mills. Mill lead times extending beyond 18 months constrain terminal commissioning schedules.
- EU F-Gas Refrigerant Constraints:The EU F-Gas Regulation phases down hydrofluorocarbon availability for liquefaction cycles. Project developers face equipment specification changes mid-construction as refrigerant alternatives require redesigned compressor trains.
- Electrification Substitution:Battery storage and green hydrogen pilot projects in German and Dutch industrial zones compete for the same grid interconnection capacity. Utility planners delay final investment decisions on LNG terminals where electrification pathways appear viable.
Strategic Opportunities
- Vietnam Coastal Development:The Thi Vai and Son My port complexes lack pipeline backbone density. Floating storage and regasification unit deployments can serve dispersed manufacturing zones before onshore infrastructure matures.
- ISO 19870 Certification Pathways:The ISO methane emissions quantification standard creates differentiation for terminal operators demonstrating verified intensity performance. Cargo buyers in Japan and South Korea are embedding certification requirements into term contracts.
- Bio-LNG Convergence:Biomethane liquefaction integrated with conventional LNG terminals allows shared storage and regasification assets. European terminals in Rotterdam and Zeebrugge are retrofitting receipt facilities for bio-LNG truck loading.
Industry Challenges
- Cryogenic Welding Certification Shortage:Qualified 9-percent nickel steel welders require specialized ASME Section IX qualifications. Training program throughput in India and Southeast Asia lags project staffing requirements by 40 percent.
- Legacy SCADA Integration:Brownfield terminal expansions must interface with 1990s-era distributed control systems. Cybersecurity hardening of obsolete protocols adds six to nine months to commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Terminal Market |
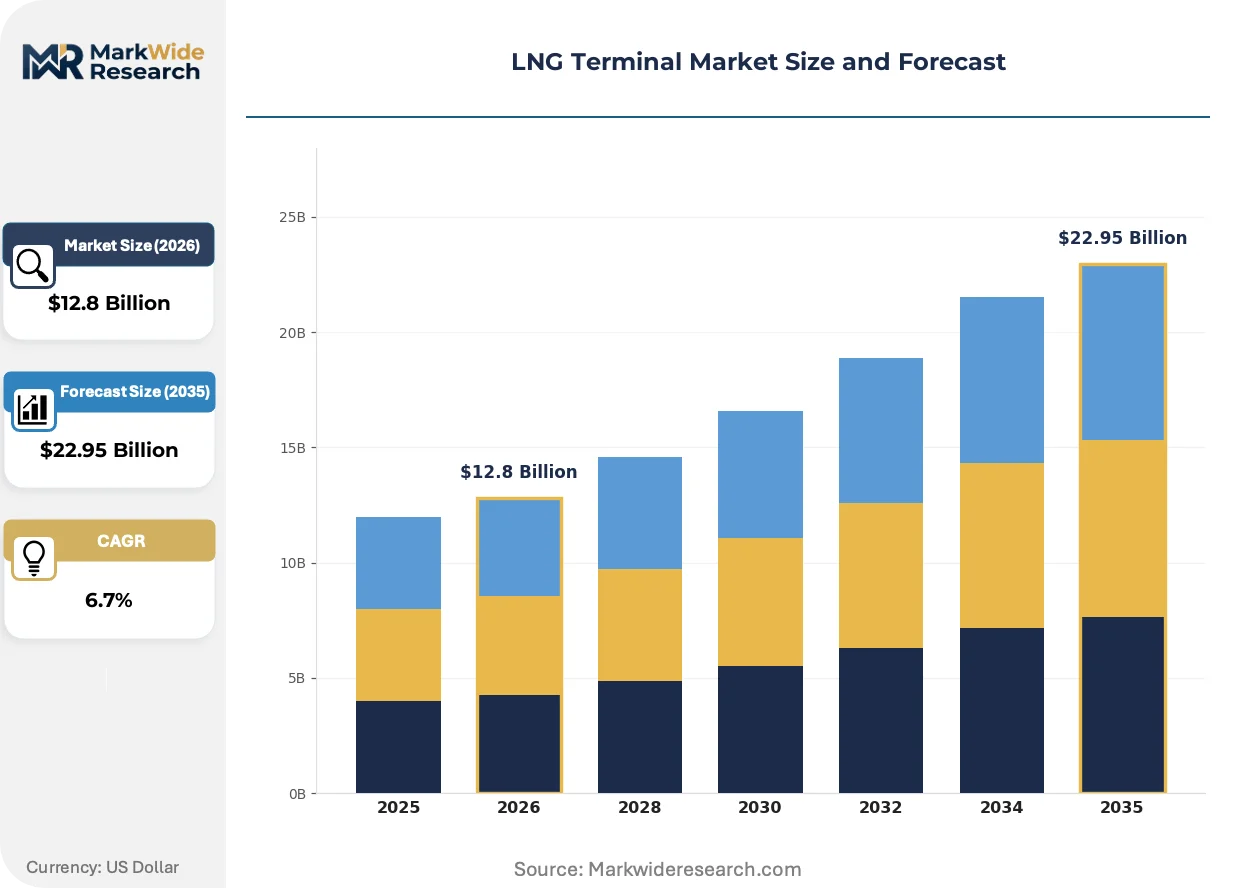
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Floating LNG, Onshore LNG, Regasification, Storage End User: Utilities, Industrial Consumers, Shipping Companies, Export Facilities Application: Power Generation, Transportation, Heating, Chemical Feedstock Capacity: Small Scale, Medium Scale, Large Scale, Extra Large |
| Companies Covered | Cheniere Energy Inc., Technip Energies N.V., Bechtel Corporation, Shell plc, QatarEnergy, TotalEnergies SE, SAIPEM SpA, Samsung C&T Corporation, JGC HOLDINGS CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Terminal Market Shifts & Advancements
Modular fabrication and emissions quantification protocols are restructuring how terminal developers approach project delivery and commercial differentiation. Technology choices increasingly reflect regulatory compliance requirements rather than pure cost optimization.
Floating LNG regasification units are displacing onshore terminal development in markets with severe coastal land constraints or environmental permitting bottlenecks. Bangladesh and Pakistan have commissioned FSRU-based import capacity at half the development timeline of greenfield onshore alternatives. The technology is displacing traditional EPC contracting models by shifting construction risk to vessel owners and converting capital expenditure to operating lease structures.
China's Ministry of Ecology and Environment enforces emissions benchmarks that filter technology choices for new import terminals along the eastern seaboard. The MEE standards mandate continuous methane monitoring and flare minimization protocols that increase instrumentation density by 30 percent. European and Japanese equipment suppliers are adapting product lines to meet these specifications for the Chinese market.
Power utilities in India and Southeast Asia are unbundling terminal capacity bookings from commodity supply contracts. Open-access tariff structures from the Petroleum and Natural Gas Regulatory Board enable third-party cargo aggregation at import facilities. This procurement fragmentation is most visible in Gujarat, where industrial buyers now contract directly with portfolio players rather than relying on integrated utility supply.
LNG Terminal Market Segmentation
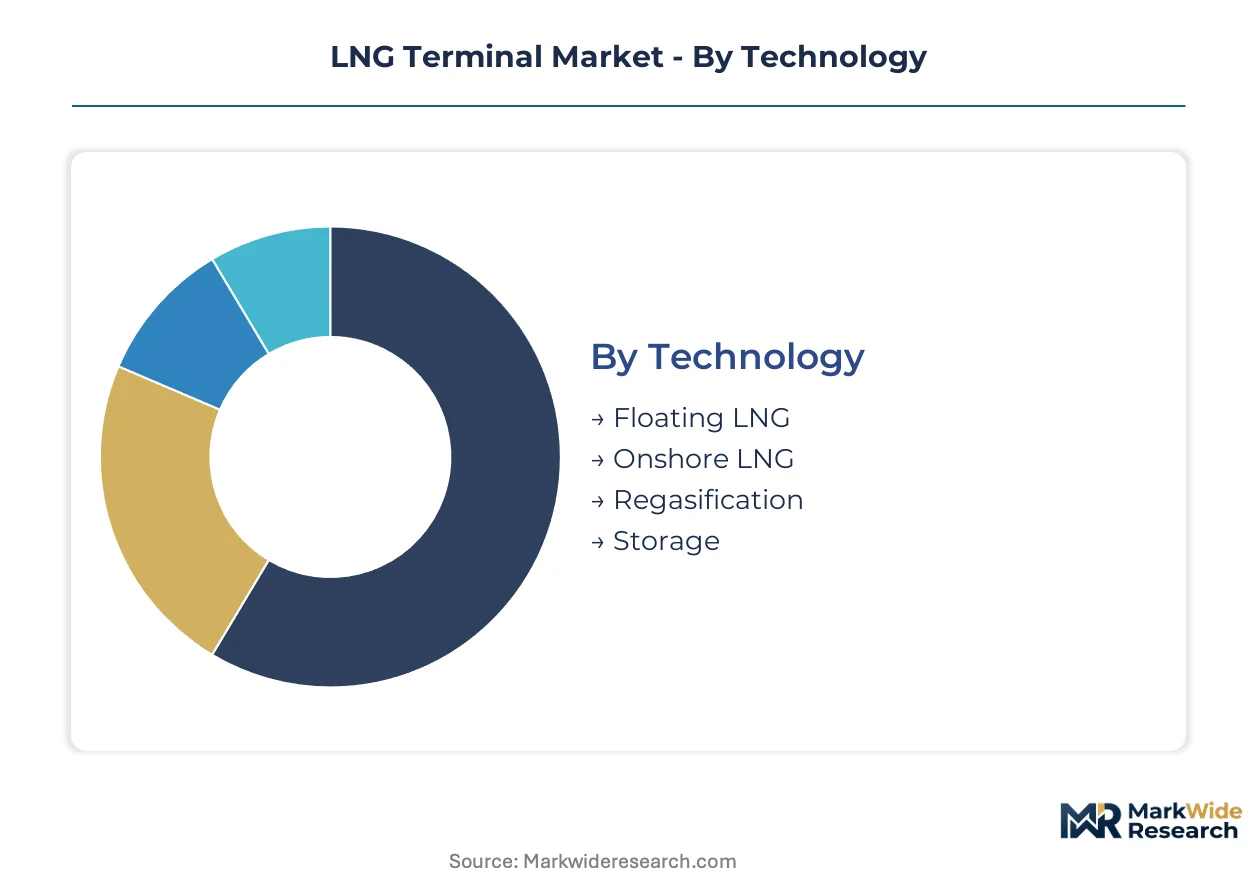
Terminal developers structure investment decisions around technology risk profiles and capacity utilization curves. Segment boundaries increasingly blur as floating solutions scale upward and onshore facilities adopt modular construction methods. Procurement patterns diverge sharply between baseload power utilities and industrial off-takers seeking peaking flexibility.
Technology:
Domestic demand concentrates in onshore regasification along established pipeline corridors, while export-led growth flows through floating LNG where coastal land scarcity blocks conventional development.
- Onshore LNG:Cryogenic storage tanks with 9-percent nickel steel construction anchor base-load import capacity. Power utilities in India and Japan favor this technology for its operational predictability and lower long-term unit costs. The FERC governs US terminal siting with environmental review timelines that favor brownfield expansions over greenfield projects.
- Floating LNG:FSRU vessels convert capital expenditure to operating lease structures, compressing development timelines by half. Bangladesh and Pakistan commissioned floating capacity ahead of onshore alternatives where permitting bottlenecks stalled progress. Singapore and Rotterdam port authorities deploy floating bunkering infrastructure to meet IMO carbon intensity deadlines.
- Regasification:Open-access tariff mandates from India's Petroleum and Natural Gas Regulatory Board reshape how terminal operators structure capacity bookings.
- Storage:Peak-shaving functions attract incremental investment alongside base-load facilities, with boil-off rates below 0.05 percent daily as the design threshold.
Onshore LNG commands the established base. The steepest expansion runs through Floating LNG.
End User:
Cost tier differentiation separates integrated utilities with long-term offtake security from industrial buyers procuring spot-indexed volumes.
- Utilities:Coal displacement mandates from China's Ministry of Ecology and Environment and Japan's METI force accelerated regasification investments. These buyers anchor terminal economics through 20-year tolling agreements with take-or-pay structures.
- Industrial Consumers:Steel and fertilizer manufacturers in Gujarat and Odisha contract for direct terminal connections, bypassing pipeline networks. India's Petroleum and Natural Gas Regulatory Board mandates open-access tariffs that enable third-party cargo aggregation.
- Shipping Companies:Dual-fuel engine retrofits drive bunkering demand at Singapore, Rotterdam, and Houston port complexes.
- Export Facilities:Cheniere Energy leverages Gulf Coast liquefaction position to anchor long-term offtake structures into Asian markets.
Utilities retain the volume anchor position. Industrial Consumers are climbing the fastest as procurement fragmentation accelerates.
Application:
Application mix shifts with electrification pathways competing for grid interconnection capacity in German and Dutch industrial zones.
- Power Generation:Asia-Pacific utilities expand regasification capacity to displace coal-fired baseload, with China, India, and Japan driving the structural expansion cycle. The EU F-Gas Regulation constrains refrigerant selection for liquefaction cycles, directly shaping equipment specifications.
- Chemical Feedstock:Ammonia and methanol producers favor direct terminal connections for feedstock security, particularly in clusters lacking pipeline backbone density.
- Transportation:IMO bunker fuel standards compel port authority infrastructure investments across compliance deadlines.
- Heating:Seasonal demand peaks strain storage and peak-shaving functions in markets with limited underground gas storage.
Power Generation holds the incumbent share. Chemical Feedstock is gaining share fastest as industrial cluster demand concentrates.
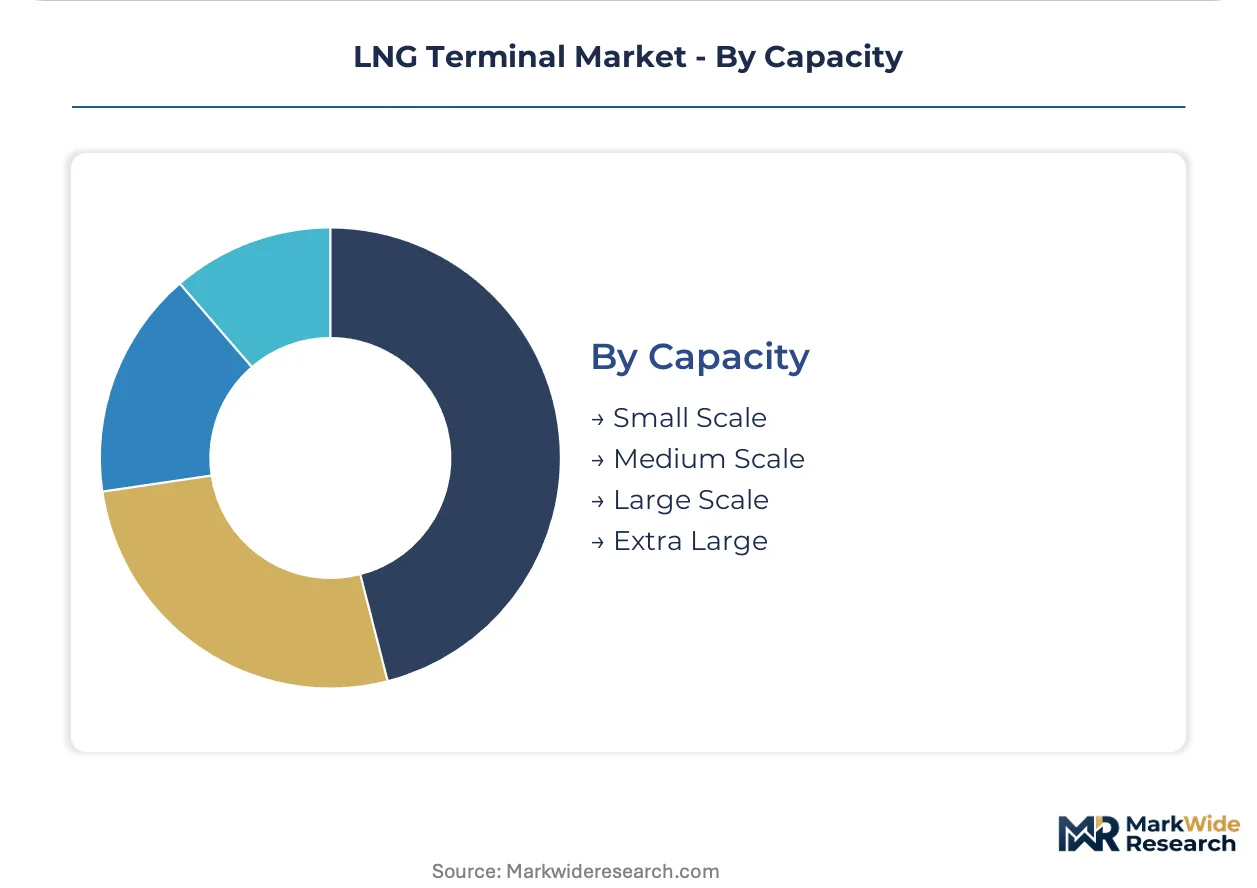
Capacity:
Volume tiering separates mega-projects above ten million tonnes per annum from modular small-scale deployments serving dispersed manufacturing zones.
- Large Scale:Specifications above ten million tonnes per annum redraw procurement criteria for EPC contracts, with Bechtel Corporation dominating execution through proprietary modular methodologies. These terminals connect to trunk pipeline networks serving multiple downstream offtakers.
- Small Scale:Industrial clusters and power generation applications in markets lacking pipeline backbone density drive the fastest capacity additions. Vietnam's Thi Vai and Son My port complexes exemplify where floating storage and regasification units serve dispersed zones before onshore infrastructure matures.
- Medium Scale:Standardized cryogenic tank fabrication in South Korean and Chinese yards compresses EPC schedules for mid-tier deployments.
- Extra Large:Qatar's expansion trains and US Gulf Coast liquefaction complexes define this tier, with unit costs amortized across massive throughput volumes.
Large Scale anchors the installed base. Small Scale shows the steepest expansion trajectory as modular methods penetrate fragmented demand pockets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
QatarEnergy exports from Ras Laffan anchor liquefaction volumes into Asian demand centers, with India and China absorbing expanding cargo flows through dedicated terminal infrastructure.
United States
Gulf Coast liquefaction complexes feed Asian and European offtake contracts through FERC-regulated export terminals. The FERC governs siting and environmental review timelines that favor brownfield expansions. Cheniere Energy anchors long-term structures from Louisiana and Texas liquefaction trains.
China
Power utilities along the eastern seaboard expand regasification capacity to displace coal-fired baseload under MEE emissions benchmarks. The Ministry of Ecology and Environment mandates continuous methane monitoring and flare minimization protocols. Shandong and Jiangsu provinces concentrate new import terminal construction.
India
Steel and fertilizer manufacturers in Gujarat and Odisha contract for direct terminal connections bypassing pipeline networks. The Petroleum and Natural Gas Regulatory Board mandates open-access regasification tariffs enabling third-party cargo aggregation. Dahej and Hazira port complexes anchor the fastest capacity additions.
Japan
Power utilities anchor terminal economics through 20-year tolling agreements with take-or-pay structures under METI coal displacement mandates. Chubu Electric and Tokyo Gas operate base-load import facilities serving Kanto and Chubu industrial zones. METI regulations force accelerated regasification investments.
Germany
Battery storage and green hydrogen pilot projects compete for grid interconnection capacity in industrial zones. The EU F-Gas Regulation constrains refrigerant selection for liquefaction cycles, shaping equipment specifications. Wilhelmshaven and Brunsbüttel terminals serve as diversification nodes reducing Russian pipeline dependence.
LNG Terminal Market Competitive Landscape
Listed energy majors compete with private EPC specialists across project execution risk allocation. The vendor base separates into liquefaction developers, engineering contractors, and integrated oil and gas portfolios. Three archetypes dominate: Gulf Coast export developers, European modular construction specialists, and Asian yard-integrated fabricators. Capacity expansion and technology licensing constitute the primary competitive vectors.
Among liquefaction-focused developers, Cheniere Energy exemplifies the tolling-structured export model. Within the EPC execution tier, Bechtel Corporation and Technip Energies N.V. occupy distinct positions—Bechtel through proprietary modular methodologies and Technip Energies through integrated floating LNG solutions. Samsung C&T Corporation represents the Asian yard-integrated archetype, leveraging South Korean fabrication capacity for cryogenic tank construction.
| Leading Market Players |
|---|
| Cheniere Energy Inc. |
| Technip Energies N.V. |
| Bechtel Corporation |
| Shell plc |
| QatarEnergy |
| TotalEnergies SE |
| SAIPEM SpA |
| Samsung C&T Corporation |
| JGC HOLDINGS CORPORATION |
| Others |
Supply & Pricing Matrix
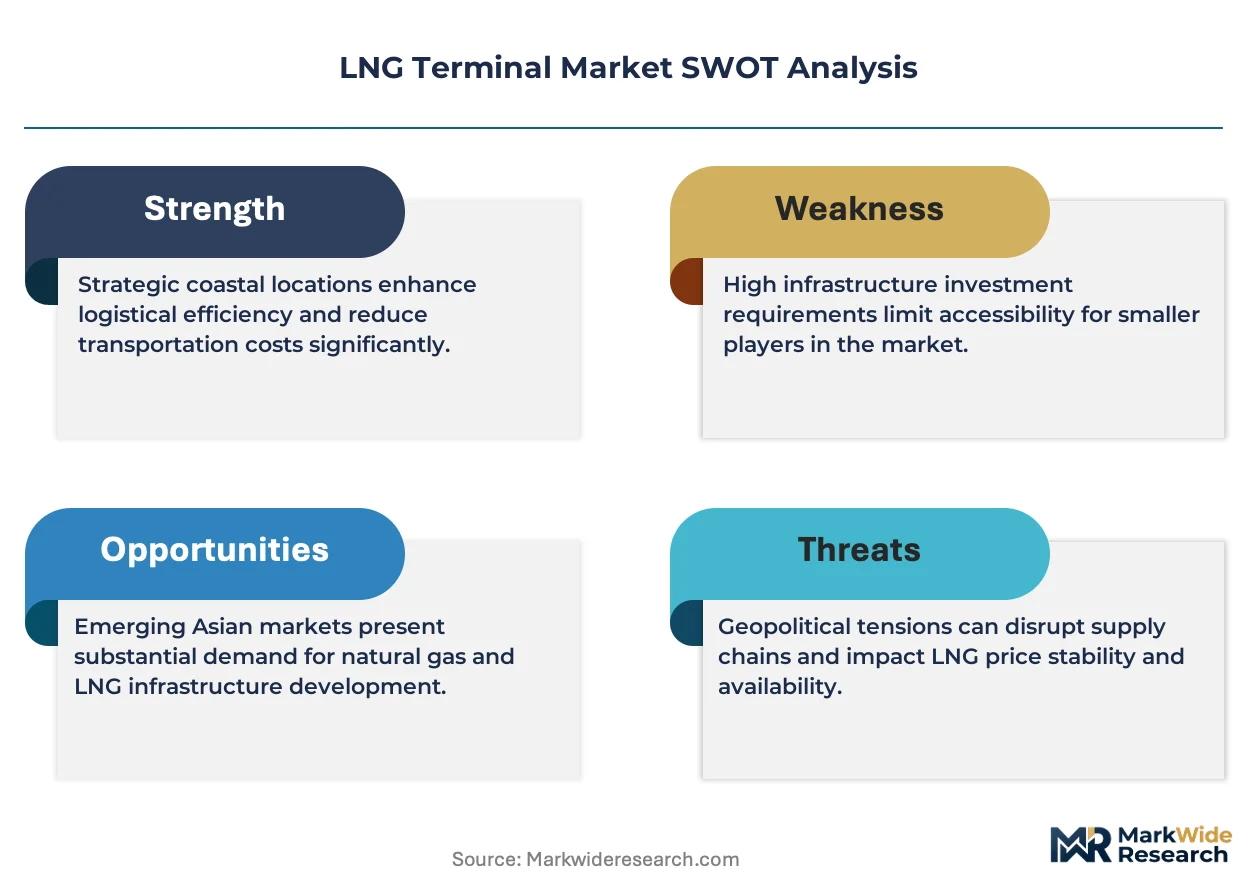
ISO 19870 methane certification gates both supplier qualification and price differentiation simultaneously, separating terminals with verified emissions performance from commodity competitors in Japanese and South Korean procurement. Buyers embed certification requirements into term contracts, creating tiered value capture that rewards instrumentation density and flare minimization protocols.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate terminal economics. Price differentiation stems from ISO 19870 certification tier and volume scale commitments, with verified low-methane terminals commanding premiums over uncertified competitors. Cost compression in standard-grade capacity is intensifying because modular fabrication in South Korean and Chinese yards compresses EPC schedules. Power utilities exhibit the least price sensitivity due to coal displacement mandates, while industrial consumers in Gujarat and Odisha show highest sensitivity as they aggregate third-party cargoes through open-access tariffs.
Supply Chain Analysis
Port congestion along the Asia-Europe trade lane elevates inbound logistics costs for cryogenic equipment and specialized alloys. Supply concentrates in Japanese and Austrian mills for 9-percent nickel steel plate, with South Korean and Chinese yards dominating modular cryogenic tank fabrication. Raw material dependencies include nickel alloy plate, specialized refrigerants constrained by EU F-Gas Regulation phase-downs, and ASME-certified welding consumables. Single-source vulnerability in nickel alloy supply creates structural risk as mill lead times extend. Distribution runs through EPC contractors with proprietary modular methodologies or integrated floating LNG solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward fragmented industrial off-takers in India and Southeast Asia as open-access tariffs unbundle terminal capacity from commodity supply. Procurement fragmentation accelerates as steel and fertilizer manufacturers contract directly with portfolio players rather than integrated utilities.
For Market Incumbents: Shield terminal economics by securing backward integration into cryogenic tank fabrication capacity in South Korean yards. Invest in ISO 19870 certification pathways before Japanese and South Korean buyers harden requirements into term contracts. Defend against floating LNG entrants by emphasizing operational predictability and lower long-term unit costs in onshore baseload positions. For New Entrants and Emerging Players: Lead with small-scale modular deployments in Vietnam's Thi Vai and Son My port complexes where pipeline backbone density remains underdeveloped. Target industrial cluster demand in Gujarat and Odisha with direct terminal connections bypassing pipeline networks. Pursue FSRU-based lease structures that convert capital expenditure to operating costs and compress development timelines. For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant phase-downs reshape the acquisition landscape toward terminals with adaptable liquefaction cycles and alternative compressor train designs. Long-term viability favors assets with demonstrated methane intensity performance and coastal positions serving coal displacement demand. Watch for ISO 19870 certification requirements embedding into Japanese and South Korean term contracts as the inflection signal for terminal competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19870 Certification Investment | Verified methane intensity performance differentiates terminals in Japanese and South Korean procurement. |
| Backward Integration into Fabrication | Captive cryogenic tank construction in South Korean yards secures supply and compresses EPC schedules. |
| Floating LNG Fleet Expansion | FSRU deployments capture margin pools where coastal land scarcity blocks onshore development. |
| Open-Access Tariff Optimization | Third-party cargo aggregation structures align with India's Petroleum and Natural Gas Regulatory Board mandates. |
| Refrigerant Adaptation Program | Alternative compressor train designs future-proof terminals against EU F-Gas Regulation phase-down constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across terminal developers, EPC contractors, power utility planning officers, and industrial procurement leads at steel and fertilizer manufacturers. Secondary validation drew from FERC filings, IEA reports, EIA data, and project development databases tracking liquefaction and regasification capacity. Bottom-up capacity buildout models triangulated with top-down trade flow analysis across the analysis window.
Across the projection horizon, forecasts segmented by technology type, end-user category, application, and capacity tier. CAGRs derived from unit cost trajectories, modular fabrication penetration rates, and regulatory compliance timelines. Industry-specific inputs included IMO carbon intensity regulation deadlines, EU F-Gas refrigerant phase-down schedules, and India's open-access tariff implementation progress.
Forecasts assume regulatory continuity in FERC siting timelines, EU F-Gas phase-down schedules, and India's Petroleum and Natural Gas Regulatory Board open-access mandates; material policy shifts would require re-modeling. Commodity price volatility in nickel alloys and refrigerant alternatives presents revision risk. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Frac Stack Market
Oil & Gas
Subsea Well Access System Market