
 Global Smart Water Meter Market | 2026-2036
Global Smart Water Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Water Meter Market Foresight
Composite polymer housings replacing brass castings is recalibrating unit economics across the Global Smart Water Meter Market. Itron Inc. leverages in-house RF module production to sustain margin control across North American utility contracts. Badger Meter Inc. anchors its position through specialized ultrasonic R&D pipelines. Kamstrup A/S dominates European deployments with district-metering expertise and wireless M-Bus certification depth.
A smart water meter is an electromechanical device equipped with flow sensors, data loggers, and communication modules that measure water consumption and transmit readings remotely at intervals as frequent as every fifteen minutes. Its primary commercial purpose is to eliminate manual meter reading, detect distribution network leaks in real time, and enable time-of-use tariff structures for conservation pricing. Ultrasonic product types lead value generation due to zero moving parts and extended calibration intervals, while NB-IoT technology segments are expanding fastest where cellular infrastructure already blankets dense urban cores. Residential application categories remain the volume anchor, though commercial facilities segments concentrate margin pools through multi-point submetering requirements.
The EPA's Lead and Copper Rule Revisions in the United States mandate enhanced leak detection infrastructure, directly expanding smart meter procurement scope for American water utilities. EMA and ECHA frameworks across Europe enforce electromagnetic compatibility and substance restriction standards that shape product certification pathways for meter manufacturers. China's MIIT and NMPA coordinate NB-IoT spectrum allocation with metering accuracy standards, compressing deployment timelines for domestic vendors. Stakeholders must weigh communication protocol longevity against municipal procurement cycle durations when committing to platform architectures.
Market Dynamics
The EU Green Deal's water efficiency mandates are compressing procurement cycles across European municipal utilities, forcing simultaneous upgrades to AMI infrastructure and billing systems that were historically staggered over decades.
Growth Catalysts
- NB-IoT spectrum allocation:China's MIIT and NMPA coordination of metering accuracy standards with cellular deployment is accelerating domestic vendor rollout timelines and reducing certification friction for new entrants.
- Lead and Copper Rule Revisions:The EPA mandate for enhanced leak detection infrastructure in the United States is directly expanding smart meter procurement scope for American water utilities beyond basic AMR replacement.
- Ultrasonic R&D pipelines:Specialized development of zero-moving-part measurement technologies is extending calibration intervals and reducing total cost of ownership for drought-prone urban districts in California.
Market Restraints
- Brass casting supply concentration:Composite polymer housings are displacing traditional metal castings, but raw material volatility in specialized polymer resins creates margin compression for housing manufacturers.
- Wireless M-Bus certification depth:European deployments require extensive district-metering expertise and protocol certification that creates bottlenecks for vendors lacking multi-year installation track records.
- Cellular infrastructure dependency:NB-IoT segments expand fastest only where dense urban cores already blanket coverage, leaving rural and ex-urban utilities with higher-cost proprietary network requirements.
Strategic Opportunities
- Commercial submetering:Multi-point measurement requirements in commercial facilities concentrate margin pools beyond residential volume anchors, with specialized ultrasonic configurations commanding pricing premiums.
- Time-of-use tariff structures:Conservation pricing frameworks enabled by fifteen-minute interval data logging create new revenue streams for utilities and metering-as-a-service providers.
- Real-time distribution monitoring:Integration of flow sensors with data loggers and communication modules enables leak detection services that utilities can monetize separately from commodity water sales.
Industry Challenges
- Protocol longevity commitment:Stakeholders must weigh communication architecture lifespan against municipal procurement cycle durations spanning 15-20 years, creating stranded asset risk for early technology adopters.
- RF module integration complexity:In-house production capabilities separate margin-sustaining vendors from contract-dependent competitors, requiring capital intensity that mid-tier players struggle to match.
- Electromagnetic compatibility certification:EMA and ECHA frameworks enforce substance restriction standards that reshape product development timelines and require dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Water Meter Market |
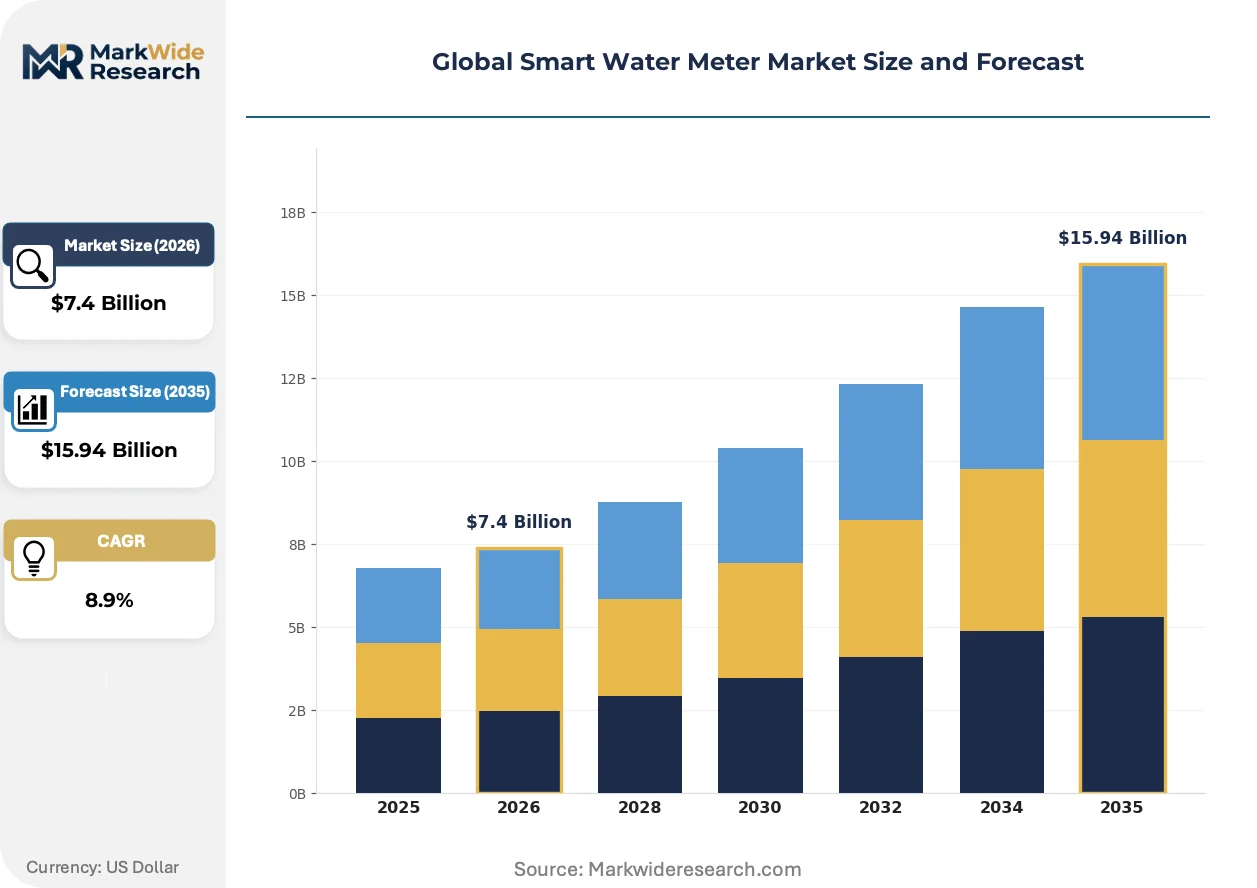
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.94 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
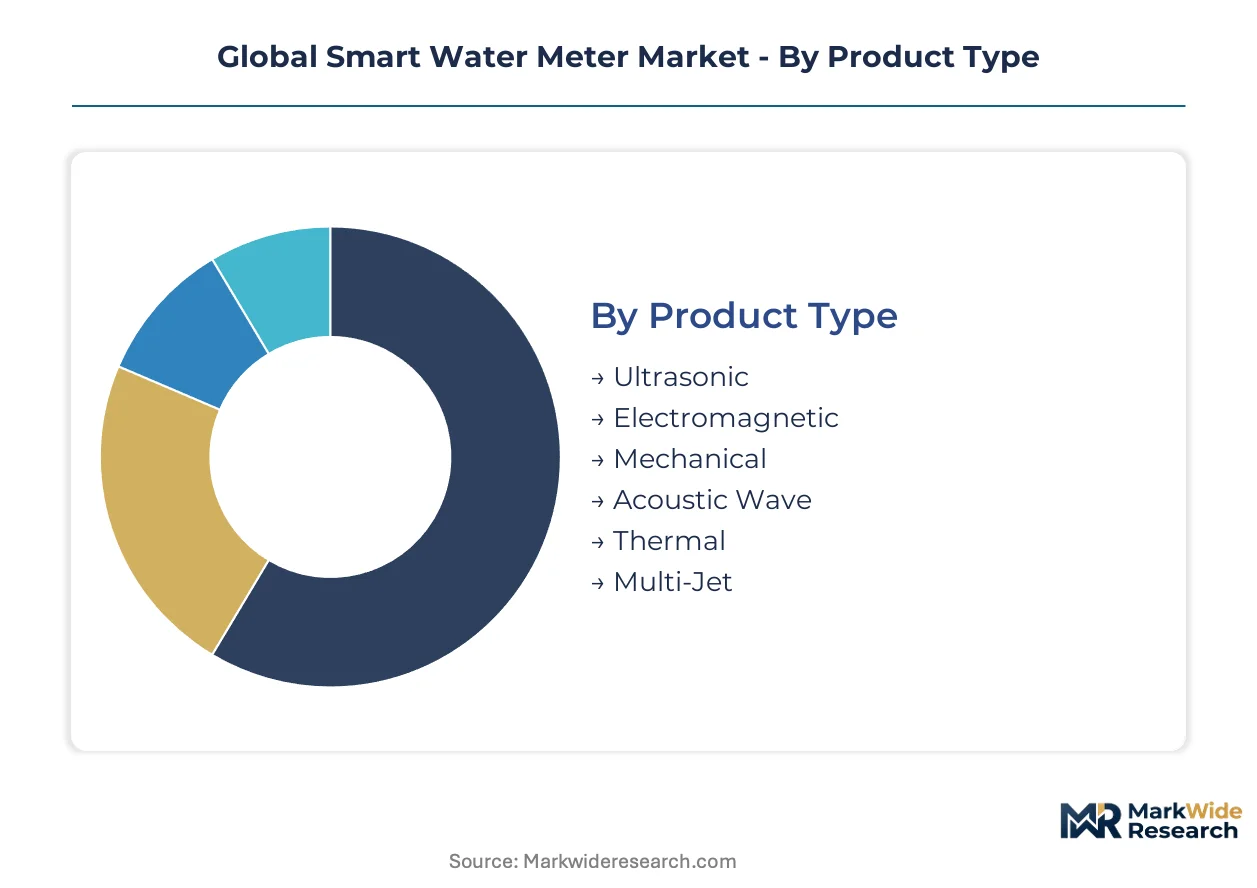
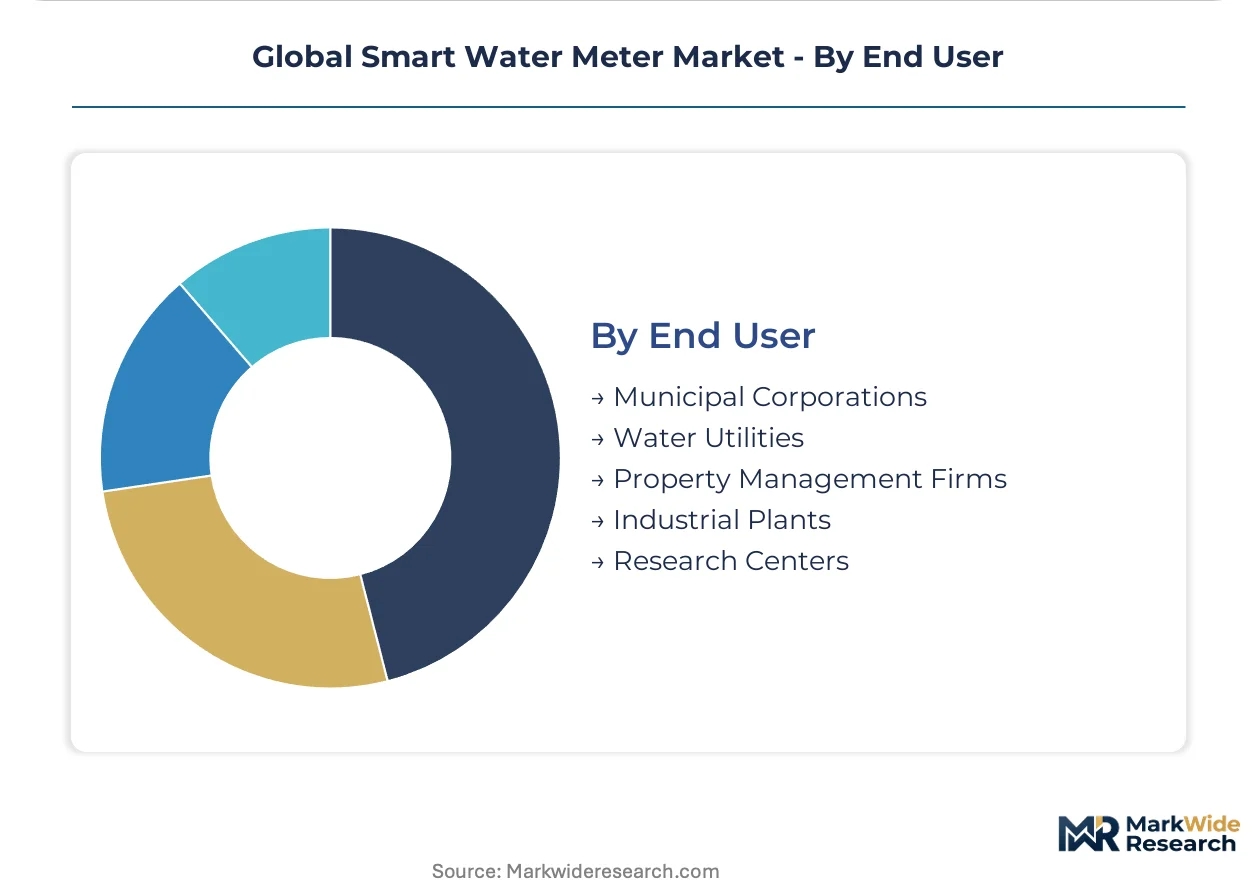
| Segmentation | Product Type: Ultrasonic, Electromagnetic, Mechanical, Acoustic Wave, Thermal, Multi-Jet Technology: IoT, RF Communication, AMR, Wireless M-Bus, PLC, NB-IoT Application: Residential, Commercial Facilities, Public Utilities, Educational Institutions, Hospitality Sector, Government Buildings End User: Municipal Corporations, Water Utilities, Property Management Firms, Industrial Plants, Research Centers |
| Companies Covered | Itron Inc., Xylem (Sensus), Badger Meter Inc., Landis+Gyr, Kamstrup A/S, Diehl Stiftung & Co. KG, Neptune Technology Group Inc., Honeywell International Inc., ZENNER International GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Water Meter Market Shifts & Advancements
Measurement architecture is shifting from mechanical displacement to acoustic time-of-flight sensing, while communication backbones migrate from proprietary mesh networks to licensed cellular spectrum. These transitions are compressing vendor differentiation around software analytics rather than hardware accuracy.
Ultrasonic time-of-flight sensing is decentralizing meter maintenance economics by eliminating wear-prone mechanical impellers. California's drought-prone urban districts are adopting these configurations at accelerated pace to extend field service intervals. The technology is decentralizing capital deployment patterns, allowing utilities to redirect maintenance budgets toward AMI network expansion rather than periodic meter replacement programs.
The EPA's Lead and Copper Rule Revisions are mandating infrastructure visibility that legacy AMR systems cannot provide. American water utilities must now detect distribution network leaks in real time or face regulatory non-compliance. Residential application categories face the steepest compliance cost escalation, driving consolidation around vendors with integrated leak detection algorithms.
Buyer concentration among large municipal utilities is compressing vendor sales cycles and unbundling after-sales service contracts. Procurement departments now separate hardware acquisition from data analytics subscriptions, forcing meter manufacturers to compete on recurring software revenue rather than upfront equipment margins. Germany's municipal water utilities exemplify this pattern, with EU Green Deal procurement frameworks requiring transparent lifecycle cost evaluation.
Global Smart Water Meter Market Segmentation
Smart water meter procurement decisions diverge sharply across technical specifications, with certification requirements and infrastructure compatibility filtering vendor eligibility before price negotiations begin. Segment boundaries reflect not just functional differences but procurement cycle timing, regulatory pressure intensity, and total cost of ownership calculations that reshape utility capital allocation.
Product Type:
EMA electromagnetic compatibility certification and ECHA substance restriction standards apply differentially across product categories, with ultrasonic and electromagnetic configurations facing stricter protocol validation than mechanical alternatives.
- Ultrasonic:Time-of-flight acoustic sensing eliminates mechanical wear components entirely. California's drought-prone urban districts concentrate procurement here for extended calibration intervals and reduced field service requirements.
- Electromagnetic:Faraday's law-based flow measurement delivers accuracy across turbid water conditions without flow obstruction. Industrial plants and municipal corporations with high-solids distribution networks prioritize this configuration for operational reliability.
- Mechanical:Displacement and velocity designs persist in cost-sensitive retrofit programs where existing AMR infrastructure limits upgrade budgets.
- Acoustic Wave:Doppler-shift measurement targets leak detection specialization with sensitivity to low-flow conditions.
- Thermal:Heat-transfer principles suit niche applications in research centers requiring extreme precision at low flow rates.
- Multi-Jet:Multiple inlet impeller designs balance accuracy against unit cost for mid-tier municipal deployments.
Mechanical meters sit at the top of the volume ranking, with ultrasonic configurations climbing the fastest.
Technology:
Communication protocol selection locks utilities into 15-20 year infrastructure commitments, with RF module integration complexity and cellular spectrum allocation creating divergent cost structures across deployment geographies.
- NB-IoT:Licensed cellular spectrum enables fifteen-minute interval data transmission without proprietary network buildout. Dense urban cores in China leverage MIIT-coordinated spectrum allocation for accelerated vendor rollout timelines.
- IoT:Broad sensor integration platforms extend beyond metering into pressure monitoring and quality sensing. Water utilities pursuing AMI network expansion prioritize this architecture for future-proofing against regulatory escalation.
- RF Communication:Proprietary mesh networks persist in suburban districts where cellular coverage gaps increase NB-IoT deployment costs.
- AMR:Drive-by and walk-by reading systems face replacement pressure from EPA leak detection mandates that require real-time transmission.
- Wireless M-Bus:European district-metering deployments demand extensive certification depth that bottlenecks vendor qualification.
- PLC:Power-line carrier transmission suits industrial plants with captive electrical infrastructure and electromagnetic-hardened environments.
AMR retains the largest installed base, though NB-IoT gains share fastest where cellular infrastructure already blankets target geographies.
Application:
Margin concentration varies inversely with volume scale, with multi-point submetering requirements in commercial and institutional segments commanding pricing premiums over standardized residential deployments.
- Residential:Single-point measurement dominates unit volume with standardized fifteen-minute interval logging. Germany's municipal utilities accelerate deployments under EU Green Deal water efficiency mandates that compress procurement cycles.
- Commercial Facilities:Multi-tenant submetering and cooling tower monitoring create specialized configuration demand. Property management firms concentrate procurement here for conservation pricing frameworks and tenant billing accuracy.
- Public Utilities:District-level master metering and distribution network monitoring require integration with SCADA systems.
- Educational Institutions:Campus-wide sustainability reporting drives adoption for LEED certification maintenance.
- Hospitality Sector:Guest billing precision and leak prevention in high-rise configurations shape specification requirements.
- Government Buildings:Federal procurement standards and public accountability mandates accelerate smart meter mandates.
Residential applications anchor volume rankings, with commercial facilities expanding most quickly on submetering specialization.
End User:
Procurement authority concentration among large municipal utilities compresses sales cycles and unbundles hardware from analytics subscriptions, reshaping vendor revenue models toward recurring software streams.
- Municipal Corporations:Consolidated purchasing power enables transparent lifecycle cost evaluation under EU Green Deal frameworks. These entities separate AMI infrastructure from billing system upgrades that were historically staggered over decades.
- Water Utilities:Regulatory compliance pressure from EPA Lead and Copper Rule Revisions mandates real-time leak detection infrastructure. American utilities face steepest cost escalation where legacy AMR systems cannot satisfy enhanced visibility requirements.
- Property Management Firms:Tenant submetering and conservation pricing create demand for interval data logging capabilities.
- Industrial Plants:Process water measurement and effluent monitoring require hardened configurations with extreme temperature tolerance.
- Research Centers:Calibration-grade accuracy and thermal measurement precision suit experimental water flow studies.
Water utilities occupy the top volume position, with municipal corporations gaining procurement momentum fastest under compressed regulatory timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal water utilities anchor deployment momentum under EU Green Deal water efficiency mandates, compressing procurement cycles that historically stretched across decades. The country's district-metering expertise and wireless M-Bus certification depth create qualification bottlenecks for new entrants.
United States
California's drought-prone urban districts concentrate ultrasonic meter procurement for extended calibration intervals. EPA Lead and Copper Rule Revisions mandate enhanced leak detection infrastructure that legacy AMR systems cannot satisfy. Texas utilities face similar compliance pressure, driving consolidation around vendors with integrated real-time monitoring capabilities.
China
MIIT-coordinated NB-IoT spectrum allocation accelerates domestic vendor rollout timelines in dense urban cores. NMPA metering accuracy standards compress certification friction for new entrants. Shanghai and Beijing municipal utilities lead deployment scale, leveraging existing cellular infrastructure to avoid proprietary network buildout costs.
France
EMA electromagnetic compatibility frameworks enforce product validation requirements that reshape development timelines. Paris metropolitan utilities unbundle hardware acquisition from data analytics subscriptions under transparent lifecycle cost evaluation. Auvergne-Rhône-Alpes water authorities prioritize AMI network expansion over staggered billing system upgrades.
Japan
METI industrial standards coordinate with utility procurement frameworks to extend meter replacement intervals. Tokyo metropolitan waterworks pursue conservation pricing structures enabled by fifteen-minute interval data logging. Osaka-Kansai industrial corridors demand hardened configurations for process water measurement in manufacturing facilities.
Global Smart Water Meter Market Competitive Landscape
Global majors compete with regional champions across certification depth and wireless protocol expertise, creating a tiered structure where RF module integration capabilities separate margin-sustaining vendors from contract-dependent competitors. European specialists dominate district-metering deployments through multi-year installation track records, while North American players anchor utility relationships through in-house component production. Three archetypes define positioning: integrated technology developers with captive RF supply, specialized ultrasonic R&D houses, and scale-driven mechanical meter converters. Dominant competitive moves include backward integration into communication module production and strategic partnerships for AMI software analytics.
Within the integrated technology tier, Itron Inc. and Honeywell International Inc. exemplify vendors with in-house RF module production sustaining margin control across North American utility contracts. Badger Meter Inc. occupies a position among specialized developers, representing the ultrasonic R&D archetype with zero-moving-part measurement configurations. Kamstrup A/S anchors the European specialist category, sitting within the district-metering expertise segment where wireless M-Bus certification depth creates vendor qualification barriers.
| Leading Market Players |
|---|
| Itron Inc. |
| Xylem (Sensus) |
| Badger Meter Inc. |
| Landis+Gyr |
| Kamstrup A/S |
| Diehl Stiftung & Co. KG |
| Neptune Technology Group Inc. |
| Honeywell International Inc. |
| ZENNER International GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Specialized polymer resin price indices cascade through smart water meter manufacturing tiers, compressing margins for housing fabricators while amplifying pricing power for integrated vendors with captive RF module production. Brass casting displacement by composite polymers recalibrates unit economics across procurement categories, with California utilities and German municipal buyers facing divergent landed cost structures.
Pricing Analysis
Input-cost pass-through from electromagnetic compatibility certification and wireless M-Bus validation expenses stratifies vendor tiers. Three-tier pricing structure across premium, standard, and economy levels separates ultrasonic configurations with fifteen-minute interval logging from mechanical retrofit units. Pricing pressure stems from raw material volatility in specialized polymer resins. Municipal corporations exhibit lowest price sensitivity due to EU Green Deal lifecycle cost frameworks, while cost-sensitive retrofit programs in emerging markets face steepest budget constraints.
Supply Chain Analysis
Container freight rates from Chinese component hubs to European district-metering sites and North American utility depots amplify working capital requirements for non-integrated assemblers. Manufacturing concentrates in China, Germany, and the United States, with RF communication modules and ultrasonic transducers drawing from semiconductor fabrication networks. Single-source vulnerability in NB-IoT chipset supply creates bottleneck exposure. Distribution runs through municipal procurement departments that unbundle hardware from analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's MIIT-coordinated NB-IoT deployment timelines and Europe's wireless M-Bus certification bottlenecks creates divergent capital efficiency profiles for vendors with multi-region manufacturing footprints.
For Market Incumbents: Acquire ultrasonic R&D pipelines and district-metering installation track records to defend against specialized European challengers. Backward integration into RF module production sustains margin control as municipal procurement unbundles hardware from software subscriptions. Certification depth in EMA electromagnetic compatibility frameworks creates switching costs that delay competitive erosion. For New Entrants and Emerging Players: Enter via commercial facilities submetering segments where multi-point measurement requirements command pricing premiums absent in standardized residential deployments. Target drought-prone urban districts in California with ultrasonic configurations emphasizing extended calibration intervals. Pursue metering-as-a-service revenue models that bypass capital-intensive AMI infrastructure buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated technology developers possessing captive RF supply and established utility billing system integrations. Long-term viability hinges on protocol longevity alignment with fifteen-to-twenty-year municipal procurement cycles. Monitor EPA enforcement patterns on Lead and Copper Rule Revisions as inflection indicator for American utility replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RF Module Production | In-house component supply shields margins from semiconductor procurement volatility affecting contract-dependent competitors. |
| Wireless M-Bus Certification Investment | EMA validation depth creates vendor qualification barriers that bottleneck European district-metering competition. |
| AMI Software Analytics Partnership | Recurring revenue streams offset hardware margin compression as German utilities unbundle procurement categories. |
| Ultrasonic R&D Pipeline Expansion | Zero-moving-part configurations extend calibration intervals for California drought-prone urban district requirements. |
| NB-IoT Platform Standardization | Cellular spectrum alignment with MIIT-coordinated standards accelerates rollout timelines in Chinese dense urban cores. |
Research Methodology
Coverage spans Germany, the United States, China, France, and Japan, with primary inputs from each market validating cross-regional patterns. Utility planning officers, municipal procurement managers, AMI network engineers, and RF module procurement leads contributed operational data. Secondary sources included EPA regulatory filings, EMA electromagnetic compatibility registers, MIIT spectrum allocation notices, and utility capital expenditure disclosures. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows.
Granularity-level modeling distinguished product types, communication technologies, application segments, and end-user categories across national regulatory clusters. CAGRs derived from fitted growth curves applied to utility replacement cycles and regulatory compliance deadlines. Forecast inputs incorporated NB-IoT infrastructure buildout timelines, EU Green Deal procurement acceleration patterns, and ultrasonic sensor adoption curves in drought-affected regions.
Inputs from municipal utility planning departments and regulatory filing databases were available through the study window; gaps in proprietary AMI software pricing introduce uncertainty bands around recurring revenue projections. Forecasts reflect documented assumptions on protocol longevity and certification timeline stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Digital Water Meters Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Watt Meter Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Smart Utility Solutions Market