
 United States (US) Residential Smart Meters Market | 2026-2036
United States (US) Residential Smart Meters Market Size, Share, and Industry Trends Forecast 2026-2036
United States (US) Residential Smart Meters Market Insights
Aftermarket service revenue is rewriting value capture in the US residential smart meter landscape. Itron Inc. leverages its software platform to extend recurring revenue beyond hardware installation. Landis+Gyr anchors its position through deep utility relationships and AMI system integration. Honeywell International Inc. competes by embedding cybersecurity protocols into its meter firmware, differentiating on data protection.
United States residential smart meters are two-way communication devices that measure electricity, gas, or water consumption at 15-minute or shorter intervals and transmit data via RF mesh, cellular, or power-line carrier networks to utility back-office systems. These meters enable time-of-use pricing, outage detection, and remote disconnect functions that underpin modern grid operations. Cellular meters command premium positioning where rural infrastructure lacks mesh density, while AMI technology leads deployment volume as utilities phase out one-way AMR systems. Zigbee and Z-Wave meters serve niche home energy management integrations, though their growth trails cellular and Wi-Fi alternatives in utility-scale rollouts.
FERC Order 2222, state public utility commission mandates, and IEEE 2030.5 interoperability standards collectively shape product certification requirements and procurement timelines across US jurisdictions. The EPA's power plant emissions rules indirectly accelerate meter replacement by pressuring utilities to enable granular demand response. Stakeholders must weigh module upgrade paths against full meter replacement as communication standards evolve and cybersecurity frameworks tighten.
Market Dynamics
FERC Order 2222 and state-level decarbonization mandates are compressing AMI replacement cycles as utilities face dual pressure to modernize aging infrastructure and enable granular demand response for distributed energy resource integration.
Growth Catalysts
- Grid Modernization Mandates:Federal infrastructure funding and state renewable portfolio standards require two-way communication capabilities that only AMI systems deliver, forcing accelerated meter swaps.
- California:The state's 2045 carbon neutrality target and aggressive building electrification timeline create concentrated procurement pull for advanced metering infrastructure with remote disconnect functions.
- Edge Computing Integration:On-meter processing capabilities enable real-time outage detection and voltage optimization, reducing truck rolls and improving grid reliability metrics that regulators track.
Market Restraints
- Semiconductor Supply Concentration:RF transceiver and power management chip sourcing remains concentrated among Asian foundries, creating procurement bottlenecks for domestic meter assembly.
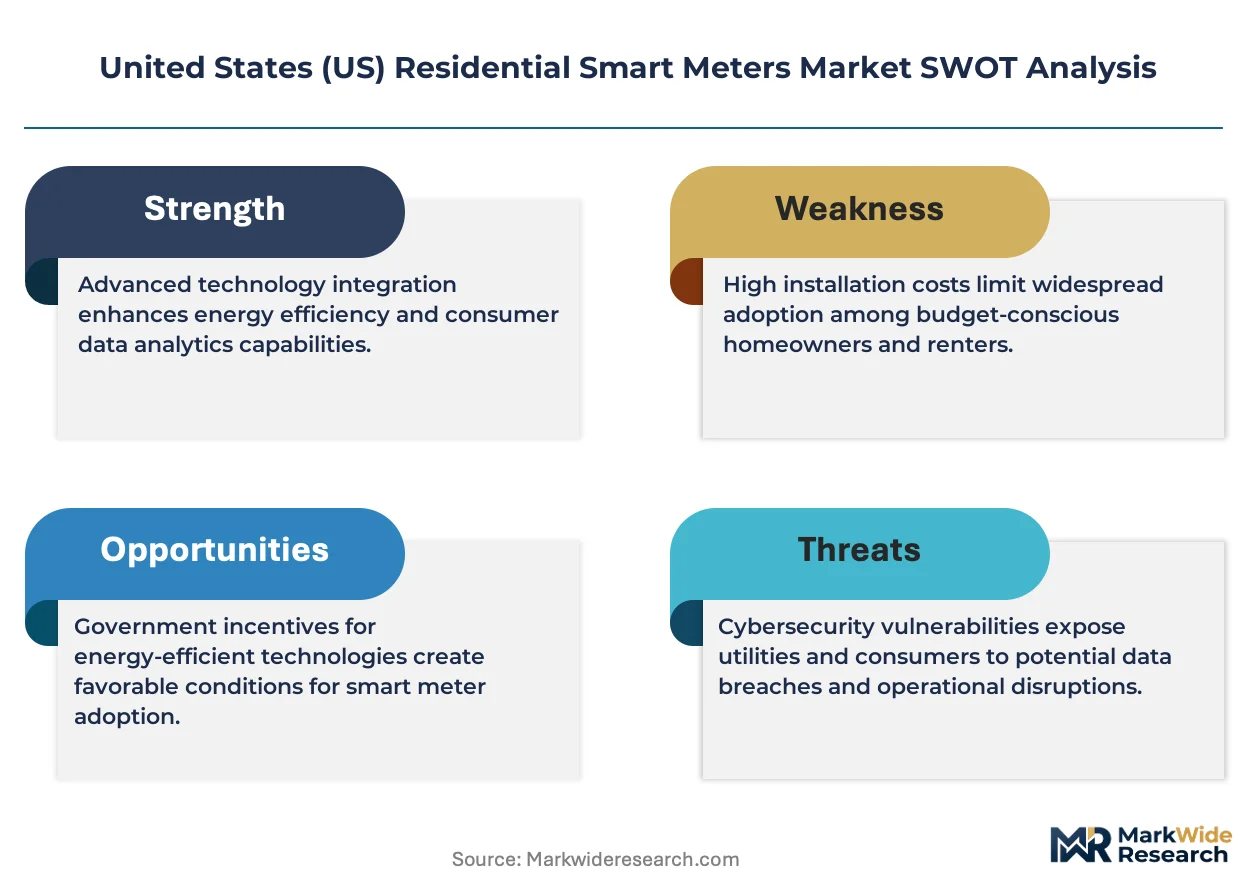
- Cybersecurity Compliance Costs:NERC CIP standards and state-level data protection requirements impose certification overhead that extends procurement timelines and raises total cost of ownership.
- Mesh Network Limitations:Rural infrastructure gaps in the Mountain West and Great Plains force utilities toward premium cellular modules where RF density proves insufficient.
Strategic Opportunities
- Texas Multi-Family Housing:Underpenetrated apartment and condominium segments present white space as municipal utilities and retail electric providers compete for tenant data access.
- Home Energy Management Convergence:Zigbee and Z-Wave module integration with thermostat and solar inverter ecosystems creates stickier utility-customer relationships beyond basic billing.
- Inflation Reduction Act Incentives:Grid resilience funding streams reward utilities that deploy meters with integrated voltage sensors and transformer monitoring capabilities.
Industry Challenges
- Firmware Engineering Talent:Scarce embedded systems developers with RF protocol expertise constrain product roadmap velocity for meter OEMs competing on feature cadence.
- AMI-AMR Transition Complexity:Utilities operating hybrid fleets face integration friction between legacy one-way systems and modern two-way platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States (US) Residential Smart Meters Market |
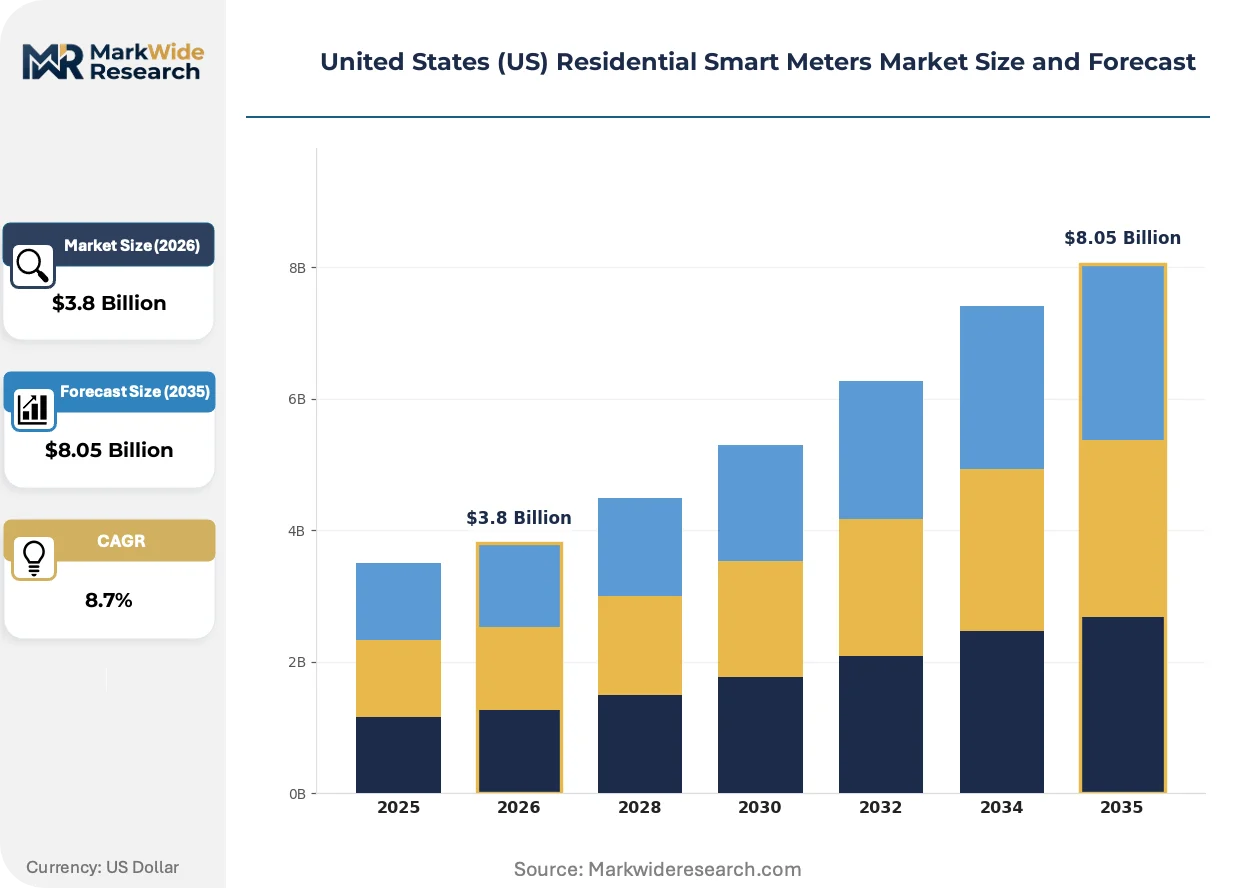
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Meters, Zigbee Meters, Z-Wave Meters, Cellular Meters Technology: AMI, AMR, IoT-based, Digital End User: Homeowners, Property Managers, Builders, Utility Companies Installation Type: Indoor, Outdoor, Wall-mounted, Portable |
| Companies Covered | Itron Inc., Landis+Gyr, Honeywell International Inc., Badger Meter Inc., General Electric Company, Sensus (Xylem Inc.), Kamstrup, Mueller Systems LLC, Aclara Technologies LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States (US) Residential Smart Meters Market Trends and Innovations
Communication module evolution and software-defined meter architectures are compressing hardware replacement cycles while opening recurring revenue streams that reshape vendor economics.
Cellular LTE-M and NB-IoT modules are digitizing rural and suburban deployment economics where RF mesh density proves uneconomical. Municipal utilities in the Mountain West and Great Plains are adopting these protocols to bypass infrastructure build-out, collapsing the historical urban-rural deployment gap and forcing mesh-centric vendors to diversify module portfolios.
FERC Order 2222 aggregation rules and IEEE 2030.5 interoperability mandates are tightening certification requirements for distributed energy resource integration. Meter vendors must now validate seamless communication with solar inverters, battery storage systems, and electric vehicle chargers, compressing product development timelines for utilities targeting 2030 decarbonization milestones.
Aftermarket software subscriptions are displacing upfront hardware margins as the primary value capture mechanism. Itron and Landis+Gyr are unbundling analytics and demand response platforms from meter sales, while smaller utilities in the Southeast and Midwest resist this shift, preferring capital expenditure treatment over operational expenditure models that complicate rate case filings.
United States (US) Residential Smart Meters Market Segmentation
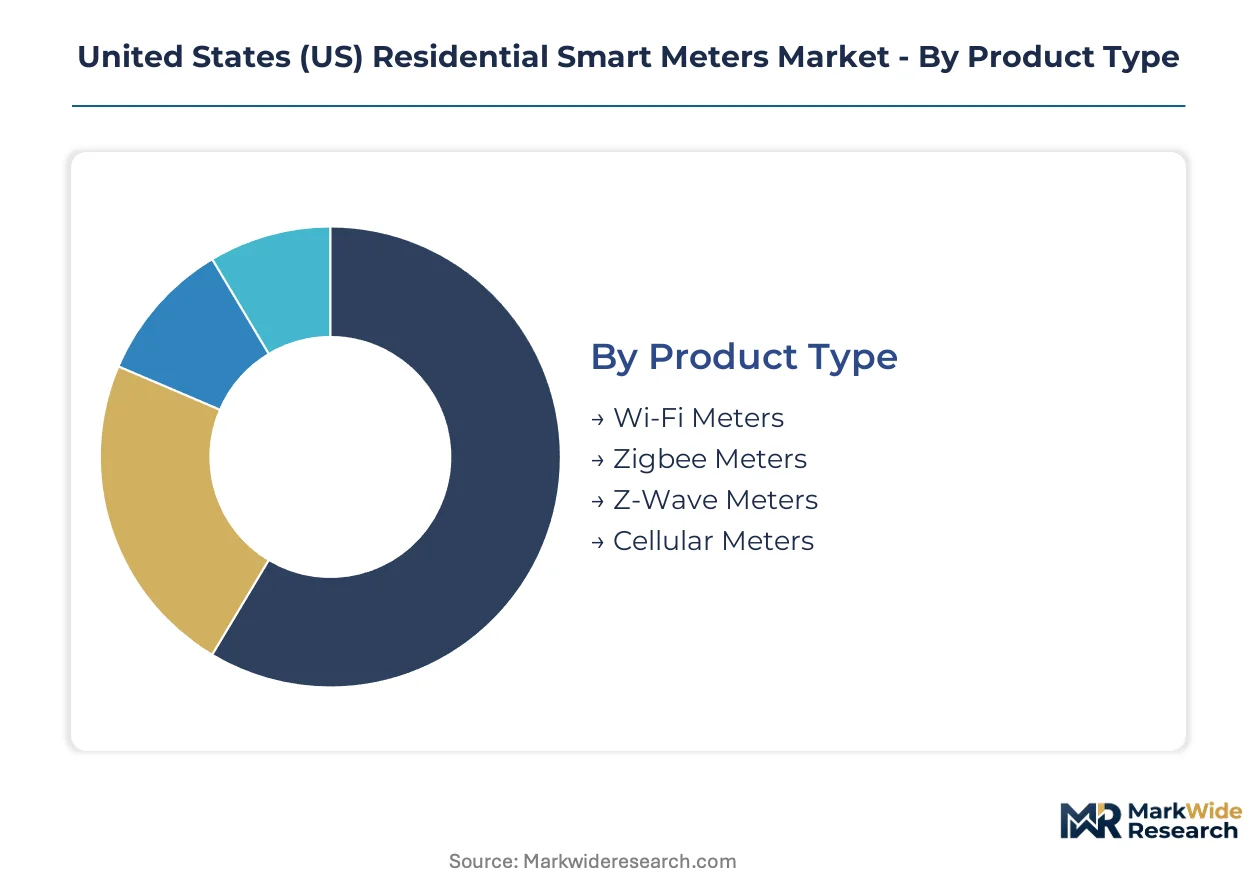
Smart meter procurement patterns diverge sharply across communication protocols, technology generations, and customer archetypes. Understanding these fault lines reveals where hardware margins concentrate versus where software and service revenue opportunities emerge.
Product Type:
Communication protocol determines infrastructure requirements, deployment economics, and integration complexity for utility back-office systems.
- Cellular Meters:LTE-M and NB-IoT modules transmit consumption data over carrier networks, eliminating mesh infrastructure build-out. Utilities in Texas and the Mountain West favor these units where RF density proves uneconomical, though recurring data costs compress long-term margins.
- Wi-Fi Meters:These units leverage existing residential broadband for backhaul, reducing utility-owned infrastructure. California municipal utilities deploy Wi-Fi variants in dense urban corridors where household internet penetration exceeds ninety percent, though cybersecurity compliance adds certification overhead.
- Zigbee Meters:Low-power mesh protocol enabling home energy management ecosystem integration.
- Z-Wave Meters:Sub-GHz frequency alternative for residential automation interoperability with thermostats and inverters.
Cellular meters hold installed capacity. Wi-Fi meters are rotating up the share rankings.
Technology:
Architecture maturity separates capital-intensive AMI replacements from legacy AMR maintenance and emerging IoT-native platforms.
- AMI:Two-way Advanced Metering Infrastructure enables remote disconnect, time-of-use pricing, and outage detection through RF mesh or cellular backhaul. FERC Order 2222 and state decarbonization mandates in New York and California force accelerated AMI swaps as utilities phase out one-way systems.
- IoT-based:Cloud-native architectures with over-the-air firmware updates and edge computing capabilities. Southwest utilities pilot these platforms for real-time voltage optimization and transformer monitoring, though NERC CIP compliance timelines lag hardware availability.
- AMR:One-way Automated Meter Reading systems facing replacement pressure from regulators demanding demand response enablement.
- Digital:Basic electronic meters without communication modules, serving cost-sensitive rural cooperatives.
AMI dominates current procurement volume. IoT-based platforms are climbing the fastest as greenfield deployments accelerate.
End User:
Customer type dictates purchasing authority, technical specifications, and contract structure across the deployment lifecycle.
- Utility Companies:Investor-owned utilities and municipal power authorities drive volume procurement through multi-year AMI rollout programs. Texas utilities and California IOUs specify integrated voltage sensors and cybersecurity-hardened firmware to capture Inflation Reduction Act grid resilience incentives.
- Property Managers:Multi-family housing operators in Texas and Florida seek submetering solutions for tenant billing transparency, creating white space as retail electric providers compete for data access.
- Homeowners:Individual purchasers through energy efficiency programs or solar installer partnerships.
- Builders:New construction developers pre-wiring homes for smart grid readiness.
Utility Companies anchor procurement volume. Property Managers are gaining share fastest as multi-family electrification timelines tighten.
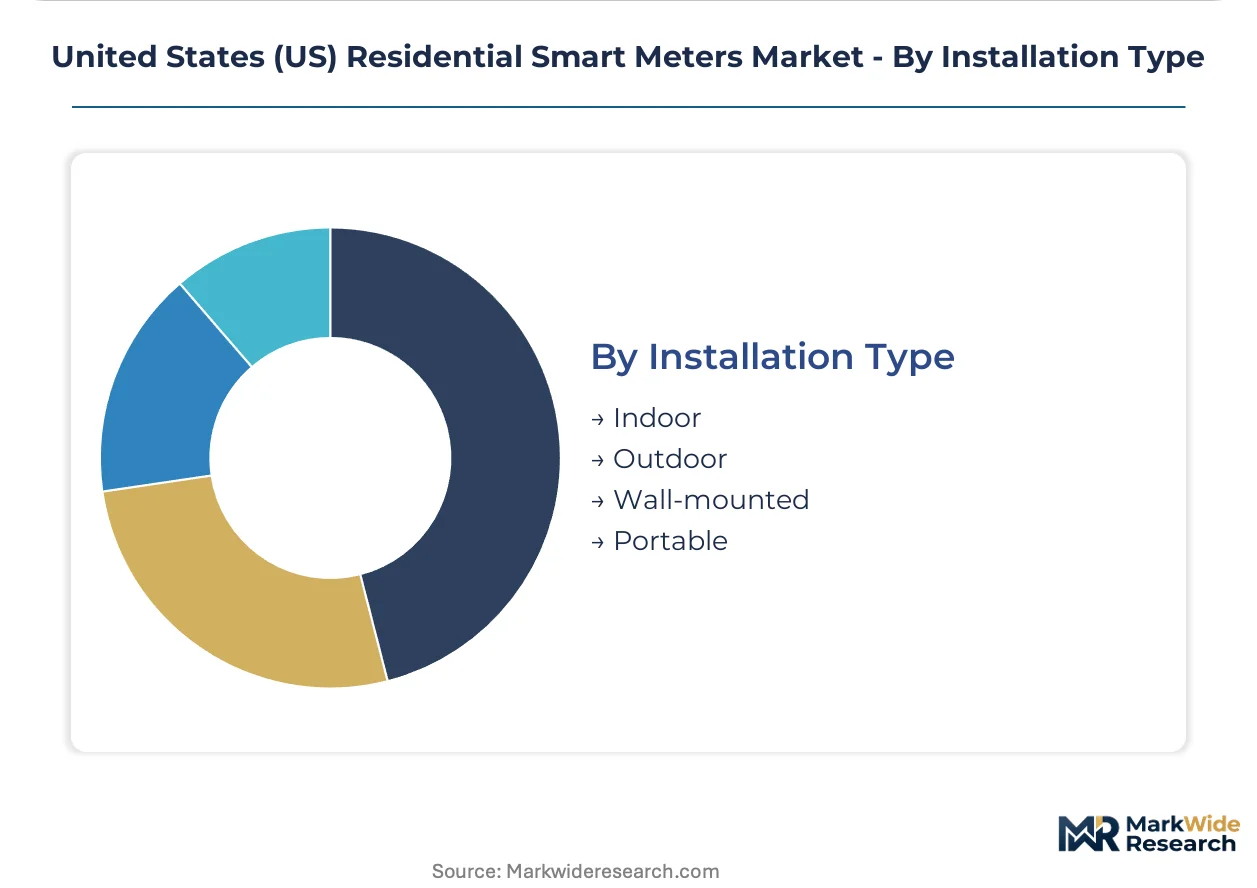
Installation Type:
Physical mounting configuration shapes hardware specifications, labor costs, and exposure to environmental degradation.
- Outdoor:NEMA-rated enclosures withstand temperature extremes, moisture, and UV exposure for utility pole or pedestal mounting. Arizona and Nevada utilities specify these variants for desert climate resilience, with IP68 ingress protection becoming standard for new procurements.
- Wall-mounted:Compact form factors for residential exterior wall installation with tamper-evident sealing. Northeast utilities favor these for urban density constraints and basement-to-exterior conduit runs in older housing stock.
- Indoor:Basement or utility closet placement in regions with severe weather exposure.
- Portable:Temporary deployment for construction sites or disaster recovery scenarios.
Outdoor units hold installed capacity. Wall-mounted configurations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across US states, with California and New York utilities absorbing premium pricing for advanced AMI features while rural cooperatives in the Mountain West resist operational expenditure shifts. Price-sensitive buyers cluster in the Southeast and Midwest where municipal utilities favor capital expenditure treatment and extended hardware lifecycles. The Southwest and Texas markets split between cost-conscious retail electric providers and aggressive IOUs chasing federal grid resilience incentives.
California
The state's 2045 carbon neutrality mandate and building electrification timeline drive concentrated procurement of AMI meters with remote disconnect and time-of-use pricing capabilities. California Public Utilities Commission mandates require utilities to enable granular demand response for distributed solar and battery storage integration. Southern California Edison and Pacific Gas & Electric anchor deployment volume in Los Angeles Basin and Bay Area corridors where urban density favors Wi-Fi backhaul configurations.
Texas
Retail electric provider competition and ERCOT grid independence create bifurcated demand between premium cellular meters for rural cooperatives and cost-optimized mesh deployments for municipal utilities in Dallas-Fort Worth and Houston metros. The Public Utility Commission of Texas has accelerated submetering requirements for multi-family housing, opening white space in Austin and San Antonio apartment markets. Texas utilities lead national adoption of integrated voltage sensors to capture Inflation Reduction Act resilience funding.
New York
Climate Leadership and Community Protection Act targets compress AMI replacement cycles as Consolidated Edison and New York State Electric & Gas face regulatory pressure to phase out one-way AMR systems by 2030. The New York Public Service Commission mandates interoperability standards that favor vendors with IEEE 2030.5 certification. Deployment concentrates in New York City metro and Hudson Valley corridors where ConEd's advanced metering infrastructure program targets 4.8 million endpoints.
Florida
Hurricane resilience requirements and municipal utility cost constraints create unique demand for outdoor-rated NEMA enclosures with IP68 ingress protection. The Florida Public Service Commission has stopped short of mandating AMI timelines, leaving investor-owned utilities Florida Power & Light and Duke Energy Florida to self-direct modernization pace. Tampa and Orlando metros see emerging interest in Zigbee-enabled meters for home energy management integration with solar inverter ecosystems.
Mountain West
Rural infrastructure gaps and low population density force utilities toward premium cellular LTE-M and NB-IoT modules where RF mesh build-out proves uneconomical. Colorado and Arizona regulators have prioritized grid hardening over smart meter mandates, creating procurement driven by federal infrastructure grants rather than state decarbonization deadlines. Municipal utilities in Phoenix and Denver suburbs pilot edge-computing meters for real-time voltage optimization and transformer monitoring.
United States (US) Residential Smart Meters Market Competitive Landscape
Capability concentration sits with integrated AMI platform vendors; scale advantage sits with diversified industrial conglomerates with captive utility relationships. The market structures around three tiers: full-stack AMI providers with software unbundling strategies, hardware-focused OEMs competing on module flexibility, and niche specialists in submetering or home energy management integration. Consolidation pressure intensifies as firmware engineering talent scarcity raises barriers for mid-tier players. Dominant competitive moves include strategic partnerships for cellular module sourcing and portfolio diversification into grid edge analytics.
Within the integrated platform tier, Itron Inc. and Landis+Gyr exemplify vendors unbundling software subscriptions from hardware sales to capture recurring revenue. Honeywell International Inc. anchors the industrial conglomerate segment, leveraging cybersecurity-hardened firmware as differentiation. These three companies represent divergent strategic postures: software-led value capture, deep utility relationship anchoring, and embedded security positioning.
| Leading Market Players |
|---|
| Itron Inc. |
| Landis+Gyr |
| Honeywell International Inc. |
| Badger Meter Inc. |
| General Electric Company |
| Sensus (Xylem Inc.) |
| Kamstrup |
| Mueller Systems LLC |
| Aclara Technologies LLC |
| Others |
Pricing and Supply Chain Analysis
The Port of Long Beach container corridor shapes cost dynamics across the US residential smart meter supply chain, with freight volatility amplifying price differentiation between cellular module tiers and pressuring utilities toward extended procurement cycles. Asian foundry concentration for RF transceivers and power management chips concentrates upstream pricing power, while downstream buyers fragment across cost-sensitive rural cooperatives and premium-seeking IOUs in decarbonization-mandated states.
Pricing Analysis
Aftermarket software subscriptions now drive lifetime value capture, with vendors unbundling analytics platforms from hardware sales to secure recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with NERC CIP-compliant firmware commanding substantial premiums. Cost compression in economy-tier mesh deployments is intensifying because municipal utilities resist operational expenditure shifts. Rural cooperatives in the Mountain West exhibit highest price sensitivity, while California IOUs absorbing integrated voltage sensor premiums show lowest.
Supply Chain Analysis
Extended payment terms from Taiwanese and South Korean foundries now structure working capital requirements for domestic meter assemblers facing procurement bottlenecks. RF transceiver, power management IC, and cellular modem production draws from concentrated Asian manufacturing hubs. Single-source vulnerability in advanced semiconductor nodes threatens delivery timelines for edge-computing meter platforms. Distribution runs through direct utility procurement contracts and authorized distributor networks serving municipal and cooperative segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US residential smart meter market is in cyclical recovery, with federal grid modernization funding and state decarbonization mandates driving replacement wave timing.
For Market Incumbents: Harden firmware engineering capabilities through captive development centers or strategic acquisitions, as embedded systems talent scarcity constrains product roadmap velocity. Deepen utility relationship anchoring by pre-certifying IEEE 2030.5 interoperability for distributed energy resource integration, defending against cloud-native IoT platform entrants.
For New Entrants and Emerging Players: Texas multi-family housing submetering presents underpenetrated white space, with Public Utility Commission mandates accelerating apartment and condominium procurement. Target municipal utilities in the Southeast resisting software subscription models, offering capital expenditure-friendly hardware bundles with extended warranty terms as entry wedge.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive smart meter divisions lacking standalone software platforms. Five-to-ten year viability hinges on recurring revenue transition completion. Monitor cellular module cost curves as inflection indicator for rural deployment economics and competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Platform Unbundling | Itron and Landis+Gyr are displacing upfront hardware margins with analytics subscriptions. |
| Cellular Module Portfolio Diversification | Mesh-centric vendors must add LTE-M and NB-IoT variants to serve Mountain West utilities. |
| Cybersecurity Certification Investment | Honeywell's NERC CIP-hardened firmware commands premium positioning in procurement. |
| Multi-Family Submetering Expansion | Texas apartment markets open white space as retail electric providers compete for tenant data. |
| Edge Computing Capability Integration | On-meter processing enables real-time voltage optimization, capturing IRA resilience funding. |
Research Methodology
The analysis maps cellular, Wi-Fi, Zigbee, and Z-Wave protocol segments, each validated through utility planning officers, AMI program directors, meter OEM product managers, and state regulatory commission staff. Primary fieldwork combined with secondary sources including FERC filings, EIA electricity sales data, state public utility commission dockets, and IEEE standards documentation. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending projections.
Assumptions held federal grid modernization funding and state renewable portfolio standards fixed across the analysis window, while cellular module cost curves and semiconductor supply availability were treated as variable inputs. Segmentation dimensions modeled include communication protocol, technology generation, end user type, and installation configuration. CAGRs derived from utility capital expenditure pipeline analysis and replacement cycle compression factors. Forecast inputs incorporated NERC CIP compliance timelines and IEEE 2030.5 certification adoption curves.
Practitioners should monitor FERC Order 2222 implementation pace and cellular carrier data pricing volatility for early signals of demand or margin deviation. Forecasts reflect these documented assumptions; tariff escalation on semiconductor imports or accelerated state decarbonization deadlines would prompt revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Solar Meter Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Home Energy Monitor Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Watt Meter Market
Smart Meters
Power Metering Market
Smart Meters
Europe Smart Meters Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Smart Meters Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Smart Meter Battery Market
Smart Meters
AMI Smart Water Meter Market