
 Interspinous Process Decompression Devices Market | 2026-2036
Interspinous Process Decompression Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Interspinous Process Decompression Devices Market Outlook
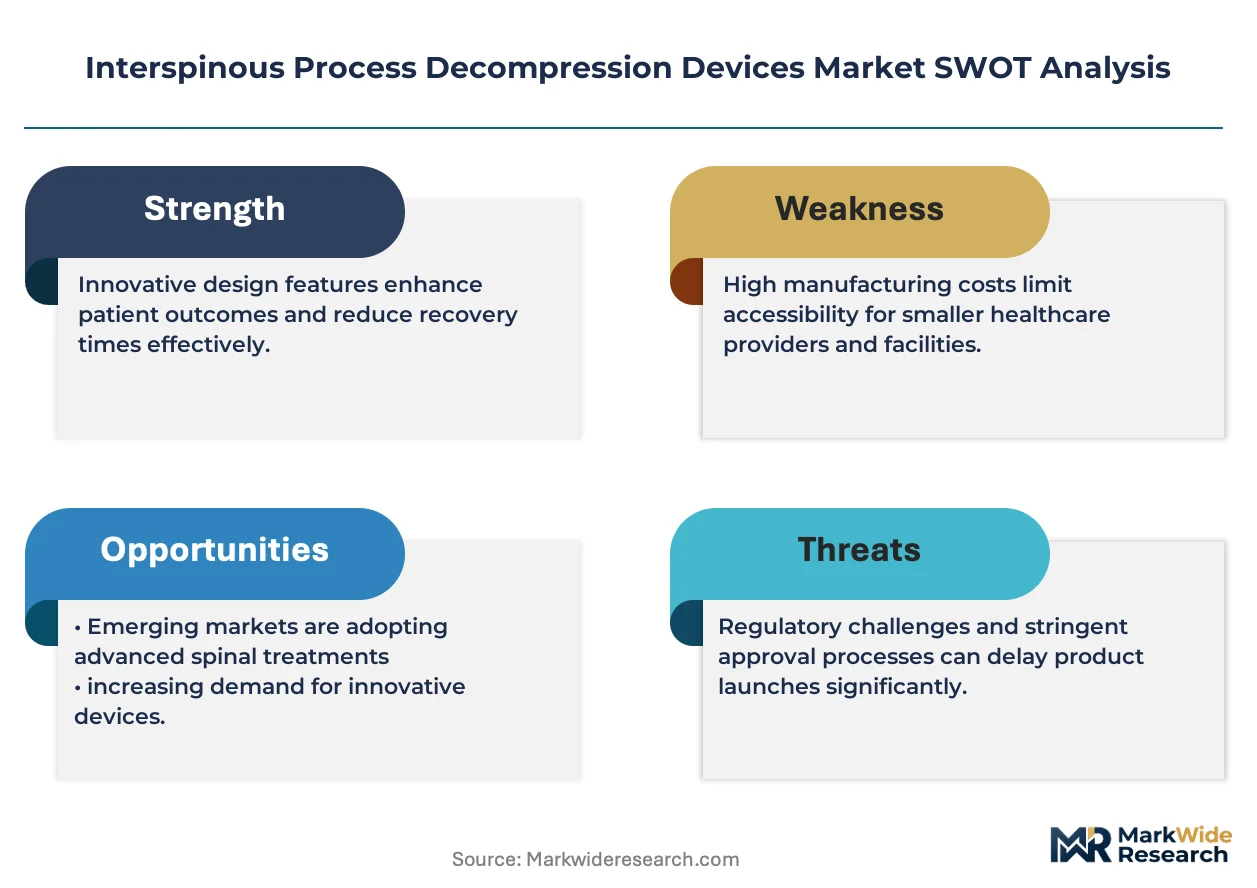
The divergence between premium and commodity tiers in interspinous process decompression devices is hardening around material sophistication and surgical integration depth. Medtronic leverages its integrated spine portfolio to bundle decompression hardware with navigation and biologics, sustaining higher attach rates across hospital systems. Globus Medical anchors its position through robotics-compatible spacer designs that compete directly in the minimally invasive surgery channel. NuVasive differentiates via specialized lateral access training programs that lock in surgeon loyalty beyond the device itself.
Interspinous process decompression devices are mechanical implants inserted between adjacent spinous processes to limit pathological extension and unload the neural elements, typically constructed from titanium alloys or PEEK polymer with titanium coating to balance radiolucency and osseointegration; their primary purpose is to provide dynamic stabilization as an alternative to laminectomy or fusion in lumbar spinal stenosis patients. Static devices dominate current procedural volumes due to established reimbursement codes and simpler surgical learning curves, while expandable devices represent the fastest-growing product category as surgeons seek intraoperative adjustability to match variable anatomy. Minimally invasive surgery technology commands the deepest margin pools because instrument and navigation bundling amplifies per-procedure revenue beyond the implant itself.
The FDA's 510(k) pathway governs US market entry for these devices, while the EU Medical Device Regulation imposes stricter clinical evidence requirements that reshape competitive timelines for European access. Japan's PMDA maintains distinct biocompatibility testing protocols that filter which manufacturers can sustain dual-hemisphere registration costs. Stakeholders must monitor how CMS reimbursement decisions for outpatient interspinous procedures reshape site-of-service economics and device selection criteria.
Market Dynamics
Site-of-service economics is compressing device selection criteria as CMS reimbursement alignment for outpatient interspinous procedures accelerates volume migration from inpatient settings.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's evolving clearance framework for spinal implants compresses product entry timelines, enabling faster commercialization of expandable device variants.
- Ambulatory surgical center expansion:Outpatient spine procedures gain procedural volume as reimbursement codes align with minimally invasive alternatives, pulling device demand toward ASC-distributed models.
- PEEK-titanium hybrid materials:Advanced polymer-ceramic composites balance radiolucency with osseointegration, expanding surgeon adoption in dynamic stabilization cases.
Market Restraints
- EU MDR clinical evidence burden:The EU Medical Device Regulation imposes stricter documentation requirements that reshape competitive timelines and filter smaller manufacturers from European access.
- Titanium alloy supply concentration:Raw material sourcing clusters in select Asian refining jurisdictions create input cost volatility and qualification bottlenecks for device fabricators.
- Adjacent fusion technology substitution:Motion-preserving total disc replacement systems compete for the same lumbar stenosis patient cohort, capping decompression device addressable share.
Strategic Opportunities
- Japan PMDA biocompatibility protocols:Manufacturers sustaining dual-hemisphere registration capabilities capture premium positioning in Asia-Pacific's aging demographic markets.
- Robotics-integrated spacer platforms:Convergence of navigation systems with expandable device designs opens minimally invasive surgery channel penetration beyond traditional open approaches.
- Biologics bundling models:Hospital systems seeking cost consolidation create attach-rate expansion for decompression hardware paired with bone graft substitutes.
Industry Challenges
- Surgeon training program scalability:Specialized lateral access technique certification creates bottlenecks in expanding procedural adoption beyond early-adopter centers.
- Legacy EHR integration friction:Device tracking and outcomes registry connectivity requires capital-intensive IT infrastructure upgrades for ASC network operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interspinous Process Decompression Devices Market |
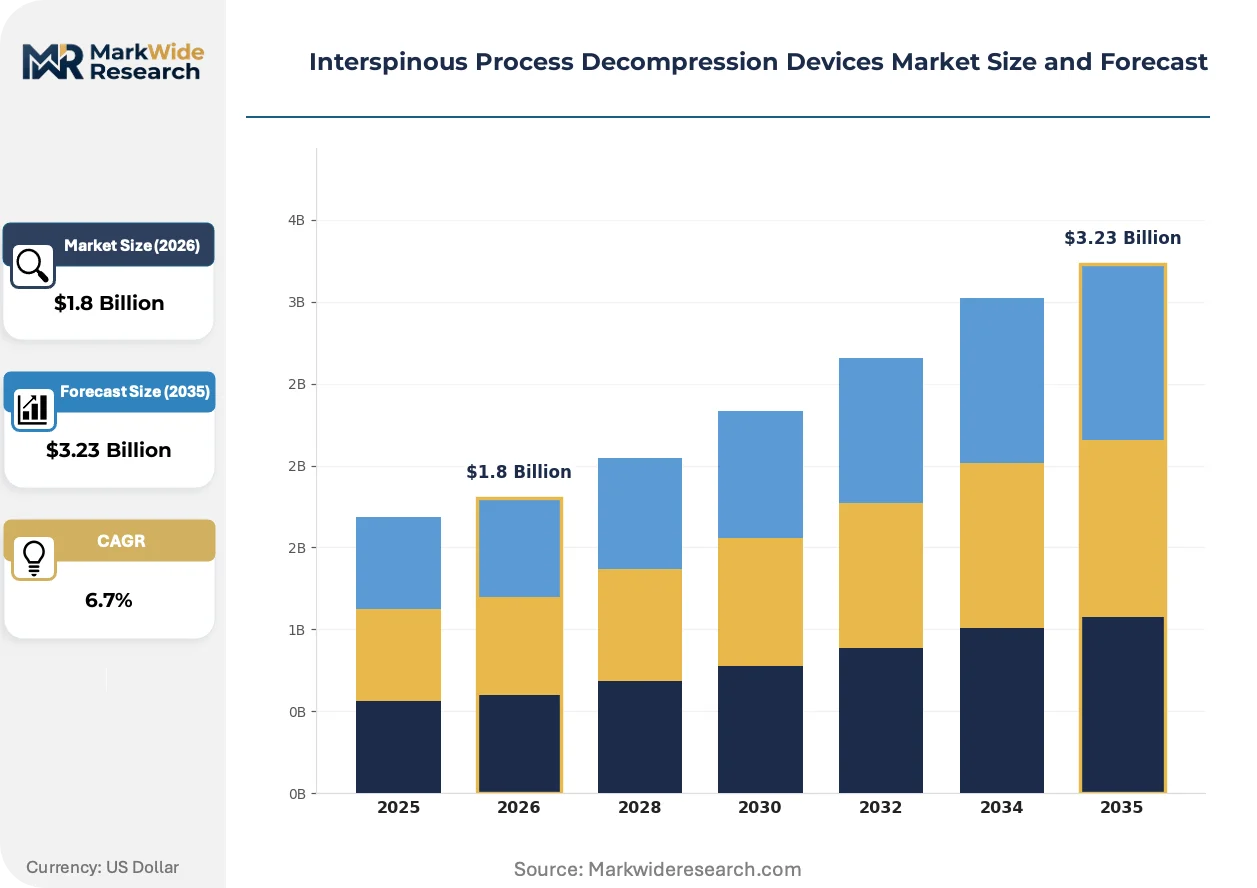
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Devices, Dynamic Devices, Interspinous Spacers, Expandable Devices End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Technology: Minimally Invasive Surgery, Traditional Surgery, Robotic Surgery, Imaging Guidance Application: Spinal Stenosis, Degenerative Disc Disease, Herniated Discs, Chronic Back Pain |
| Companies Covered | Medtronic, Globus Medical, Zimmer Biomet, NuVasive, Boston Scientific, Orthofix Medical, Vertiflex, Paradigm Spine, Life Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interspinous Process Decompression Devices Market Strategic Shifts
Expandable interspinous device architectures are compressing the static-implant installed base as intraoperative adjustability becomes the operative default for variable anatomy matching.
PEEK polymer with titanium coating is consolidating material specification across premium device tiers, delivering radiolucent imaging compatibility with enhanced bone-implant interface stability. Academic medical centers and high-volume spine centers are adopting this hybrid construction at accelerated procurement cycles. The technology is consolidating supplier margins around coating process expertise rather than raw polymer sourcing.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical follow-up obligations for Class IIb spinal implants, forcing manufacturers to rebuild European economic models around longitudinal data collection infrastructure. Device firms are responding by prioritizing MDR-compliant quality management systems over legacy CE-mark transition pathways. Expandable device categories face the steepest documentation burden given their mechanical complexity.
Hospital procurement committees are unbundling device selection from historical vendor loyalty contracts, creating competitive rebidding cycles for interspinous spacer contracts. Integrated delivery networks are replacing individual surgeon preference cards with system-wide value-analysis protocols. This behavioral shift concentrates most visibly in United States multi-hospital systems where CMS bundled payment pilots apply pressure to implant expenditure per episode.
Interspinous Process Decompression Devices Market Segmentation
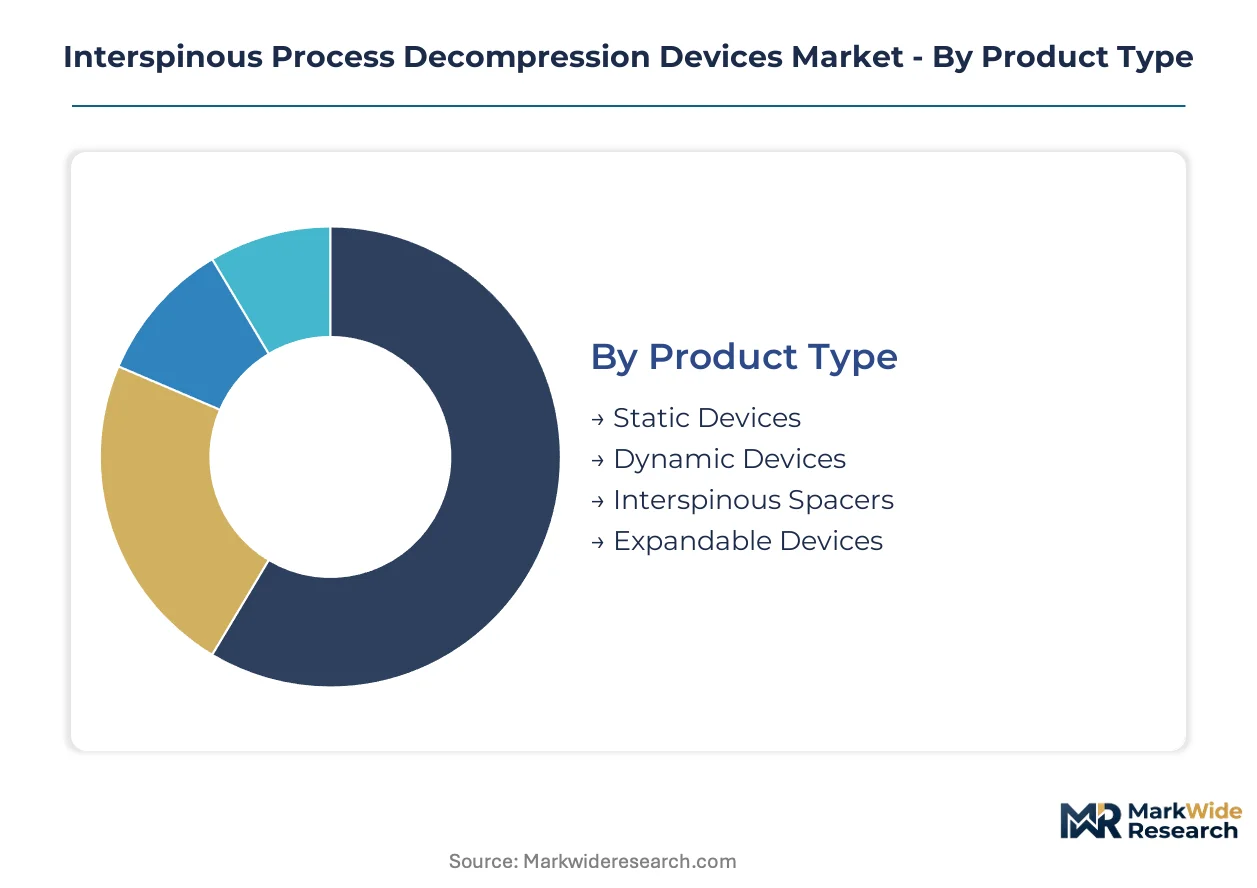
Segmentation in interspinous process decompression devices reveals how regulatory pathways, surgical site economics, and material specifications fragment commercial opportunity. Device manufacturers must align product portfolios across multiple approval frameworks and reimbursement environments.
Product Type:
FDA 510(k) clearance timelines vary substantially across these segments, with static devices benefiting from predicate-rich submission pathways while expandable architectures face heightened mechanical testing scrutiny.
- Static Devices:Fixed-dimension titanium or PEEK constructs dominate current procedural volumes due to established reimbursement codes and simpler surgical learning curves. Hospital procurement committees in the United States favor these implants for their predictable cost-per-case profiles and extensive clinical history.
- Expandable Devices:Intraoperatively adjustable spacers deliver anatomical matching flexibility that static designs cannot replicate. Ambulatory surgical centers in Florida and Texas are adopting these platforms fastest as outpatient lumbar decompression volumes accelerate.
- Dynamic Devices:Motion-preserving designs with flexible cores or hinge mechanisms target younger patients seeking alternatives to fusion.
- Interspinous Spacers:Distraction implants limit pathological extension without rigid fixation, serving mild-to-moderate stenosis cases.
Static devices sit at the top of the volume ranking, with expandable devices climbing the fastest.
End User:
Site-of-service reimbursement differentials are reshaping capital allocation across these customer types, with CMS payment alignment pulling device demand toward outpatient settings.
- Hospitals:Inpatient spine programs retain complex revision cases and comorbid patient cohorts requiring overnight observation. Academic medical centers in California and New York anchor premium-tier procurement for robotic-compatible implant systems.
- Ambulatory Surgical Centers:Freestanding surgical facilities capture straightforward decompression cases as payor policies align with same-day discharge protocols. Texas and Arizona ASC networks are expanding interspinous procedure volumes fastest.
- Orthopedic Clinics:Office-based surgical suites handle diagnostic workup and postoperative monitoring.
- Rehabilitation Centers:Post-acute facilities coordinate recovery protocols and functional outcome tracking.
Hospitals retain the highest absolute case volume, though ambulatory surgical centers are expanding most quickly.
Technology:
Instrument and navigation bundling economics concentrate margin capture in specific technical approaches, with minimally invasive platforms commanding premium attach rates.
- Minimally Invasive Surgery:Percutaneous and tubular retractor approaches reduce tissue disruption and accelerate recovery timelines. High-volume spine centers in Minnesota and Ohio are standardizing MIS workflows for interspinous placement.
- Robotic Surgery:Navigation-integrated placement systems improve implant positioning accuracy and reduce fluoroscopy exposure. Massachusetts and Pennsylvania academic hospitals lead robotic platform adoption for lumbar decompression.
- Traditional Surgery:Open midline approaches with direct visualization serve complex anatomical variants.
- Imaging Guidance:Intraoperative CT and 3D navigation assist device positioning in challenging spinal anatomy.
Minimally invasive surgery holds the largest installed base, with robotic surgery demonstrating the steepest expansion trajectory.
Application:
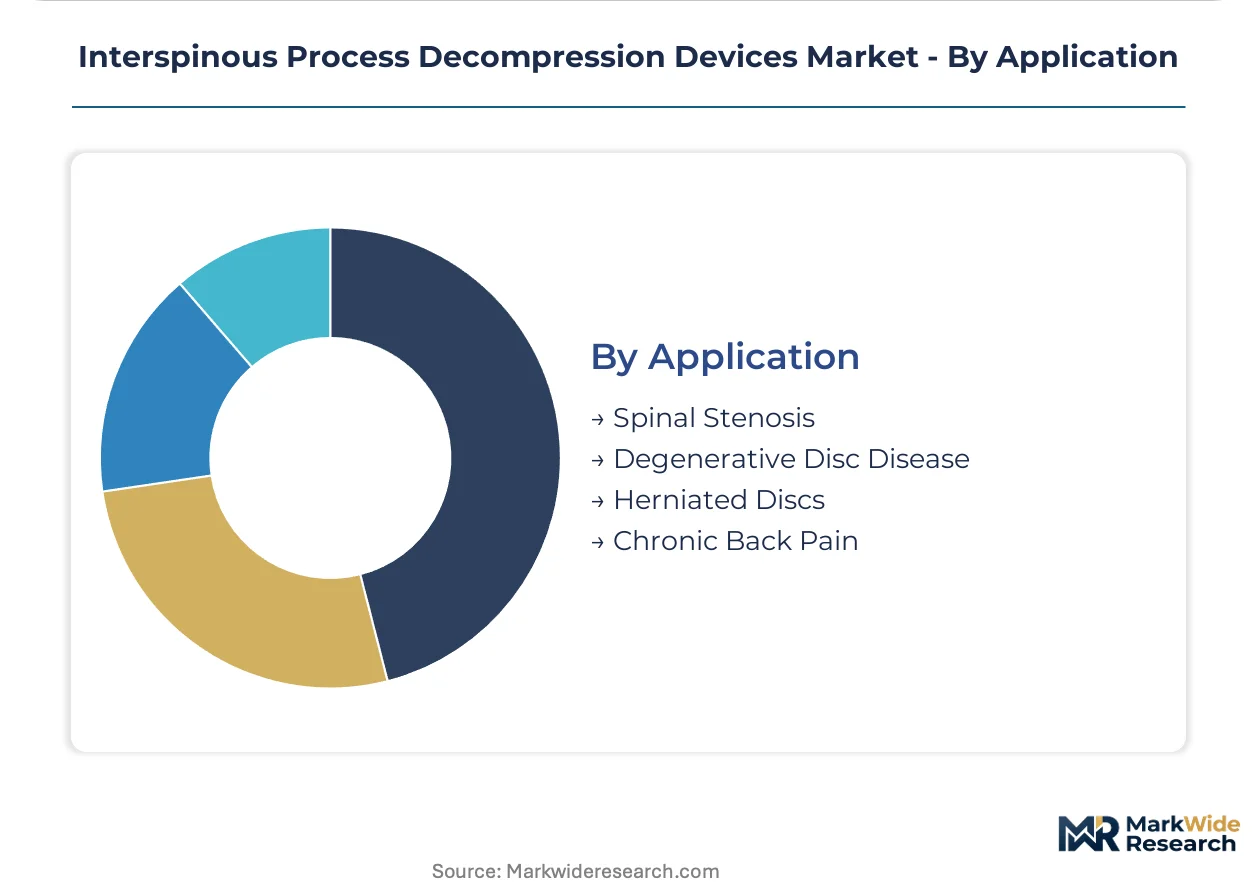
Patient selection criteria and reimbursement coding alignment vary across clinical indications, with spinal stenosis commanding the most established coverage policies.
- Spinal Stenosis:Neurogenic claudication from central or foraminal narrowing represents the primary approved indication for interspinous decompression. Medicare coverage determinations in the United States explicitly support device placement for this diagnosis.
- Degenerative Disc Disease:Adjacent segment pathology and discogenic pain drive demand for motion-preserving alternatives to fusion. Florida and California patient populations with age-related disc degeneration expand addressable cases.
- Herniated Discs:Contained disc herniations with concomitant stenosis occasionally warrant combined decompression approaches.
- Chronic Back Pain:Mechanical low back pain without clear neurogenic compression presents coverage challenges for device reimbursement.
Spinal stenosis dominates procedure volume, with degenerative disc disease gaining share fastest among emerging indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized spine surgeons concentrate in metropolitan medical corridors across the United States, Germany, Japan, China, and Australia, anchoring procedural demand for interspinous decompression implants.
United States
Aging demographics and CMS reimbursement alignment for outpatient alternatives to fusion drive procedural volume. FDA 510(k) clearance pathways compress product entry timelines for expandable device variants. Texas and Florida ASC networks are expanding interspinous procedure volumes fastest as same-day discharge protocols mature.
Germany
Motion-preserving surgical philosophy and established minimally invasive spine training programs sustain device demand. EU MDR post-market surveillance requirements extend clinical follow-up obligations for Class IIb spinal implants. Baden-Württemberg academic medical centers anchor premium-tier procurement for robotic-compatible implant systems.
Japan
Super-aged population structure and conservative treatment preferences expand addressable patient cohorts for dynamic stabilization. PMDA biocompatibility testing protocols filter which manufacturers sustain dual-hemisphere registration costs. Tokyo and Osaka metropolitan hospital systems concentrate robotic platform adoption for lumbar decompression.
China
Rising lumbar spinal stenosis diagnosis rates and hospital infrastructure expansion pull device demand upward. NMPA medical device registration requirements reshape competitive timelines for domestic and foreign manufacturers. Yangtze River Delta spine centers are standardizing minimally invasive workflows for interspinous placement.
Australia
Private health insurance coverage for motion-preserving alternatives and aging population demographics support procedural growth. TGA medical device approval pathways govern market entry for titanium and PEEK hybrid constructs. New South Wales and Victoria academic hospitals lead adoption of navigation-integrated placement systems.
Interspinous Process Decompression Devices Market Competitive Environment
Top-tier vendors anchor integrated spine portfolios, while mid-scale specialists occupy robotics-compatible and lateral-access niches. The vendor base stratifies across three tiers: diversified multinationals with navigation bundling capabilities, spine-focused pure-plays with specialized training ecosystems, and emerging entrants with expandable device architectures. Competitive moves concentrate on strategic partnerships for biologics bundling and geographic expansion into Asia-Pacific regulatory jurisdictions.
Among diversified multinationals, Medtronic, Globus Medical, and NuVasive occupy positions that exemplify distinct competitive archetypes. Medtronic represents the integrated portfolio anchor with navigation and biologics attach-rate expansion. Globus Medical sits within the robotics-compatible spacer design tier competing directly in minimally invasive surgery channels. NuVasive exemplifies the specialized training ecosystem model that locks in surgeon loyalty beyond hardware procurement.
| Leading Market Players |
|---|
| Medtronic |
| Globus Medical |
| Zimmer Biomet |
| NuVasive |
| Boston Scientific |
| Orthofix Medical |
| Vertiflex |
| Paradigm Spine |
| Life Spine |
| Others |
Value Chain & Pricing Dynamics
Backward integration into titanium alloy refining and PEEK polymer synthesis anchors supply position for premium-tier device manufacturers while compressing input cost volatility. This captive sourcing strategy concentrates pricing power among vendors with dual-hemisphere registration capabilities, particularly those serving United States hospital procurement committees and European academic medical centers.
Pricing Analysis
Bundled service models dominate hospital system contracts where navigation hardware and biologics attach to interspinous spacer procurement, while unbundled transactional pricing prevails in ambulatory surgical center networks. Three-tier pricing structure across premium, standard, and economy levels separates robotics-compatible titanium-PEEK hybrids from static PEEK constructs and commodity titanium spacers. Cost compression in the standard tier is intensifying because GPO contracts consolidate purchasing volume across multi-hospital systems. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Regional distribution centers in Tennessee and Arizona serve hub-and-spoke patterns for United States ASC networks, while Rotterdam and Singapore anchor European and Asia-Pacific fulfillment. Titanium alloy feedstock concentrates in Chinese and Japanese refining jurisdictions; PEEK polymer resin sources from German and United States chemical manufacturers. Single-source vulnerability in titanium sponge processing creates qualification bottlenecks when geopolitical friction disrupts Asian supply lanes. Distribution runs through manufacturer-direct sales forces for hospital systems and specialized distributors for outpatient surgical facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in interspinous process decompression devices rests on coating process expertise consolidation and robotics-compatible platform premiums that offset raw material volatility.
For Market Incumbents: Acquire expandable device patent portfolios to neutralize mechanical complexity advantages held by emerging entrants. Defensive consolidation should prioritize FDA 510(k) predicate libraries that accelerate clearance timelines for next-generation architectures; capacity addition in Texas and Florida ASC corridors secures volume growth in the fastest-expanding site-of-service segment. Threat substitution from motion-preserving total disc replacement systems demands biologics bundling lock-in through exclusive hospital system partnerships. For New Entrants and Emerging Players: Ambulatory surgical center distributors represent the most penetrable channel partner type for expandable device platforms lacking established hospital GPO contracts. White-space targets include Japan's PMDA-registered premium tier and European MDR-compliant dynamic stabilization niches filtered by clinical evidence burdens. Go-to-market execution should emphasize intraoperative adjustability training programs that differentiate from static-implant incumbents. For Investors and Strategic Acquirers: Roll-up economics work for spine-focused pure-plays with specialized training ecosystems because surgeon loyalty transcends hardware procurement in this referral-driven specialty. Long-term viability favors vendors with dual-hemisphere registration infrastructure and robotics integration capabilities. Acquisition target archetype: mid-scale specialists with lateral-access technique certification programs. Signal to watch: CMS reimbursement alignment for outpatient interspinous procedures as volume migration inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate-rich pathways compress clearance timelines for expandable device variants in United States markets. |
| CE Marking Pathway | MDR-compliant quality management systems filter smaller manufacturers from European access. |
| Hospital System Partnership | Integrated delivery networks replace surgeon preference cards with value-analysis protocols. |
| Software Companion Development | Navigation-integrated placement systems improve implant positioning accuracy and reduce fluoroscopy exposure. |
| Reimbursement Strategy | CMS bundled payment pilots pressure implant expenditure per episode in multi-hospital systems. |
Study Parameters
Direct dialogue with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative findings in procurement decision dynamics. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up and top-down triangulation reconciled procedural volume estimates with manufacturer-reported implant sales.
Segmentation outputs across product type, end user, technology, and application dimensions informed the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical procedural adoption patterns and reimbursement policy trajectories. Forecast inputs incorporated ambulatory surgical center expansion rates and robotics platform penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement intensity and titanium alloy supply disruptions. Forecasts reflect documented assumptions around CMS reimbursement stability and PMDA biocompatibility protocol continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cryosurgery Devices Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Pen Needles Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Digital BTE Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Clear Aligners Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Lacrimal Duct Stent Tube Market