
 Disposable Medical Devices Sensors Market | 2026-2036
Disposable Medical Devices Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Medical Devices Sensors Market Analysis
Hospital procurement departments are unwinding their historical preference for capital-intensive reusable monitoring equipment, redirecting capital toward single-use sensor contracts that reduce cross-contamination liability. Medtronic leverages its vertically integrated glucose sensing platform to capture recurring consumable revenue streams. Abbott Laboratories anchors its FreeStyle portfolio through pharmacy and direct-to-consumer channels that bypass traditional hospital purchasing committees. Dexcom competes aggressively in the remote monitoring segment with factory-calibrated systems that eliminate patient fingerstick routines.
Disposable medical devices sensors are single-use electrochemical, optical, or pressure-transducing elements fabricated from biocompatible polymers and conductive inks, designed to measure physiological parameters for one patient encounter before controlled disposal. These components typically operate within narrow tolerance bands of ±2% for glucose readings or ±1 mmHg for invasive pressure monitoring, ensuring clinical-grade accuracy without sterilization overhead. Glucose sensors dominate product-type revenue due to the chronic management burden of diabetes populations across developed and emerging economies. Pulse oximeters represent the fastest-growing application segment as post-acute care settings adopt fingertip disposable variants to limit nosocomial transmission. Wireless technology leads the technology category, though NFC-enabled sensors are gaining traction in medication adherence and implantable device communication protocols.
FDA enforces 510(k) and De Novo pathways that mandate clinical validation of sensor accuracy before commercialization, while the EU MDR requires notified body oversight and post-market surveillance for all Class IIa and above disposable sensors. The EPA regulates the downstream disposal of sensors containing lithium batteries or heavy-metal electrodes, pushing manufacturers toward biodegradable substrate research. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring in Medicare and national health systems, as coding decisions directly determine sensor volume pull-through from physician practices and home health agencies.
Market Dynamics
Hospital procurement departments are unwinding their historical preference for capital-intensive reusable monitoring equipment, redirecting capital toward single-use sensor contracts that reduce cross-contamination liability and simplify sterilization logistics across acute and post-acute care networks.
Growth Catalysts
- Hospital-at-home program expansion:CMS reimbursement codes for remote patient monitoring in the United States are pulling sensor volume through physician practices and home health agencies, creating predictable demand streams for disposable glucose and pulse oximetry devices.
- EU MDR biocompatibility mandates:The Medical Device Regulation's tightened requirements for single-use sensing components are accelerating replacement cycles for legacy inventory across German, French, and Italian hospital systems.
- Printed electronics manufacturing:Roll-to-roll fabrication of conductive polymer substrates is compressing unit economics for electrochemical sensors, enabling price points that penetrate outpatient surgical centers previously locked out of continuous monitoring.
Market Restraints
- Lithium battery supply concentration:Disposable sensors with wireless transmission depend on cell production concentrated in East Asian manufacturing clusters, exposing OEMs to input volatility and export control friction.
- EPA hazardous waste downstream:The Environmental Protection Agency's disposal regulations for heavy-metal electrodes and battery-containing sensors impose compliance costs that erode margin on low-ASP products.
- Reusable monitor substitution:Capital equipment vendors are leasing multi-parameter monitors with sterilizable probes to ambulatory surgery centers, creating price competition at the facility level.
Strategic Opportunities
- Underpenetrated Chinese hospital-at-home:The National Health Commission's pilot programs for chronic disease management outside tertiary facilities are opening procurement channels for NFC-enabled medication adherence sensors.
- Biodegradable substrate R&D:Convergence of polylactic acid films with screen-printed conductive inks addresses EPA disposal constraints while differentiating premium product lines for environmentally credentialed health systems.
- Direct-to-consumer pharmacy channels:Bypassing traditional hospital purchasing committees through retail pharmacy partnerships captures recurring revenue from diabetes patients managing therapy outside clinical settings.
Industry Challenges
- Biocompatibility certification timelines:FDA 510(k) and De Novo pathway validation for novel polymer substrates extends development cycles, compressing window for first-mover advantage on next-generation form factors.
- Legacy HIS integration complexity:Disposable sensors transmitting to cloud platforms require API development for hospital information systems with decades-old architecture, delaying deployment in budget-constrained community hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Medical Devices Sensors Market |
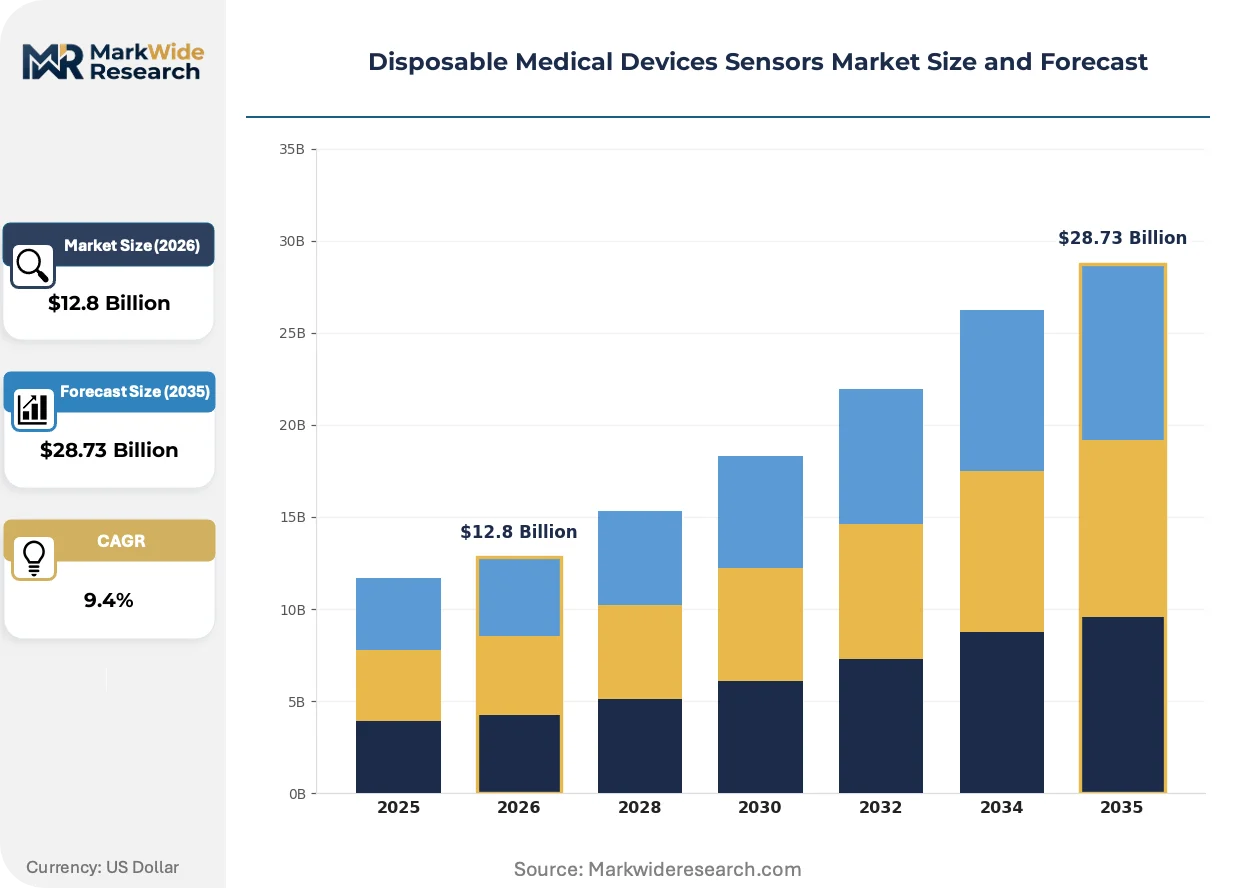
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Sensors, Pressure Sensors, Temperature Sensors, Pulse Oximeters Application: Home Healthcare, Hospital Use, Remote Monitoring, Surgical Procedures Technology: Wireless Technology, NFC, Bluetooth, Membrane-based Technology End User: Patients, Healthcare Providers, Laboratories, Clinics |
| Companies Covered | Medtronic, Abbott Laboratories, Koninklijke Philips N.V., GE Healthcare, Honeywell International Inc., Johnson & Johnson, Dexcom, Analog Devices, Inc., NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Medical Devices Sensors Market Emerging Trajectories
Wireless transmission architectures are compressing the cost structure of continuous monitoring while regulatory pressure on sterilization overhead accelerates design decisions toward single-use formats. Three developments are restructuring competitive positioning.
Factory-calibrated optical glucose sensors are displacing electrochemical strips that require patient-performed fingerstick calibration. Endocrinology practices and pharmacy chains are adopting these systems at pace, eliminating user error in glucose measurement and compressing the addressable market for traditional self-monitoring blood glucose devices. The structural consequence is a revenue model shift from device sales toward recurring consumable subscriptions.
The EU MDR's post-market surveillance requirements for Class IIa disposable sensors are extending notified body oversight timelines and documentation burdens. Industrial consequence includes consolidation of quality management systems among smaller OEMs unable to sustain regulatory affairs overhead. Cardiovascular pressure monitoring catheters and implantable glucose sensors face the steepest compliance ramps, with manufacturers redirecting R&D toward predicate device strategies that leverage existing clinical data packages.
Hospital purchasing committees are fragmenting decision authority across infection control officers, supply chain directors, and clinical department heads. Traditional capital equipment vendors with bundled service contracts are losing gatekeeper status to group purchasing organizations negotiating sensor-specific contracts. This pattern concentrates in United States health systems where value-based care contracts create accountability for readmission rates that disposable monitoring can influence.
Disposable Medical Devices Sensors Market Segmentation
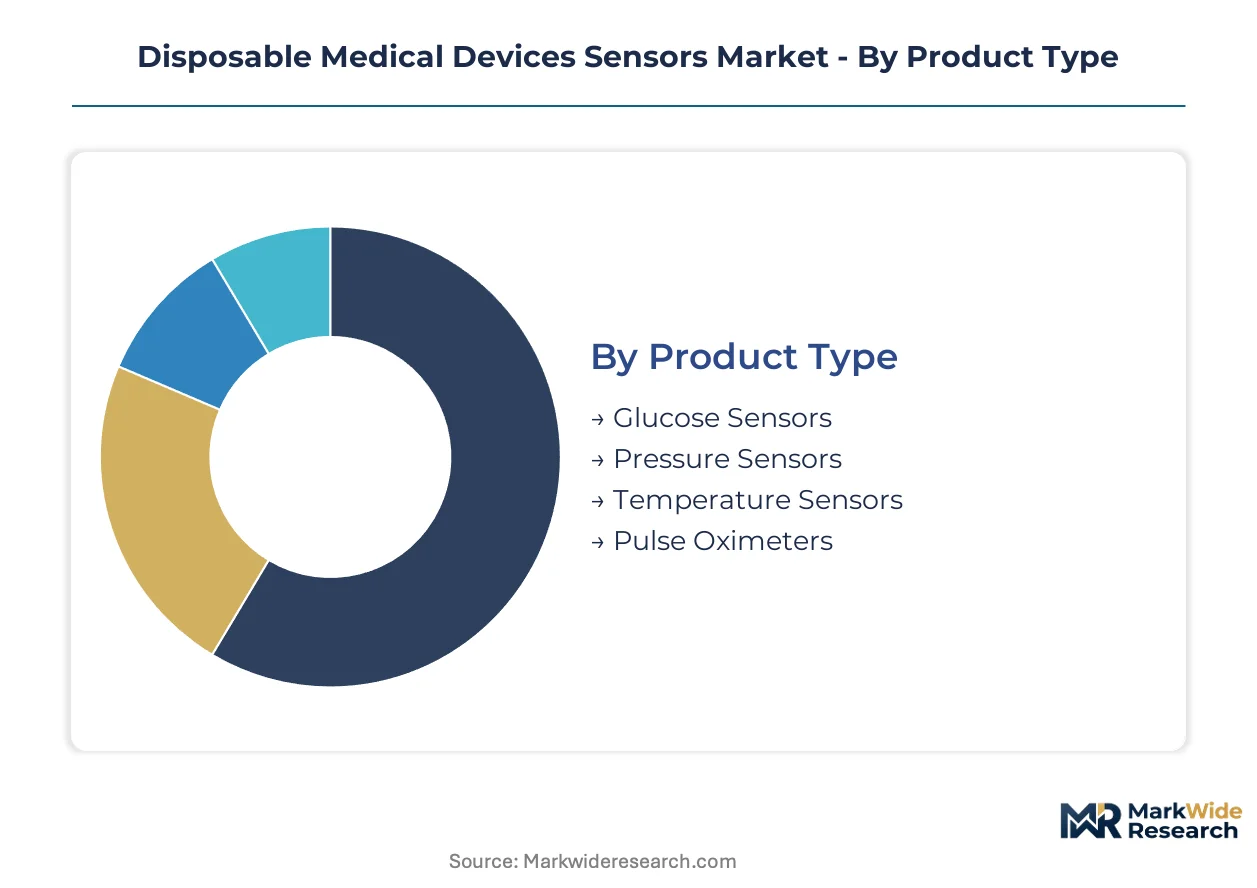
Segmentation in disposable medical devices sensors reveals distinct procurement patterns across acute care networks and decentralized patient settings. Each dimension—product composition, clinical application, transmission protocol, and decision-maker type—carries specific regulatory and reimbursement implications that shape vendor go-to-market strategy.
Product Type:
Domestic production dominates glucose and pressure sensors through vertically integrated U.S. and German manufacturing clusters, while temperature sensors and pulse oximeters rely heavily on East Asian contract fabrication for cost-sensitive hospital contracts.
- Glucose Sensors:Electrochemical strips and factory-calibrated optical elements measure interstitial glucose through enzymatic reactions or near-infrared spectroscopy. Demand concentrates in U.S. pharmacy chains and German diabetes management networks where CMS and statutory health insurance reimbursement codes create predictable pull-through. The chronic disease burden across aging populations sustains recurring consumable revenue models.
- Pressure Sensors:MEMS-based invasive and non-invasive transducers monitor arterial, venous, and intracranial pressures with ±1 mmHg accuracy. Cardiac catheterization labs and neuro-ICUs in tertiary U.S. hospitals drive specification requirements, while EU MDR biocompatibility mandates accelerate replacement of legacy silicon diaphragm designs.
- Temperature Sensors:Thermistor and infrared thermopile elements for core and surface temperature monitoring.
- Pulse Oximeters:Fingertip disposable variants with LED-photodiode arrays for SpO2 and pulse rate detection.
Glucose sensors command the established base. The steepest expansion runs through pulse oximeters.
Application:
Cost tier stratification separates capital-intensive hospital installations from low-ASP home healthcare deployments, with remote monitoring occupying a mid-tier pricing band that scales through subscription economics.
- Home Healthcare:Patient-operated glucose meters, pulse oximeters, and temperature patches designed for unsupervised use with simplified user interfaces. U.S. Medicare remote patient monitoring reimbursement codes and German disease management program contracts concentrate demand, though patient adherence variability constrains clinical utility.
- Hospital Use:Multi-parameter disposable sensors integrated with bedside monitors and central nursing stations. Infection control officers in U.S. health systems and German Krankenhaus procurement departments drive single-use adoption to eliminate cross-contamination liability and sterilization logistics.
- Remote Monitoring:Cellular- and Bluetooth-enabled sensors transmitting to cloud platforms for physician oversight.
- Surgical Procedures:Single-use pressure and temperature sensors for intraoperative hemodynamic monitoring.
Hospital use captures the volume base. Remote monitoring scales most quickly through reimbursement tailwinds.
Technology:
Volume concentration favors wireless architectures, while margin accretion concentrates in NFC-enabled medication adherence and implantable communication protocols requiring specialized antenna design and security certification.
- Wireless Technology:Proprietary and standards-based radio frequency transmission in unlicensed ISM bands for continuous data streaming to receivers and smartphones. Dexcom and Abbott factory-calibrated systems dominate U.S. pharmacy and direct-to-consumer channels, eliminating fingerstick calibration routines and compressing traditional self-monitoring blood glucose device markets.
- NFC:Near-field communication for short-range, low-power data exchange in medication blister packs and implantable device interrogation. Pilot programs through China's National Health Commission for chronic disease management outside tertiary facilities are opening procurement channels for adherence-tracking applications.
- Bluetooth:Low-energy protocols for smartphone-tethered sensor systems.
- Membrane-based Technology:Ion-selective and enzymatic membranes for electrochemical detection.
Wireless technology holds the installed base. NFC gains share fastest through pharmaceutical packaging integration.
End User:
Customer type determines channel structure: patients purchase through retail pharmacy and direct-to-consumer platforms, healthcare providers negotiate through group purchasing organizations, laboratories demand reference-grade accuracy, and clinics seek workflow-integrated disposable bundles.
- Patients:Individual consumers managing diabetes, respiratory conditions, and post-acute recovery outside clinical settings. U.S. pharmacy chains and German mail-order diabetes supply distributors capture recurring revenue through subscription models that bypass hospital purchasing committee gatekeepers.
- Healthcare Providers:Hospital systems, physician practices, and home health agencies procuring through institutional contracts. U.S. value-based care accountability for readmission rates and German hospital efficiency reforms concentrate decision authority with supply chain directors negotiating sensor-specific agreements.
- Laboratories:Reference and point-of-care testing facilities requiring calibrated disposable sensing elements.
- Clinics:Ambulatory and specialty care settings with constrained capital budgets.
Healthcare providers anchor procurement volume. Patient-directed purchasing expands most rapidly through pharmacy channel bypass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution of temperature-sensitive disposable sensors, while the Shenzhen-Dongguan manufacturing corridor anchors East Asian sensor component fabrication.
United States
Hospital-at-home program expansion through CMS remote patient monitoring reimbursement codes drives glucose and pulse oximetry sensor procurement. FDA 510(k) pathways enforce clinical validation standards for wireless transmission systems. The Minneapolis medical device cluster concentrates vertically integrated glucose sensing platforms serving pharmacy and direct-to-consumer channels.
Germany
Statutory health insurance disease management programs create predictable demand for diabetes monitoring consumables. EU MDR biocompatibility mandates accelerate replacement of legacy silicon diaphragm pressure sensors in cardiac catheterization labs. The Baden-Württemberg precision manufacturing belt hosts MEMS fabrication facilities supplying invasive pressure transducers to tertiary hospital systems.
China
National Health Commission pilot programs for chronic disease management outside tertiary facilities open procurement channels for NFC-enabled medication adherence sensors. NMPA clearance requirements for Class IIa disposable sensors extend notified body oversight timelines. The Yangtze River Delta electronics manufacturing base produces roll-to-roll conductive polymer substrates compressing electrochemical sensor unit economics.
Japan
Aging population chronic disease burden sustains recurring consumable revenue models for home-operated glucose meters. PMDA post-market surveillance requirements for implantable glucose sensors redirect R&D toward predicate device strategies. The Kanto region's medical device cluster integrates printed electronics manufacturing with pharmaceutical packaging for medication adherence applications.
United Kingdom
NHS long-term plan commitments to outpatient care shift procurement toward single-use sensors reducing sterilization logistics. MHRA convergence with EU MDR standards extends quality management system documentation burdens. The Cambridge-Oxford-London life sciences triangle concentrates biodegradable substrate research addressing EPA-aligned disposal constraints for premium product differentiation.
Disposable Medical Devices Sensors Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates and specialized glucose monitoring platforms. The vendor base spans vertically integrated device manufacturers with captive sensor production, semiconductor firms supplying MEMS and optical components, and contract fabricators serving cost-sensitive hospital contracts. Two strategic archetypes dominate: pharmacy-channel glucose specialists and hospital-system infection control suppliers. Competitive moves center on backward integration into MEMS fabrication and strategic partnerships with group purchasing organizations bypassing traditional capital equipment gatekeepers.
Among diversified medical technology conglomerates, Medtronic plc exemplifies the vertically integrated archetype with captive glucose sensing platform production, while Abbott Laboratories anchors the pharmacy-channel direct-to-consumer vector. Dexcom Inc. occupies a position within the factory-calibrated remote monitoring tier, representing the wireless transmission specialization that eliminates patient fingerstick calibration routines. These three entities collectively illustrate the competitive spectrum from hospital procurement committee engagement to retail pharmacy subscription economics.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Honeywell International Inc. |
| Johnson & Johnson |
| Dexcom |
| Analog Devices, Inc. |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for conductive polymer substrates concentrate pricing power with roll-to-roll manufacturers in the Yangtze River Delta, while hospital group purchasing organizations exploit volume concentration to compress per-unit glucose sensor costs across U.S. health systems. This lead-time asymmetry between raw material suppliers and downstream procurement committees shapes margin distribution across the disposable sensor value chain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates factory-calibrated optical systems from electrochemical strips and basic temperature patches. FDA 510(k) certification tier and wireless transmission capability drive price differentiation, with Bluetooth-enabled glucose monitors commanding premiums over NFC-only adherence trackers. Cost compression in economy-tier pulse oximetry is intensifying because East Asian contract fabricators compete on volume for hospital infection control contracts. Ambulatory surgery centers exhibit highest price sensitivity, while tertiary cardiac catheterization labs prioritize accuracy specifications over per-unit cost.
Supply Chain Analysis
Inventory buffers for lithium coin cells and MEMS pressure transducers stretch to twelve weeks, exposing OEMs to supply chain friction when East Asian battery clusters face export control reviews. Manufacturing concentration in China, South Korea, and Germany feeds the tier-one sensor assembly operations, with conductive inks and biocompatible polymer substrates drawing from specialized chemical suppliers in the U.S. and Switzerland. Single-source vulnerability for precision MEMS fabrication creates qualification bottlenecks when cardiac catheterization labs demand ±1 mmHg accuracy guarantees. Distribution runs through medical device distributors and group purchasing organizations serving hospital systems, bypassing traditional capital equipment leasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable sensor markets are approaching a platform-economics inflection where interoperability between hospital information systems and cloud-native monitoring platforms determines competitive survival, with CMS reimbursement codes for remote patient monitoring accelerating ecosystem consolidation around standardized data exchange protocols.
For Market Incumbents: Compound recurring revenue streams by deepening backward integration into MEMS fabrication for pressure transducers, while defending pharmacy-channel glucose subscriptions against factory-calibrated optical entrants. FDA De Novo pathway investments for novel biocompatible substrates protect margin against commodity electrochemical strip competition.
For New Entrants and Emerging Players: Lead with biodegradable substrate differentiation targeting NHS long-term plan sustainability commitments and German Krankenhaus environmental credentialing requirements. China's National Health Commission pilot programs for NFC-enabled medication adherence outside tertiary facilities represent the most penetrable geography, with pharmaceutical packaging partnerships as the viable go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consumable-subscription play because chronic disease monitoring outside acute settings generates predictable replacement demand regardless of macroeconomic cycles. Acquisition targets should display captive sensor production and established GPO contracts. The signal to watch is CMS reimbursement code expansion for continuous glucose monitoring in non-diabetic populations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercialization timelines for wireless glucose sensors targeting U.S. pharmacy chains. |
| CE Marking Pathway | Unlocks statutory health insurance reimbursement across German, French, and Italian hospital systems. |
| Hospital System Partnership | Secures multi-year sensor contracts through GPO negotiations bypassing capital equipment committees. |
| Software Companion Development | Enables cloud platform integration with legacy hospital information systems in budget-constrained community hospitals. |
| Reimbursement Strategy | Aligns product specifications with CMS remote patient monitoring codes driving volume pull-through. |
Methodological Framework
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings across the disposable medical devices sensors landscape. Primary interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee chairs, and regulatory affairs specialists at glucose monitoring platforms combined with FDA 510(k) databases, EU MDR notified body documentation, CMS Medicare reimbursement code releases, and hospital supply chain expenditure records. Bottom-up sensor shipment estimates and top-down healthcare expenditure allocation triangulate market sizing.
Sensitivity analysis around reimbursement code expansion timelines and battery supply concentration scenarios tests forecast robustness across the projection horizon. Segmentation modeling spans product type, application setting, transmission protocol, and end-user archetype, with regional regulatory clusters and hospital-at-home program maturity as additional dimensions. CAGRs derive from patient population growth, replacement cycle compression, and pricing trajectory assumptions, with chronic disease prevalence curves and outpatient surgical volume trends as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement support or unanticipated EU MDR documentation burden increases would require recalibration. Forecasts reflect documented assumptions regarding wireless technology adoption curves and biocompatibility certification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Neurointerventional Devices Market