
 North America Insulin Delivery Devices Market | 2026-2036
North America Insulin Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insulin Delivery Devices Market Analytics
Subscription-based software layers for dose optimization and remote monitoring is restructuring how manufacturers capture recurring revenue beyond hardware sales. Novo Nordisk leverages its connected pen ecosystem to sustain patient engagement through data-linked services. Medtronic anchors its competitive position with closed-loop algorithm updates that extend pump lifecycle value. Tandem Diabetes Care differentiates through smartphone-integrated control interfaces that occupy the premium automation tier.
Insulin delivery devices comprise electromechanical and disposable systems engineered to administer precise hormone dosages via subcutaneous, intramuscular, or inhalation routes, typically incorporating flow-rate sensors, microprocessors, and sterile fluid pathways for metabolic disease management. Insulin pumps and smart insulin pens currently lead installed base metrics, while closed-loop systems represent the fastest-expanding technology segment driven by algorithmic glucose control improvements. Home care settings command the largest end-user volume, though diabetes clinics retain concentrated margin pools through specialized training and device fitting services.
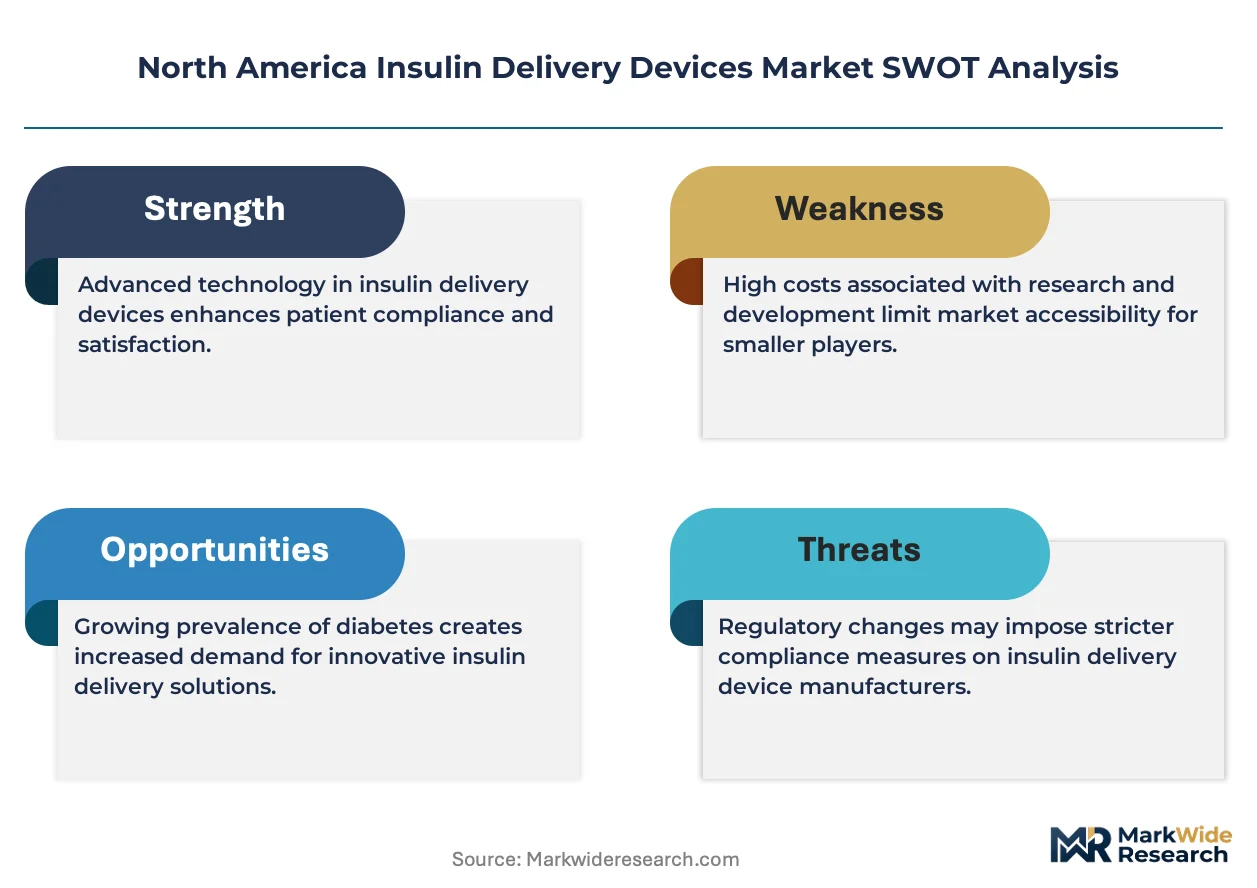
FDA digital health pre-certification and HIPAA data interoperability standards shape product development timelines and software update protocols across North American manufacturers. Health Canada and PMRA requirements for biocompatibility testing and adverse event reporting further condition cross-border market access for pump and pen suppliers. Stakeholders must monitor evolving reimbursement codes for automated insulin dosing and prepare for potential CMS coverage expansions that could shift patient cost responsibility structures.
Market Dynamics
FDA digital health pre-certification pathways are compressing development cycles for algorithm-enabled insulin pumps while CMS reimbursement code expansions for automated insulin dosing are redrawing competitive boundaries across device manufacturers.
Growth Catalysts
- Home Care Migration:Diabetes patients across the United States and Canada are relocating chronic management from clinical settings to residential environments, expanding demand for self-administration tools with connectivity features.
- HIPAA-Aligned Data Interoperability:Standardized health information exchange protocols are enabling seamless glucose data flow between pens, pumps, and electronic health records, reducing provider friction for connected device adoption.
- Algorithmic Closed-Loop Control:Real-time glucose sensing paired with predictive insulin dosing software is reducing hypoglycemic events, creating clinical pull for advanced pump systems in pediatric and Type 1 populations.
Market Restraints
- Biocompatibility Testing Burden:Health Canada and PMRA requirements for extended wear adhesive and infusion set materials are extending validation timelines and raising pre-market compliance costs for pump suppliers.
- Concentrated Insulin API Supply:Active pharmaceutical ingredient production for rapid-acting analogs clusters among a limited set of contract manufacturers, exposing device makers to upstream pricing volatility and allocation constraints.
- Disposable Pen Cost Floor:Single-use insulin pen manufacturing faces sterilization and precision molding cost structures that resist further automation-driven reduction, limiting price elasticity in cash-pay segments.
Strategic Opportunities
- Remote Patient Monitoring Integration:Medicare Advantage plans in the United States are expanding coverage for continuous glucose monitor and pump data review services, creating reimbursement tailwinds for cloud-connected device ecosystems.
- Pediatric Automated Dosing:FDA breakthrough device designation pathways for closed-loop systems targeting adolescent populations offer expedited review and premium pricing potential in an underserved demographic.
- Subscription Software Layers:Dose optimization algorithms and predictive analytics delivered as recurring services are enabling manufacturers to capture lifetime value beyond initial hardware transactions.
Industry Challenges
- Firmware Validation Talent Scarcity:Medical device software engineering expertise, particularly for safety-critical control systems compliant with IEC 62304, commands premium compensation and extended recruitment cycles.
- Legacy Pump Integration Complexity:Hospital networks and diabetes clinics maintain heterogeneous installed bases of earlier-generation devices, complicating enterprise-wide data aggregation and training standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insulin Delivery Devices Market |
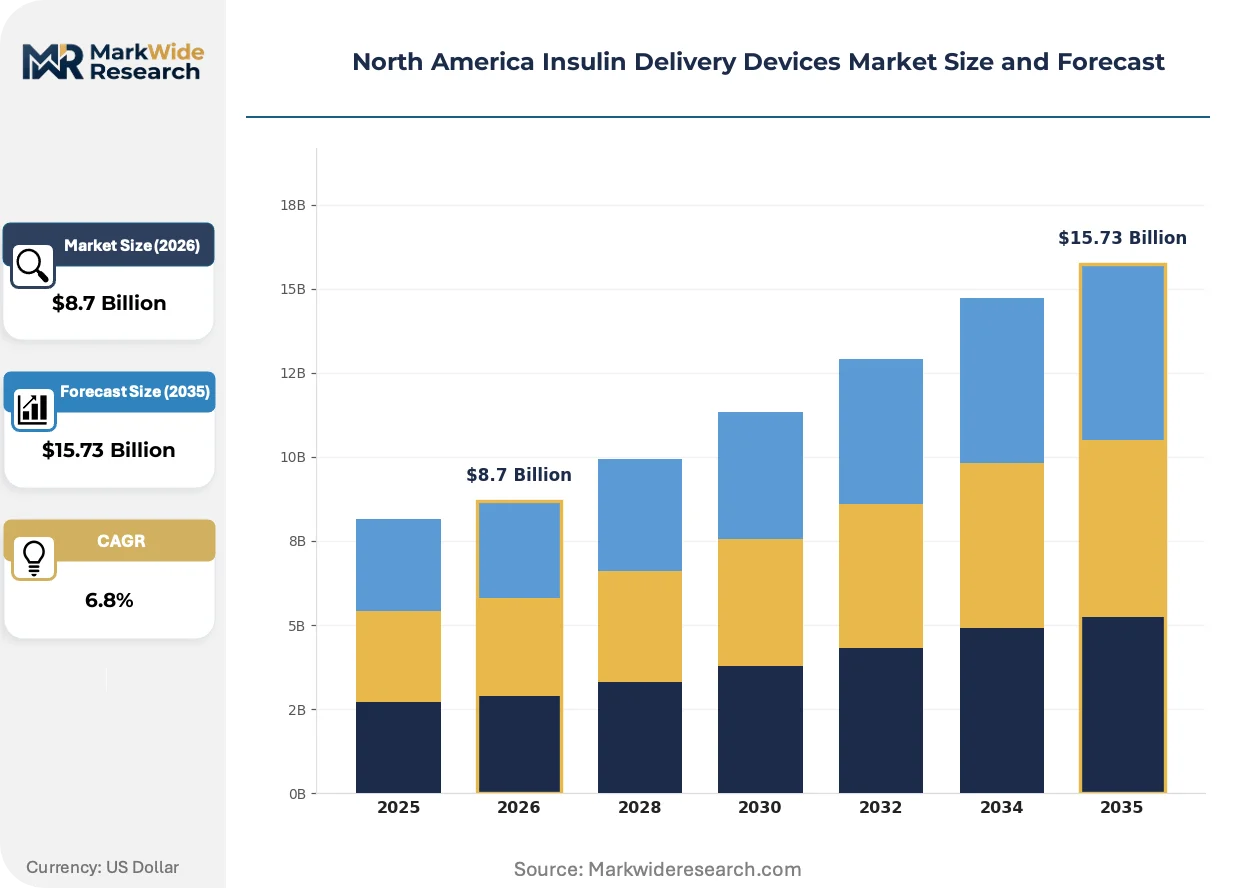
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Jet Injectors, Inhalers End User: Hospitals, Home Care Settings, Diabetes Clinics, Pharmacies Technology: Smart Insulin Pens, Continuous Glucose Monitors, Closed-Loop Systems, Wearable Devices Delivery Mode: Subcutaneous, Intramuscular, Inhalation, Others |
| Companies Covered | Novo Nordisk, Medtronic, Sanofi, Eli Lilly and Company, Becton Dickinson and Company, Insulet Corporation, Ypsomed, Tandem Diabetes Care, Embecta Corp, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insulin Delivery Devices Market Evolving Landscape
Connected device architectures are displacing standalone hardware as the foundational competitive variable, with data services and algorithmic capabilities now determining vendor selection criteria across North American payers and health systems.
Smart insulin pens equipped with dose logging and Bluetooth transmission are overtaking conventional disposable pens in prescriber preference across United States endocrinology practices. Patients managing multiple daily injections are adopting these devices at accelerating rates. The shift is compressing market share for non-connected pen manufacturers while expanding recurring revenue opportunities through companion software subscriptions.
FDA digital health pre-certification pilot programs are enabling qualified manufacturers to deploy software updates to in-market pumps without traditional 510(k) submissions for each modification. This regulatory pathway accelerates algorithm improvement cycles for glucose control systems. Closed-loop pump vendors with pre-certified quality management systems are capturing competitive advantage through faster feature deployment.
Hospital procurement committees are consolidating insulin delivery device purchasing decisions under centralized pharmacy and biomedical engineering oversight, displacing decentralized clinician-led selection. This concentration shifts vendor negotiation leverage toward institutional contracting teams demanding interoperability guarantees and total cost-of-ownership guarantees. The pattern is most pronounced in integrated delivery networks across the Northeastern and Midwestern United States.
North America Insulin Delivery Devices Market Segmentation
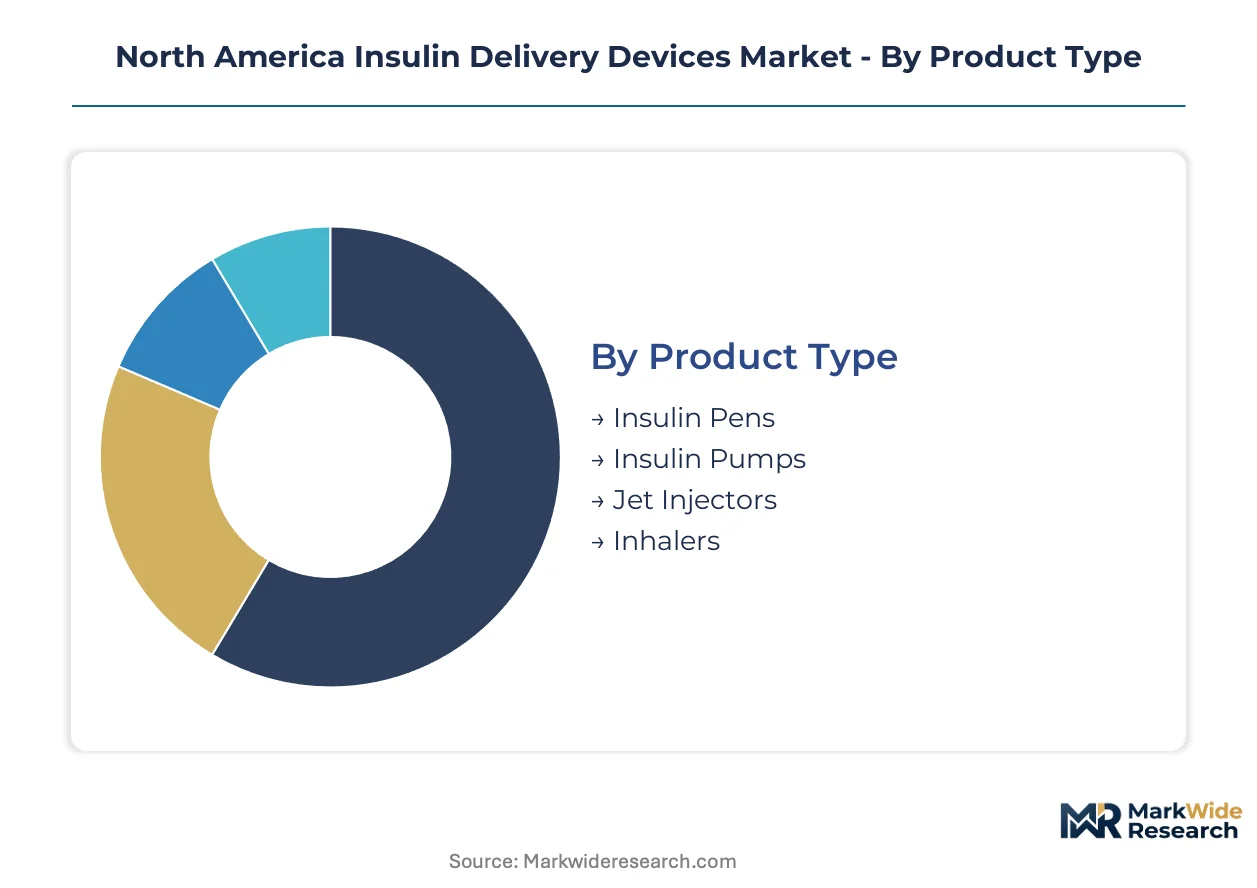
Insulin delivery device manufacturers design product portfolios around distinct patient workflows, reimbursement pathways, and clinical oversight levels. Each segmentation axis reveals where hardware margins concentrate versus where software services capture recurring value.
Product Type:
Standardization dominates disposable pen manufacturing while pumps demand intensive customization for infusion set configurations and algorithm personalization.
- Insulin Pens:Disposable and reusable pen systems integrate precision dose dials with sterile cartridge chambers. Demand clusters in United States retail pharmacy channels where Medicare Part D coverage drives volume; Bluetooth-enabled smart variants are displacing conventional pens in endocrinology practices seeking adherence data.
- Insulin Pumps:Electromechanical reservoir systems with programmable basal-bolus profiles and occlusion detection sensors. Tethered and patch pump formats split demand between pediatric Type 1 patients requiring tubing flexibility and adults prioritizing discretion; closed-loop algorithm subscriptions now determine vendor stickiness more than hardware specifications.
- Jet Injectors:Needle-free systems using high-pressure fluid streams to breach skin barriers. Limited penetration in needle-averse patient niches and specific Canadian provincial formulary exceptions where phobia documentation qualifies for coverage.
- Inhalers:Pulmonary insulin delivery devices utilizing dry powder or liquid aerosol formulations. Restricted availability following earlier product withdrawals; residual demand concentrates in United States academic medical centers conducting comparative effectiveness research against subcutaneous alternatives.
Most installed capacity flows through Insulin Pens. Expansion is steepest in Insulin Pumps.
End User:
Cost absorption patterns diverge sharply across settings, with institutional procurement demanding total cost-of-ownership guarantees while direct-to-patient channels prioritize out-of-pocket affordability.
- Hospitals:Acute care facilities managing diabetic ketoacidosis episodes and perioperative glucose control. United States integrated delivery networks in the Northeast and Midwest are consolidating device purchasing under centralized pharmacy committees; interoperability with electronic health record systems now gates contract eligibility.
- Home Care Settings:Residential environments where patients or caregivers perform self-administration. Fastest-growing end-use category as remote patient monitoring reimbursement codes expand under Medicare Advantage plans; connectivity features enabling clinician data review are becoming baseline expectations rather than premiums.
- Diabetes Clinics:Specialized outpatient facilities providing device training, pump initiation, and continuous glucose monitor interpretation. Concentrated margin pools persist through bundled fitting fees and manufacturer co-marketing arrangements despite volume migration toward home-based management.
- Pharmacies:Community and specialty dispensaries handling pen needle and insulin co-prescription fulfillment. United States retail chains are deploying pharmacists for device education to capture medication therapy management reimbursement; limited pump involvement due to fitting complexity.
Volume concentrates in Home Care Settings. Margin intensity peaks in Diabetes Clinics.
Technology:
Patent-protected algorithm layers are displacing commodity hardware as the primary value capture mechanism across this segmentation axis.
- Smart Insulin Pens:Bluetooth-enabled dose capture with timestamp and carbohydrate logging transmitted to companion applications. United States endocrinology practices are adopting these as standard-of-care for multiple daily injection patients; subscription analytics for pattern recognition generate recurring revenue streams beyond device sale.
- Continuous Glucose Monitors:Factory-calibrated sensors providing interstitial glucose readings every 1-5 minutes. Integration with pump systems via automated insulin dosing algorithms is becoming the default configuration for Type 1 patients with pharmacy benefit coverage; sensor manufacturing scale and adhesive biocompatibility remain supply constraints.
- Closed-Loop Systems:Integrated pump-sensor platforms with predictive low glucose suspend and hybrid automated dosing. FDA breakthrough device designations for adolescent indications are accelerating pediatric adoption; algorithm update frequency now differentiates vendor performance more than hardware specifications.
- Wearable Devices:Patch pumps and alternative form factors emphasizing discretion and activity compatibility. Demand from United States working-age adults prioritizing occupational concealment; smaller reservoir capacity requires more frequent change intervals than conventional pumps.
Continuous Glucose Monitors anchor current installed base. Closed-Loop Systems are gaining share fastest.
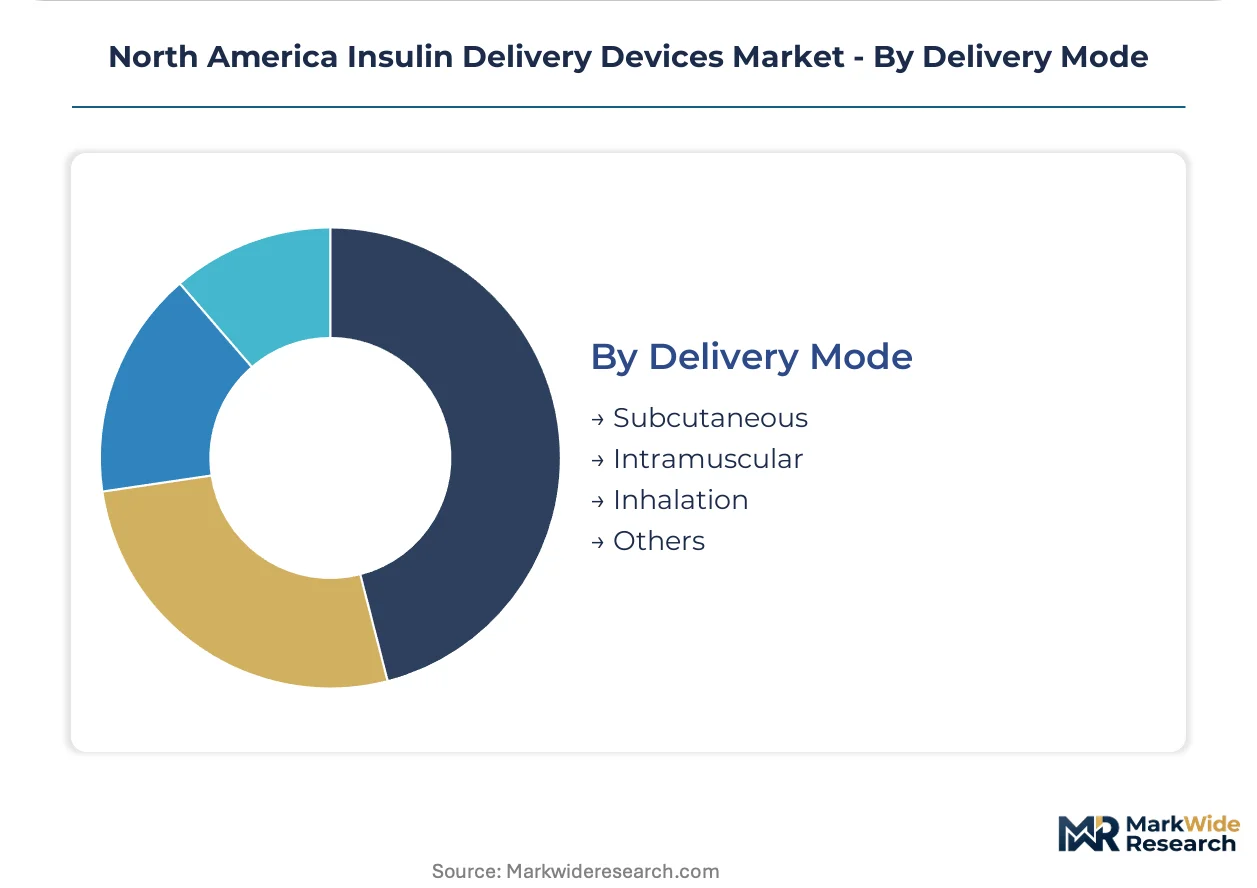
Delivery Mode:
Route selection reflects insulin pharmacokinetics, patient manual dexterity, and tissue absorption variability across demographic segments.
- Subcutaneous:Abdominal, thigh, or arm tissue deposition using pen needles or infusion sets. Dominant delivery route for rapid-acting and basal analogs; lipohypertrophy from site rotation failures drives demand for shorter needle lengths and automated site tracking applications.
- Intramuscular:Deeper tissue penetration for accelerated absorption in specific clinical scenarios. Limited to hospital-based acute management and rare home emergency protocols; requires longer needles and anatomical training that most outpatient settings avoid.
- Inhalation:Pulmonary absorption through inhaled insulin formulations. Restricted to United States markets with residual product availability; pulmonary function testing requirements and dosing granularity limitations constrain expansion beyond highly motivated patient subsets.
- Others:Investigational and niche routes including intranasal, oral, and transdermal approaches. No commercial significance in current North American market; academic research interest persists for closed-loop compatible alternatives to injection burden.
Nearly all therapeutic insulin flows through Subcutaneous delivery. Inhalation retains marginal presence only in specific United States prescribing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's regulatory pathways for connected insulin devices diverge from United States timelines, creating asynchronous product launch windows across the border. Mexico's expanding diabetes prevalence and evolving reimbursement infrastructure are attracting device manufacturers seeking volume growth beyond saturated northern markets.
United States
Integrated delivery networks in the Northeast and Midwest are consolidating insulin pump procurement under centralized pharmacy committees. FDA digital health pre-certification programs enable faster algorithm updates for closed-loop systems. The Boston-Cambridge corridor anchors concentrated diabetes technology R&D activity alongside major academic medical centers.
Canada
Provincial formulary variations create patchwork coverage for advanced insulin pumps across Ontario, Quebec, and British Columbia. Health Canada and PMRA biocompatibility requirements for extended-wear adhesives extend validation timelines for new infusion sets. Toronto's hospital networks serve as early evaluation sites for connected pen technologies before broader rollout.
Mexico
Rising Type 2 diabetes prevalence in Mexico City and Guadalajara metropolitan zones is expanding addressable patient populations for pen-based therapies. Seguro Popular and IMSS reimbursement expansions for glucose monitoring devices are creating incremental access pathways. Northern border states exhibit higher pump adoption rates tied to cross-border healthcare utilization patterns.
North America Insulin Delivery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary algorithm developers commanding premium positioning in closed-loop systems while disposable pen fabricators compete on sterilization scale and molding precision. The vendor base concentrates around three strategic archetypes: integrated pharmaceutical-device conglomerates, pure-play diabetes technology specialists, and infusion set component suppliers. Dominant competitive moves include algorithm licensing partnerships between sensor manufacturers and pump developers, plus backward integration into continuous glucose monitor production by established pump vendors.
Within the integrated pharmaceutical-device tier, Novo Nordisk and Sanofi occupy positions that span insulin API production through connected delivery hardware, exemplifying vertical control over patient workflow capture. Eli Lilly and Company sits within the same archetype, representing the remaining major insulin manufacturer with device development capabilities. Among pure-play technology developers, Medtronic anchors the pump-centric specialist segment, while Tandem Diabetes Care exemplifies the smartphone-integrated control interface approach that defines premium automation tiers.
| Leading Market Players |
|---|
| Novo Nordisk |
| Medtronic |
| Sanofi |
| Eli Lilly and Company |
| Becton Dickinson and Company |
| Insulet Corporation |
| Ypsomed |
| Tandem Diabetes Care |
| Embecta Corp |
| Others |
Value Network & Pricing Analysis
Backward integration into continuous glucose monitor production anchors competitive positioning for insulin pump manufacturers, concentrating supply control among vendors with captive sensor fabrication while compressing price floors for standalone pen suppliers lacking algorithmic software layers.
Pricing Analysis
Capacity additions in Mexico and Southeast Asia are reshaping price floors for disposable pen components, though sterilization validation costs resist full pass-through. Subscription-tiered pricing for closed-loop algorithm updates now dominates premium pump segments, separating vendors with FDA pre-certification from hardware-only competitors. Price differentiation hinges on HIPAA-aligned data interoperability certification and bundled remote monitoring service levels. Cost compression in conventional pen manufacturing intensifies as Mexican contract manufacturers scale precision molding capacity, while Medicare Advantage coverage expansion reduces patient price sensitivity for connected device ecosystems.
Supply Chain Analysis
Refurbishment flows for insulin pumps concentrate in United States third-party service centers handling warranty extensions and algorithm hardware upgrades. Active pharmaceutical ingredient production for rapid-acting analogs draws from Ireland, Denmark, and United States contract manufacturing sites. Supply chain risk centers on single-source vulnerability for extended-wear adhesive polymers subject to Health Canada biocompatibility validation delays. Distribution runs through United States integrated delivery network pharmacy committees and Canadian provincial formulary procurement bodies, with retail pharmacy channels handling pen and needle fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States manufacturers face geographic-arbitrage pressure as Mexican production zones offer sterilization cost advantages below FDA-regulated domestic facilities, while Canadian regulatory asynchrony creates launch-timing premiums for cross-border product differentiation.
For Market Incumbents: Deploy algorithm update velocity as the primary retention mechanism against smartphone-integrated control interface challengers. Consolidate hospital procurement committee relationships through interoperability guarantee contracts that lock out non-connected pen competitors. Counter firmware engineering talent scarcity with captive training pipelines tied to Boston-Cambridge R&D corridor partnerships. For New Entrants and Emerging Players: Capture pediatric automated dosing segments where FDA breakthrough device designation pathways offer expedited review and premium pricing headroom. Target Mexico City and Guadalajara metropolitan zones with pen-based therapy solutions as Seguro Popular reimbursement expansions reduce patient cost barriers. Pursue pharmacist-led device education partnerships with United States retail chains seeking medication therapy management reimbursement capture. For Investors and Strategic Acquirers: Roll-up economics work for infusion set component specialists because Health Canada and PMRA biocompatibility requirements create regulatory moats that deter new fabrication entrants. Five-to-ten year viability favors vendors with closed-loop algorithm patent estates and captive continuous glucose monitor supply. Monitor CMS coverage determinations for automated insulin dosing as the inflection signal for hardware-versus-software value capture shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates algorithm deployment timelines for Medtronic and Tandem pump systems. |
| Hospital System Partnership | Locks in enterprise-wide interoperability contracts with Northeastern integrated delivery networks. |
| Software Companion Development | Generates recurring revenue through Novo Nordisk dose optimization subscription layers. |
| Reimbursement Strategy | Aligns connected pen offerings with expanding Medicare Advantage remote monitoring codes. |
| CE Marking Pathway | Enables Canadian provincial formulary access ahead of asynchronous Health Canada approvals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with diabetes technology executives, hospital biomedical engineers, GPO contracts managers, and endocrinology practice administrators with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and Health Canada medical device licenses. Bottom-up installed base estimates for pumps and pens triangulated against top-down pharmaceutical manufacturer shipment disclosures.
Comparable historical periods anchored the projection horizon across product type, end user setting, technology tier, and delivery mode segmentation dimensions. CAGRs derived from algorithmic adoption curve modeling and connectivity penetration rates specific to closed-loop system diffusion. Forecast inputs incorporated HIPAA interoperability implementation timelines and provincial formulary expansion patterns.
Underlying measurement precision varies by segment; closed-loop system revenue estimates carry tighter precision than inhaler device projections given limited residual availability. Forecasts incorporate assumptions regarding FDA digital health guidance evolution and CMS coverage determination schedules. Practitioners should monitor Health Canada biocompatibility validation backlogs and Mexican reimbursement infrastructure maturation for early signals of supply chain and pricing inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital X-Ray Devices Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
Global Retinoscopes Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Global Pessary Market
Medical Devices
Manometry System Market
Medical Devices
Global Medical Footwear Market