
 North America Exosome Research Products Market | 2026-2036
North America Exosome Research Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Exosome Research Products Market Analytics
Software-defined analytics bundled with isolation instrumentation is restructuring how research laboratories procure exosome research products. Thermo Fisher Scientific leverages its chromatography and mass spectrometry installed base to cross-sell exosome characterization workflows. Bio-Techne anchors its position through specialized growth media and exosome-depleted serum formulations that reduce variability in cell culture experiments. QIAGEN competes with automated nucleic acid extraction platforms optimized for exosomal RNA and DNA profiling.
Exosome research products comprise reagents, kits, instruments, and services designed to isolate, characterize, and manipulate extracellular vesicles ranging from 30 to 150 nanometers in diameter, typically derived from cell culture supernatant or biofluids through differential ultracentrifugation or size-exclusion chromatography. These products enable researchers to investigate intercellular communication mechanisms, disease biomarkers, and therapeutic delivery vectors across oncology, neurology, and infectious disease domains. Reagents and kits currently occupy the largest revenue share due to recurring consumable demand, while microfluidics-based isolation technologies represent the fastest-expanding segment as labs seek higher purity and throughput than conventional ultracentrifugation methods provide. Services, particularly contract manufacturing and analytical testing for exosome therapeutics, concentrate margin pools as pharmaceutical sponsors outsource GMP-compliant production.
FDA oversight of cell and gene therapy products, combined with NIH funding allocation policies and institutional biosafety committee protocols, shapes validation requirements and commercial access conditions for exosome research products in the United States. Health Canada and PMRA guidelines for biological product characterization extend similar regulatory framing for Canadian research institutions and manufacturers. Stakeholders must monitor evolving distinctions between research-use-only and clinical-grade product classifications, as this boundary determines pricing power, liability exposure, and addressable customer base expansion.
Market Dynamics
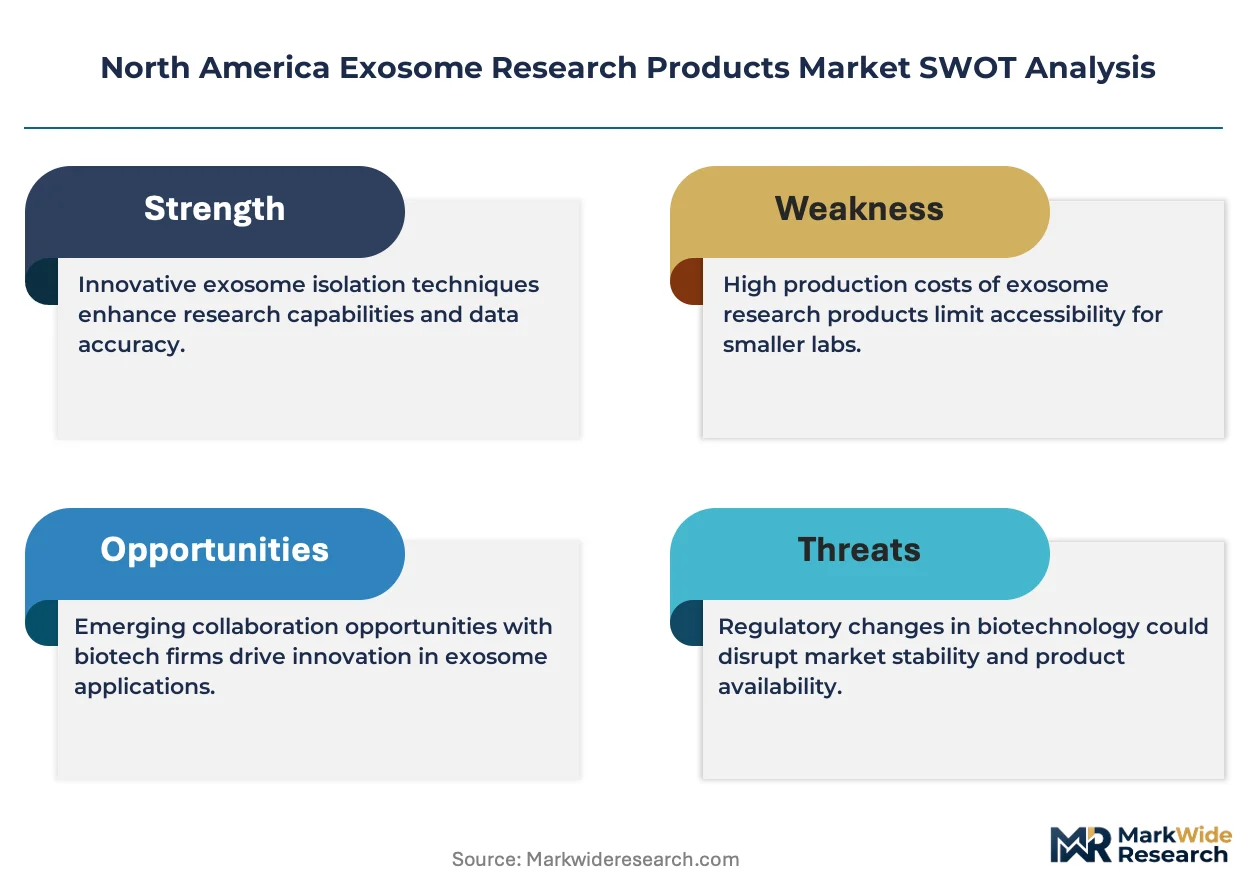
FDA guidance on extracellular vesicle-based therapeutics is compressing validation timelines and forcing manufacturers to restructure quality systems before clinical-grade product commercialization. This regulatory pressure cascades through procurement contracts at academic medical centers and contract research organizations.
Growth Catalysts
- NIH funding allocation policies:The National Institutes of Health prioritizes extracellular vesicle biomarker research in oncology and neurology, channeling grant capital toward institutions purchasing isolation kits and characterization platforms.
- Cell culture standardization:Exosome-depleted serum formulations reduce experimental variability, pulling demand from translational research labs seeking reproducible intercellular communication studies.
- Boston-Cambridge biotech corridor:Clustered research hospitals and venture-backed startups in Massachusetts concentrate reagent consumption, creating localized demand density that supports specialized distribution infrastructure.
Market Restraints
- Ultracentrifugation equipment concentration:Supply of high-performance centrifugation systems concentrates among limited German and Japanese manufacturers, exposing North American labs to extended lead times and service dependency.
- Research-use-only boundary:FDA distinctions between RUO and clinical-grade classifications create compliance friction, forcing manufacturers to maintain dual product lines and documentation systems.
- Technical purity limitations:Conventional differential centrifugation yields exosome preparations contaminated with protein aggregates and lipoproteins, restricting downstream applications in therapeutic development.
Strategic Opportunities
- Canadian institutional expansion:Health Canada and PMRA guidelines for biological product characterization are maturing, creating regulatory clarity that supports academic hospital procurement in Toronto, Montreal, and Vancouver research clusters.
- Microfluidics-convergent isolation:Integration of nanofabricated membrane technologies with automated liquid handling is modularizing workflow architectures, enabling labs to bypass ultracentrifugation bottlenecks entirely.
- GMP-compliant contract manufacturing:Pharmaceutical sponsors outsource exosome therapeutic production to specialized CDMOs, concentrating margin pools in analytical testing and quality release services.
Industry Challenges
- Extracellular vesicle isolation expertise gap:Technical proficiency in size-exclusion chromatography optimization and nanoparticle tracking analysis interpretation remains scarce, extending experimental timelines at academic labs.
- Multi-platform integration complexity:Characterization workflows requiring correlated data from NTA, flow cytometry, and mass spectrometry demand specialized bioinformatics infrastructure that stretches institutional IT budgets.
- Institutional biosafety committee protocols:Varied approval timelines across university compliance offices delay project initiation, particularly for human biofluid-derived exosome studies requiring enhanced containment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Exosome Research Products Market |
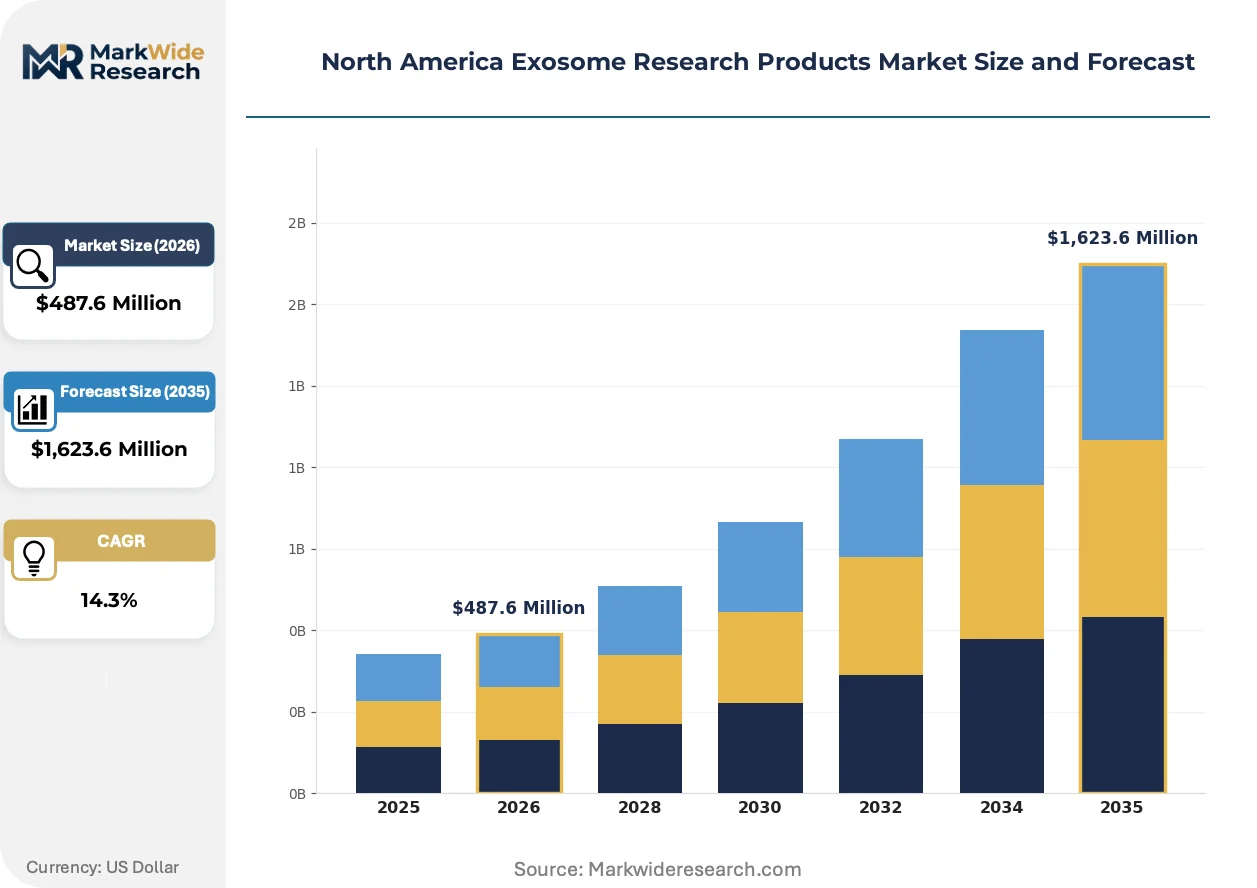
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,623.6 Million |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Services End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotech Firms Application: Diagnostics, Therapeutics, Drug Delivery, Biomarker Discovery Technology: Microfluidics, Nanoparticle Isolation, Imaging Techniques, Sequencing |
| Companies Covered | Thermo Fisher Scientific, Hologic Inc., Bio-Techne, QIAGEN, Luminex Corporation, Lonza Group, Danaher Corporation, Agilent Technologies, RoosterBio, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Exosome Research Products Market Evolving Landscape
Software-defined analytics bundled with isolation instrumentation is restructuring laboratory procurement patterns, compressing capital equipment replacement cycles while expanding recurring consumable attachment rates. This convergence favors vendors with established chromatography and mass spectrometry installed bases.
Microfluidics-based isolation technology is modularizing exosome purification workflows, replacing room-scale ultracentrifugation footprints with benchtop cartridge systems. Academic cancer centers and startup biotechs in California and Massachusetts are adopting these platforms at accelerated pace. The technology is compressing sample-to-data timelines from days to hours while reducing operator technical skill requirements.
FDA guidance on extracellular vesicle-based therapeutics is tightening quality system expectations for manufacturers seeking clinical-grade designations. The agency now requires expanded characterization data including potency assays and immunophenotyping panels. Exosome therapeutic developers in the United States are responding by building in-house analytical capabilities or securing dedicated CDMO partnerships before IND submission.
Consolidated procurement contracts at academic medical centers are displacing decentralized lab-level purchasing, concentrating vendor negotiations through shared services organizations. Research hospitals in the Texas Medical Center and University of California system are leading this transition, unifying reagent standardization across multiple principal investigator labs. The shift is most visible in oncology and infectious disease departments where biomarker program scale justifies centralized inventory management.
North America Exosome Research Products Market Segmentation
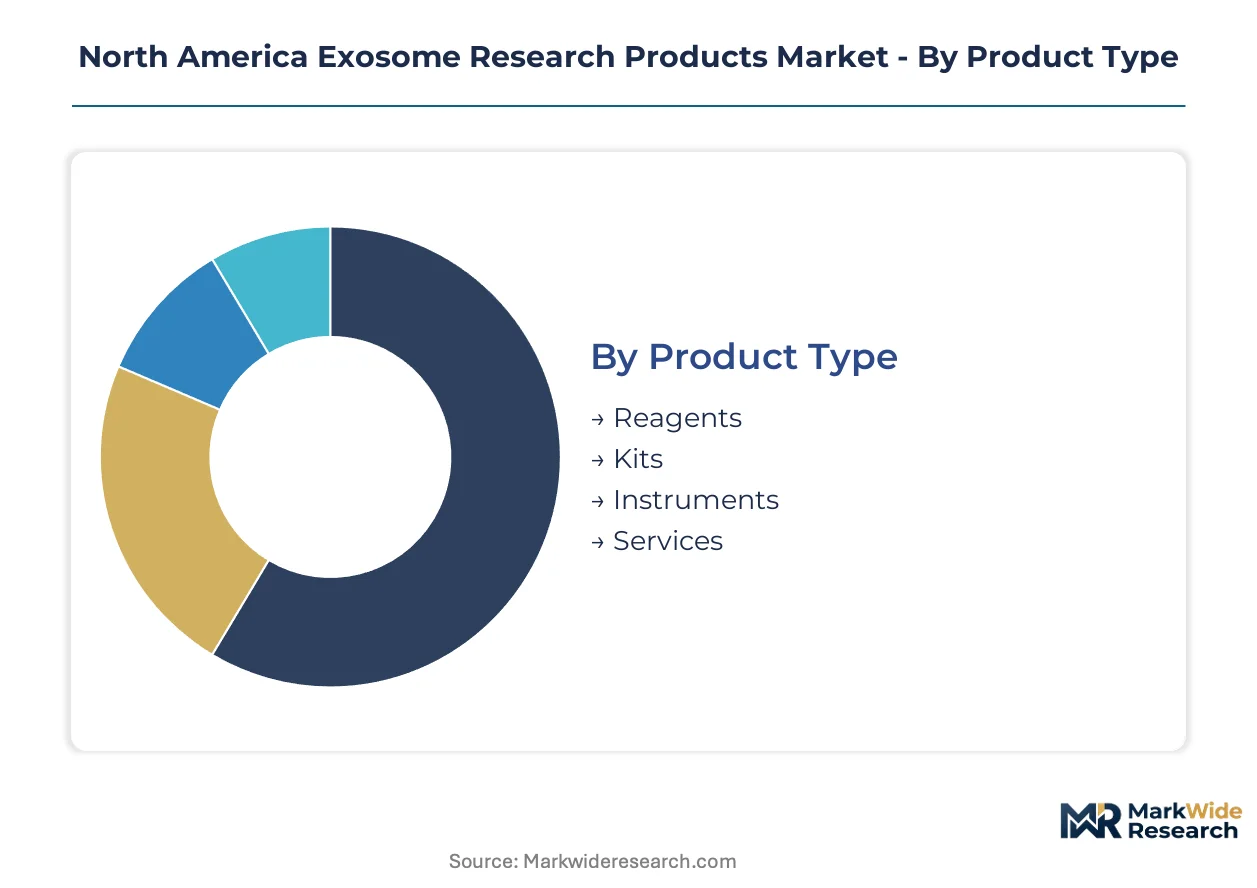
Exosome research products serve distinct technical workflows and institutional purchasing patterns across North America. Segmentation reveals where procurement concentrates and which technology platforms command premium positioning.
Product Type:
Technology specifications determine recurring revenue attachment and capital replacement cycles.
- Reagents:Specialized growth media, exosome-depleted serum formulations, and precipitation reagents constitute the consumable backbone of cell culture workflows. Academic medical centers in the Boston-Cambridge corridor standardize on these formulations to reduce batch-to-batch variability in biomarker studies.
- Kits:Commercial isolation kits bundle optimized buffers, spin columns, and size-exclusion matrices for standardized purification. Pharmaceutical sponsors in California and Massachusetts procurement contracts favor kit-based workflows for IND-enabling studies requiring documented lot traceability.
- Instruments:Ultracentrifugation systems, nanoparticle tracking analyzers, and flow cytometry platforms represent capital-intensive infrastructure investments with 5-7 year replacement cycles.
- Services:Contract manufacturing and analytical testing for GMP-compliant exosome therapeutics concentrate margin pools as sponsors outsource quality release and potency assay development.
Reagents lead on scale; services lead on momentum.
End User:
Customer type shapes pricing power and contract structure.
- Pharmaceutical Companies:Sponsors of exosome therapeutics procure clinical-grade products under quality agreements with audit rights and dedicated supply allocations. FDA guidance on extracellular vesicle-based therapeutics is forcing these buyers to validate vendor quality systems before IND submission.
- Academic Institutions:Universities and medical schools dominate kit and reagent volume through NIH-funded grants prioritizing extracellular vesicle biomarker research. Consolidated procurement contracts at Texas Medical Center and University of California system research hospitals are displacing decentralized lab-level purchasing.
- Research Organizations:Nonprofit institutes and government labs operate under federal acquisition regulations with extended vendor qualification timelines.
- Biotech Firms:Venture-backed startups in the Boston-Cambridge and San Francisco Bay Area clusters demand flexible procurement terms and technical support for platform development.
Academic institutions lead on scale; pharmaceutical companies lead on pricing premium.
Application:
Functional use case determines regulatory pathway and product classification boundaries.
- Diagnostics:Exosome-based liquid biopsy development drives demand for high-purity isolation and standardized characterization panels. Cancer centers across the United States are scaling procurement for early detection programs in oncology and neurology.
- Therapeutics:Engineered exosome drug delivery vectors require GMP manufacturing capabilities and expanded immunophenotyping characterization. FDA distinctions between research-use-only and clinical-grade classifications create compliance friction for developers.
- Drug Delivery:Loading capacity optimization and targeting ligand display pull specialized reagent demand from gene therapy programs.
- Biomarker Discovery:Proteomic and transcriptomic profiling of exosomal cargo supports precision medicine initiatives with less stringent quality requirements than therapeutic applications.
Therapeutics commands the steepest pricing tier; diagnostics shows the fastest volume expansion.
Technology:
Platform architecture determines throughput, purity, and operator skill requirements.
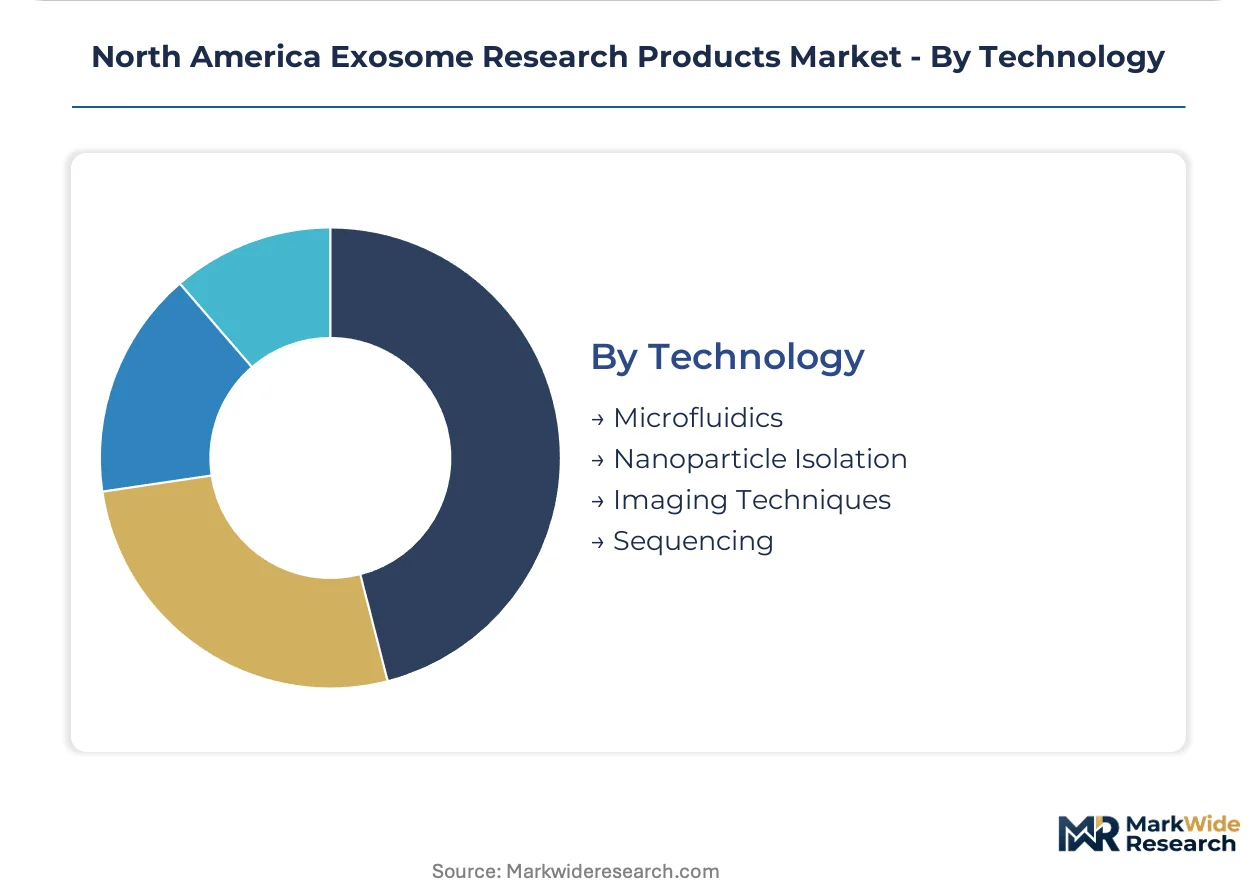
- Microfluidics:Nanofabricated membrane cartridges integrated with automated liquid handling compress sample-to-data timelines from days to hours. Academic cancer centers in California and Massachusetts are adopting these benchtop systems to bypass ultracentrifugation bottlenecks entirely.
- Nanoparticle Isolation:Size-exclusion chromatography and precipitation methods remain the workhorse technologies for routine purification with established protocol libraries.
- Imaging Techniques:Transmission electron microscopy and super-resolution fluorescence systems provide morphological validation for high-impact publications.
- Sequencing:Next-generation and single-molecule platforms for exosomal RNA and DNA profiling require specialized nucleic acid extraction workflows optimized for low-input material.
Nanoparticle isolation leads on installed base; microfluidics leads on adoption velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger procurement volumes than Canada, though Canadian regulatory maturation is accelerating institutional adoption across Toronto and Vancouver research clusters. Both countries operate under distinct but converging frameworks for extracellular vesicle therapeutic development.
United States
NIH grant allocations for extracellular vesicle biomarker research channel federal capital toward academic medical centers purchasing isolation platforms. FDA guidance on extracellular vesicle-based therapeutics mandates expanded characterization data including potency assays and immunophenotyping panels. The Boston-Cambridge corridor concentrates demand density where clustered research hospitals and venture-backed startups drive reagent consumption.
Canada
Health Canada and PMRA guidelines for biological product characterization are maturing, creating regulatory clarity that supports academic hospital procurement. Federal research funding through the Canadian Institutes of Health Research prioritizes exosome biomarker programs in oncology and neurology. Toronto, Montreal, and Vancouver research clusters are scaling kit-based workflows for standardized purification requiring documented lot traceability.
California
Academic cancer centers and startup biotechs are adopting microfluidics-based isolation platforms at accelerated pace to bypass ultracentrifugation bottlenecks. University of California system research hospitals lead consolidated procurement contracts displacing decentralized lab-level purchasing. The San Francisco Bay Area cluster demands flexible procurement terms and technical support for platform development.
Texas
The Texas Medical Center unifies reagent standardization across multiple principal investigator labs through shared services organizations. NIH-funded grants at Houston-area institutions prioritize extracellular vesicle biomarker research in infectious disease and oncology domains. Consolidated procurement contracts concentrate vendor negotiations for oncology and infectious disease departments.
Massachusetts
Venture-backed startups in Greater Boston demand clinical-grade products under quality agreements with audit rights and dedicated supply allocations. FDA distinctions between research-use-only and clinical-grade classifications force developers to validate vendor quality systems before IND submission. The Boston-Cambridge biotech corridor supports specialized distribution infrastructure for recurring consumable demand.
North America Exosome Research Products Market Competitive Landscape
Top-tier vendors anchor the premium instrumentation and GMP services tier, while mid-sized specialists occupy reagent and kit segments with recurring consumable models. The market structure reflects consolidation among chromatography and mass spectrometry platform providers alongside fragmentation in specialized growth media formulations. Three archetypes dominate: diversified life science conglomerates with cross-selling capabilities, pure-play exosome reagent specialists, and contract manufacturing organizations capturing therapeutic development margins. M&A activity targets automated liquid handling capabilities, while strategic partnerships between academic medical centers and vendors secure dedicated supply allocations for biomarker programs.
Among diversified platform providers, Thermo Fisher Scientific and Danaher Corporation exemplify the cross-selling archetype leveraging installed bases in chromatography and mass spectrometry. Bio-Techne occupies a position within the specialized reagent tier, anchoring demand through exosome-depleted serum formulations that reduce experimental variability. QIAGEN sits within the automated nucleic acid extraction segment, competing on platforms optimized for exosomal RNA and DNA profiling.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hologic Inc. |
| Bio-Techne |
| QIAGEN |
| Luminex Corporation |
| Lonza Group |
| Danaher Corporation |
| Agilent Technologies |
| RoosterBio |
| Others |
Value Network & Pricing Analysis
Chromatography resin costs anchor price floors across reagent tiers, flowing from German and Japanese specialty chemical manufacturers through kit assemblers in Massachusetts and California before reaching academic buyers under NIH grant procurement protocols.
Pricing Analysis
Capacity additions in microfluidics cartridge manufacturing are reshaping price floors for benchtop isolation platforms. Three-tier pricing structure across GMP-certified clinical-grade, research-use-only validated, and unvalidated economy levels separates pharmaceutical sponsors from academic grant-funded labs. Price differentiation rests on FDA quality system certification and documented lot traceability. Pricing pressure stems from consolidated procurement contracts at Texas Medical Center and University of California system hospitals. Academic institutions exhibit highest price sensitivity; pharmaceutical sponsors under IND timelines show lowest.
Supply Chain Analysis
Refurbishment flows for ultracentrifugation rotors and nanoparticle tracking analyzers create secondary equipment channels that undercut new-instrument pricing for budget-constrained labs. Manufacturing concentrates in Germany, Japan, and the United States for precision centrifugation systems and chromatography platforms. Raw material dependencies include borosilicate glass, specialized membrane polymers, and fetal bovine serum for exosome-depleted formulations. Single-source vulnerability concentrates in high-performance rotor manufacturing. Distribution runs through specialized life science distributors with field application scientist support for complex instrumentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA guidance on extracellular vesicle-based therapeutics operates as a regulatory compounder, with each guidance revision expanding mandatory characterization data and pulling forward quality system investments from manufacturers seeking clinical-grade designations.
For Market Incumbents: Deploy automated liquid handling integration as the primary lever to compress customer sample-to-data timelines and lock in consumable attachment. Deepen backward integration into chromatography resin manufacturing to defend margin position against German and Japanese specialty chemical suppliers. Counter emerging microfluidics specialists by bundling characterization software with installed base instrumentation. For New Entrants and Emerging Players: Launch via GMP-compliant contract manufacturing services targeting pharmaceutical sponsors before IND submission, where quality agreement structures create high switching costs. Penetrate Canadian academic hospital procurement in Toronto and Vancouver research clusters where Health Canada regulatory maturation is accelerating kit adoption. White-space exists in exosome-depleted serum formulations with documented traceability for reproducible cell culture workflows. For Investors and Strategic Acquirers: Consolidation pressure builds where automated nucleic acid extraction platforms overlap with exosomal RNA profiling demand, creating capability gaps for mid-sized reagent specialists. Five-to-ten year viability favors vendors with chromatography installed bases cross-selling exosome characterization workflows. Acquisition target archetype: microfluidics cartridge developers with FDA master file documentation. Monitor FDA draft guidance publication timing as inflection signal for clinical-grade product validation spending.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Enables pharmaceutical sponsors to meet FDA potency assay requirements before IND submission. |
| Software-Defined Analytics Integration | Thermo Fisher Scientific leverages chromatography installed base to cross-sell exosome characterization workflows. |
| Automated Liquid Handling Partnership | QIAGEN competes on platforms optimized for exosomal RNA profiling with reduced operator skill requirements. |
| Regulatory Approval Pathway Investment | Bio-Techne anchors position through exosome-depleted serum formulations reducing experimental variability. |
| Academic Medical Center Consolidated Contract | Texas Medical Center unifies reagent standardization across multiple principal investigator labs. |
Research Methodology
Multiple input streams — primary interviews with exosome therapeutic development executives, regulatory affairs leads at FDA-registered manufacturers, academic medical center procurement managers, and NIH program officers — were reconciled against secondary validation from FDA guidance documents, ClinicalTrials.gov exosome trial registrations, NIH RePORTER grant databases, and SEC 10-K filings from diversified life science conglomerates. Bottom-up kit and reagent volume estimates were triangulated against top-down market sizing from capital equipment replacement cycles and services contract values.
Historical shipment data from chromatography and mass spectrometry platform providers were cross-referenced against expert panel inputs on microfluidics adoption velocity across the projection horizon. Segmentation modeling incorporated product type, end user archetype, application domain, and technology platform architecture dimensions. CAGRs were derived from regression analysis of NIH funding allocation trends and pharmaceutical sponsor pipeline advancement rates. Industry-specific forecast inputs included extracellular vesicle therapeutic IND submission trajectories and Health Canada regulatory guidance maturation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance revision timing and ultracentrifugation equipment import disruption scenarios. Forecasts reflect documented assumptions regarding grant funding continuity and clinical-grade product classification boundary stability. Practitioners should monitor FDA draft guidance publication schedules and German centrifugation manufacturer order backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Global Organoids Market
Biomedical Technology
BOD Incubator Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Drug Delivery Technology Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Glycomics Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Liquid Biopsy Market