
 DNA Synthesis Market | 2026-2036
DNA Synthesis Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Synthesis Market Intelligence
ISO 13485 certification for in vitro diagnostic raw materials is redrawing supplier eligibility across the DNA synthesis value chain. Twist Bioscience leverages silicon-based DNA writing to sustain cost leadership in high-throughput oligonucleotide production. Thermo Fisher Scientific anchors the market through backward integration into reagent supply and instrument platforms. GenScript competes on geographic proximity to Asia-Pacific biotech clusters with specialized gene synthesis services.
DNA synthesis denotes the enzymatic or chemical assembly of nucleic acid polymers from individual nucleotides, with phosphoramidite chemistry historically dominating through iterative deprotection, coupling, capping, and oxidation cycles on solid supports. The process enables programmable genetic sequences for therapeutic vectors, diagnostic primers, and engineered biological systems. Oligonucleotides occupy the largest revenue pool due to CRISPR guide RNA and qPCR probe consumption, while gene synthesis segments register the fastest structural expansion as pharmaceutical companies outsource increasingly complex therapeutic transgene construction. Solid-phase synthesis retains manufacturing dominance, though enzymatic platforms are capturing early commercial traction through reduced hazardous waste profiles and longer read lengths.
FDA oversight of gene therapy investigational new drug applications shapes product quality specifications for clinical-grade DNA materials, while EPA regulations govern phosphoramidite reagent disposal from high-volume synthesis facilities. ISO standards for medical device raw materials further constrain supplier qualification pathways in diagnostic applications. Stakeholders must monitor enzymatic synthesis scale-up economics and evolving regulatory distinctions between research-use and clinical-grade DNA products.
Market Dynamics
Enzymatic DNA synthesis is bifurcating the manufacturing base, splitting capacity between legacy phosphoramidite infrastructure and next-generation biologically-driven platforms that promise longer read lengths and reduced hazardous waste profiles.
Growth Catalysts
- NIH funding expansion:Sustained federal research budgets in the United States pull through demand for synthetic oligonucleotides across academic and commercial gene therapy pipelines.
- Gene therapy commercialization:Pharmaceutical companies now outsource complex therapeutic transgene construction, accelerating structural expansion in the gene synthesis segment.
- Silicon-based DNA writing:Semiconductor-derived fabrication methods compress per-base synthesis costs, enabling high-throughput production economies previously unattainable with traditional column chemistry.
Market Restraints
- Phosphoramidite reagent volatility:Input costs for acetonitrile and controlled-pore glass solid supports fluctuate with specialty chemical supply chains concentrated in Germany and China.
- EPA disposal compliance:Hazardous waste regulations governing organic solvent recovery from high-volume synthesis facilities add operational overhead to legacy manufacturing footprints.
- Read-length limitations:Solid-phase chemistry caps practical synthesis length below 200 bases for complex sequences, constraining applications requiring full gene constructs.
Strategic Opportunities
- India biotech cluster proximity:Contract research organizations in Hyderabad and Bengaluru seek localized gene synthesis partners to reduce turnaround times for CRISPR screening campaigns.
- ISO 13485 diagnostic certification:Medical device raw material standards create supplier qualification barriers that favor early certifiers in the in vitro diagnostic oligonucleotide channel.
- Enzymatic-CRISPR convergence:Template-free DNA synthesis combined with guide RNA production enables integrated cell engineering workflows for cell therapy developers.
Industry Challenges
- Bioinformatics talent scarcity:Sequence optimization and error-correction algorithm development require computational biology expertise that outpaces current training pipeline output.
- Clinical-grade validation timelines:FDA investigational new drug application requirements for GMP DNA materials extend supplier qualification cycles by 18-24 months versus research-use specifications.
- Instrument-platform lock-in:Synthesis hardware from established vendors creates switching friction for customers seeking to migrate toward enzymatic alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Synthesis Market |
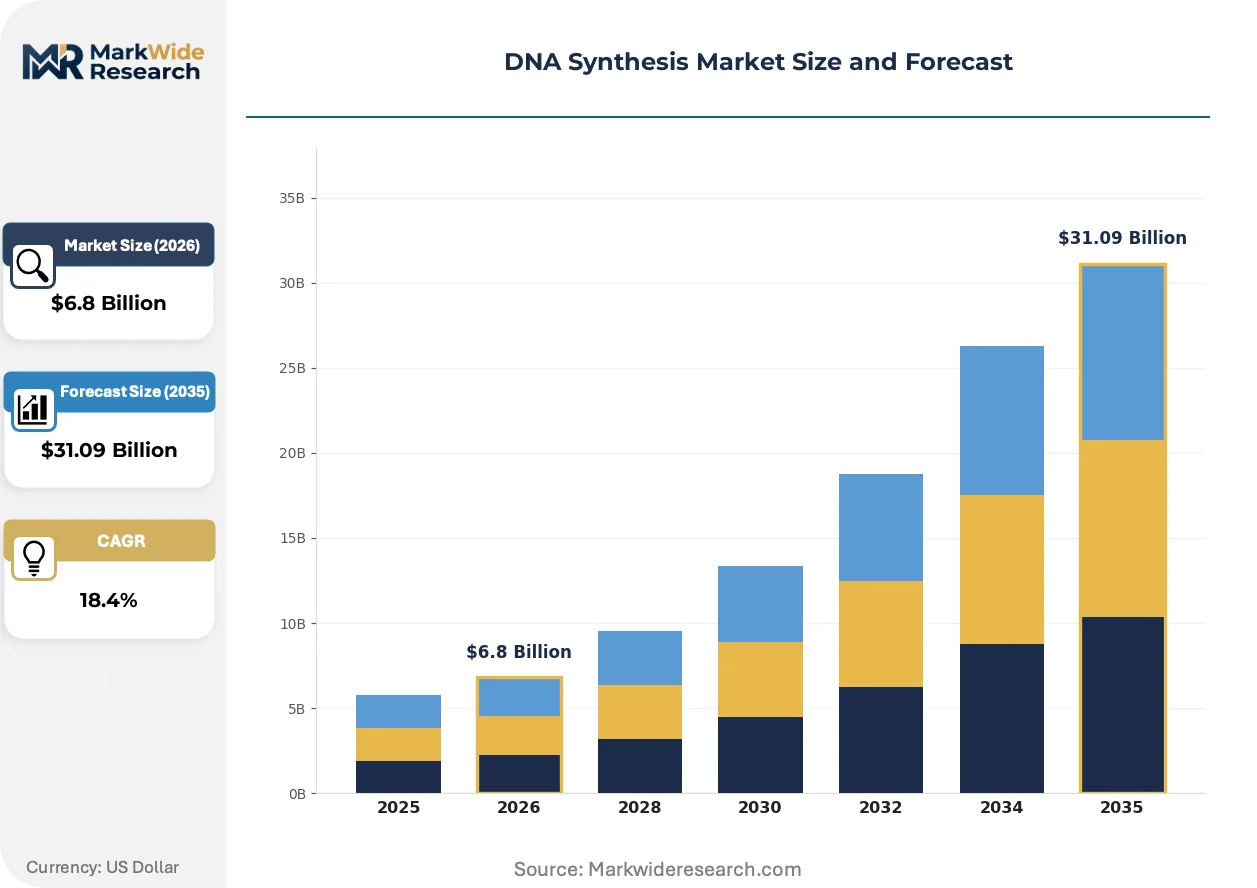
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oligonucleotides, Genes, cDNA, Plasmids Technology: PCR, Solid-Phase Synthesis, Liquid Handling, Microarray Application: Gene Therapy, Synthetic Biology, Diagnostics, Research End User: Academia, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Integrated DNA Technologies, Inc., Twist Bioscience, GenScript, Eurofins Scientific, Azenta, Inc., LGC Limited, DNA Script, Telesis Bio Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Synthesis Market Strategic Shifts & Innovations
Active transformation across DNA synthesis stems from manufacturing technology divergence, regulatory recalibration for clinical-grade materials, and procurement consolidation among pharmaceutical buyers seeking vertically integrated supply security.
Enzymatic DNA synthesis platforms leverage terminal deoxynucleotidyl transferase and engineered polymerases to assemble sequences without iterative deprotection cycles. Cell therapy developers and synthetic biology startups adopt these systems for rapid prototyping of genetic circuits. The technology is bifurcating the supplier landscape, separating capital-heavy incumbents with installed phosphoramidite bases from nimble entrants scaling biological production.
EMA's evolving guidance on genetically modified organism-derived starting materials reshapes documentation requirements for European gene therapy sponsors. Manufacturers must now trace enzyme origins and demonstrate absence of adventitious agents through extended qualification protocols. Germany and Switzerland-based synthesis providers invest in dedicated GMP suites to capture clinical-grade contracts from EU pharmaceutical clients.
Pharmaceutical procurement teams consolidate vendor panels from twelve-plus suppliers to three-to-four strategic partners with full regulatory dossiers. This concentration rewards synthesis houses with backward integration into reagent supply and quality control infrastructure. The United States exhibits the most pronounced consolidation, where gene therapy developers prioritize FDA-audited facilities over cost-optimized alternatives.
DNA Synthesis Market Segmentation
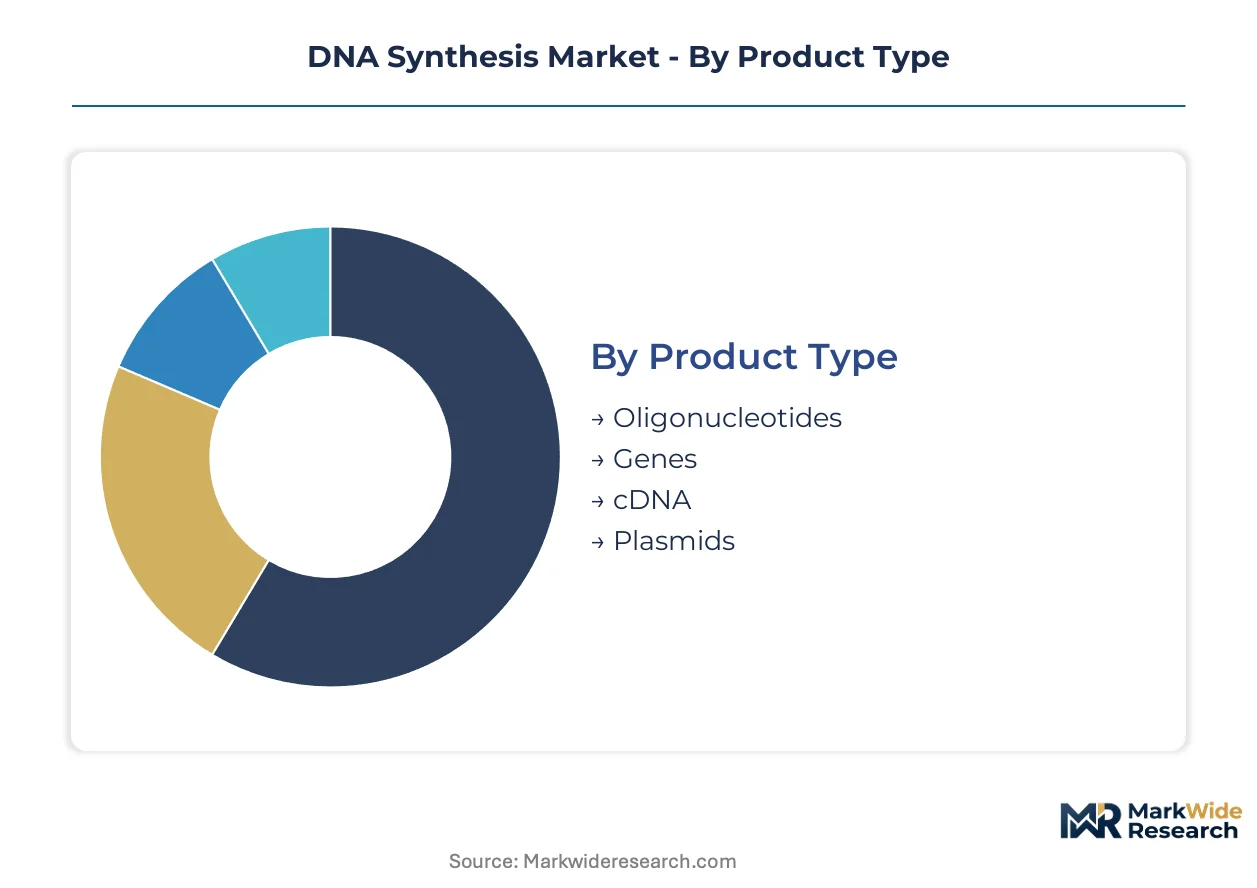
DNA synthesis segmentation reflects divergent manufacturing economics across product formats and the regulatory distance between research-grade and clinical-grade supply chains. Technology choices determine capital intensity and waste profiles, while end-user concentration shapes geographic demand patterns.
Product Type:
Oligonucleotides dominate export flows to European and Asian diagnostic manufacturers, while gene synthesis services concentrate domestically around NIH-funded academic clusters and pharmaceutical R&D campuses.
- Oligonucleotides:Short synthetic sequences (15-200 bases) produced via solid-phase chemistry for PCR primers, CRISPR guide RNAs, and antisense therapeutics. Demand clusters in the United States around qPCR diagnostic manufacturers and gene therapy developers sourcing GMP-grade materials for IND submissions.
- Genes:Full-length coding sequences assembled from oligonucleotide building blocks through overlap extension or enzymatic methods. Pharmaceutical companies in Boston and San Francisco outsource increasingly complex therapeutic transgene construction, accelerating structural expansion in this segment.
- cDNA:Complementary DNA synthesized from mRNA templates for expression studies and protein production workflows. Academic core facilities in the United States represent the primary domestic channel.
- Plasmids:Circular DNA vectors propagated in bacterial hosts for gene therapy manufacturing and vaccine development. Clinical-grade plasmid supply concentrates in FDA-audited facilities serving cell therapy sponsors.
Oligonucleotides hold the largest share; momentum sits with genes.
Technology:
Cost tiers separate legacy phosphoramidite infrastructure from emerging enzymatic platforms, with microarray-based methods occupying a mid-tier position for high-complexity screening applications.
- PCR:Enzymatic amplification of existing DNA templates rather than de novo synthesis, serving as an enabling technology for downstream cloning and sequencing workflows. Research laboratories and diagnostic manufacturers in the United States deploy high-throughput PCR for template preparation prior to gene assembly.
- Solid-Phase Synthesis:Iterative phosphoramidite chemistry on controlled-pore glass or polystyrene supports, dominating oligonucleotide manufacturing through sub-dollar per-base economics at scale. EPA hazardous waste regulations elevate operational costs for high-volume facilities concentrated in Massachusetts and California.
- Liquid Handling:Automated pipetting robotics for parallel synthesis reactions and reagent dispensing, reducing labor costs in service laboratories. Contract research organizations in Hyderabad and Bengaluru leverage localized liquid handling infrastructure for CRISPR screening campaigns.
- Microarray:Semiconductor-derived fabrication enabling simultaneous synthesis of thousands to millions of sequences on silicon substrates. Twist Bioscience deploys this technology for high-complexity oligo pools supporting synthetic biology and next-generation sequencing applications.
Solid-phase synthesis retains volume leadership; microarray methods are gaining share fastest.
Application:
Customer maturity stratifies demand, with gene therapy sponsors requiring GMP compliance and synthetic biology startups prioritizing turnaround speed over documentation depth.
- Gene Therapy:Synthetic DNA for viral vector construction, regulatory T-cell engineering, and in vivo gene editing. FDA IND application requirements extend supplier qualification timelines, concentrating demand among pharmaceutical companies with audited manufacturing partnerships.
- Synthetic Biology:Programmable genetic circuits and metabolic pathway construction for industrial biotechnology. Startups in the San Francisco Bay Area and Boston pursue rapid prototyping cycles that favor enzymatic synthesis platforms with reduced hazardous waste profiles.
- Diagnostics:PCR primers, FISH probes, and CRISPR-based detection reagents for infectious disease and oncology testing. ISO 13485 certification for in vitro diagnostic raw materials is redrawing supplier eligibility across this channel.
- Research:Cloning vectors, sequencing adapters, and mutagenesis libraries for academic and government laboratories. NIH funding expansion sustains baseline demand across the United States.
Research commands the largest volume; gene therapy shows the steepest expansion trajectory.
End User:
Procurement consolidation distinguishes pharmaceutical buyers seeking supply security from academic purchasers optimizing per-reaction costs.
- Academia:University core facilities and government research laboratories with fragmented purchasing patterns and price-sensitive procurement. NIH-funded investigators at institutions like Stanford, MIT, and the Broad Institute constitute the domestic demand base.
- Pharmaceutical Companies:Integrated drug developers outsourcing therapeutic transgene construction and GMP plasmid manufacturing. These buyers consolidate vendor panels from twelve-plus suppliers to three-to-four strategic partners with full regulatory dossiers.
- Biotechnology Firms:Venture-backed startups and mid-cap developers in cell therapy, gene editing, and synthetic biology. Synthetic biology startups in South San Francisco and Cambridge favor rapid-turnaround gene synthesis services over lowest-unit-cost alternatives.
- Contract Research Organizations:Service providers managing outsourced R&D for pharmaceutical and agricultural biotechnology clients. CROs in India seek localized synthesis partners to reduce turnaround times for CRISPR screening campaigns.
Academia retains the broadest installed base; pharmaceutical companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal research budgets and gene therapy commercialization incentives are redrawing geographic demand patterns. NIH funding expansion in the United States, EMA regulatory clarity in Europe, and biotech cluster formation in Asia-Pacific are concentrating synthesis capacity in specific metropolitan corridors.
United States
NIH funding expansion sustains the world's largest synthetic oligonucleotide procurement base across academic and commercial gene therapy pipelines. FDA investigational new drug application requirements for GMP DNA materials extend supplier qualification timelines, concentrating demand among audited manufacturing partnerships. Boston and San Francisco anchor therapeutic transgene construction outsourcing, while Research Triangle Park hosts phosphoramidite reagent production facilities.
Germany
Specialty chemical supply chains for acetonitrile and controlled-pore glass solid supports concentrate manufacturing infrastructure in the Rhine-Ruhr industrial corridor. ECHA REACH compliance protocols govern phosphoramidite reagent registration and hazard classification across European synthesis operations. Heidelberg and Munich biotech clusters source clinical-grade materials from domestic GMP suites certified for EU pharmaceutical clients.
Switzerland
Gene therapy sponsors leverage Swissmedic's streamlined genetically modified organism-derived starting material guidance to accelerate therapeutic vector development timelines. The country's central bank stability and intellectual property framework attract contract manufacturing organizations serving EU and US pharmaceutical markets. Basel and Zurich host synthesis providers investing in dedicated GMP capacity for cell therapy developers.
China
NMPA evolving standards for gene therapy products are driving domestic investment in clinical-grade plasmid and viral vector manufacturing infrastructure. MIIT industrial biotechnology initiatives support enzymatic synthesis platform development through state-funded research consortia. Shanghai and Suzhou biotech parks attract multinational synthesis providers seeking proximity to domestic pharmaceutical R&D campuses.
India
CDSCO regulatory harmonization with ICH guidelines is enabling contract research organizations to source localized gene synthesis for CRISPR screening campaigns. PLI scheme biotechnology manufacturing incentives support capital investment in automated liquid handling infrastructure. Hyderabad and Bengaluru clusters seek reduced turnaround times through regional synthesis partnerships rather than US or European suppliers.
DNA Synthesis Market Key Industry Players
Listed leaders compete with private specialists across technology platforms and regulatory certification tiers. The supplier base splits between capital-heavy incumbents with installed phosphoramidite infrastructure and nimble entrants scaling enzymatic production. Three archetypes dominate: silicon-based high-throughput producers, GMP-certified clinical-grade specialists, and geographic proximity-focused service laboratories. Capacity expansion and backward integration into reagent supply represent the dominant competitive moves as pharmaceutical buyers consolidate vendor panels.
Within the listed-leader tier, Thermo Fisher Scientific Inc. anchors the market through reagent supply and instrument platform integration. Twist Bioscience exemplifies silicon-based DNA writing scale economics. GenScript occupies a position serving Asia-Pacific biotech clusters with specialized gene synthesis services. These three represent distinct strategic archetypes rather than direct substitutes for buyer procurement teams.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Integrated DNA Technologies, Inc. |
| Twist Bioscience |
| GenScript |
| Eurofins Scientific |
| Azenta, Inc. |
| LGC Limited |
| DNA Script |
| Telesis Bio Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between pharmaceutical sponsors and GMP-certified synthesis providers lock in multi-year supply access while stabilizing per-base pricing visibility against acetonitrile and controlled-pore glass volatility. These contractual structures concentrate procurement power among FDA-audited facilities, compressing margins for research-grade suppliers competing on spot-market terms.
Pricing Analysis
Certification level creates the primary spread between research-use and clinical-grade DNA materials, with ISO 13485 and FDA IND-compliant production commanding substantial premiums over standard oligonucleotide synthesis. Three-tier pricing structure across premium GMP, certified diagnostic-grade, and economy research-use levels stratifies the market, with enzymatic platform entrants applying cost compression in the mid-tier through reduced hazardous waste disposal burdens. Pharmaceutical companies exhibit lowest price sensitivity due to IND timeline risks, while academic core facilities prioritize per-reaction cost minimization.
Supply Chain Analysis
Specialty chemical production in Germany and China anchors global phosphoramidite reagent supply, with acetonitrile purification and controlled-pore glass manufacturing concentrated in the Rhine-Ruhr corridor and Jiangsu province. Synthesis operations draw from these dual-source inputs while facing single-source vulnerability in semiconductor-derived silicon substrates for microarray-based DNA writing. Distribution runs through direct pharmaceutical partnerships for clinical-grade materials and distributor networks serving fragmented academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy commercialization represents an early-cycle expansion story, with therapeutic transgene outsourcing accelerating as FDA approvals validate synthetic DNA supply chains for clinical application.
For Market Incumbents: Compound defensive positioning through backward integration into phosphoramidite reagent manufacturing and accelerated enzymatic platform deployment to neutralize emerging biologically-driven entrants. Prioritize GMP capacity expansion in FDA-audited facilities to capture pharmaceutical vendor consolidation, while maintaining research-grade cost leadership against silicon-based high-throughput competitors. For New Entrants and Emerging Players: Anchor in enzymatic synthesis technology to exploit read-length advantages and waste-profile differentiation against legacy phosphoramidite infrastructure. Target synthetic biology startups in Boston and San Francisco prioritizing rapid prototyping cycles, with a go-to-market angle emphasizing template-free DNA production integrated with CRISPR guide RNA workflows. For Investors and Strategic Acquirers: Capital is best deployed toward GMP-certified synthesis specialists with established FDA audit histories and pharmaceutical customer concentration, as clinical-grade validation timelines create durable competitive moats. Long-term viability favors facilities with backward integration into reagent supply and quality control infrastructure; the signal to watch is enzymatic platform scale-up economics achieving cost parity with solid-phase chemistry at commercial volumes.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Suite Certification | FDA IND compliance extends supplier qualification cycles, concentrating demand among early certifiers. |
| Enzymatic Platform Scale-Up | Terminal deoxynucleotidyl transferase systems promise longer read lengths with reduced EPA disposal overhead. |
| Backward Reagent Integration | In-house phosphoramidite production insulates margin structures from German and Chinese supply volatility. |
| Silicon-Based DNA Writing | Semiconductor fabrication methods compress per-base costs for high-complexity oligo pool applications. |
| Diagnostic Channel Certification | ISO 13485 qualification redraws supplier eligibility for in vitro diagnostic raw material procurement. |
Research Approach
Operator-level perspectives from gene therapy development executives, regulatory affairs leads at pharmaceutical sponsors, GMP facility quality directors, and academic core facility managers anchored the qualitative base for this study. Primary interview findings were cross-validated against FDA IND filing databases, NIH funding disbursement records, EMA genetically modified organism guidance documents, and EPA hazardous waste reporting systems. Bottom-up synthesis capacity estimates triangulated with top-down pharmaceutical R&D spending allocations across the analysis window.
Sensitivity analysis tested forecast robustness across enzymatic platform adoption rates, phosphoramidite reagent price volatility bands, and gene therapy pipeline progression scenarios. Segmentation modeling incorporated product type, technology platform, application area, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from volume-demand build-ups tied to NIH funding trajectories and pharmaceutical outsourcing penetration curves, with cross-referencing to clinical-grade plasmid and viral vector manufacturing capacity expansion plans.
Underlying assumptions cover sustained NIH budget allocation, FDA gene therapy approval momentum, and phosphoramidite chemistry cost structures, with deviation risk concentrated in enzymatic synthesis scale-up economics and EMA regulatory guidance evolution. Practitioners should keep alternative scenarios live as pharmaceutical procurement consolidation patterns and enzymatic platform commercial traction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Middle East and Africa Exosome Research Products Market
Biomedical Technology
Macrophage Marker Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Life Science Analytics Market