
 America Cell Counting Market | 2026-2036
America Cell Counting Market Size, Share, and Industry Trends Forecast 2026-2036
America Cell Counting Market Outlook
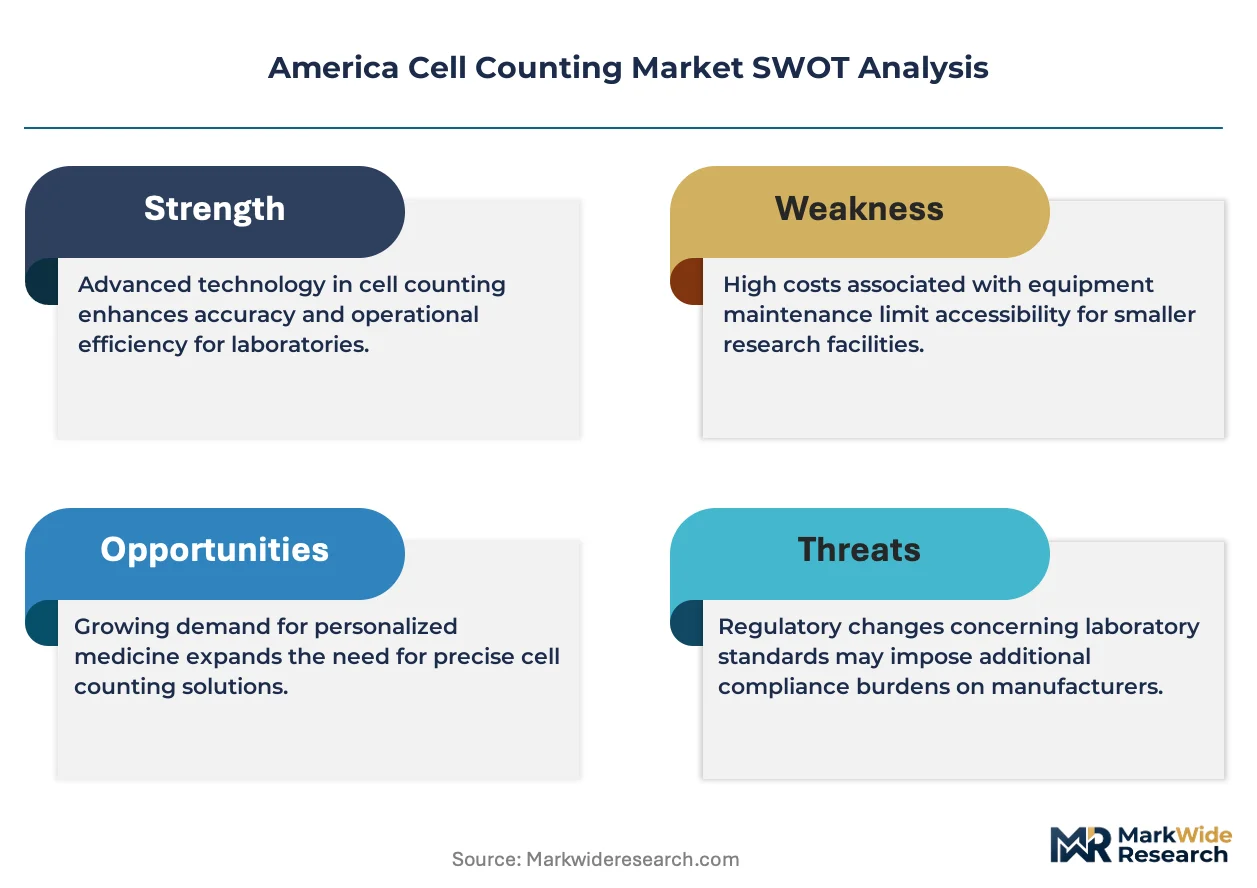
Biopharmaceutical manufacturers are bifurcating from academic research laboratories as the dominant procurement archetype in the America Cell Counting Market. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to anchor high-throughput screening workflows across North American contract development organizations. Danaher Corporation sustains competitive intensity through Beckman Coulter's specialized position in clinical diagnostics automation, while Bio-Rad Laboratories differentiates via fluorescence detection architectures for cell biology research.
Cell counting encompasses quantitative enumeration of viable and non-viable cells using optical, electrical, or image-based detection methods, typically resolving concentrations from 10^4 to 10^7 cells per milliliter with CVs below 5% for automated platforms. Automated cell counters dominate capital expenditure flows due to 21 CFR Part 11 compliance requirements in pharmaceutical quality control, while flow cytometers command premium positioning in cancer research applications requiring multiparametric immunophenotyping. Image-based cell counters represent the fastest-expanding technology segment as artificial vision algorithms displace manual hemocytometer workflows in stem cell biology laboratories.
FDA process analytical technology initiatives and EPA hazardous waste disposal standards for fluorescent reagents shape instrument design requirements and consumables formulations across the Americas. ISO 13485 quality management systems govern manufacturing protocols for clinical diagnostic cell counters distributed in the United States and Canada. Stakeholders must monitor evolving NIST reference material certifications for cell concentration standards that will determine next-generation platform calibration requirements.
Market Dynamics
FDA process analytical technology mandates are compressing manual hemocytometer workflows into automated fluorescence platforms across North American biopharmaceutical quality control laboratories. This regulatory pressure is accelerating capital redeployment toward 21 CFR Part 11-compliant systems.
Growth Catalysts
- Process Analytical Technology (PAT) Framework:FDA guidelines for real-time quality monitoring are compelling biopharmaceutical manufacturers to deploy automated cell counters with integrated data integrity architectures.
- Stem Cell Biology Laboratories:Academic and commercial regenerative medicine research facilities in California and Massachusetts are replacing manual counting with image-based platforms featuring artificial vision algorithms.
- Fluorescence Detection Architectures:Multiparametric immunophenotyping requirements in cancer immunotherapy development are concentrating demand for flow cytometry systems with expanded laser configurations.
Market Restraints
- Fluorescent Reagent Disposal Costs:EPA hazardous waste standards for ethidium bromide and proprietary nucleic acid stains impose recurring operational burdens on high-throughput screening facilities.
- Optical Component Supply Concentration:Precision laser diodes and high-sensitivity photomultiplier tubes rely on concentrated Asian manufacturing bases, exposing lead time vulnerabilities.
- CV Floor in Low-Concentration Samples:Automated platforms struggle to maintain coefficient of variation below 5% at concentrations below 10^4 cells per milliliter without extended acquisition times.
Strategic Opportunities
- Point-of-Care Diagnostics Expansion:Portable impedance-based cell counters for rapid CD4+ T-cell enumeration present unpenetrated deployment potential in rural American clinical settings.
- CAR-T Manufacturing Workflows:Cell therapy production facilities require closed-system cell counting modules compatible with isolator technology and single-use fluid paths.
- NIST Reference Material Certification:Emerging calibration standards for cell concentration traceability will create first-mover advantages for platforms with embedded metrology validation protocols.
Industry Challenges
- Image Analysis Specialist Scarcity:Deployment of artificial vision cell counters requires laboratory personnel trained in algorithm parameter optimization and artifact recognition.
- Legacy LIMS Integration Complexity:Automated cell counters must interface with established laboratory information management systems through custom API development and validation protocols.
- ISO 13485 Certification Timeline:Clinical diagnostic instrument manufacturers face extended quality management system audit cycles before commercial distribution authorization in the United States and Canada.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Cell Counting Market |
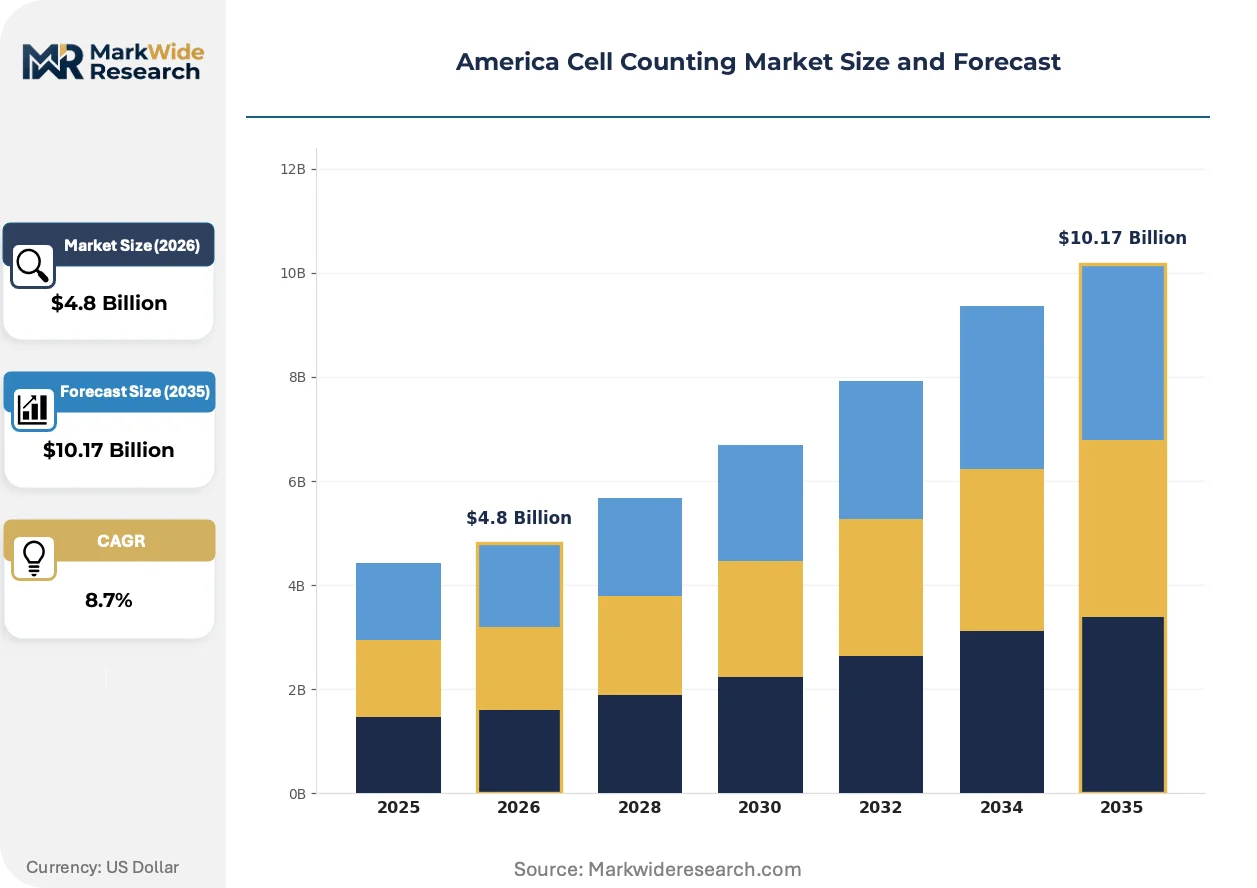
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemocytometers, Automated Cell Counters, Flow Cytometers, Image-Based Cell Counters End User: Research Laboratories, Hospitals, Diagnostic Centers, Pharmaceutical Companies Technology: Fluorescence, Bright Field, Digital Imaging, Laser Scattering Application: Cancer Research, Stem Cell Biology, Immunology, Clinical Diagnostics |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Becton Dickinson, Beckman Coulter, Bio-Rad Laboratories, Merck KGaA, Agilent Technologies, PerkinElmer, Sysmex Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Cell Counting Market Strategic Shifts
Artificial vision algorithms are compressing the analytical workflow in cell biology laboratories, displacing manual hemocytometer methods that have dominated quantitative cell enumeration for decades. Three distinct forces are reshaping instrument architecture and procurement patterns across the Americas.
Deep learning-based image analysis is displacing threshold-based cell detection in automated counters, enabling accurate enumeration of irregular morphologies and clustered cell populations. Contract development organizations in the Boston-Cambridge corridor are adopting these platforms for high-throughput antibody discovery workflows. The technology is displacing fluorescence-based methods in applications where label-free operation preserves cell viability for downstream functional assays.
FDA guidance on analytical procedures and methods validation is tightening data integrity requirements for cell counting in regulated pharmaceutical manufacturing. Biopharmaceutical quality control departments must now implement audit trails and electronic signature workflows that manual platforms cannot support. This regulatory compression is accelerating replacement cycles for legacy Coulter counter installations in New Jersey and North Carolina manufacturing hubs.
Service unbundling is fragmenting traditional instrument-reagent bundling models as third-party reagent manufacturers achieve compatibility certification for major automated platforms. Academic core facilities and mid-sized biotechnology companies are purchasing instruments and sourcing consumables through separate procurement channels. This purchasing pattern is most pronounced in California life science clusters where capital budget constraints favor operational expenditure flexibility.
America Cell Counting Market Segmentation
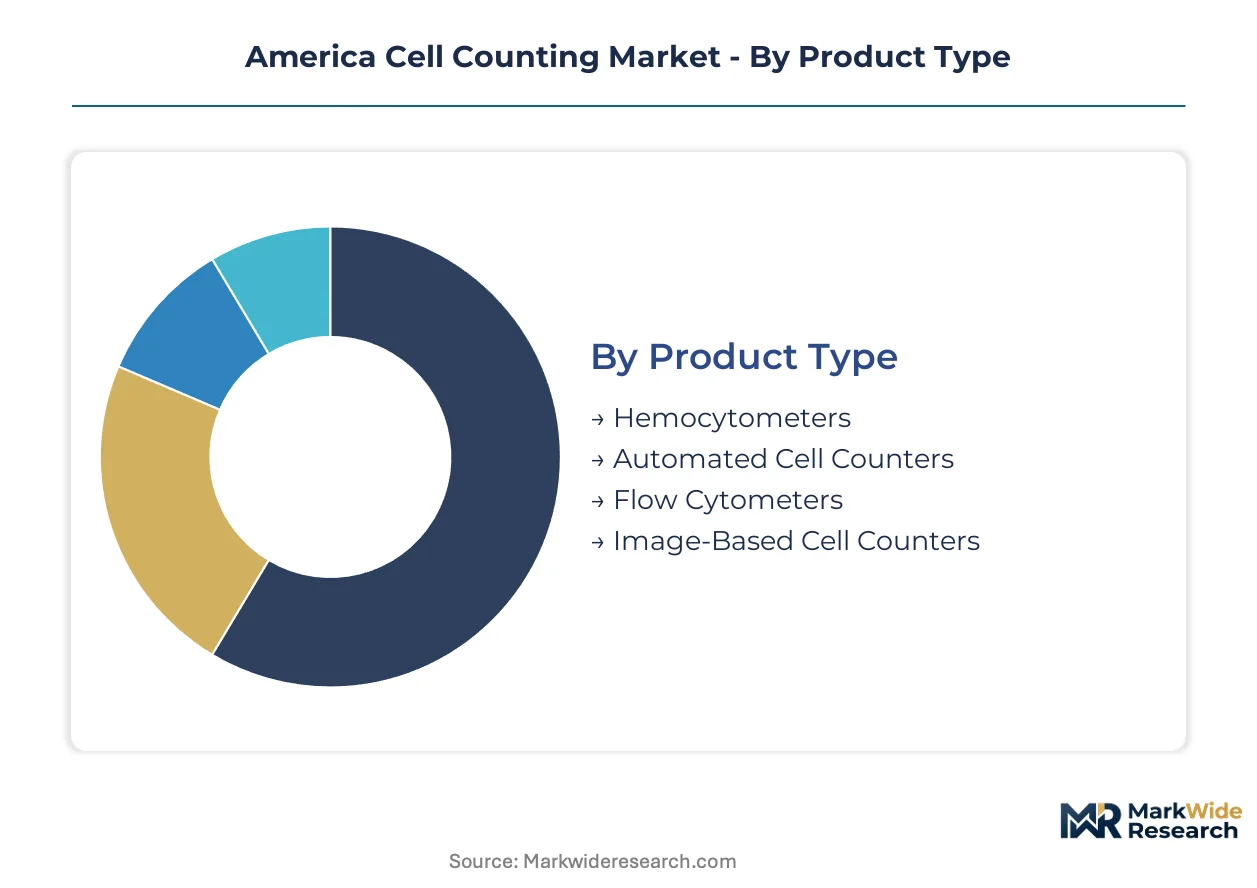
Cell counting instrumentation fragments across four distinct product architectures, each commanding differentiated margin pools based on regulatory compliance burden and throughput specifications. Procurement patterns bifurcate sharply between regulated pharmaceutical manufacturing and academic research environments, reshaping vendor pricing power across the Americas.
Product Type:
Margin pools concentrate in automated platforms where 21 CFR Part 11 compliance architectures command 40-60% price premiums over research-grade equivalents.
- Automated Cell Counters:These systems integrate impedance-based detection with automated sample handling, achieving CVs below 5% across 10^4 to 10^7 cells per milliliter concentration ranges. Biopharmaceutical quality control laboratories in New Jersey and North Carolina manufacturing hubs are replacing legacy Coulter counters to satisfy FDA process analytical technology mandates for real-time release testing.
- Flow Cytometers:Multiparametric platforms employing expanded laser configurations enable simultaneous immunophenotyping of 8-12 cellular markers. Cancer immunotherapy developers in the Boston-Cambridge corridor concentrate procurement of these systems for CAR-T cell characterization workflows, where fluorescence detection sensitivity directly correlates with therapeutic potency assessment reliability.
- Hemocytometers:Manual counting chambers with Neubauer ruling patterns persist in resource-constrained academic settings despite throughput limitations of 50-100 samples per day.
- Image-Based Cell Counters:Artificial vision algorithms now resolve irregular morphologies and clustered populations without fluorescent labels, preserving cell viability for downstream functional assays.
The dominant share belongs to automated cell counters, while image-based platforms are gaining share fastest as deep learning displaces threshold-based detection methods.
End User:
Procurement authority has shifted toward integrated biopharmaceutical manufacturing organizations with capital budgets exceeding $500K for single-platform deployments.
- Pharmaceutical Companies:Quality control departments within FDA-regulated manufacturing facilities require closed-system architectures compatible with isolator technology and single-use fluid paths. Cell therapy production workflows demand continuous in-process monitoring that manual methods cannot support, driving replacement cycles of 5-7 years for legacy installations.
- Research Laboratories:Academic core facilities prioritize operational expenditure flexibility over capital intensity, unbundling instrument and reagent procurement to manage constrained budgets. California and Massachusetts life science clusters exhibit pronounced preference for third-party reagent compatibility across multiple platform vendors.
- Hospitals:Clinical diagnostic laboratories face ISO 13485 certification timelines extending commercial distribution authorization for new platform installations.
- Diagnostic Centers:Point-of-care settings present unpenetrated potential for portable impedance-based CD4+ T-cell enumeration in rural American clinical environments.
Pharmaceutical companies command the largest procurement volume, though research laboratories are expanding most quickly as regenerative medicine funding accelerates.
Technology:
Detection modality selection directly determines consumables revenue streams and service contract attach rates across the installed base.
- Fluorescence:Laser-excited fluorophore detection enables multiparametric immunophenotyping with sensitivity to 100 molecules per cell. EPA hazardous waste disposal standards for ethidium bromide and proprietary nucleic acid stains impose recurring operational burdens that reagent manufacturers are addressing through biodegradable formulation development.
- Digital Imaging:CMOS sensor arrays coupled with convolutional neural networks achieve enumeration accuracy matching fluorescence methods without phototoxicity or label interference. Stem cell biology laboratories are adopting these platforms where downstream differentiation protocols require intact cellular machinery.
- Bright Field:Transmitted light microscopy with trypan blue exclusion remains the lowest-cost viability assessment method for high-volume screening applications.
- Laser Scattering:Forward and side scatter detection provides rapid size and granularity discrimination for heterogeneous population analysis in hematology workflows.
Fluorescence retains the dominant technology position, while digital imaging is climbing the fastest as artificial vision algorithms mature.
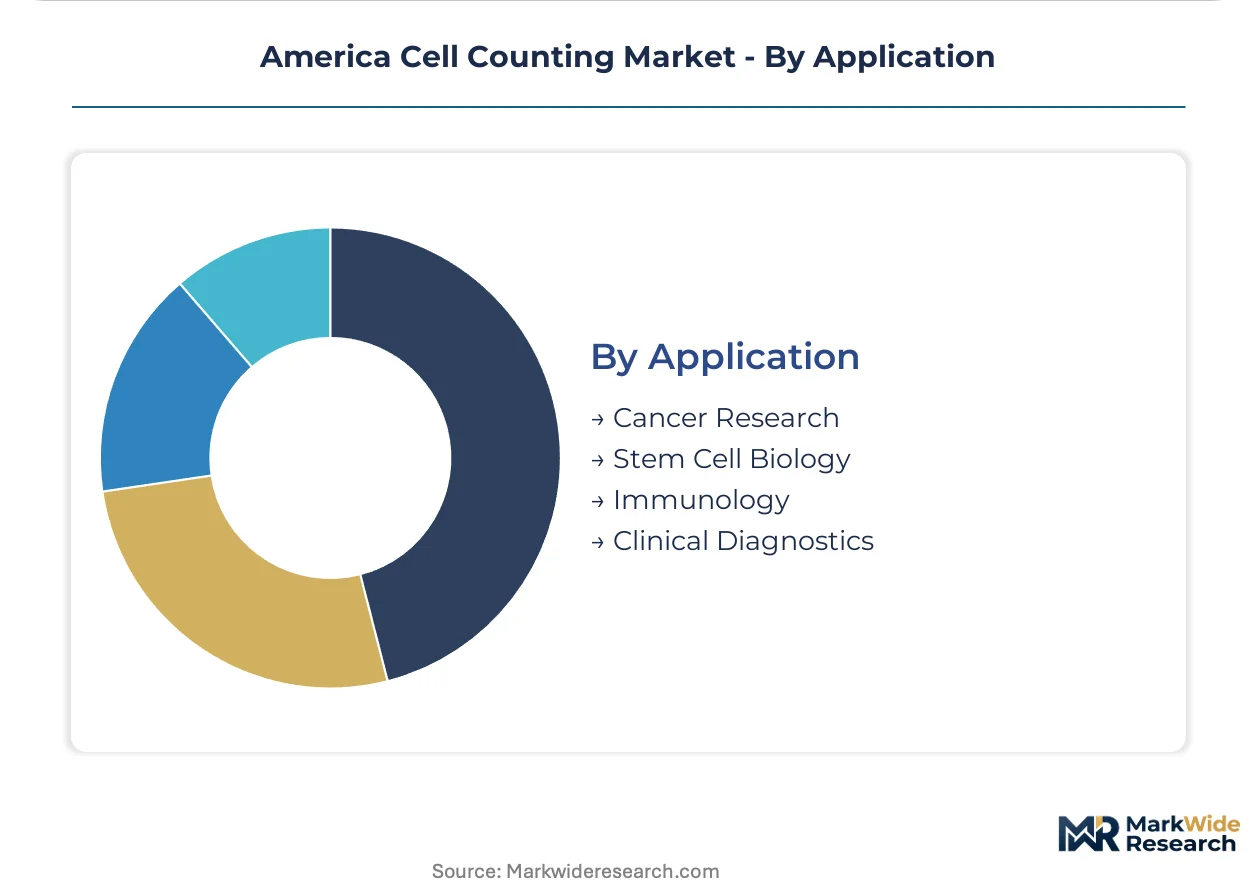
Application:
Clinical validation requirements create divergent margin structures between regulated diagnostic applications and exploratory research use cases.
- Cancer Research:Immunophenotyping workflows for checkpoint inhibitor development and CAR-T manufacturing require multiparametric platforms with 8-color minimum configurations. Massachusetts and California oncology centers concentrate demand for systems supporting rare event detection at frequencies below 0.1% of total cellular population.
- Stem Cell Biology:Regenerative medicine facilities prioritize label-free enumeration methods preserving pluripotency for downstream differentiation protocols. Academic and commercial laboratories in California are replacing manual hemocytometers with artificial vision platforms featuring automated confluence assessment and colony counting capabilities.
- Immunology:Autoimmune disease research and vaccine development programs utilize flow cytometry for lymphocyte subset quantification with NIST-traceable calibration standards.
- Clinical Diagnostics:Hematology and CD4 monitoring applications require FDA-cleared platforms with embedded quality control tracking and LIMS integration protocols.
Cancer research holds the dominant application share, while stem cell biology is expanding most quickly as regenerative medicine commercialization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers concentrate procurement authority across four Americas sub-regions, with California and Massachusetts life science clusters anchoring demand for high-throughput fluorescence platforms.
United States
FDA process analytical technology mandates drive replacement of manual hemocytometers in New Jersey and North Carolina manufacturing hubs. EPA hazardous waste standards for fluorescent reagents shape consumables purchasing decisions in high-throughput screening facilities. The Boston-Cambridge corridor concentrates flow cytometry procurement for CAR-T cell characterization workflows.
Canada
Health Canada ISO 13485 certification timelines extend commercial distribution authorization for clinical diagnostic platforms. Stem cell biology laboratories in Ontario and Quebec prioritize image-based counters with artificial vision algorithms. Toronto's regenerative medicine research institutes are unbundling instrument and reagent procurement to manage constrained capital budgets.
Mexico
Contract development organizations in Mexico City Metro adopt automated cell counters to serve North American pharmaceutical outsourcing demand. The country's national pharmaceutical regulator aligns technical standards with FDA guidance for export-oriented manufacturing. Baja California's medical device assembly clusters are integrating quality control cell counting into finished product validation protocols.
Brazil
ANVISA clinical trial regulations require validated cell enumeration methods for oncology and immunology studies. Cancer research institutes in São Paulo and Rio de Janeiro concentrate demand for multiparametric immunophenotyping platforms. The Southeast region's biotechnology parks are deploying automated counters to support biosimilar development programs.
Argentina
Academic research laboratories in Buenos Aires maintain manual hemocytometer workflows due to import restrictions on automated platforms. The national biotechnology development program funds stem cell biology infrastructure in Córdoba and Rosario. Public research institutes are prioritizing bright-field microscopy systems for trypan blue exclusion viability assessment.
America Cell Counting Market Competitive Environment
Player mix skews toward diversified life science conglomerates with integrated reagent-instrument ecosystems. Consolidation pressure concentrates procurement power among three to four platform vendors capable of delivering 21 CFR Part 11 compliance architectures. Strategic archetypes include full-stack solution providers, specialized clinical diagnostics automators, and research-grade fluorescence specialists. Competitive moves center on service unbundling to capture third-party reagent compatibility certification and artificial vision algorithm licensing for image-based platforms.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify integrated ecosystem strategies that anchor high-throughput screening workflows across North American contract development organizations. Bio-Rad Laboratories occupies a specialized position representing research-grade fluorescence detection architectures for cell biology applications. These three entities collectively illustrate the competitive tension between full-stack integration and modular specialization that shapes vendor pricing power across the Americas installed base.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Becton Dickinson |
| Beckman Coulter |
| Bio-Rad Laboratories |
| Merck KGaA |
| Agilent Technologies |
| PerkinElmer |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at precision optical component foundries in Japan and Germany shapes both supply availability and price floors for automated cell counting platforms. High-mix, low-volume production of photomultiplier tubes and laser diodes concentrates fixed cost recovery across fewer units, elevating baseline pricing for fluorescence-based systems while compressing margins for research-grade instrument vendors.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate long-term supply agreements for photodetector arrays and CMOS sensors. Pricing stratifies across FDA-validated, ISO-certified, and research-grade tiers, with 21 CFR Part 11 compliance architectures commanding substantial premiums. Cost compression in the research-grade segment is intensifying because third-party reagent compatibility erodes bundled consumables revenue. Academic core facilities exhibit highest price sensitivity, while pharmaceutical quality control departments prioritize compliance over unit cost.
Supply Chain Analysis
Japan, Germany, and the United States anchor production of high-sensitivity photomultiplier tubes, precision laser diodes, and advanced CMOS sensors for cell counting instrumentation. Manufacturing draws from rare earth elements for optical coatings, specialized glass substrates, and semiconductor-grade silicon wafers. Single-source vulnerability concentrates in photodetector supply, where two Japanese producers control majority capacity. Distribution runs through authorized life science distributors with field service capabilities, direct OEM sales to large pharmaceutical accounts, and academic purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The America Cell Counting Market represents an early-cycle expansion story as FDA process analytical technology mandates compress manual workflows into automated platforms across biopharmaceutical quality control laboratories.
For Market Incumbents: Consolidate around integrated reagent-instrument ecosystems to defend against third-party reagent unbundling. Deepen backward integration into precision optical component supply through captive manufacturing partnerships in Japan and Germany. Prioritize 21 CFR Part 11 compliance certification investments to maintain pricing power in pharmaceutical manufacturing accounts. For New Entrants and Emerging Players: Differentiate on artificial vision algorithm performance for label-free stem cell enumeration. Target academic core facilities in California and Massachusetts with capital-efficient image-based platforms compatible with third-party reagent workflows. Pursue go-to-market partnerships with existing laboratory information management system vendors to bypass legacy integration barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated platform vendors with installed bases in pharmaceutical manufacturing. Five-to-ten year viability favors companies with FDA-validated platforms and service contract attach rates above industry median. Target acquisition archetypes include specialized fluorescence detection firms and artificial vision software developers. Watch NIST reference material certification timelines as inflection indicators for next-generation platform calibration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Third-Party Reagent Compatibility Certification | Enables unbundled procurement for academic core facilities seeking operational expenditure flexibility. |
| Artificial Vision Algorithm Licensing | Accelerates displacement of manual hemocytometer workflows in stem cell biology laboratories. |
| 21 CFR Part 11 Compliance Architecture Investment | Secures pharmaceutical quality control replacement cycles driven by FDA process analytical technology mandates. |
| Closed-System Isolator Technology Integration | Addresses CAR-T manufacturing workflow requirements for single-use fluid path compatibility. |
| NIST Reference Material Embedded Validation | Creates first-mover advantage as cell concentration traceability standards emerge. |
Study Parameters
A spread of perspectives from biopharmaceutical quality control directors, academic core facility managers, regulatory affairs specialists, and laboratory information system integrators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 21 CFR Part 11 guidance documents, EPA hazardous waste disposal standards, ISO 13485 certification protocols, and NIST reference material specifications. Bottom-up instrument shipment data triangulated against top-down biopharmaceutical capital expenditure disclosures.
Segmentation dimensions modeled include product architecture, end-user procurement authority, detection modality, and application workflow requirements across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles, regulatory compliance investment patterns, and stem cell biology funding trajectories. Forecast inputs incorporated pharmaceutical manufacturing capacity expansion in New Jersey and North Carolina, plus regenerative medicine commercialization timelines in California and Massachusetts.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of process analytical technology guidelines or accelerated NIST certification timelines would require recalibration. Forecasts reflect assumptions about regulatory compliance investment continuity and optical component supply chain stability. Recalibration cycles align with material shifts in FDA guidance issuance, EPA reagent disposal rulemaking, and NIST reference material availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Europe Transfection Technologies Market