
 Global Transcriptomics Market | 2026-2036
Global Transcriptomics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transcriptomics Market Foresight
Buyer concentration among pharmaceutical companies is repositioning procurement power toward large-scale RNA sequencing contracts. Illumina leverages its installed base of sequencing instruments to sustain recurring reagent revenue. Thermo Fisher Scientific anchors its position through integrated workflow solutions spanning sample preparation to data analysis. QIAGEN differentiates with automated sample processing systems that reduce hands-on time for high-throughput transcriptomic studies.
Transcriptomics encompasses the complete set of RNA transcripts in a cell or population, quantified through technologies measuring messenger RNA, non-coding RNA, and alternative splice variants with single-molecule sensitivity. RNA sequencing dominates technology adoption due to its dynamic range and discovery power, while qPCR retains cost advantages for targeted validation studies. Drug discovery applications command the largest application segment, though biomarker identification is expanding fastest as companion diagnostic requirements tighten. Reagents generate the steadiest revenue stream, while software and services capture expanding margin pools as data complexity outpaces in-house bioinformatics capacity.
The FDA's biomarker qualification framework and the EMA's parallel scientific advice pathway are shaping how transcriptomic signatures enter regulated diagnostic use. ISO 15189 laboratory accreditation and CLIA certification requirements in the United States filter market access for clinical transcriptomic service providers. Stakeholders must monitor evolving reimbursement policies for RNA-based diagnostics across Medicare, national health systems, and private payers to anticipate revenue timing and geographic prioritization.
Market Dynamics
Pharmaceutical procurement consolidation is compressing vendor margins and favoring integrated workflow providers capable of delivering end-to-end transcriptomic solutions under multi-year enterprise agreements.
Growth Catalysts
- NIH funding expansion:The United States has enlarged extramural research budgets, channeling capital into academic medical centers conducting large-scale RNA sequencing studies for precision oncology.
- FDA biomarker qualification framework:This regulatory pathway accelerates the clinical validation of transcriptomic signatures, reducing uncertainty for diagnostic developers seeking companion test approval.
- Single-cell RNA sequencing:This technology resolution leap enables researchers to dissect cellular heterogeneity in tumor microenvironments, driving replacement demand from bulk transcriptomic methods.
Market Restraints
- Reagent cost concentration:Sequencing consumables account for substantial per-run expenditure, with proprietary chemistries locked to specific instrument platforms limiting supplier switching.
- Bioinformatics bottleneck:Shortage of trained computational biologists capable of interpreting complex transcriptomic datasets slows study turnaround and inflates service outsourcing costs.
- Data storage infrastructure:Petabyte-scale raw file accumulation from high-throughput experiments strains institutional IT budgets and cloud compute allocations.
Strategic Opportunities
- India biotech corridor expansion:Hyderabad and Bangalore clusters attract contract research organizations seeking lower-cost transcriptomic service delivery for multinational pharmaceutical clients.
- Spatial transcriptomics integration:Convergence of histopathology imaging with RNA profiling creates new diagnostic categories for tissue-based biomarker localization.
- Liquid biopsy transcriptomics:Circulating tumor RNA analysis from blood samples opens non-invasive monitoring applications in immuno-oncology patient management.
Industry Challenges
- CLIA certification timelines:Clinical laboratories pursuing transcriptomic test validation face prolonged accreditation processes that delay revenue recognition for diagnostic services.
- Inter-platform standardization gaps:Inconsistent RNA quantification across sequencing instruments complicates multi-site clinical trial data integration and regulatory submission packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transcriptomics Market |
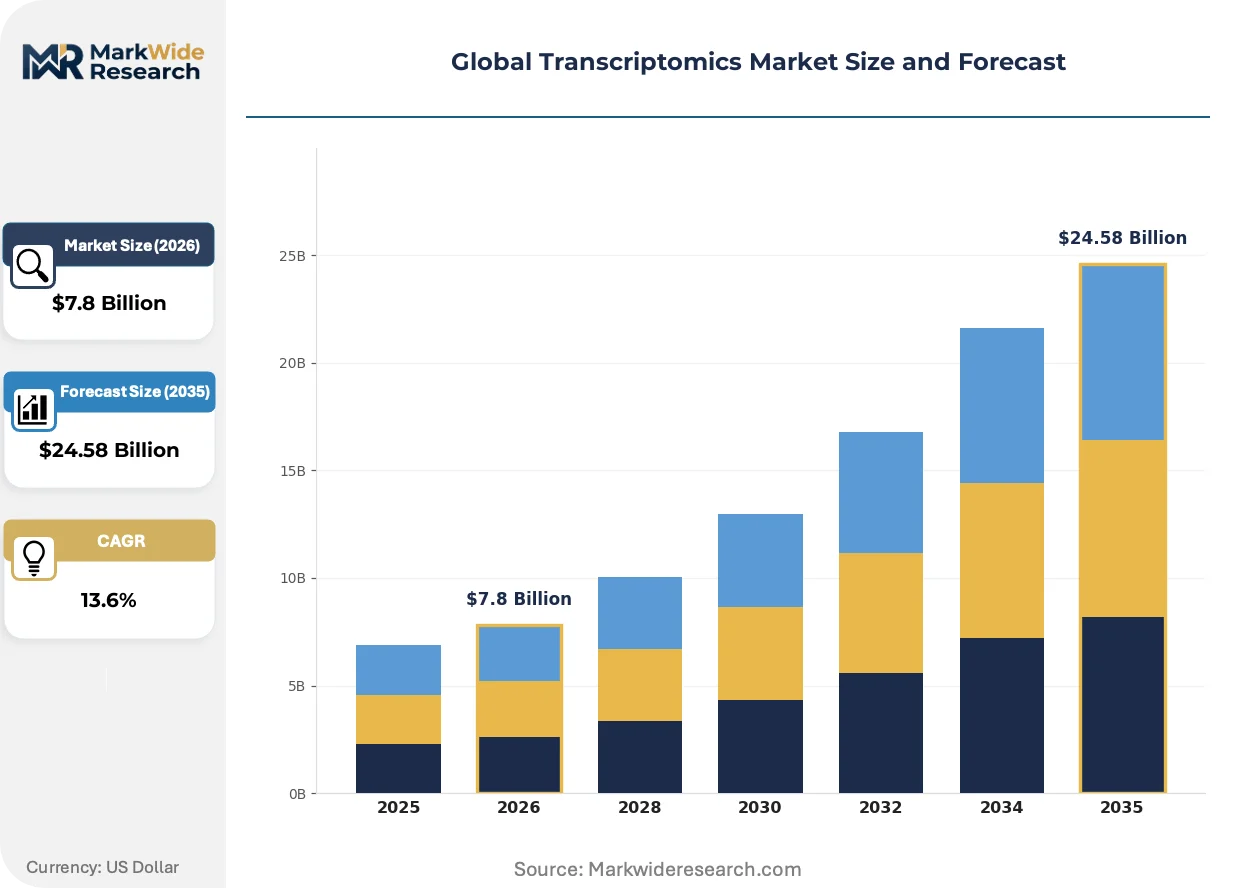
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $24.58 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RNA Sequencing, Microarray, qPCR, Northern Blotting Application: Drug Discovery, Toxicology Analysis, Biomarker Identification, Functional Genomics End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Academic Laboratories Product Type: Reagents, Instruments, Software, Services |
| Companies Covered | Illumina, Thermo Fisher Scientific, 10x Genomics, Agilent Technologies, Bio-Rad Laboratories, QIAGEN, NanoString Technologies, Roche, BGI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transcriptomics Market Shifts & Advancements
Cloud-native bioinformatics pipelines are compressing the interval between sample acquisition and actionable transcriptomic insight, reshaping how pharmaceutical R&D organizations structure their analytical operations.
Long-read sequencing platforms from Pacific Biosciences and Oxford Nanopore are unifying full-length transcript detection with epigenetic modification mapping in single analytical runs. Academic consortia in the United States and Germany have adopted these systems for reference transcriptome curation. This unification is collapsing the sequential workflow of short-read assembly followed by targeted validation, reducing project timelines from months to weeks.
EMA's parallel scientific advice pathway now permits simultaneous regulatory consultation on transcriptomic biomarker qualification across multiple European jurisdictions. This procedural innovation reduces redundant dossier preparation for companion diagnostic developers. France and Germany have seen the highest uptake of this mechanism among transcriptomic test sponsors seeking synchronized market entry.
Pharmaceutical buyers are consolidating sequencing procurement under centralized vendor management offices rather than distributing contracts across individual research sites. This organizational shift concentrates annual spend with fewer suppliers capable of delivering global service level agreements. The restructuring is most pronounced among top-twenty pharmaceutical companies headquartered in the United States and Switzerland.
Global Transcriptomics Market Segmentation
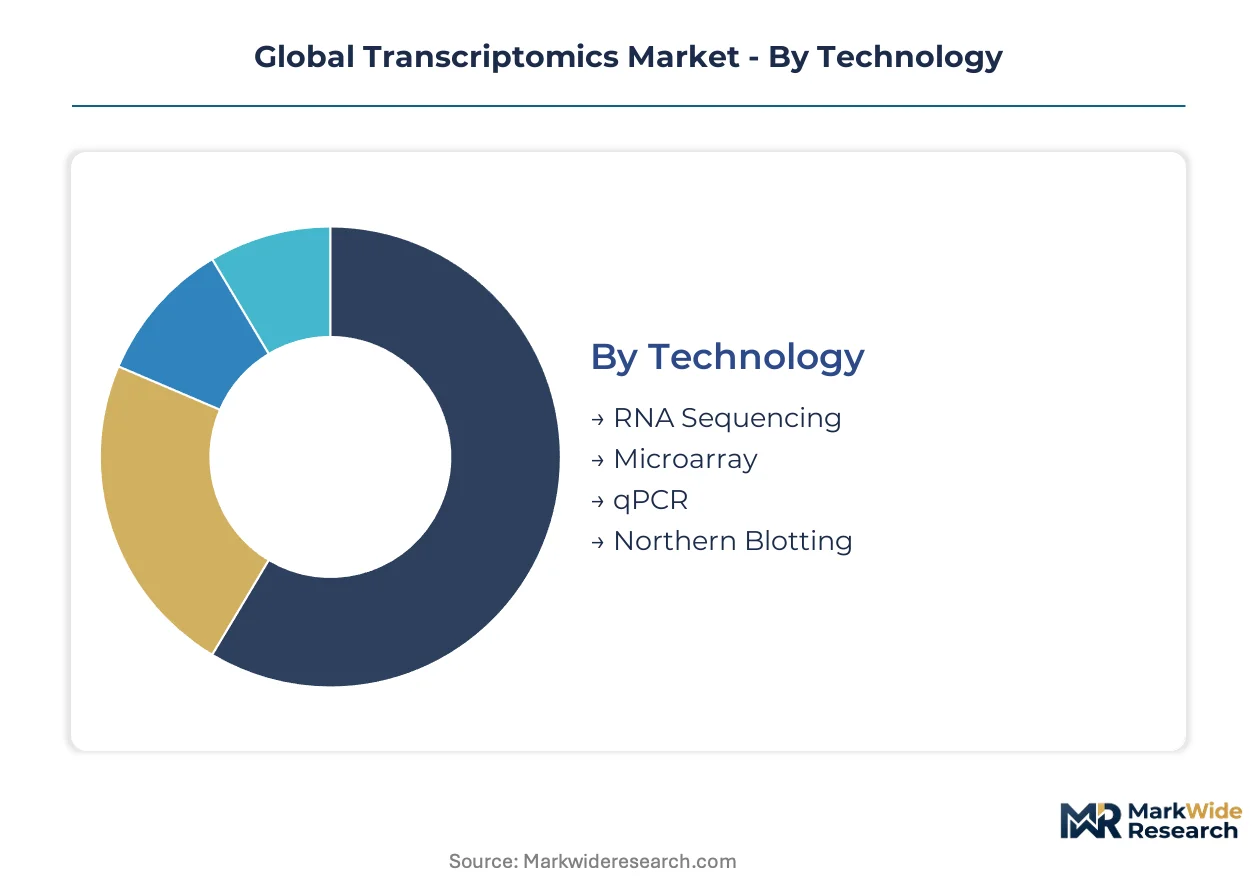
Transcriptomics market segmentation reveals how technology choices, application priorities, and procurement models allocate revenue across distinct value pools. Understanding these divisions exposes where vendor margins concentrate and where competitive displacement risks emerge.
Technology:
Volume-driven platforms dominate routine screening, while premium-resolution technologies capture high-complexity discovery budgets.
- RNA Sequencing:Short-read and long-read platforms quantify messenger RNA, non-coding RNA, and splice variants with single-molecule sensitivity. Pharmaceutical companies in Boston and San Diego deploy this for precision oncology target identification, driven by NIH funding expansion and companion diagnostic requirements.
- Microarray:Hybridization-based systems offer standardized expression profiling for large cohort studies at lower per-sample cost. Academic medical centers in Germany leverage this for population-scale transcriptome mapping where discovery power matters less than statistical power.
- qPCR:Cost-efficient validation of targeted transcripts from extracted RNA samples.
- Northern Blotting:Classic technique for specific RNA size detection and integrity assessment.
Today's leader: RNA Sequencing. Tomorrow's challenger: Long-read platforms unifying transcript detection with epigenetic mapping.
Application:
Mature therapeutic areas anchor current spending, while regulatory tightening redirects investment toward diagnostic qualification.
- Drug Discovery:Transcriptomic screening identifies disease mechanisms, target engagement biomarkers, and off-target effects across therapeutic programs. Biotechnology firms in Switzerland integrate this into early-stage pipeline decisions, constrained by bioinformatics bottlenecks that slow data interpretation.
- Biomarker Identification:Signature development for patient stratification and companion diagnostic pairing. Contract research organizations in Hyderabad and Bangalore build service capabilities here, climbing the fastest as FDA biomarker qualification frameworks reduce regulatory uncertainty.
- Toxicology Analysis:Transcriptomic response profiling for compound safety assessment.
- Functional Genomics:Gene function elucidation through systematic expression manipulation studies.
Revenue gravity centers on drug discovery workflows. Steepest expansion trajectory belongs to biomarker qualification services.
End User:
Procurement consolidation favors vendors capable of enterprise-scale contracts with centralized vendor management offices.
- Pharmaceutical Companies:Integrated transcriptomic platforms spanning target discovery through clinical validation. Top-twenty firms headquartered in the United States and Switzerland concentrate annual sequencing spend with fewer suppliers, demanding global service level agreements.
- Biotechnology Firms:Outsourced or shared-resource access to RNA sequencing infrastructure.
- Research Institutes:Academic and government-funded facilities conducting large-scale reference transcriptome projects.
- Academic Laboratories:Individual investigator-driven studies with fragmented purchasing authority.
Enterprise buyers command pricing leverage. Fragmented academic demand sustains instrument placement strategies.
Product Type:
Recurring consumables generate predictable revenue streams, while analytical software captures expanding margin pools.
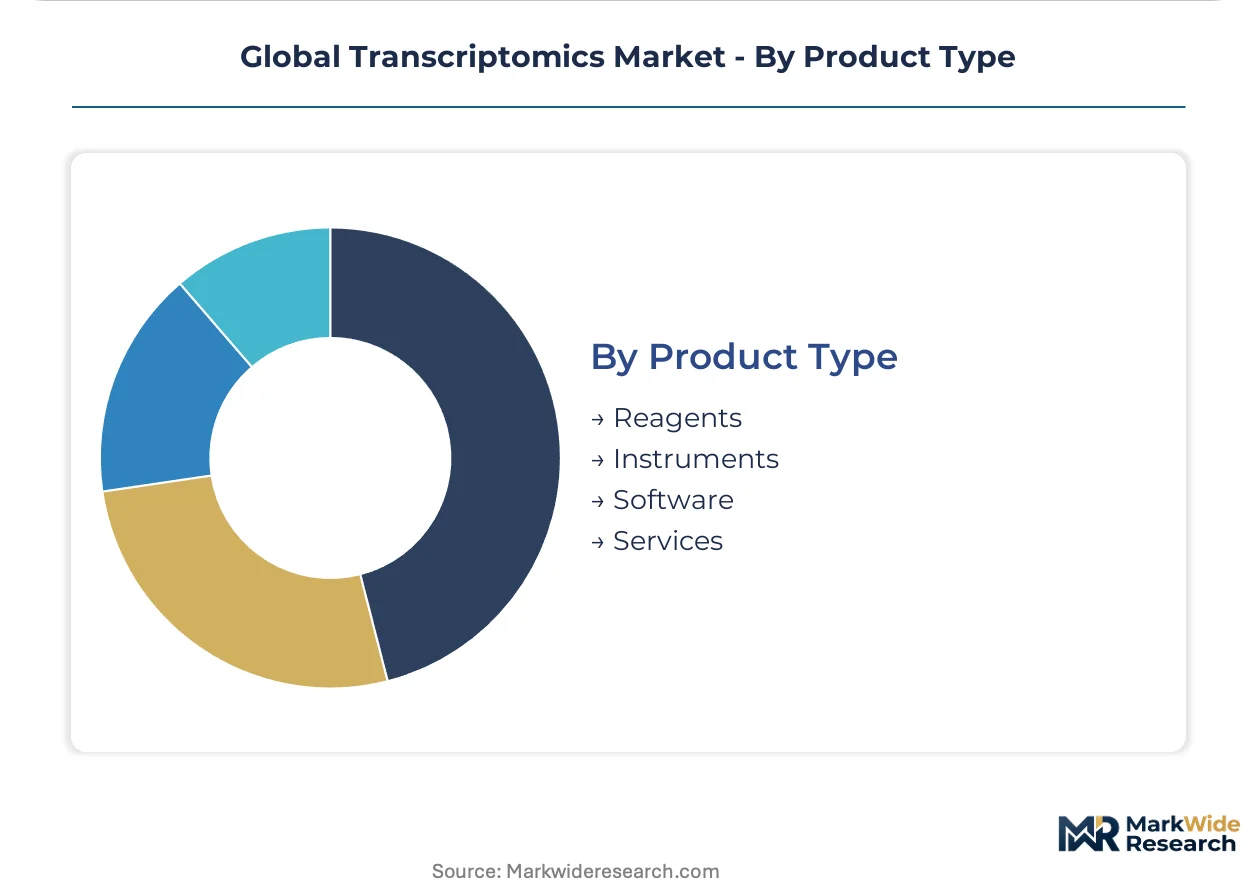
- Reagents:Sequencing chemistries, library preparation kits, and nucleic acid extraction consumables locked to specific instrument platforms. Proprietary reagent-instrument pairings limit supplier switching and sustain per-run expenditure concentration.
- Software:Cloud-native bioinformatics pipelines and variant interpretation platforms. Data complexity outpaces in-house computational biology capacity, forcing pharmaceutical R&D organizations toward outsourced analytical operations.
- Instruments:Capital equipment for RNA sequencing, microarray, and qPCR workflows.
- Services:Contract sequencing and bioinformatics analysis from specialized providers.
Reagents anchor vendor profitability. Software margins expand fastest as data volumes overwhelm internal infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially larger transcriptomics procurement volumes than Germany, though both countries anchor pharmaceutical R&D investment in distinct regulatory environments. NIH funding trajectories and EMA consultation pathways create divergent market access conditions for transcriptomic diagnostic developers.
United States
NIH extramural budget expansion channels capital into Boston and San Diego biotech clusters conducting large-scale RNA sequencing for precision oncology. FDA biomarker qualification frameworks accelerate regulatory clarity for companion diagnostic submissions. Academic medical centers in these coastal hubs replace aging microarray infrastructure with single-cell transcriptomic platforms.
Germany
EMA parallel scientific advice mechanisms attract transcriptomic test sponsors seeking synchronized European market entry across multiple jurisdictions. Federal research funding through the German Research Foundation sustains reference transcriptome curation projects at Heidelberg and Munich institutes. The country's national pharmaceutical regulator enforces ISO 15189 laboratory accreditation standards that filter clinical service provider access.
China
Domestic pharmaceutical companies expand transcriptomic outsourcing to contract research organizations in Beijing and Shanghai life science parks. NMPA regulatory reforms streamline biomarker-based diagnostic approval pathways for oncology applications. BGI anchors sequencing service capacity in Shenzhen's genomics industrial cluster, supplying multinational clients with cost-competitive transcriptomic analysis.
India
Hyderabad and Bangalore biotech corridors attract contract research organizations delivering lower-cost transcriptomic services for pharmaceutical clients headquartered in Europe and North America. CDSCO regulatory harmonization initiatives align with ICH guidelines for RNA-based diagnostic validation. The country's national pharmaceutical regulator oversees clinical trial transcriptomic endpoint qualification for domestic drug development programs.
Switzerland
Headquarters concentration among top-twenty pharmaceutical companies concentrates enterprise-scale sequencing procurement decisions in Basel and Zurich metropolitan areas. Swissmedic maintains rigorous quality standards for transcriptomic biomarker integration into clinical trial protocols. Roche anchors diagnostic development capabilities in Basel, supplying companion test infrastructure for precision medicine pipelines.
Global Transcriptomics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the transcriptomics value chain, creating tiered competitive dynamics. The vendor base organizes around three strategic archetypes: integrated workflow providers spanning sample preparation through data analysis, platform-locked reagent suppliers sustaining recurring revenue through proprietary chemistries, and specialized bioinformatics service vendors addressing computational biology capacity gaps. Competitive positioning hardens through multi-year enterprise agreements with centralized pharmaceutical procurement offices and technology licensing arrangements that extend platform ecosystems.
Within the integrated workflow tier, Thermo Fisher Scientific and QIAGEN exemplify diversified life science conglomerates competing through end-to-end solution bundling. Illumina occupies a position as a platform-centric specialist anchoring sequencing infrastructure decisions across academic and commercial research settings. These three companies represent contrasting strategic postures: conglomerate breadth versus platform-specific depth, each capturing distinct margin pools across reagent, instrument, and software revenue streams.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| 10x Genomics |
| Agilent Technologies |
| Bio-Rad Laboratories |
| QIAGEN |
| NanoString Technologies |
| Roche |
| BGI |
| Others |
Supply & Pricing Matrix
Computational biology talent clustering in Boston and San Diego generates labor-cost differentials that widen pricing-tier spreads between premium single-cell transcriptomic services and economy-scale bulk RNA sequencing offerings.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for contract transcriptomic services, compressing margins for mid-tier providers. Three-tier pricing structure across premium, standard, and economy levels separates single-cell spatial platforms from bulk sequencing and qPCR validation tiers. Price differentiation hinges on ISO 15189 certification status and CLIA accreditation timelines. Pharmaceutical procurement offices demonstrate lowest price sensitivity, while academic laboratories face budget constraints that intensify cost scrutiny.
Supply Chain Analysis
CLIA certification and ISO 15189 laboratory accreditation function as gating mechanisms that filter supplier participation in clinical transcriptomic services. Manufacturing concentration for sequencing instruments rests in the United States, China, and Switzerland, with reagent production anchored in proprietary chemistries from California and Massachusetts facilities. Raw material dependencies include modified nucleotides, polymerase enzymes, and flow-cell substrates. Single-source vulnerability around Illumina instrument platforms creates supply risk. Distribution runs through direct enterprise agreements with pharmaceutical vendor management offices and academic core facility consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA biomarker qualification framework operates as a regulatory compounder, accelerating transcriptomic diagnostic commercialization and concentrating procurement power among qualified service providers.
For Market Incumbents: Extend platform ecosystems through multi-year enterprise agreements with top-twenty pharmaceutical companies, locking in reagent-instrument pairings that limit supplier switching. Defend against long-read sequencing displacement by integrating epigenetic mapping capabilities into existing short-read workflows. Prioritize backward integration into proprietary polymerase enzyme production to secure supply continuity. For New Entrants and Emerging Players: The price-point gap between premium spatial transcriptomics and economy qPCR validation creates entry space for hybrid service models targeting mid-market biotechnology firms. White-space targets include liquid biopsy transcriptomic monitoring for immuno-oncology and automated sample processing systems for high-throughput studies. Penetrate through cloud-native bioinformatics partnerships that address pharmaceutical computational biology capacity gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among contract research organizations in Hyderabad and Bangalore with established CLIA-equivalent quality systems and multinational pharmaceutical client relationships. Long-term viability over the next decade hinges on regulatory qualification track records and geographic diversification beyond single-country service delivery. Watch FDA biomarker qualification approval velocity as the primary inflection signal for diagnostic service revenue timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Pathway | FDA biomarker qualification accelerates companion diagnostic commercialization timelines for precision oncology. |
| Cloud-Native Bioinformatics Platform | Cloud-native pipelines compress turnaround from sample to actionable transcriptomic insight for pharmaceutical R&D. |
| Long-Read Sequencing Integration | Full-length transcript detection with epigenetic mapping collapses sequential validation workflows into single runs. |
| Geographic Service Expansion | Hyderabad and Bangalore facilities deliver cost-competitive transcriptomic services for European and North American clients. |
| Spatial Transcriptomics Development | Histopathology-RNA convergence creates new diagnostic categories for tissue-based biomarker localization. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, core facility directors, and bioinformatics service managers grounded qualitative findings in operational realities. Secondary validation drew from FDA biomarker qualification submissions, EMA parallel scientific advice records, ClinicalTrials.gov transcriptomic endpoint registrations, and NIH extramural funding databases. Bottom-up segmentation modeling triangulated against top-down pharmaceutical R&D expenditure analysis.
Segmented outputs across technology platforms, application areas, end-user archetypes, and product categories structured the analytical framework throughout the projection horizon. CAGRs derived from NIH funding trajectory analysis, pharmaceutical sequencing procurement consolidation patterns, and single-cell platform replacement cycle assumptions. Technology diffusion curves and regulatory approval velocity informed adoption modeling for long-read and spatial transcriptomic systems.
Caveats apply where FDA biomarker qualification timeline shifts or reimbursement policy changes for RNA-based diagnostics could materially shift the outlook. Forecasts reflect assumptions about continued NIH extramural budget expansion and sustained pharmaceutical precision oncology investment. A model refresh is warranted upon material change in companion diagnostic regulatory pathways or cloud compute cost trajectories affecting bioinformatics outsourcing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Drug Discovery Enzymes Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Middle East and Africa Exosome Research Products Market
Biomedical Technology
Enzymatic DNA Synthesis Market