
 Cell Cycle Analysis Market | 2026-2036
Cell Cycle Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Cycle Analysis Market Analysis
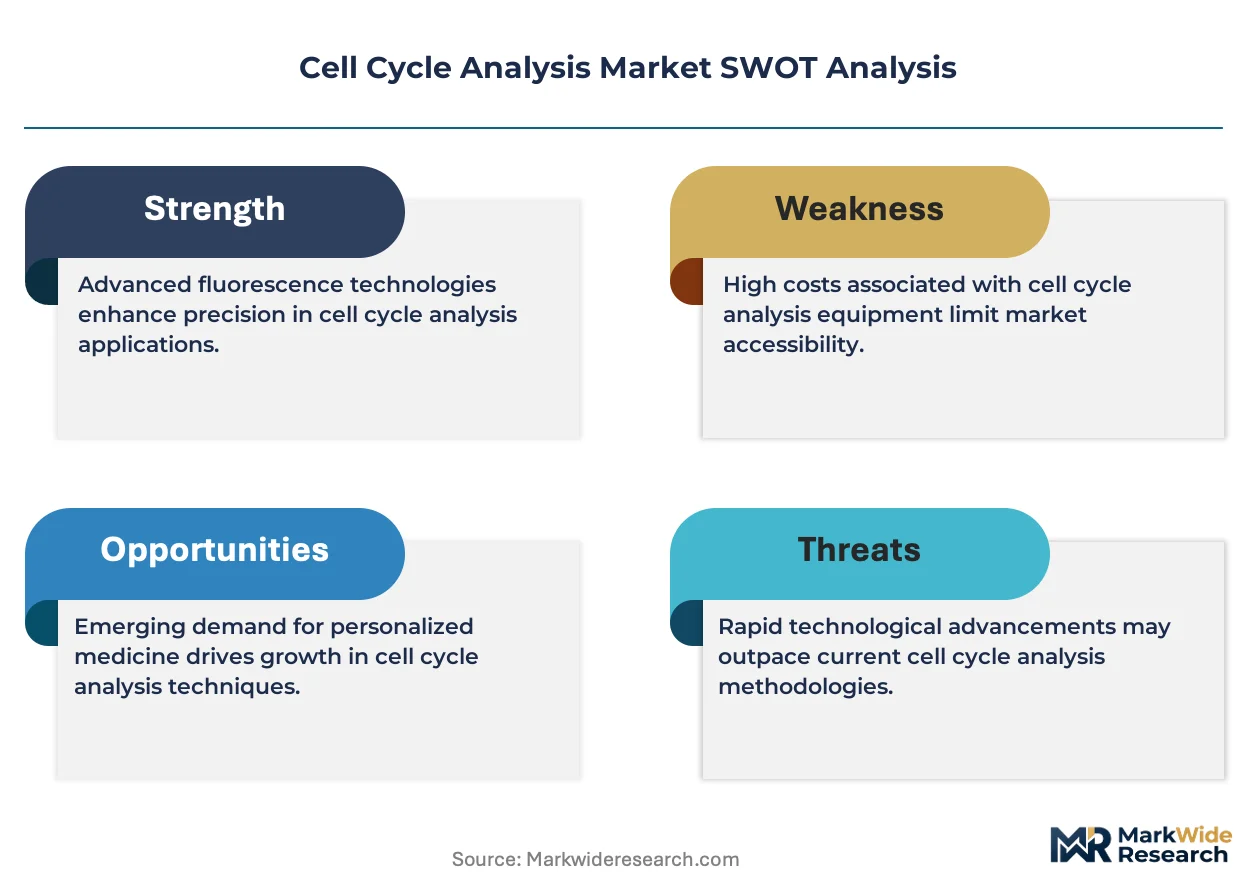
Multi-source procurement of cell cycle analysis reagents and instruments is expanding as pharmaceutical companies diversify supply risk across vendors. Thermo Fisher Scientific leverages its vertically integrated life sciences platform to dominate flow cytometry consumables. BD Biosciences anchors its position through deep R&D intensity in fluorescence-activated cell sorting systems. Bio-Rad Laboratories differentiates via specialized PCR-compatible cell proliferation assays that integrate with existing genomic workflows.
Cell cycle analysis encompasses quantitative methods for measuring DNA content, replication status, and mitotic progression in proliferating cell populations, typically employing fluorescent nucleic acid dyes such as propidium iodide or BrdU incorporation paired with flow cytometric detection. Its primary commercial purpose is to enable precise characterization of cell division kinetics for therapeutic development and diagnostic stratification. Flow cytometry instruments command the largest installed base and generate recurring consumable revenue, while live cell imaging systems represent the fastest-expanding segment due to real-time kinetic demands in drug screening. Academic institutions remain the most price-sensitive end user cohort, whereas pharmaceutical companies concentrate margin pools through high-volume, long-term service contracts.
FDA oversight of in vitro diagnostic devices and EMA's In Vitro Diagnostic Regulation shape product registration pathways and clinical validation requirements for cell cycle assays marketed in the United States and European Union. ISO 13485 quality management standards further constrain manufacturing practices for instruments deployed in regulated diagnostic settings. Stakeholders must monitor evolving harmonization between FDA's quality system regulation and EU MDR technical documentation requirements to sustain market access across both jurisdictions.
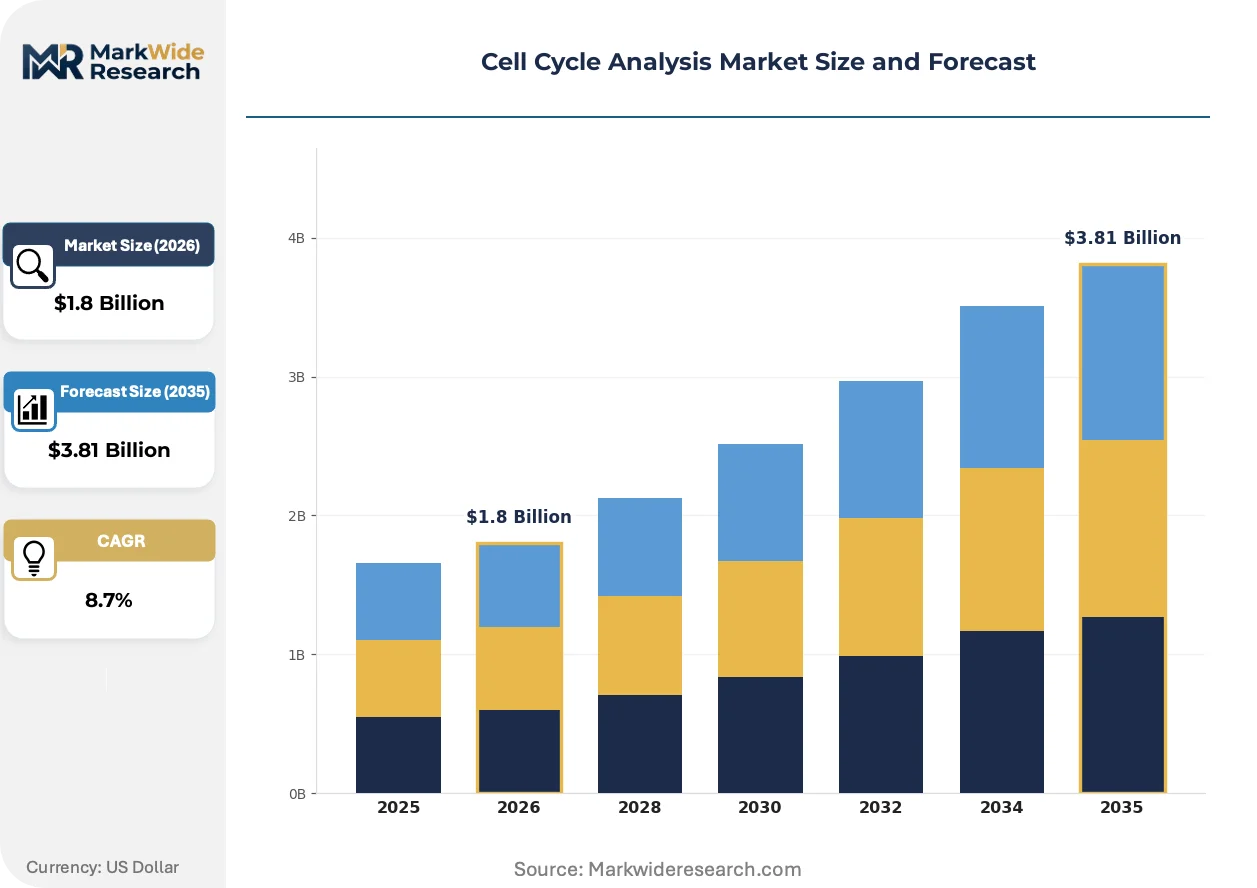
Market Dynamics
Pharmaceutical pipelines are intensifying demand for kinetic cell proliferation data, forcing reagent suppliers to validate assays under FDA and EMA quality system mandates that now govern companion diagnostic development workflows.
Growth Catalysts
- Companion Diagnostic Mandates:FDA guidance on co-development of oncology therapeutics with predictive biomarkers is expanding contract research demand for standardized cell cycle assays in clinical trial settings.
- Live-Cell Imaging Adoption:Real-time kinetic monitoring is displacing endpoint assays in high-throughput screening, with biotech clusters in Germany and the United States driving instrument procurement.
- ISO 13485 Certification Expansion:Diagnostic laboratories in Japan and South Korea are requiring quality-certified reagents, pulling suppliers toward regulated manufacturing investments.
Market Restraints
- Fluorophore Supply Concentration:German and Swiss chemical suppliers dominate high-purity nucleic acid dye production, creating input vulnerability for assay manufacturers.
- EMA MDR Technical Documentation Burden:The In Vitro Diagnostic Regulation's clinical evidence requirements are extending product registration timelines and inflating regulatory compliance costs.
- Manual Protocol Variability:Inter-laboratory inconsistency in BrdU incorporation and fixation procedures limits cross-study comparability, constraining multi-site trial adoption.
Strategic Opportunities
- India Biopharma Manufacturing:CDSCO's streamlined medical device registration pathway and PLI scheme incentives are attracting contract assay development investment from multinational reagent suppliers.
- AI-Assisted Image Analysis:Machine learning classification of mitotic figures is converging with high-content imaging platforms to automate proliferation scoring in phenotypic screens.
- Single-Cell Multi-Omics Workflows:Integration of cell cycle state with transcriptomic profiling is opening specialized reagent demand from academic systems biology consortia.
Industry Challenges
- Flow Cytometry Specialist Shortage:Clinical diagnostic laboratories face recruitment gaps for operators capable of gating complex DNA histograms and troubleshooting instrument drift.
- Legacy LIMS Integration Friction:New imaging platforms require custom API development to connect with established laboratory information management systems, delaying deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Cycle Analysis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometry, DNA Staining Reagents, Live Cell Imaging, Cell Proliferation Kits Technology: Fluorescence Microscopy, Image Cytometry, Mass Cytometry, Automated Cell Counters Application: Cancer Research, Stem Cell Research, Drug Discovery, Genetic Engineering End User: Academic Institutions, Pharmaceutical Companies, Diagnostic Laboratories, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific, BD Biosciences, Merck KGaA, Beckman Coulter, Bio-Rad Laboratories, PerkinElmer, Miltenyi Biotec, Abcam, Cell Signaling Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Cycle Analysis Market Emerging Trajectories
Automation and computational biology are compressing assay turnaround times while regulatory convergence across FDA and EMA jurisdictions is standardizing validation protocols for cell-based diagnostic platforms.
EdU (5-ethynyl-2'-deoxyuridine) click-chemistry proliferation assays are replacing BrdU antibody detection methods due to simplified workflows and multiplexing compatibility. Mid-sized pharmaceutical companies are adopting EdU kits for oncology screening programs. This chemistry is decentralizing proliferation analysis from centralized core facilities into distributed discovery laboratories.
EMA's In Vitro Diagnostic Regulation is mandating clinical performance studies and post-market surveillance for cell cycle assays marketed as companion diagnostics. Manufacturers must now generate patient-derived evidence prior to CE marking. European oncology diagnostic laboratories are consolidating procurement around suppliers with established MDR technical documentation capabilities.
Service unbundling is separating instrument maintenance contracts from reagent supply agreements, allowing pharmaceutical buyers to negotiate consumable pricing independently. Large biotech clusters in Massachusetts and Bavaria are driving this disaggregation. Contract research organizations in these regions now specify open-platform reagent compatibility as a procurement requirement.
Cell Cycle Analysis Market Segmentation
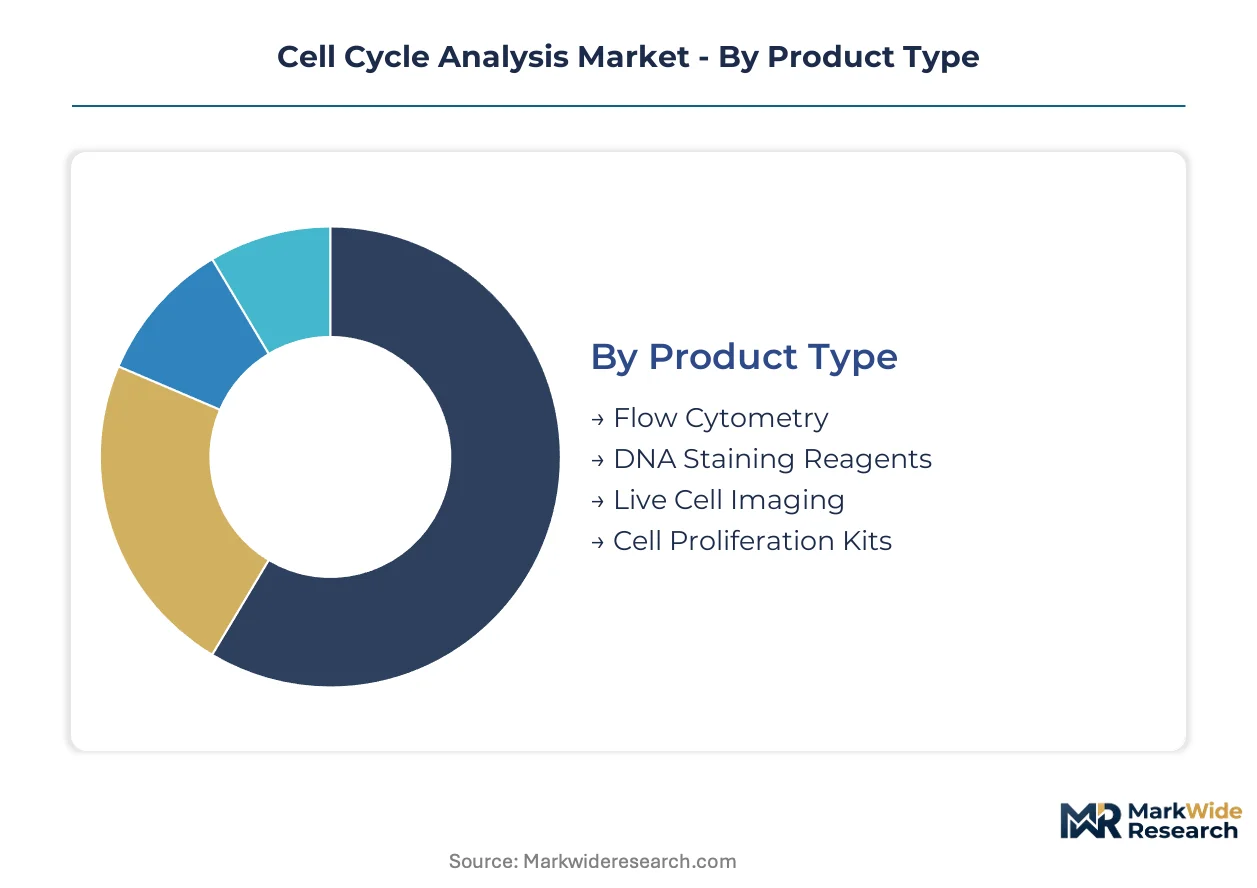
Cell cycle analysis vendors configure product portfolios around workflow complexity and regulatory burden. Standardized reagent kits serve high-throughput screening environments while customizable imaging platforms address phenotypic discovery programs requiring protocol flexibility.
Product Type:
Customization intensity varies sharply across this category, with instrument systems demanding extensive protocol tailoring while consumable reagents ship as validated, ready-to-use formulations.
- Flow Cytometry:Multi-laser analytical instruments quantifying DNA content via fluorescent dye excitation. Pharmaceutical companies in Massachusetts and Bavaria anchor procurement through long-term service contracts tied to oncology pipeline screening. These systems generate recurring consumable revenue through proprietary sheath fluid and calibration bead dependencies.
- DNA Staining Reagents:Nucleic acid dyes including propidium iodide and DAPI formulations for fixed-cell ploidy analysis. Academic medical centers concentrate demand for cost-per-sample optimization in multi-investigator core facilities. Supply vulnerability persists due to German and Swiss chemical manufacturers dominating high-purity fluorophore synthesis.
- Live Cell Imaging:Time-lapse microscopy platforms enabling kinetic proliferation tracking without fixation artifacts. Biotech clusters drive adoption for real-time compound mechanism studies.
- Cell Proliferation Kits:EdU click-chemistry and BrdU incorporation assay systems for S-phase detection. Mid-sized pharmaceutical discovery groups favor simplified workflow formats.
Most installed capacity flows through Flow Cytometry. Expansion is steepest in Live Cell Imaging.
Technology:
Cost tiering separates capital-intensive imaging infrastructure from benchtop counting devices, with price differentials exceeding an order of magnitude between research-grade microscopy and automated hematology-adjacent counters.
- Fluorescence Microscopy:Widefield and confocal systems utilizing mercury arc or LED illumination for multi-channel DNA and protein detection. Academic institutions in Germany and the United States represent price-sensitive procurement concentrated around open-platform hardware specifications. FDA guidance on image-based companion diagnostics is elevating validation documentation requirements for clinical deployment.
- Image Cytometry:Slide-based automated microscopy combining high-content imaging with algorithmic cell classification. Contract research organizations in Massachusetts specify these platforms for phenotypic screening programs requiring GxP-compliant data integrity.
- Mass Cytometry:Metal-isotope tagged antibody detection enabling 40-plus parameter single-cell analysis. Specialized academic consortia drive niche adoption despite high capital and operational complexity.
- Automated Cell Counters:Benchtop impedance or imaging-based devices for rapid viability and concentration assessment. Diagnostic laboratories favor these for routine quality control applications.
Capital deployment concentrates in Fluorescence Microscopy. Image Cytometry gains share fastest in pharmaceutical contract research settings.
Application:
Customer maturity separates established therapeutic areas with standardized assay panels from emerging domains requiring protocol development investment and technical support intensity.
- Cancer Research:Tumor proliferation kinetics and therapeutic resistance mechanism studies utilizing DNA histogram analysis and mitotic index quantification. Pharmaceutical oncology pipelines in the United States and Germany generate sustained reagent demand through longitudinal clinical biomarker programs. EMA MDR technical documentation requirements are consolidating procurement around suppliers with established companion diagnostic validation capabilities.
- Stem Cell Research:Pluripotency maintenance and differentiation trajectory monitoring via cell cycle phase distribution. Academic consortia in Japan and South Korea concentrate demand for ISO 13485-certified reagents supporting regenerative medicine translation.
- Drug Discovery:High-throughput compound screening for anti-proliferative activity across diverse therapeutic modalities. Biotechnology firms prioritize kinetic imaging platforms over endpoint assays.
- Genetic Engineering:Cell line engineering workflow integration for CRISPR-edited clone selection and expansion optimization. Contract development organizations specify multiplexed proliferation and viability readouts.
Revenue concentration sits with Cancer Research. Stem Cell Research climbs the fastest as regenerative medicine manufacturing scales.
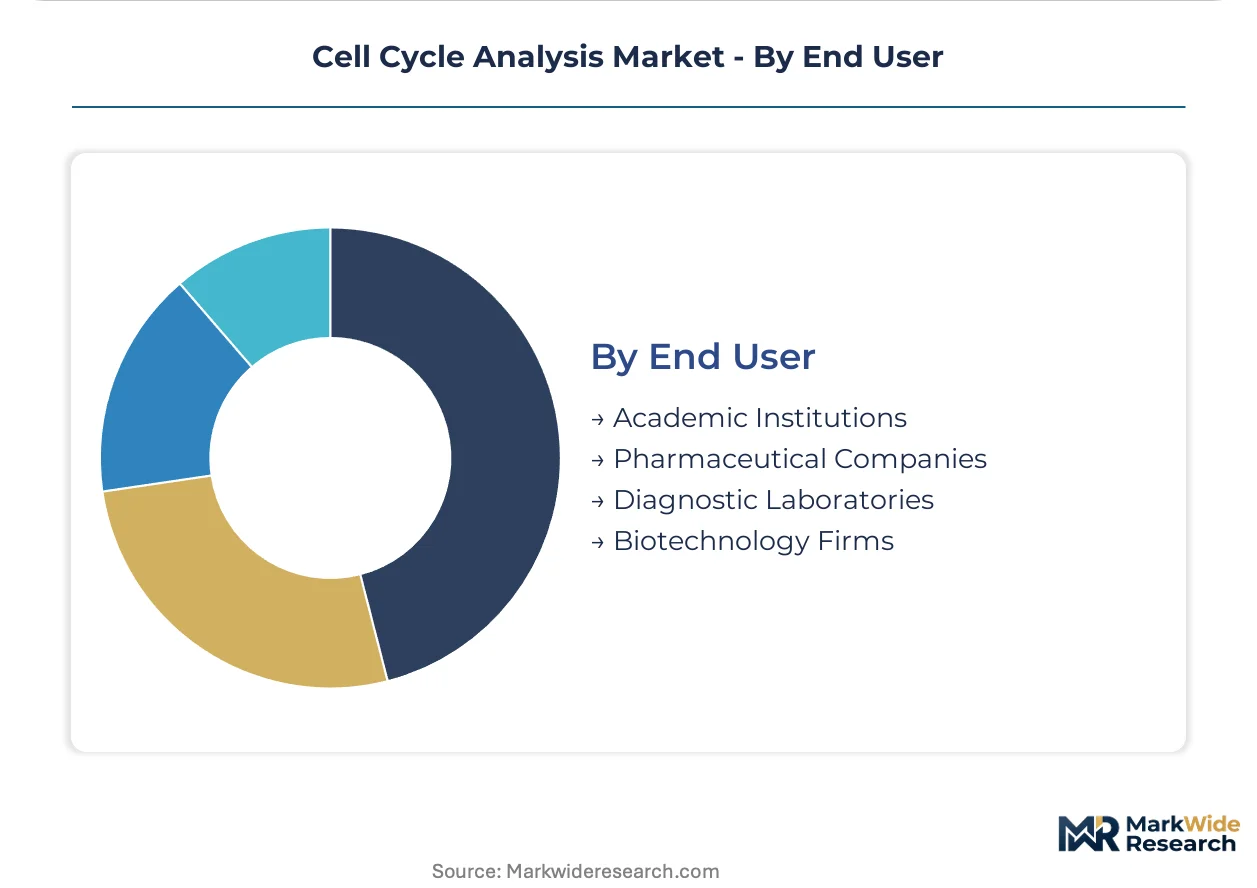
End User:
Volume scale and margin structure diverge across this category, with institutional procurement favoring competitive bidding while pharmaceutical accounts negotiate multi-year enterprise agreements bundling instrumentation, reagents, and technical support.
- Academic Institutions:University core facilities and medical school research laboratories operating under grant-funded budget constraints with extended capital replacement cycles. Price sensitivity drives multi-vendor reagent sourcing and open-platform instrument specifications. These end users generate high sample throughput but resist long-term consumable lock-in contracts.
- Pharmaceutical Companies:Integrated discovery and development organizations requiring GxP-compliant data integrity and regulatory documentation for IND-enabling studies. Massachusetts and Bavaria biotech clusters anchor procurement volume through centralized screening infrastructure and distributed satellite laboratory networks.
- Diagnostic Laboratories:Clinical reference laboratories and hospital pathology departments performing prognostic proliferation index testing. FDA oversight of in vitro diagnostic devices shapes product registration and quality system requirements.
- Biotechnology Firms:Venture-funded discovery-stage companies prioritizing workflow flexibility and rapid assay deployment over capital-intensive infrastructure commitment.
Pharmaceutical Companies command the largest contract values. Biotechnology Firms represent the steepest expansion trajectory as venture financing flows into phenotypic drug discovery platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors procurement volume for cell cycle analysis instrumentation through concentrated pharmaceutical discovery infrastructure. Biotech clusters in Cambridge and Boston generate sustained demand for kinetic proliferation platforms and GxP-compliant reagent supply. FDA oversight of companion diagnostic development shapes vendor qualification requirements across the region.
United States
FDA guidance on oncology therapeutic co-development is expanding contract research demand for standardized cell cycle assays in clinical trial settings. The agency's quality system regulation for in vitro diagnostic devices elevates validation documentation requirements. Massachusetts biotech clusters drive instrument procurement through centralized screening infrastructure and distributed satellite laboratory networks.
Germany
EMA's In Vitro Diagnostic Regulation is mandating clinical performance studies prior to CE marking for cell cycle assays marketed as companion diagnostics. Bavaria's academic medical centers and pharmaceutical research hubs anchor procurement volumes for flow cytometry systems. German chemical suppliers dominate high-purity nucleic acid dye production, creating upstream input concentration for assay manufacturers.
Japan
PMDA alignment with ICH quality guidelines is accelerating ISO 13485 certification requirements for reagent suppliers serving regenerative medicine translation. Academic consortia in Kanto and Kansai regions concentrate demand for stem cell proliferation monitoring tools. METI funding for advanced cell manufacturing infrastructure is pulling instrument investment toward GMP-compliant platforms.
India
CDSCO's streamlined medical device registration pathway and PLI scheme incentives are attracting contract assay development investment from multinational reagent suppliers. Biopharma manufacturing clusters in Maharashtra and Telangana are scaling cell line engineering workflows requiring proliferation analysis. DGFT export promotion frameworks support domestic production of diagnostic reagents for regional supply.
South Korea
MFDS quality system requirements for in vitro diagnostics are consolidating procurement around suppliers with established technical documentation capabilities. Seoul Capital Area biotech clusters drive adoption of live-cell imaging platforms for real-time compound mechanism studies. Government-funded national research consortia are integrating cell cycle state analysis with single-cell multi-omics workflows.
Cell Cycle Analysis Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized imaging modalities and AI-assisted analysis tools. The vendor base organizes around three maturity levels: integrated life sciences conglomerates with vertically reagent-instrument platforms, mid-scale specialists in fluorescence detection chemistry, and niche entrants in computational image analysis. Strategic moves center on service contract unbundling to separate instrument maintenance from reagent supply, plus backward integration into high-purity fluorophore manufacturing to secure input supply.
Among integrated platform providers, Thermo Fisher Scientific and BD Biosciences occupy positions exemplifying the capital-instrument-recurring-consumable model. Merck KGaA represents the European-centered chemical-reagent archetype with deep synthesis capabilities. These three entities anchor the competitive structure through divergent geographic emphases and portfolio breadth strategies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| BD Biosciences |
| Merck KGaA |
| Beckman Coulter |
| Bio-Rad Laboratories |
| PerkinElmer |
| Miltenyi Biotec |
| Abcam |
| Cell Signaling Technology |
| Others |
Supply Flow & Price Mechanics
High-purity fluorophore synthesis costs cascade through nucleic acid dye production into tiered reagent pricing, with German and Swiss chemical manufacturers capturing margin at the upstream bottleneck while assay suppliers in the United States and Germany absorb volatility through long-term pharmaceutical service contracts.
Pricing Analysis
Input-cost pass-through from concentrated fluorophore suppliers elevates pricing for propidium iodide and DAPI formulations, particularly affecting academic medical centers purchasing through grant-funded budgets. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified companion diagnostic reagents from research-grade kits and bulk unvalidated dyes. Cost compression in standard-tier consumables is intensifying because mid-sized pharmaceutical discovery groups are unbundling instrument maintenance from reagent supply agreements. Academic institutions represent the most price-sensitive buyer cohort, negotiating multi-vendor sourcing for open-platform compatibility, while pharmaceutical companies in Massachusetts and Bavaria accept premium pricing for GxP-compliant documentation and regulatory validation support.
Supply Chain Analysis
Workforce availability constraints in Swiss and German specialty chemical manufacturing limit expansion of high-purity nucleic acid dye capacity despite pharmaceutical demand growth. Supply concentrates in Germany, Switzerland, and the United States for fluorophore synthesis, instrument assembly, and reagent formulation respectively. Raw material dependencies include rare earth elements for laser optics, high-grade solvents for chromatography purification, and semiconductor components for detector arrays. Single-source vulnerability persists in Swiss-German fluorophore production, where two chemical suppliers dominate global output. Distribution runs through direct sales forces for pharmaceutical enterprise accounts, specialized distributors for academic core facilities, and OEM partnerships for instrument-integrated reagent bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell cycle analysis functions as a regulatory compounder where EMA MDR technical documentation mandates and FDA companion diagnostic guidance are consolidating procurement around validated suppliers with established quality systems.
For Market Incumbents: Deepen backward integration into high-purity fluorophore manufacturing to secure input supply against Swiss-German chemical supplier concentration. Expand ISO 13485-certified production capacity in Massachusetts and Bavaria to capture pharmaceutical contract research demand for GxP-compliant assays. Defensive positioning requires preemptive MDR technical documentation investment before smaller competitors achieve CE marking capability for companion diagnostic applications.
For New Entrants and Emerging Players: Launch via cloud-connected image cytometry platforms targeting biotechnology firms in the Seoul Capital Area and distributed discovery laboratories seeking workflow flexibility without capital-intensive infrastructure. White-space opportunity sits with AI-assisted mitotic figure classification for phenotypic screening, where incumbent platforms lack integrated machine learning. Penetrable entry points include EdU click-chemistry kits for mid-sized pharmaceutical oncology programs and API-compatible reagents for open-platform live-cell imaging systems.
For Investors and Strategic Acquirers: Consolidation pressure builds where MDR documentation capabilities separate viable companion diagnostic suppliers from research-grade reagent vendors facing regulatory exclusion. Long-term viability favors platforms combining instrument hardware with recurring consumable revenue and regulatory validation services. Acquisition target archetype: niche image cytometry specialists with established pharmaceutical customer relationships and draft clinical performance studies. Signal to watch is CDSCO registration acceleration for contract assay development facilities in Maharashtra and Telangana, indicating multinational supplier commitment to India biopharma manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Validation Pathway | EMA MDR clinical evidence requirements now govern CE marking for oncology proliferation assays. |
| Backward Integration into Fluorophore Synthesis | German and Swiss chemical supplier concentration creates input vulnerability for assay manufacturers. |
| AI-Assisted Image Analysis Development | Machine learning classification of mitotic figures automates proliferation scoring in phenotypic screens. |
| Service Contract Unbundling | Pharmaceutical buyers in Massachusetts and Bavaria now negotiate consumable pricing independently. |
| CDSCO Registration Acceleration | PLI scheme incentives attract contract assay development investment to India biopharma clusters. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flow cytometry core facility directors, pharmaceutical regulatory affairs leads, reagent procurement managers at biotechnology firms, and diagnostic laboratory quality officers with secondary validation against FDA 510(k) filings, EMA MDR technical documentation databases, ISO 13485 certification registries, and pharmaceutical pipeline disclosure records. Bottom-up triangulation across instrument installation data, reagent shipment volumes, and service contract values converged with top-down market sizing from industry association reports and trade flow analysis.
Segment-weighting approaches distributed value across flow cytometry systems, live-cell imaging platforms, DNA staining reagents, and proliferation assay kits according to pharmaceutical procurement patterns, academic grant funding cycles, and diagnostic laboratory capital replacement timelines. Technology dimensions modeled included fluorescence microscopy, image cytometry, mass cytometry, and automated cell counters across cancer research, stem cell research, drug discovery, and genetic engineering applications. CAGRs derived from regression analysis of historical instrument placements and consumable consumption rates, incorporating PMDA alignment with ICH quality guidelines and MFDS technical documentation requirements as regional regulatory drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluorophore supply disruption, EMA MDR implementation delays, or pharmaceutical pipeline cancellations. Practitioners should monitor CDSCO medical device registration volumes, ISO 13485 certification expansion rates, and live-cell imaging platform adoption in German biotech clusters for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Global Expression Vectors Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Latin America Flow Cytometry Market