
 Silver-Platinum Paste Market | 2026-2036
Silver-Platinum Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Silver-Platinum Paste Market Insights
High-purity silver-platinum formulations above 99.9% metal content is unwinding legacy cost structures across front-side metallization. DuPont leverages captive precious metal refining to sustain wafer-thin margin positions in solar paste supply. Mitsubishi Materials Corporation anchors East Asian supply through vertical control over sponge platinum feedstock.
Silver-platinum paste denotes a bimetallic thick-film conductor comprising 60-85% silver, 5-15% platinum, and glass frit in organic vehicle, fired at 650-850°C to form ohmic contacts on silicon substrates. Conductive paste commands the largest volume share as solar cell busbar designs shift toward finer line widths requiring lower contact resistance. Die attach paste represents the fastest-expanding category, driven by power module packaging for electric vehicle inverters where thermal cycling durability determines reliability grades.
China's NMPA and GB standards govern impurity thresholds in electronic-grade pastes, while REACH and RoHS in Europe restrict cadmium and lead content in imported formulations. The EU Green Deal's carbon border adjustments will reshape sourcing economics for Korean and Japanese exporters. Stakeholders must track how dual carbon goals in China and IRA domestic content rules in the United States reroute regional supply corridors before committing to capacity expansion.
Market Dynamics
Front-side metallization line widths below 20 microns are compressing silver loadings per cell while demanding higher platinum ratios to maintain conductivity, forcing paste formulators to recalibrate glass chemistry and organic vehicle viscosity simultaneously.
Growth Catalysts
- EU Green Deal carbon border adjustments:Korean and Japanese exporters are accelerating high-purity paste qualification to maintain access to European photovoltaic module assembly plants under tightening embodied carbon rules.
- Finer busbar architectures:Solar cell manufacturers in Japan and South Korea are adopting multi-busbar designs requiring paste formulations with enhanced rheological stability for screen printing below 25-micron apertures.
- Power module packaging:Die attach paste consumption is accelerating in electric vehicle inverter production where thermal cycling durability above 1000 cycles determines automotive reliability grades.
Market Restraints
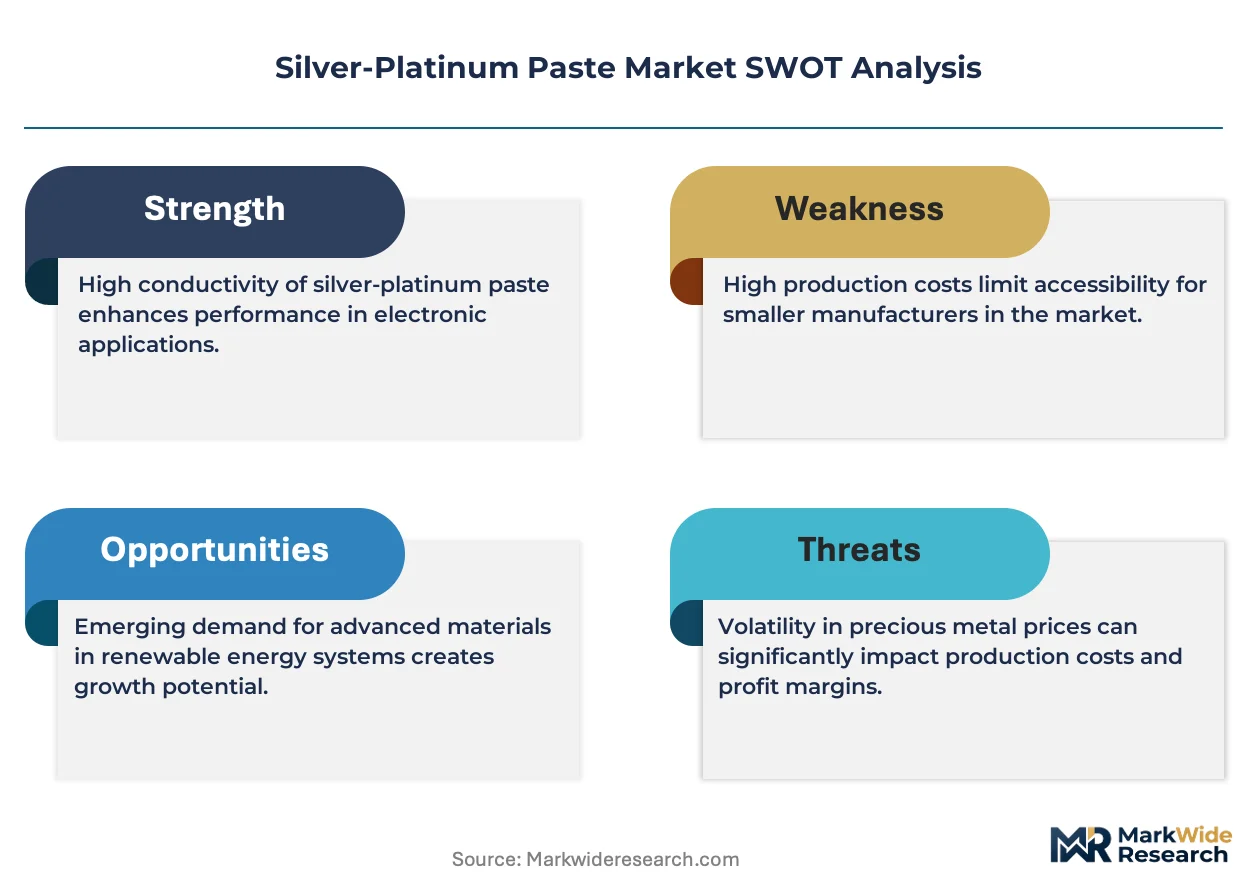
- Sponge platinum supply concentration:East Asian refiners control over 70% of electronic-grade platinum sponge feedstock, creating single-source vulnerability for paste manufacturers outside vertical supply arrangements.
- Silver price volatility:Paste formulators cannot fully pass through metal cost swings to solar cell producers locked into annual procurement contracts, squeezing compound margins during commodity spikes.
- High-temperature firing incompatibility:Perovskite-silicon tandem cell architectures require firing temperatures below 600°C, rendering conventional silver-platinum glass systems incompatible with next-generation substrates.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Domestic cell and module capacity expansion under production-linked incentives creates first-mover advantage for paste suppliers establishing local blending operations.
- Copper-platinum hybrid development:Convergence of electroplated copper seed layers with platinum capping pastes offers pathway to sub-15-micron metallization without silver content.
- Direct-to-cellmaker distribution:Bypassing traditional distributor networks in South Korea allows paste producers to capture technical service premiums through embedded formulation support.
Industry Challenges
- Glass frit formulation expertise:The specialized knowledge required to engineer lead-free borosilicate systems with matched thermal expansion to silicon resides with a shrinking cohort of senior materials scientists approaching retirement.
- Dual certification timelines:Simultaneous qualification under China's GB standards and Japan's JIS certification for the same paste SKU extends time-to-revenue by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver-Platinum Paste Market |
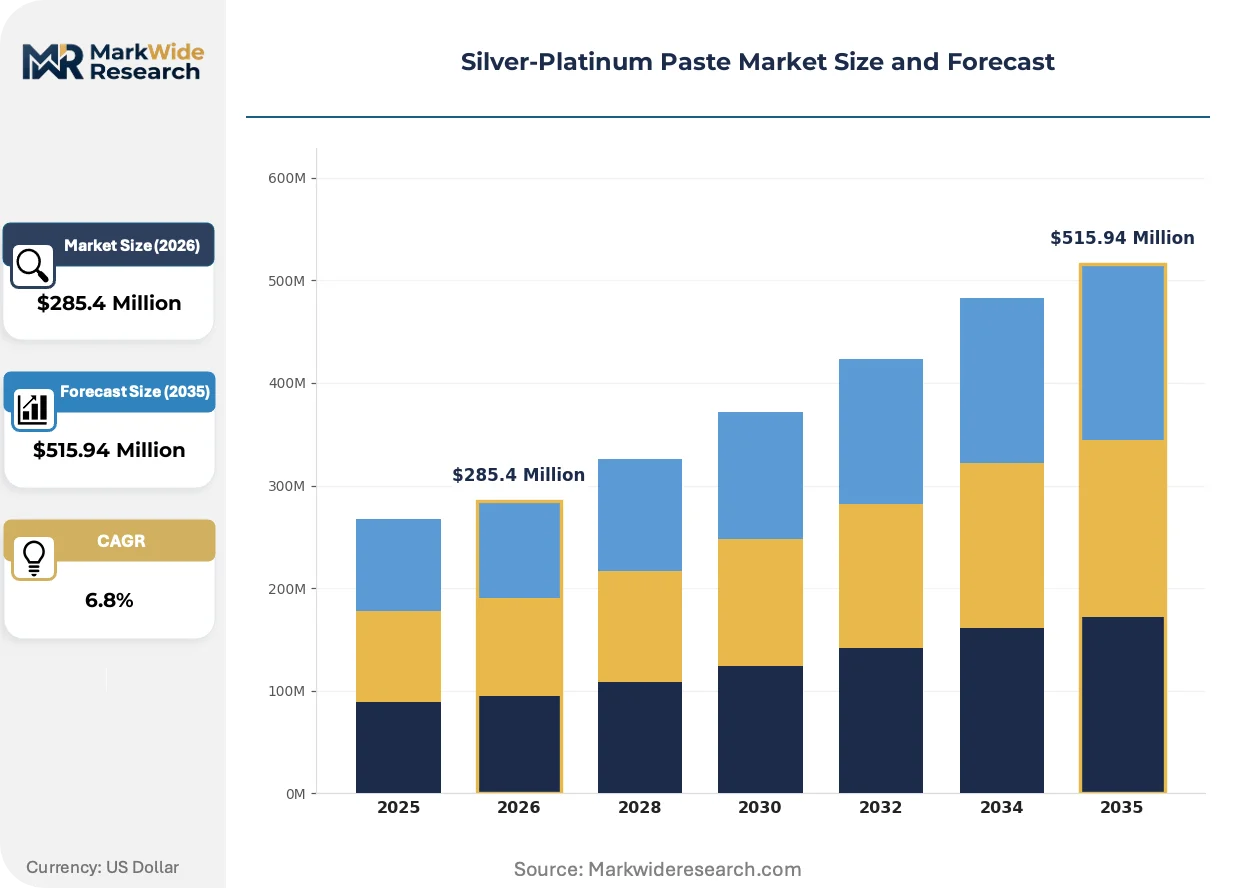
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Paste, Adhesive Paste, Shielding Paste, Die Attach Paste Industry Vertical: Electronics, Automotive, Aerospace, Telecommunications Application: Solar Cells, IC Packaging, Surface Mount Technology, PCBs Delivery Mode: Bulk Supply, Pre-Mixed Kits, Custom Formulations, Others |
| Companies Covered | Heraeus Holding, DuPont, Giga Solar Materials, Henkel AG & Co. KGaA, Mitsubishi Materials Corporation, Samsung SDI, Dowa Electronics Materials, Namics Corporation, Tokuyama Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver-Platinum Paste Market Trends and Innovations
Metallization chemistry is diverging along temperature and metal-loading axes as cell architectures split between passivated contact and heterojunction platforms with incompatible processing windows.
Nano-silver platinum core-shell particles are fragmenting traditional paste formulation approaches by enabling lower-temperature sintering while maintaining bulk conductivity. Heterojunction cell producers in Japan are adopting these structures to preserve amorphous silicon layer integrity during contact formation. The technology is fragmenting equipment supplier influence as inkjet and aerosol jet deposition methods displace screen printing for ultra-fine line applications.
REACH Annex XVII restrictions on cadmium and lead content are forcing reformulation of legacy glass frit systems across European-bound paste shipments. Paste producers are accelerating bismuth-zinc-borate glass development to meet impurity thresholds without sacrificing adhesion strength. Solar module assemblers in the Netherlands and Germany are demanding full material disclosure documentation upstream to avoid downstream liability under extended producer responsibility frameworks.
Cell manufacturers are consolidating paste qualification lists from twelve to four approved suppliers per metallization line to reduce process variation. Technical service contracts now bundle formulation customization with real-time viscosity monitoring during production runs. South Korean solar producers are driving this consolidation most aggressively, linking supplier retention to defect rate performance in busbar pull testing.
Silver-Platinum Paste Market Segmentation
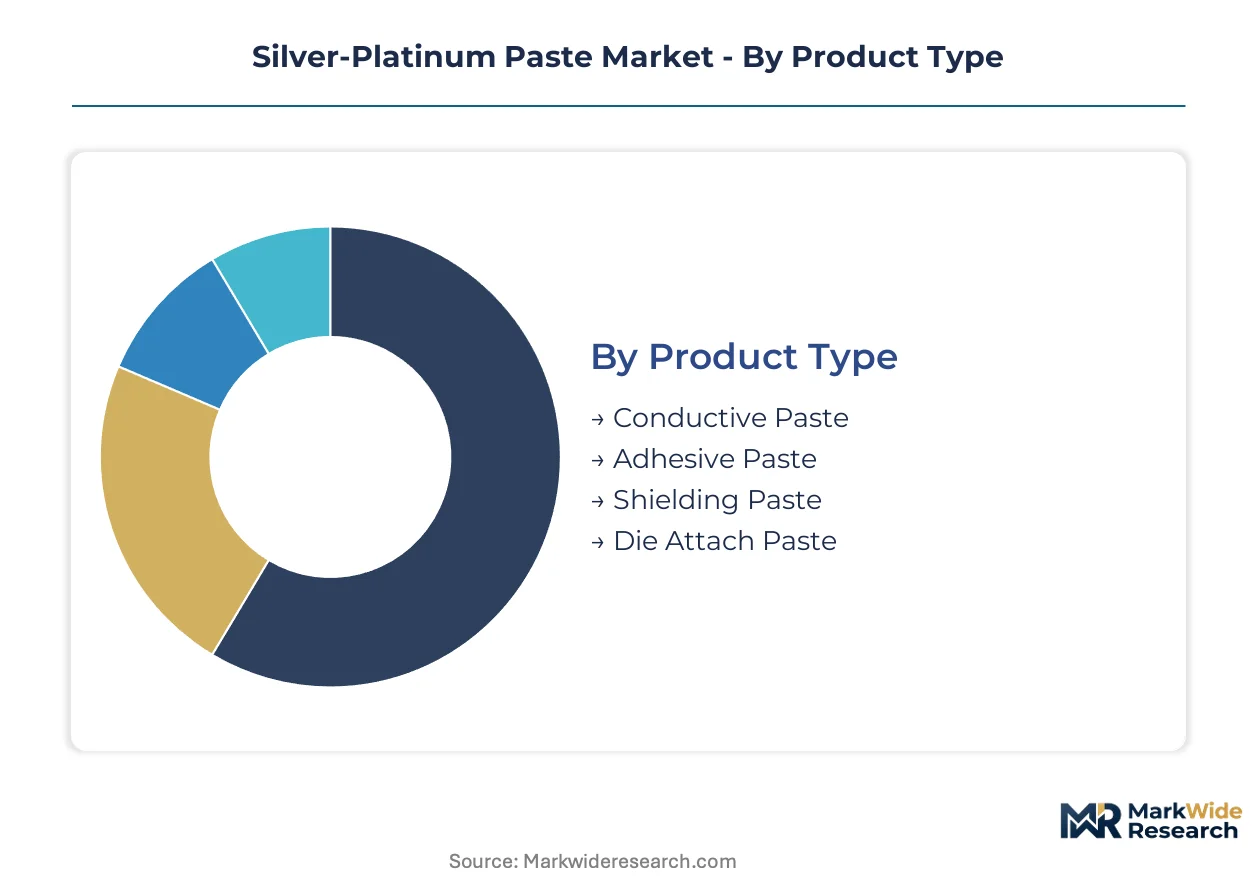
Silver-platinum paste formulations diverge sharply across metallization temperatures, adhesion chemistry, and thermal cycling requirements. Each segment demands distinct glass frit systems and organic vehicle engineering that locks suppliers into specialized competency clusters.
Product Type:
Margin pools concentrate in formulations serving high-reliability thermal cycling environments where platinum loading premiums justify technical service bundling.
- Conductive Paste:Bimetallic compositions with 60-85% silver and 5-15% platinum in lead-free borosilicate glass matrices fire at 650-850°C to form ohmic contacts. Solar cell manufacturers in Japan and South Korea are compressing line widths below 20 microns, forcing simultaneous recalibration of glass chemistry and organic vehicle viscosity to maintain conductivity with reduced silver loadings per cell.
- Die Attach Paste:High-temperature formulations engineered for power module packaging in electric vehicle inverters where thermal cycling durability above 1000 cycles determines automotive reliability grades. Korean automotive tier-1 suppliers are qualifying these pastes under MFDS frameworks for silicon carbide module assembly.
- Adhesive Paste:Lower-temperature curing systems for substrate bonding in consumer electronics assemblies where JIS certification governs outgassing specifications.
- Shielding Paste:Electromagnetic interference coatings for telecommunications enclosures requiring consistent sheet resistance across batch variations.
Conductive paste holds installed capacity. Die attach paste is rotating up the share rankings.
Industry Vertical:
Volume concentration tracks regulatory intensity, with carbon border adjustments and domestic content rules rerouting procurement corridors.
- Electronics:Precision metallization for IC packaging and surface mount applications where METI efficiency mandates in Japan drive sub-25-micron aperture printing requirements. Screen printing equipment suppliers are fragmenting as inkjet and aerosol jet methods displace traditional deposition for ultra-fine line formation.
- Automotive:Power electronics packaging for electric vehicle traction inverters where thermal management specifications under EU Green Deal embodied carbon rules are reshaping Korean and Japanese exporter qualification timelines.
- Aerospace:High-reliability die attach for satellite power systems requiring hermetic sealing compatibility.
- Telecommunications:5G base station shielding and RF module packaging where REACH Annex XVII cadmium restrictions force bismuth-zinc-borate glass reformulation.
Electronics commands the volume base. Automotive is climbing the fastest on inverter buildout.
Application:
Customer consolidation from twelve to four approved suppliers per metallization line is compressing formulation differentiation into technical service bundling.
- Solar Cells:Front-side and rear-side metallization for crystalline silicon and heterojunction architectures. Perovskite-silicon tandem cells require firing below 600°C, rendering conventional silver-platinum glass systems incompatible and fragmenting chemistry roadmaps.
- IC Packaging:Wire bond pad metallization and flip-chip underfill applications where dual certification under China's GB standards and Japan's JIS extends time-to-revenue by 14-18 months for the same paste SKU.
- Surface Mount Technology:Solder replacement pastes for high-temperature component attachment in automotive ECUs.
- PCBs:Through-hole plating and via fill for high-frequency circuit boards where impedance control demands consistent particle size distribution.
Solar cells anchor the demand base. IC packaging is gaining share fastest on advanced packaging expansion.
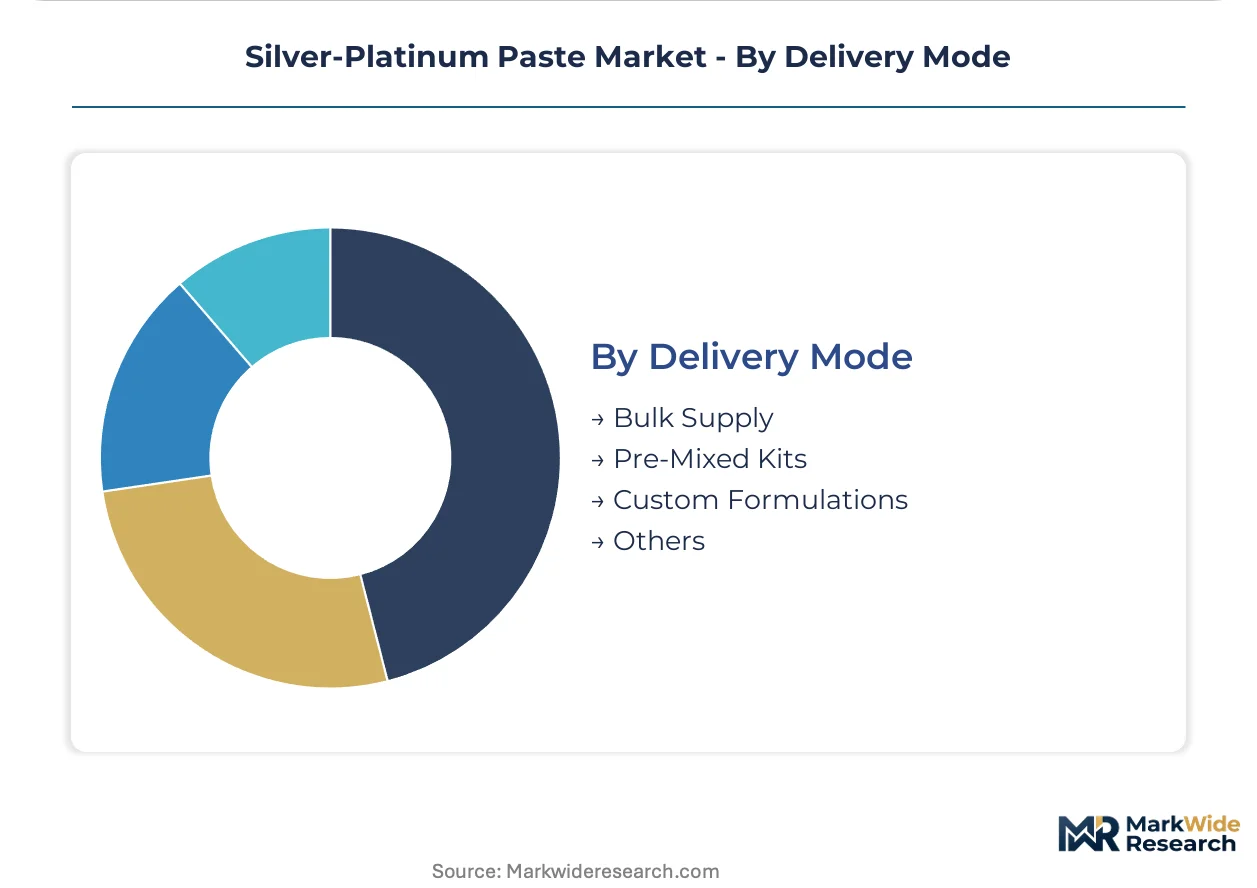
Delivery Mode:
Supply configuration determines working capital intensity and technical support embedding depth.
- Bulk Supply:Drum quantities for high-volume solar cell metallization lines where annual procurement contracts lock silver price exposure with paste formulators unable to fully pass through commodity spikes.
- Pre-Mixed Kits:Standardized viscosity formulations with matched squeegee and screen specifications for rapid line qualification.
- Custom Formulations:Co-development arrangements with South Korean solar producers linking supplier retention to defect rate performance in busbar pull testing and real-time viscosity monitoring during production runs.
- Others:Emergency spot orders and trial quantities for new process validation.
Bulk supply dominates the tonnage base. Custom formulations are rotating up the margin rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sponge platinum refining concentrates in East Asian supply corridors, while solar cell metallization demand clusters in technology-intensive manufacturing belts across three continents. Regulatory fragmentation around carbon border adjustments and domestic content rules is rerouting procurement corridors for paste formulators.
China
Photovoltaic module assembly expansion under the dual carbon goals and GB standards compliance is tightening impurity thresholds for electronic-grade pastes. The NMPA and MIIT frameworks govern metal content specifications for solar cell producers in Jiangsu and Zhejiang provinces. Yangtze River Delta manufacturing clusters are consolidating paste qualification lists as cell manufacturers compress supplier bases from twelve to four approved vendors per metallization line.
Japan
Heterojunction cell producers in Kansai and Chubu regions are adopting nano-silver platinum core-shell particles to preserve amorphous silicon layer integrity during contact formation. METI efficiency mandates drive sub-25-micron aperture printing requirements for precision electronics manufacturing. Osaka-based solar producers are linking supplier retention to defect rate performance in busbar pull testing and real-time viscosity monitoring protocols.
South Korea
Automotive tier-1 suppliers are qualifying die attach pastes under MFDS frameworks for silicon carbide module assembly in electric vehicle inverter production. Samsung SDI and affiliated power electronics fabricators in Gyeonggi Province are demanding thermal cycling durability above 1000 cycles for automotive reliability grades. Korean solar producers are driving supplier consolidation most aggressively, bypassing traditional distributor networks to capture technical service premiums.
Germany
Solar module assemblers in Bavaria and North Rhine-Westphalia are demanding full material disclosure documentation to avoid downstream liability under extended producer responsibility frameworks. REACH Annex XVII restrictions on cadmium and lead content are forcing bismuth-zinc-borate glass reformulation for European-bound paste shipments. The EU Green Deal's carbon border adjustments are reshaping qualification timelines for Korean and Japanese exporters seeking access to photovoltaic module assembly plants.
United States
IRA domestic content rules are rerouting regional supply corridors for paste manufacturers evaluating capacity expansion commitments. Precision electronics fabricators in Arizona and Texas are navigating dual certification requirements as NHTSA automotive standards intersect with state-level clean energy procurement mandates. Southwest manufacturing clusters are emerging as alternative qualification sites for paste formulators seeking to circumvent carbon border exposure on European exports.
Silver-Platinum Paste Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the silver-platinum paste value chain. The market structure consolidates around precious metal refiners with captive sponge platinum supply and specialized formulators with glass frit chemistry expertise. Three archetypes dominate: vertically integrated materials conglomerates controlling upstream sponge feedstock, dedicated paste formulators bundling technical service with formulation customization, and diversified electronics chemical suppliers leveraging distribution scale. Competitive dynamics center on dual certification timeline compression and direct-to-cellmaker distribution bypass.
Among East Asian materials conglomerates, Mitsubishi Materials Corporation and Dowa Electronics Materials exemplify the upstream-integrated archetype through sponge platinum refining positions. DuPont occupies a position representing the formulation-specialist tier with captive precious metal refining capabilities. These three anchors demonstrate how vertical control over feedstock or glass chemistry expertise determines margin sustainability in wafer-thin solar paste supply.
| Leading Market Players |
|---|
| Heraeus Holding |
| DuPont |
| Giga Solar Materials |
| Henkel AG & Co. KGaA |
| Mitsubishi Materials Corporation |
| Samsung SDI |
| Dowa Electronics Materials |
| Namics Corporation |
| Tokuyama Corporation |
| Others |
Pricing and Supply Chain Analysis
Nano-silver platinum core-shell particle adoption is displacing conventional paste formulations, simultaneously shifting procurement geography toward Japanese heterojunction cell producers and compressing pricing premiums for legacy high-temperature glass systems. This substitution dynamic concentrates margin pressure on formulators lacking low-temperature sintering capabilities while rewarding suppliers with captive precious metal refining positions.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European-bound shipments, separating lead-free bismuth-zinc-borate certified formulations from legacy cadmium-tolerant grades. Price differentiation centers on dual GB-JIS certification status and embedded carbon documentation under EU Green Deal border adjustments. Pricing pressure stems from solar cell manufacturers consolidating supplier bases from twelve to four approved vendors per line. Bulk supply contracts for high-volume metallization show highest price sensitivity, while custom formulation tiers with real-time viscosity monitoring retain pricing power.
Supply Chain Analysis
Sponge platinum refining chokepoints in Japan and South Korea anchor upstream supply, with East Asian refiners controlling over seventy percent of electronic-grade feedstock. The supply chain draws from silver mining concentrates, platinum group metal sponge, and borosilicate glass frit precursors. Single-source vulnerability in platinum sponge creates structural risk for paste manufacturers outside vertical arrangements. Distribution runs through direct-to-cellmaker channels in South Korea, bypassing traditional distributor networks to capture technical service premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling now expands faster than base paste volumes, as South Korean solar producers link supplier retention to real-time viscosity monitoring and defect rate performance in busbar pull testing. This service-attach layer outpaces hardware growth across precision metallization applications.
For Market Incumbents: Compound formulation customization capabilities with embedded process support to defend against copper-platinum hybrid substitution threats. Deepen captive precious metal refining positions to offset silver price volatility squeezing compound margins. Prioritize dual GB-JIS certification pipeline compression to accelerate time-to-revenue against emerging low-temperature sintering specialists. For New Entrants and Emerging Players: India's PLI scheme certification fast-track offers entry pathway into domestic solar cell capacity expansion. Target die attach paste qualification for silicon carbide power modules under MFDS frameworks, where thermal cycling durability requirements create specialist margin pools. Pursue direct technical service partnerships with automotive tier-1 suppliers to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors glass frit chemistry specialists with retiring senior materials scientist cohorts. Long-term viability over the mid-term horizon rests on acquiring formulation expertise in lead-free borosilicate systems. Watch nano-silver platinum core-shell particle adoption curves as inflection indicator for conventional paste obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Compression | Simultaneous GB-JIS qualification reduces time-to-revenue for paste SKUs entering Asian solar markets. |
| Backward Integration into Sponge Platinum | Captive refining secures feedstock access against East Asian supply concentration vulnerabilities. |
| Low-Temperature Sintering Development | Perovskite-silicon tandem compatibility opens next-generation cell architecture procurement channels. |
| Direct-to-Cellmaker Distribution | Bypassing Korean distributor networks captures technical service premiums and locks in viscosity monitoring contracts. |
| Copper-Platinum Hybrid Pilot Programs | Sub-15-micron metallization pathways without silver content hedge against commodity price volatility exposure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the value chain, including solar cell metallization engineers, power module packaging specialists at automotive tier-1 suppliers, precious metal procurement leads, glass frit R&D directors, and regulatory affairs managers navigating REACH and GB standards. Secondary validation drew from customs trade data, SEC filings of listed materials conglomerates, MIIT production statistics, and EIA solar deployment tracking. Bottom-up paste volume modeling triangulated against top-down solar cell production capacity estimates.
Across the analysis window, forecasts segmented by product type, industry vertical, application, and delivery mode incorporated firing temperature compatibility matrices and regional regulatory cluster effects. CAGRs derived from weighted average of historical price-volume relationships and projected substitution elasticities for copper-platinum hybrid technologies. Forecast inputs included sponge platinum supply concentration indices and solar cell busbar architecture evolution timelines.
Underlying assumptions cover heterojunction cell production scaling and EU Green Deal carbon border adjustment implementation, with deviation risk concentrated in perovskite-silicon tandem commercialization pace and silver price volatility spikes. Practitioners should keep alternative scenarios live as low-temperature sintering technology maturation and IRA domestic content rule enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Copper Sputtering Target Market
Metals
Europe Aluminium Cans Market
Metals
Europe Metal Casting Market
Metals
Steel Wire Market
Metals
Battery Metals Market
Metals
Stainless Steel 400 Series Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Aluminium Rolled Products Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Tinplate Market
Metals
Nickel Sulfate Market
Metals
Metal Forging Parts Market
Metals
Steel Drums and Ibcs Market
Metals
Global Tantalum Market
Metals
Palladium Market