
 Sodium Tungstate Dihydrate Market | 2026-2036
Sodium Tungstate Dihydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Tungstate Dihydrate Market Analytics
The EU Green Deal's chemical sector decarbonization targets is realigning procurement priorities for sodium tungstate dihydrate across European catalyst supply chains. H.C. Starck leverages its integrated tungsten refining operations in Germany to sustain premium-grade output for medical and electronics clients. China Minmetals Corporation anchors regional supply through its control of domestic tungsten concentrate sources. Ganzhou Grand Sea W& Mo Group differentiates via specialized production of high-purity analytical grades for research institutions.
Sodium tungstate dihydrate, Na₂WO₄·2H₂O, is a crystalline inorganic salt produced by alkaline digestion of tungsten ores followed by crystallization, typically assaying 99.5% purity on an anhydrous basis and serving primarily as a tungsten source for homogeneous and heterogeneous catalysis. The material functions as a precursor in the manufacture of tungsten oxides, tungstic acid, and various tungstate salts employed in electroplating, flame retardants, and diagnostic imaging contrast agents. Technical grade material dominates volume shipments to chemical manufacturers running large-scale catalytic processes, while reagent grade commands margin concentration from pharmaceutical and electronics end users. The catalysts application segment leads absolute consumption, though medical applications exhibit the fastest trajectory as radiopaque compound formulations expand.
REACH registration requirements and the EU F-Gas Regulation shape product specifications and market access conditions for European chemical distributors handling sodium tungstate dihydrate. China's SAMR enforces GB standards on industrial chemical purity that directly determine which grades qualify for domestic catalyst manufacturing. The US EPA maintains reporting thresholds under TSCA that affect import volumes and documentation burdens for American electronics manufacturers. Stakeholders must monitor evolving tungsten concentrate export restrictions and purity certification requirements to secure supply continuity.
Market Dynamics
The EU Green Deal's chemical sector decarbonization targets are compressing procurement timelines for sodium tungstate dihydrate across European catalyst supply chains, forcing buyers to pre-qualify suppliers against tightening purity specifications.
Growth Catalysts
- REACH compliance mandates:The European Union's F-Gas Regulation and REACH registration requirements are eliminating lower-purity grades from catalyst supply chains, redirecting volume toward certified reagent-grade producers.
- Petrochemical cracking expansion:Catalyst manufacturers in Germany and China are expanding alkaline digestion capacity to secure tungsten feedstock for fluid catalytic cracking units processing heavier crude slates.
- Yangtze River Delta concentration:Chemical cluster density around Shanghai-Ningbo is generating procurement efficiencies that lower logistics costs for tungstate buyers serving domestic electroplating operations.
Market Restraints
- Tungsten concentrate export controls:China's Ministry of Commerce maintains export licensing for ammonium paratungstate intermediates, constraining non-integrated processors in Europe and North America.
- Alkali digestion energy intensity:Sodium hydroxide and thermal inputs account for substantial production cost volatility, compressing margins for crystallization-stage operators lacking captive power.
- Phosphotungstic acid substitution:Heteropoly acid catalysts are displacing simple tungstate salts in certain oxidation reactions, threatening volume in fine chemical synthesis applications.
Strategic Opportunities
- India BIS certification pathway:India's Bureau of Indian Standards is formalizing purity grades for imported industrial chemicals, creating first-mover advantage for analytical-grade producers establishing testing partnerships.
- Radiopaque compound formulations:Medical imaging contrast agent developers are specifying ultra-high-purity dihydrate for barium tungstate precursors, opening margin-differentiated demand outside commodity catalyst channels.
- Dual carbon policy alignment:China's MEE carbon intensity benchmarks for chemical producers are incentivizing closed-loop crystallization processes that reduce wastewater discharge and qualify for green financing.
Industry Challenges
- ICP-MS analytical capability gaps:Trace metal certification to 99.95% purity requires inductively coupled plasma mass spectrometry infrastructure that smaller crystallization houses lack, creating bottlenecks in qualification timelines.
- Legacy ERP integration friction:Batch-level serialization for REACH compliance is forcing mid-scale producers to replace legacy manufacturing execution systems, compressing working capital during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Tungstate Dihydrate Market |
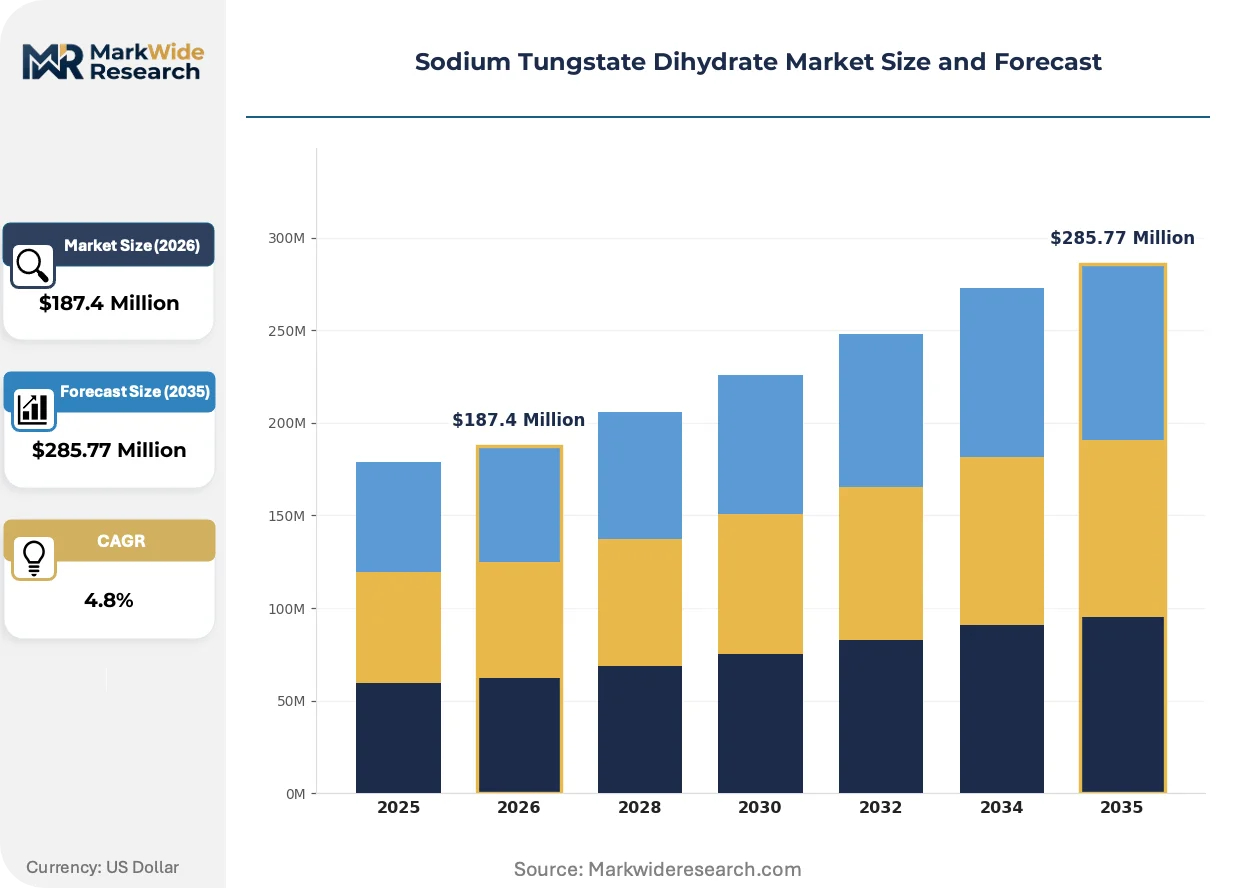
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Technical Grade, Analytical Grade, Industrial Grade Application: Catalysts, Coatings, Electronics, Medical Applications End User: Chemical Manufacturers, Pharmaceuticals, Electronics Manufacturers, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Retailers, Retail Stores |
| Companies Covered | China Minmetals Corporation, Alfa Aesar, H.C. Starck, Ningxiang Changyi, Ganzhou Grand Sea W& Mo Group, Anchor Chemicals, Global Tungsten & Powders Corp., CF Tungsten, Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Tungstate Dihydrate Market Evolving Landscape
Alkaline digestion-crystallization process control technologies are tightening assay consistency while regulatory purity mandates are fragmenting grade specifications across end-use verticals.
Solvent-free crystallization control systems are consolidating quality variance in sodium tungstate dihydrate production. Catalyst manufacturers in the Rhine-Ruhr corridor are adopting these systems to meet REACH-registered batch consistency requirements. The technology is consolidating supplier tiers by disqualifying operations unable to maintain sub-50ppm trace metal variation.
REACH registration requirements are tightening documentary burdens for tungstate importers into the European Union. ECHA's updated guidance on substance identity criteria is forcing crystallization houses to standardize hydrate stoichiometry declarations. Medical and electronics end users are responding by consolidating qualified supplier lists to pre-registered entities with full dossier compliance.
Buyers are compressing supplier qualification cycles from multi-year frameworks to annual re-certification against evolving purity benchmarks. Chemical distributors serving German automotive catalyst houses are disintermediating non-specialized traders unable to provide batch-level certificates of analysis. This behavioral shift is most visible in procurement offices along the Antwerp-Rotterdam chemical corridor, where integrated tungsten refiners are capturing share from merchant traders.
Sodium Tungstate Dihydrate Market Segmentation
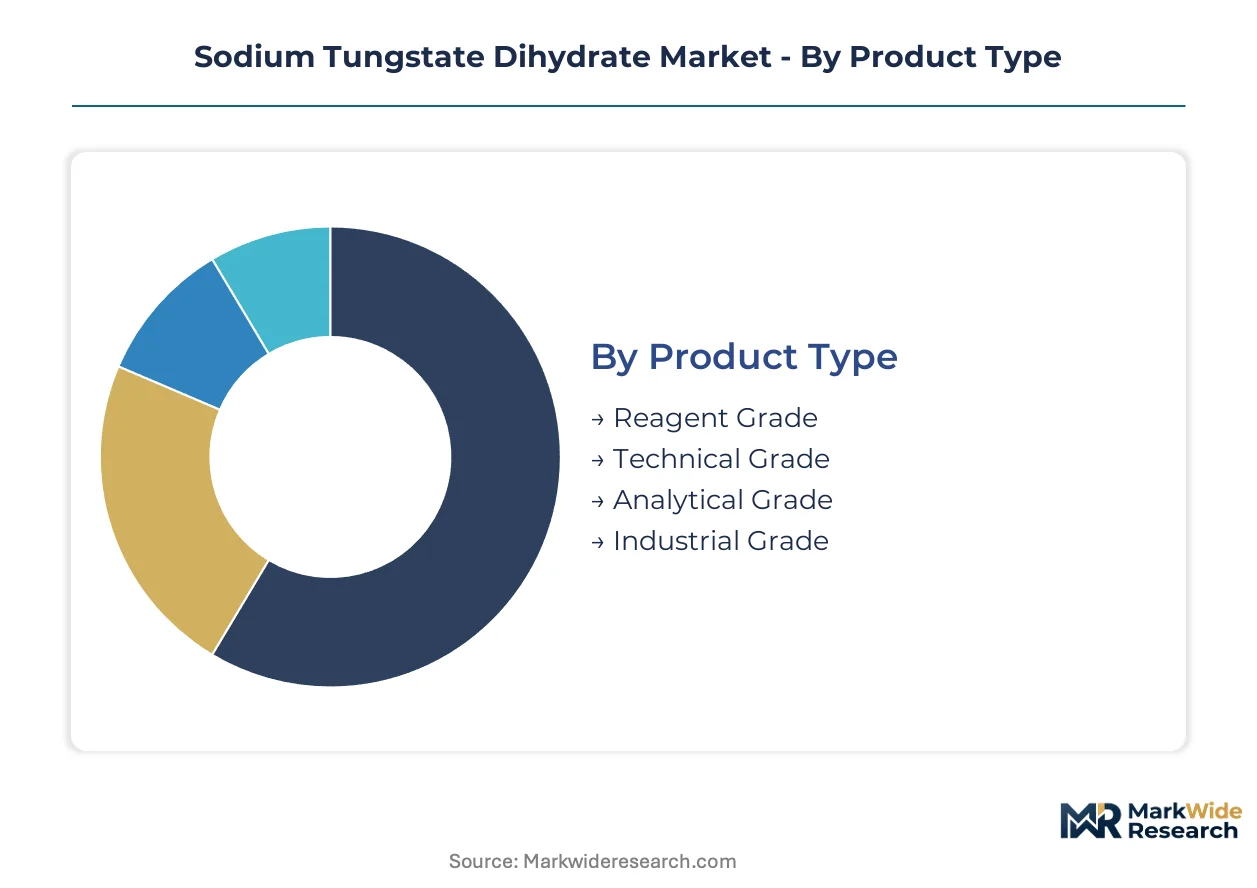
Segmentation in sodium tungstate dihydrate markets reflects divergent purity requirements across catalytic, medical, and electronics applications. Buyers select grades based on trace metal tolerances, certification burdens, and end-use regulatory exposure rather than commodity pricing alone.
Product Type:
Buyers in this category differentiate by analytical capability requirements and documentary compliance burdens rather than unit economics.
- Reagent Grade:Material assays 99.5% minimum purity on an anhydrous basis with full trace metal certification via ICP-MS. Demand concentrates in German pharmaceutical catalyst houses and Chinese research institutions where REACH and GB standards mandate batch-level documentation.
- Technical Grade:Standard crystalline product serving fluid catalytic cracking and electroplating operations. Volume clusters in the Yangtze River Delta and Rhine-Ruhr corridor where petrochemical manufacturers prioritize feedstock cost over sub-50ppm trace control.
- Analytical Grade:Ultra-high-purity material for quantitative analysis and reference standards. Japanese and Swiss laboratory suppliers specify this grade for tungstate calibration solutions.
- Industrial Grade:Bulk material for flame retardant and pigment manufacturing. Chinese construction chemical producers drive procurement through direct long-term contracts.
Volume sits with Technical Grade; growth tilts toward Reagent Grade.
Application:
End-use selection tracks regulatory intensity and performance specifications across process chemistry and functional materials.
- Catalysts:Homogeneous and heterogeneous catalysis for petrochemical cracking and oxidation processes. German automotive catalyst manufacturers and Chinese refinery operators anchor procurement, with ECHA REACH registration and SAMR GB compliance determining supplier qualification.
- Medical Applications:Radiopaque compound precursors and diagnostic imaging contrast agents. Developers in the US and EU specify ultra-high-purity dihydrate for barium tungstate formulations, with FDA and EMA purity mandates driving specification divergence from industrial grades.
- Coatings:Electroplating baths and corrosion-resistant surface treatments. Demand concentrates in Shanghai-Ningbo electroplating clusters serving automotive and electronics hardware.
- Electronics:Tungsten oxide precursors for semiconductor and display manufacturing. South Korean and Taiwanese electronics material suppliers specify tight hydrate stoichiometry for vapor deposition processes.
Catalysts command absolute volume; Medical Applications expand most quickly.
End User:
Procurement scale and technical service requirements separate commodity buyers from specification-driven purchasers.
- Chemical Manufacturers:Large-scale alkaline digestion and crystallization houses purchasing technical grade for captive catalytic process use. Integrated tungsten refiners in Germany and China dominate this segment through captive concentrate supply.
- Pharmaceuticals:Contrast agent and active pharmaceutical ingredient producers requiring reagent grade with full regulatory dossiers. EMA and FDA inspection readiness determines supplier selection.
- Electronics Manufacturers:Display and semiconductor material suppliers specifying hydrate stoichiometry for chemical vapor deposition. Japanese and South Korean electronics conglomerates drive premium grade procurement.
- Research Institutions:Universities and national laboratories purchasing analytical grade in small lots. Funding agency procurement rules favor pre-qualified distributors with REACH-registered inventory.
Chemical Manufacturers move the most tonnage; Pharmaceuticals generate the steepest margin expansion.
Distribution Channel:
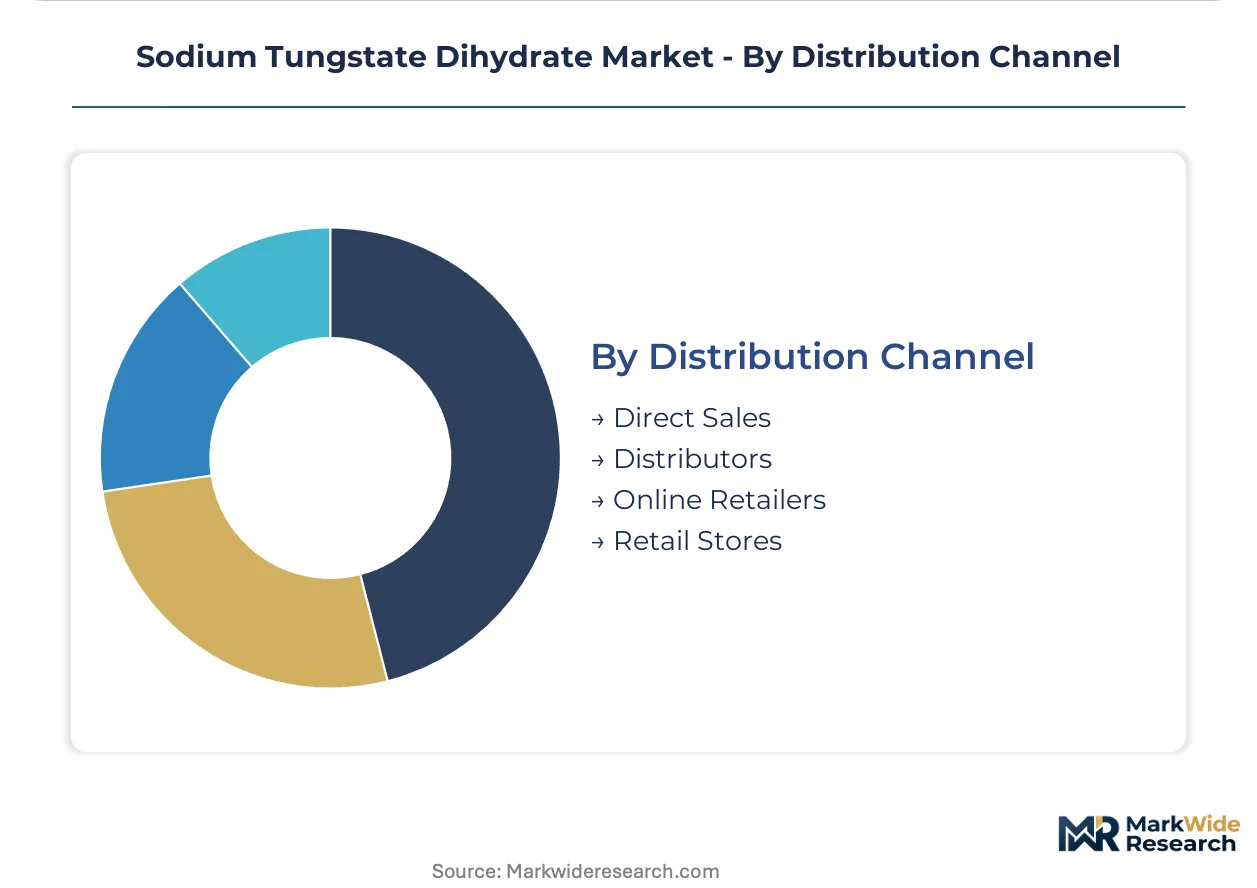
Channel selection reflects lot size, documentation urgency, and geographic proximity to qualified inventory.
- Direct Sales:Long-term contracts between integrated tungsten refiners and large catalyst houses. H.C. Starck and China Minmetals leverage direct relationships to bypass distributor margins on multi-ton orders.
- Distributors:Specialized chemical distributors serving mid-scale electroplating and electronics manufacturers. Antwerp-Rotterdam corridor distributors are consolidating share by offering REACH-compliant batch serialization.
- Online Retailers:E-commerce platforms for small-lot analytical and reagent grade sales. Research institutions in India and Southeast Asia increasingly route procurement through B2B marketplaces.
- Retail Stores:Limited channel for emergency replenishment of standard laboratory chemicals. Local supply houses in industrial zones serve maintenance and small-batch production needs.
Direct Sales anchor volume throughput; Distributors capture specification-driven premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European catalyst procurement for sodium tungstate dihydrate, while the Yangtze River Delta chemical cluster drives Asia-Pacific volume concentration. Procurement patterns diverge sharply between REACH-regulated European buyers and GB standards-driven Chinese manufacturers.
Germany
H.C. Starck leverages captive tungsten refining in the Rhine-Ruhr corridor to serve automotive catalyst manufacturers. ECHA REACH registration requirements eliminate non-compliant crystallization houses from qualified supplier lists. The Leverkusen-Düsseldorf chemical belt concentrates fluid catalytic cracking catalyst production for export across the European Union.
China
China Minmetals Corporation anchors domestic supply through control of Jiangxi tungsten concentrate sources. SAMR GB standards on industrial chemical purity determine qualification for domestic catalyst manufacturing. The Shanghai-Ningbo electroplating cluster generates concentrated demand for technical-grade material serving automotive hardware exports.
United States
EPA TSCA reporting thresholds shape import documentation burdens for electronics manufacturers specifying tungstate precursors. FDA purity mandates for radiopaque compound formulations drive reagent-grade procurement from pre-qualified distributors. The Texas-Louisiana Gulf Coast petrochemical corridor sustains catalyst demand for heavy crude processing units.
Japan
METI industrial chemical guidelines align hydrate stoichiometry specifications with semiconductor material requirements. JIS standards certification separates qualified suppliers from commodity traders in electronics supply chains. The Osaka-Kobe manufacturing belt concentrates demand for ultra-high-purity grades serving display and chip fabrication.
India
Bureau of Indian Standards is formalizing purity grades for imported industrial chemicals, creating qualification pathways for analytical-grade producers. CDSCO pharmaceutical regulations drive contrast agent developers toward documented reagent-grade sourcing. The Gujarat chemical cluster around Vadodara-Ankleshwar is expanding electroplating capacity for automotive component exports.
Sodium Tungstate Dihydrate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and documentation-capability dimensions. The vendor base stratifies into integrated tungsten refiners, specialized crystallization houses, and distributor-intermediaries with compliance infrastructure. Three archetypes dominate: captive-concentrate refiners, reagent-grade specialists, and REACH-registered distributors. Capacity expansion and backward integration into concentrate supply represent the two dominant competitive vectors.
Among integrated refiners, China Minmetals Corporation and H.C. Starck occupy positions anchored by captive raw material access. Ganzhou Grand Sea W& Mo Group exemplifies the specialist tier focused on analytical-grade production. These three entities represent the structural poles around which mid-scale crystallization houses and compliance-focused distributors organize their market participation.
| Leading Market Players |
|---|
| China Minmetals Corporation |
| Alfa Aesar |
| H.C. Starck |
| Ningxiang Changyi |
| Ganzhou Grand Sea W& Mo Group |
| Anchor Chemicals |
| Global Tungsten & Powders Corp. |
| CF Tungsten |
| Sigma-Aldrich |
| Others |
Value Network & Pricing Analysis
Ammonium paratungstate spot pricing cascades through sodium tungstate dihydrate supply chains, compressing margins for non-integrated crystallization houses while amplifying pricing power for captive-concentrate refiners in Germany and China. REACH certification premiums and GB standards compliance costs stratify procurement tiers, with medical-grade buyers absorbing purity-driven markups that petrochemical catalyst houses resist.
Pricing Analysis
Catalyst yield-per-ton performance anchors value-based pricing for reagent-grade sodium tungstate dihydrate, separating qualified suppliers from commodity traders. Certification grade and ICP-MS trace metal documentation drive price differentiation, with ECHA-registered batches commanding substantial premiums over technical-grade alternatives. Cost compression in technical-grade channels is intensifying because alkali digestion energy inputs have escalated, squeezing crystallization-stage operators lacking captive power. Petrochemical catalyst manufacturers exhibit highest price sensitivity, while pharmaceutical contrast agent developers prioritize purity documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in the Antwerp-Rotterdam corridor and Shanghai-Ningbo hub handle qualified inventory for REACH-registered and GB-compliant grades respectively. Supply concentrates in China, Germany, and the United States, with Jiangxi tungsten concentrate and Rhine-Ruhr refining capacity anchoring upstream control. The supply chain draws from ammonium paratungstate intermediates, sodium hydroxide, and thermal energy inputs. Single-source vulnerability around Chinese concentrate export licensing threatens European and North American non-integrated processors. Distribution runs through direct long-term contracts for multi-ton catalyst orders and specialized chemical distributors for mid-scale electronics and electroplating buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable players, with REACH registration timelines and ICP-MS infrastructure requirements forcing weaker crystallization houses into acquisition or exit.
For Market Incumbents: Lock in tungsten concentrate offtake agreements before export licensing tightens further, and accelerate backward integration into captive refining capacity to defend margin position against alkali digestion cost volatility. Phosphotungstic acid substitution in oxidation catalysis threatens volume in fine chemical applications, making medical-grade certification investment the critical defensive lever for margin preservation. For New Entrants and Emerging Players: B2B marketplace channels for analytical-grade small-lot sales offer the most penetrable entry vector, particularly serving research institutions in India and Southeast Asia facing procurement rule changes. Target India's Bureau of Indian Standards certification pathway before formal purity grades lock in incumbent advantage. A testing-partnership go-to-market angle with national laboratories builds qualification credibility without immediate multi-ton production scale. For Investors and Strategic Acquirers: The window for entry favors integrated tungsten refiners with captive concentrate access and REACH-registered dossiers already on file. Long-term viability rests on upstream resource control and regulatory compliance infrastructure rather than crystallization technology alone. Watch for China's Ministry of Commerce export licensing expansion as the inflection signal for Western supply security premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Concentrate | Captive Jiangxi or Vietnamese concentrate supply secures margin against export licensing volatility. |
| REACH Registration Dossier Expansion | ECHA substance identity compliance opens EU pharmaceutical and electronics procurement channels. |
| ICP-MS Analytical Infrastructure Investment | Trace metal certification to 99.95% purity qualifies suppliers for medical imaging contrast agent formulations. |
| Closed-Loop Crystallization Process Deployment | China MEE carbon intensity benchmarks reward wastewater reduction with green financing access. |
| India BIS Certification Partnership | First-mover analytical-grade qualification captures emerging contrast agent and research institution demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning tungsten refinery plant managers, catalyst house procurement leads, pharmaceutical regulatory affairs directors, and chemical distribution channel partners. ECHA registration databases, SAMR GB standard publications, US EPA TSCA filings, and India customs import records provided triangulation against bottom-up crystallization capacity estimates and top-down end-use consumption models.
Product-grade granularity modeled reagent, technical, analytical, and industrial tiers separately, with application-level splits across catalysts, medical, coatings, and electronics end uses. Regional production hub clustering captured Rhine-Ruhr, Yangtze River Delta, Texas-Louisiana Gulf Coast, and Osaka-Kobe concentration effects. CAGRs derived from segmented volume trajectories cross-referenced against purity-driven price elasticity assumptions and regulatory compliance cost pass-through rates across the projection horizon.
Inputs from ECHA, SAMR, and EPA filings were available through the study window; gaps in real-time tungsten concentrate export license issuance data introduce uncertainty bands around Chinese supply availability assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Barite Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
Sodium Gluconate Market