
 Gold Smelting Market | 2026-2036
Gold Smelting Market Size, Share, and Industry Trends Forecast 2026-2036
Gold Smelting Market Foresight
LBMA Good Delivery standard compliance is unwinding legacy capacity across the gold smelting sector. Metalor leverages its Swiss refining heritage to sustain premium accreditation across multiple continents. Rand Refinery anchors African gold flow through its Durban facility, controlling regional doré intake. Valcambi specializes in kilobar and small-bar fabrication, extending its reach into Asian investment demand.
Gold smelting extracts and purifies gold-bearing material through thermal and chemical processing to achieve commercial fineness, typically reaching 99.5% to 99.99% purity depending on end-use specifications. Pyrometallurgy dominates primary smelting flows for sulfide and oxide ores, while hydrometallurgy handles lower-grade concentrates and refractory material through leaching circuits. Hydrometallurgical capacity is expanding fastest among technology segments as miners target deeper, lower-grade deposits. Jewelry end users command the largest value share, though electronics applications are pulling higher volumes of four-nines and five-nines refined metal.
EPA emissions standards in the United States, REACH chemical protocols in Europe, and China's MEE air quality directives collectively tighten allowable discharge thresholds from smelter stacks and tailings. These frameworks elevate capital requirements for new entrants while advantaging accredited incumbents with installed scrubber and effluent systems. Stakeholders must track regulatory divergence between OECD and non-OECD jurisdictions when siting greenfield capacity or qualifying supply chains for institutional offtake agreements.
Market Dynamics
Chinese smelters are consolidating doré intake channels while EPA and MEE air quality mandates force scrubber retrofits across legacy capacity, tightening operational economics for unaccredited producers.
Growth Catalysts
- Electronics bonding wire demand:High-reliability connectors in aerospace and medical devices pull four-nines refined metal volumes upward.
- REACH chemical protocols:European environmental frameworks accelerate capital deployment into closed-loop cyanide recovery systems.
- Chinese jewelry fabrication:Domestic consumption climbs alongside kilobar investment demand, absorbing incremental refined output.
Market Restraints
- Energy cost volatility:Pyrometallurgical circuits depend on natural gas and electricity pricing that fluctuates with regional grid stress.
- Doré supply concentration:African mine output flows through limited accredited offtake agreements, constraining feedstock security.
- Technical limitation in refractory ore:Carbonaceous preg-robbing material resists standard leaching circuits, requiring pre-oxidation capex.
Strategic Opportunities
- Indian jewelry export hubs:Domestic fabrication capacity expansion creates demand for LBMA-accredited kilobar supply.
- Green hydrogen pilot smelting:Renewable thermal substitution in European refineries opens carbon-neutral positioning.
- Blockchain traceability mandates:OECD due diligence guidelines drive premium pricing for digitally documented supply chains.
Industry Challenges
- Pyrometallurgical engineer scarcity:Specialized furnace operation expertise concentrates among retiring cohorts in traditional refining centers.
- LBMA Good Delivery timeline:New entrants face multi-year accreditation cycles before qualifying for institutional offtake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gold Smelting Market |
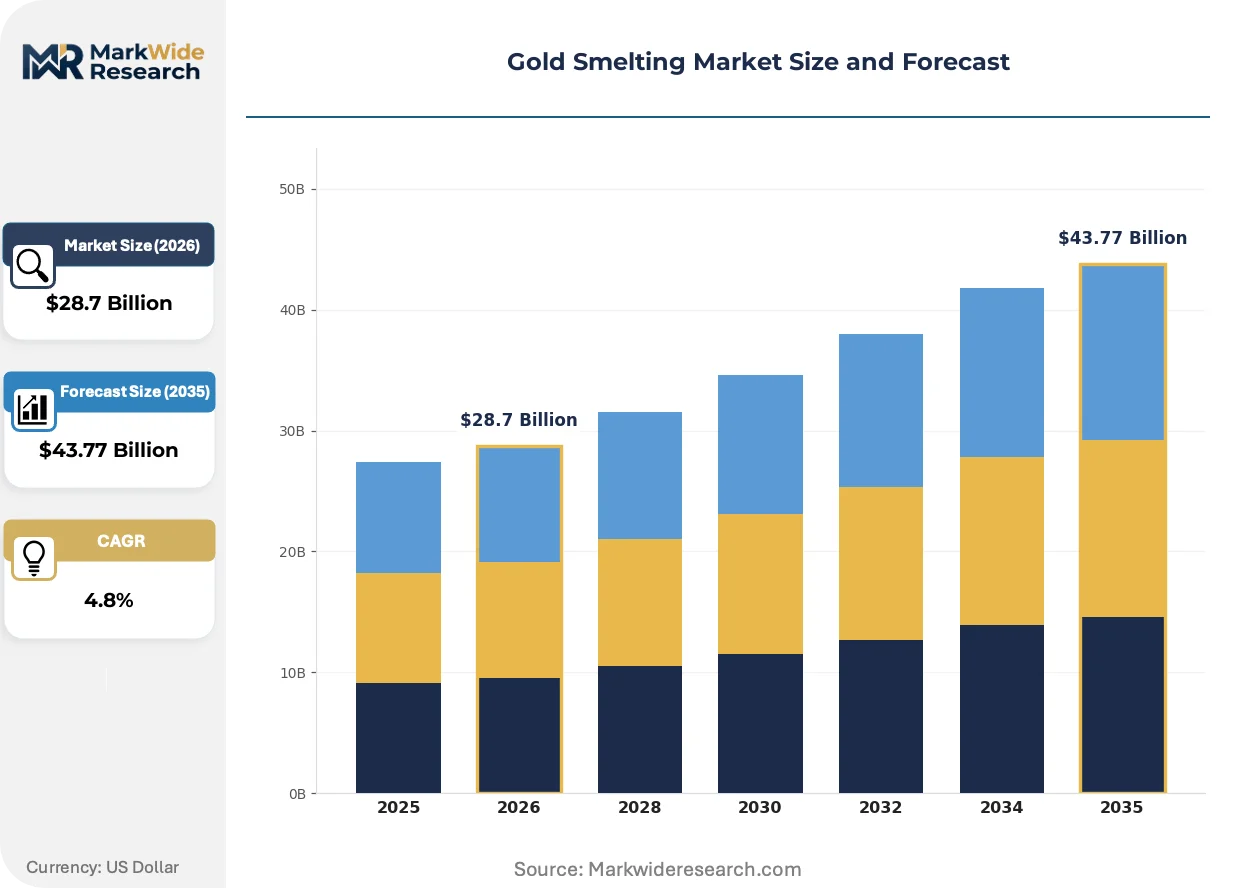
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Furnace, Arc Furnace, Cupola Furnace, Retort Furnace Technology: Hydrometallurgy, Pyrometallurgy, Biotechnological, Electrowinning End User: Jewelry, Electronics, Investment, Dental Application: Refining, Alloying, Recycling, Smelting |
| Companies Covered | Metalor, Rand Refinery, Valcambi, Barrick Gold Mining Corporation, Newmont, PAMP, Tanaka Kikinzoku Kogyo, AngloGold Ashanti, Heraeus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gold Smelting Market Shifts & Advancements
Smelting technology is bifurcating between high-volume pyrometallurgical consolidation and modular hydrometallurgical deployment for distributed ore bodies.
Chloride-based refining circuits are displacing traditional aqua regia methods in Asian refineries. Electronics manufacturers with traceability mandates adopt these systems for faster throughput and lower effluent volumes. The technology is displacing legacy batch processing capacity in Shenzhen and Singapore hubs.
China's MEE air quality directives tighten particulate and sulfur dioxide thresholds for non-ferrous smelters. Stack scrubber retrofits now consume fifteen to twenty percent of annual maintenance budgets. Secondary refiners in Shandong province accelerate consolidation to spread compliance costs across larger throughput bases.
Traceability-driven procurement now dominates institutional bullion purchasing. Investment banks and sovereign wealth funds screen supply chains against OECD conflict mineral guidelines. Swiss and Dubai refiners capture preferential offtake by embedding blockchain documentation from mine gate to vault.
Gold Smelting Market Segmentation
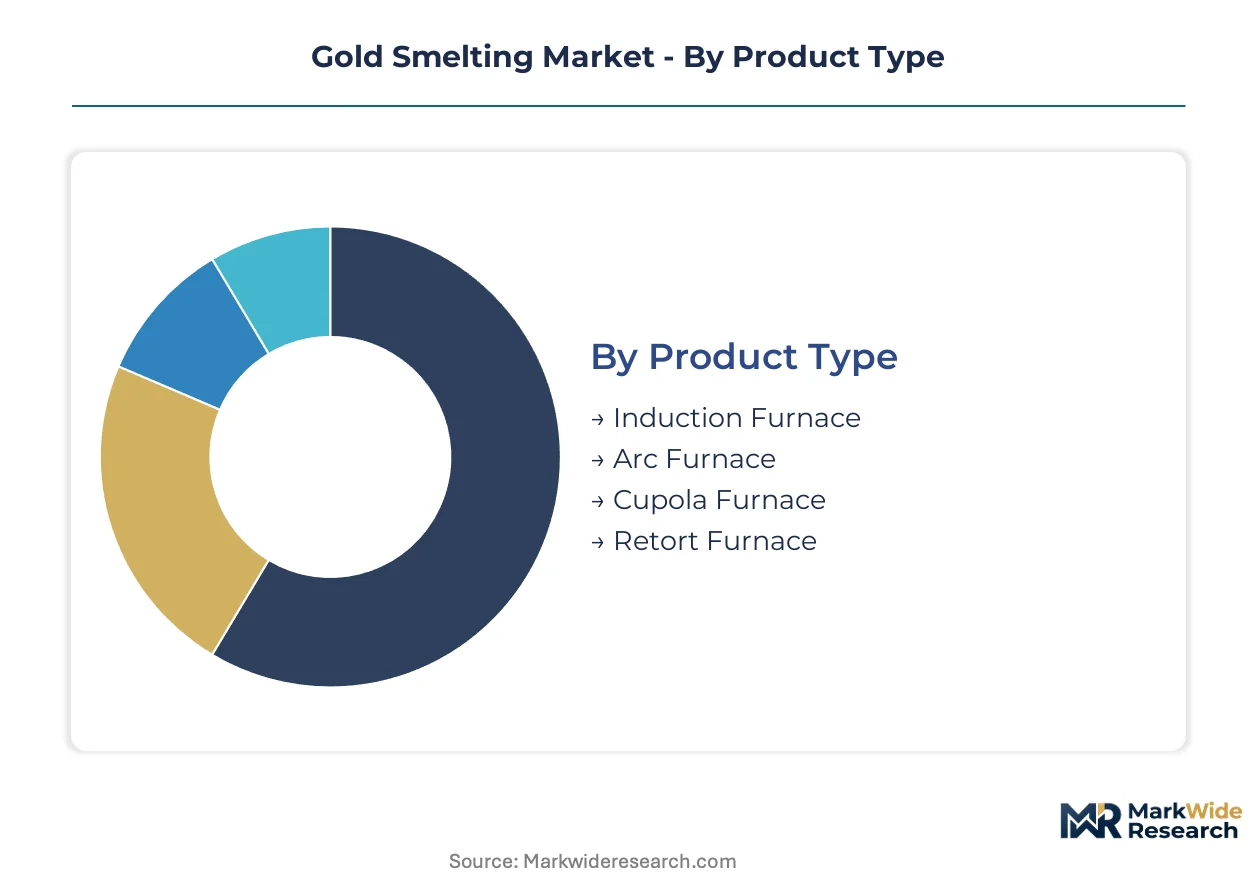
Gold smelting margins fragment sharply across furnace technologies and end-use specifications. Jewelry and electronics buyers impose divergent purity thresholds, while regulatory pressure on emissions intensifies capital allocation toward hydrometallurgical circuits.
Product Type:
Induction furnaces command the widest margin pool through energy efficiency and precise temperature control in high-purity output.
- Induction Furnace:Electromagnetic heating achieves rapid, uniform temperature distribution with minimal metal loss. Electronics manufacturers in Shenzhen and Singapore specify induction-processed four-nines gold for bonding wire, paying premiums for consistent impurity profiles.
- Arc Furnace:Electric arc discharge generates extreme temperatures for processing high-volume sulfide concentrates. African doré flows through South African arc capacity at Rand Refinery, where EPA-equivalent stack scrubbers absorb fifteen to twenty percent of operating budgets.
- Cupola Furnace:Blast-driven shaft furnaces dominate legacy secondary refining in India and Turkey, constrained by particulate emission thresholds.
- Retort Furnace:Batch distillation systems handle mercury-contaminated artisanal gold in Colombian and Ghanaian operations, limited by OECD traceability screening.
Induction furnace capacity holds installed base dominance. Arc furnace throughput is rotating up the share rankings in African feedstock processing.
Technology:
Technology choice determines compliance cost exposure and feedstock flexibility across ore grades.
- Hydrometallurgy:Leaching circuits using cyanide or thiosulfate extract gold from low-grade and refractory material without thermal emissions. China's MEE air quality directives accelerate closed-loop recovery system deployment in Shandong province, where secondary refiners consolidate to spread capital requirements.
- Pyrometallurgy:High-temperature roasting and smelting of sulfide concentrates yields doré bullion with established LBMA accreditation pathways. Swiss refiners at Metalor and Valcambi anchor premium pricing through pyrometallurgical heritage and multi-continent Good Delivery status.
- Biotechnological:Bio-oxidation pre-treatment of refractory carbonaceous ore reduces cyanide consumption and tailings toxicity, piloted at select Australian and Brazilian deposits.
- Electrowinning:Electrolytic metal recovery from pregnant leach solutions enables modular, distributed processing near remote mine sites in Nevada and Western Australia.
Pyrometallurgy holds installed capacity. Hydrometallurgy is climbing the fastest as miners target deeper, lower-grade deposits.
End User:
End-user pricing power concentrates in investment-grade kilobar buyers and traceability-mandated electronics procurement.
- Jewelry:Fabricators in India and China absorb the largest volume share, with Indian export hubs expanding capacity to capture Middle Eastern and Southeast Asian retail demand. Domestic Chinese consumption climbs alongside kilobar investment offtake, pulling refined output toward 99.5% purity specifications.
- Electronics:Aerospace and medical device manufacturers specify four-nines and five-nines gold for high-reliability connectors and bonding wire. REACH chemical protocols in Europe and conflict mineral guidelines from the OECD drive blockchain-documented supply chain premiums.
- Investment:Sovereign wealth funds and central banks screen LBMA Good Delivery lists, concentrating offtake among Swiss, Dubai, and Singapore vault channels.
- Dental:Alloy formulations for crowns and bridges require precise hardness tuning, a contracting volume segment as ceramic alternatives displace metallic restorations.
Jewelry holds installed demand share. Electronics is rotating up the share rankings on traceability-premium pricing.
Application:
Application margins split between high-volume primary refining and value-added alloying services.
- Refining:Doré purification to commercial fineness represents the core revenue base, with LBMA-accredited output commanding institutional premiums. African mine supply flows through limited accredited offtake agreements, constraining feedstock security for unaccredited entrants facing multi-year accreditation timelines.
- Alloying:Precise karat adjustment for jewelry and dental specifications captures service margins, concentrated in Turkish and Italian fabrication clusters.
- Recycling:Urban mining of e-waste and jewelry scrap expands as a feedstock source, with Asian refiners in Shenzhen and Singapore deploying chloride circuits for faster throughput.
- Smelting:Primary pyrometallurgical reduction of ore concentrates remains concentrated in mining-proximate jurisdictions with legacy energy infrastructure.
Refining holds installed capacity. Recycling is rotating up the share rankings on e-waste feedstock availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping refined gold flows as Chinese jewelry fabrication absorbs domestic doré while Swiss and Dubai vaults intermediate institutional kilobar demand. Smelter capacity expansion concentrates in mining-proximate jurisdictions with legacy energy infrastructure and evolving environmental compliance frameworks.
China
Domestic jewelry consumption and kilobar investment demand pull refined output toward 99.5% purity specifications. MEE air quality directives tighten particulate thresholds, forcing Shandong province refiners to consolidate for scrubber cost-sharing. Shenzhen and Singapore hubs deploy chloride circuits for faster electronics-grade throughput.
Switzerland
Institutional bullion purchasing concentrates offtake among Swiss vault channels screening LBMA Good Delivery lists. REACH chemical protocols accelerate capital deployment into closed-loop cyanide recovery systems. Ticino-based refiners anchor premium pricing through pyrometallurgical heritage and multi-continent accreditation status.
South Africa
African mine output flows through limited accredited offtake agreements, constraining feedstock security for unaccredited entrants. EPA-equivalent stack scrubbers absorb substantial operating budgets at Durban-area facilities. Rand Refinery controls regional doré intake through its coastal processing infrastructure.
United States
Aerospace and medical device manufacturers specify four-nines gold for high-reliability connectors and bonding wire. EPA emissions standards elevate capital requirements for new entrants versus accredited incumbents with installed scrubber systems. Nevada and Western Australia electrowinning circuits enable modular processing near remote mine sites.
India
Domestic fabrication capacity expansion creates demand for LBMA-accredited kilobar supply to capture Middle Eastern and Southeast Asian retail demand. BIS standards govern jewelry alloy specifications and hallmarking requirements. Mumbai and Surat clusters concentrate alloying services for precise karat adjustment.
Gold Smelting Market Competitive Landscape
Listed leaders compete with private specialists across accreditation tiers and geographic coverage. The vendor base stratifies between heritage refiners with multi-decade LBMA status and emerging hydrometallurgical operators targeting distributed ore bodies. Three archetypes dominate: Swiss heritage houses with vault-network integration, mining-affiliated smelters with captive feedstock, and Asian electronics-grade specialists. Competitive moves concentrate on M&A for accreditation transfer and capacity expansion in mining-proximate jurisdictions.
Among heritage Swiss refiners, Metalor and Valcambi exemplify the premium-tier archetype through multi-continent Good Delivery positioning. Rand Refinery anchors African doré processing from its South African base. Tanaka Kikinzoku Kogyo represents the Japanese electronics-grade specialization vector, serving aerospace and medical device bonding wire specifications.
| Leading Market Players |
|---|
| Metalor |
| Rand Refinery |
| Valcambi |
| Barrick Gold Mining Corporation |
| Newmont |
| PAMP |
| Tanaka Kikinzoku Kogyo |
| AngloGold Ashanti |
| Heraeus |
| Others |
Supply & Pricing Matrix
LBMA Good Delivery accreditation gates both supply qualification and price differentiation simultaneously. Unaccredited doré processors face multi-year exclusion from institutional offtake while Swiss and Dubai refiners capture premiums for blockchain-documented kilobar supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures. Pricing stratifies across LBMA-accredited, ISO-certified, and unaccredited tiers based on purity grade and traceability documentation. Cost compression in standard-grade doré processing is intensifying because Chinese smelter consolidation spreads scrubber retrofit costs across larger throughput bases. Jewelry fabricators in India exhibit highest price sensitivity, while aerospace electronics OEMs show least sensitivity due to traceability mandates.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam and Durban-Jeddah trade lanes elevate inbound logistics costs for African doré shipments. Supply concentrates in South Africa, China, and Switzerland as primary refining jurisdictions. Raw material dependencies center on mercury-contaminated artisanal feedstock, sulfide ore concentrates, and e-waste scrap flows. Single-source vulnerability runs through Rand Refinery's control of African accredited offtake channels. Distribution runs through Swiss vault networks and Dubai free trade zones for institutional kilobar delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as central bank gold purchasing rebounds from multi-year lows. Jewelry fabrication and electronics bonding wire demand provide synchronized lift across end-use segments.
For Market Incumbents: Shield LBMA accreditation status through preemptive stack scrubber investments ahead of MEE and EPA threshold tightening. Consolidate doré offtake agreements in African mining jurisdictions before unaccredited entrants complete multi-year accreditation cycles. Vertical integration into captive mine supply in Nevada and Western Australia reduces feedstock security exposure.
For New Entrants and Emerging Players: Anchor in modular hydrometallurgical deployment for distributed refractory ore bodies in Australia and Brazil. Target electrowinning circuits near remote Nevada mine sites as the most penetrable white space. Pursue joint venture structures with existing LBMA-accredited refiners to bypass multi-year Good Delivery timelines.
For Investors and Strategic Acquirers: OECD conflict mineral guideline enforcement reshapes the acquisition landscape toward traceability-embedded supply chains. Five-to-ten year viability favors Swiss heritage houses with multi-continent vault integration over unaccredited regional processors. Watch for MEE air quality directive implementation in Shandong province as inflection signal for Chinese refiner consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| LBMA Good Delivery Accreditation Investment | Multi-year certification cycles lock out competitors from institutional kilobar offtake at Swiss and Dubai vaults. |
| Closed-Loop Cyanide Recovery System Deployment | REACH and MEE compliance spreads retrofit costs across consolidated Shandong province throughput bases. |
| Blockchain Traceability Integration | OECD due diligence guidelines enable premium pricing for digitally documented doré from mine gate to vault. |
| Green Hydrogen Pilot Smelting | Renewable thermal substitution in European refineries opens carbon-neutral positioning for institutional ESG mandates. |
| African Doré Offtake Consolidation | Rand Refinery's coastal infrastructure anchors regional feedstock security against unaccredited entrant competition. |
Research Methodology
The analysis maps pyrometallurgical heritage refiners, hydrometallurgical operators, electronics-grade specialists, and mining-affiliated smelters, each validated through primary interviews with refinery operations directors, LBMA accreditation officers, electronics procurement managers, and African mine supply coordinators. Secondary validation draws from EPA emissions filings, MEE air quality disclosures, LBMA Good Delivery lists, and OECD conflict mineral reports. Bottom-up capacity modeling triangulates against top-down doré flow estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include furnace technology type, refining methodology, end-user specification tier, and regional regulatory cluster. CAGRs were derived from installed capacity expansion schedules and feedstock availability curves. Industry-specific forecast inputs incorporate jewelry fabrication demand cycles and electronics bonding wire purity specifications.
Material uncertainties — abrupt regulatory threshold revisions, African mine supply disruptions, or cyanide substitution technology breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding accreditation timeline stability and doré flow concentration patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Drums and Ibcs Market
Metals
Metal Forging Market
Metals
Global Aluminium Wire Rod Market
Metals
Titanium Powder Market
Metals
Zirconium Market
Metals
Galvanized Steel Coil Market
Metals
Ore Metals Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Saudi Arabia Aluminum Market
Metals
Steel Sheet for Home Appliances Market
Metals
Global Chromium Market
Metals
Electrodeposited Copper Foil Market
Metals
Global Stretch Spring Wire Market
Metals
India Steel Market
Metals
Galvanizing Market
Metals
Molybdenum Market