
 Tungsten Metal Powder Market | 2026-2036
Tungsten Metal Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Tungsten Metal Powder Market Outlook
Cemented carbide is consolidating its position against cobalt-drift alternatives in cutting tool applications. H.C. Starck GmbH leverages captive reduction capabilities in Germany to sustain premium powder output. Xiamen Tungsten Co. Ltd. anchors Chinese supply through integrated APT-to-powder operations. Kennametal Inc. competes in North American aerospace channels with specialized spherical grades.
Tungsten metal powder consists of reduced tungsten oxide with typical purity exceeding 99.9% and particle sizes ranging from 0.5 to 50 microns, produced via hydrogen reduction of tungstic acid or ammonium paratungstate for hardmetal, heavy alloy, and specialty chemical applications. Powdered Tungsten dominates volume for electrical contact and additive manufacturing feedstock where high density and thermal conductivity matter. Tungsten Carbide captures the largest value pool across cutting inserts and mining tools. Aerospace applications within the Application dimension are expanding fastest as engine OEMs qualify new superalloy compositions.
REACH in Europe restricts cobalt content in cemented carbides, pushing reformulation toward nickel and iron binders that demand purer tungsten feedstock. China's MEE enforces stricter tailings and wastewater rules at concentrate plants, elevating compliance costs for domestic powder producers. Stakeholders must monitor binder metal substitution rates and regional concentrate availability to secure long-term supply positions.
Market Dynamics
Aerospace turbine blade manufacturers are accelerating tungsten alloy adoption as engine OEMs qualify new superalloy compositions, while China's dual carbon goals and stricter mining permits tighten concentrate supply chains.
Growth Catalysts
- Aerospace qualification cycles:Engine OEMs in Germany and the United States are qualifying tungsten-heavy alloys for next-generation turbine blades, pulling premium spherical powder demand through specialized supply channels.
- REACH cobalt restrictions:ECHA's reformulation mandates for cemented carbides are pushing nickel and iron binder systems that require purer tungsten feedstock, elevating specification thresholds across European tooling markets.
- Additive manufacturing qualification:Powder bed fusion and directed energy deposition systems are expanding tungsten metal powder adoption for radiation shielding and thermal management components in medical and defense applications.
Market Restraints
- Concentrate supply concentration:China's MEE enforcement of stricter tailings and wastewater rules at concentrate plants is elevating compliance costs and restricting feedstock availability for non-integrated powder producers.
- Cobalt price volatility:Cemented carbide formulations remain exposed to cobalt market swings, compressing margin stability for tool manufacturers dependent on traditional binder systems.
- Ceramic cutting tool substitution:Silicon nitride and alumina-based inserts are displacing tungsten carbide in high-speed finishing applications where thermal shock resistance outweighs toughness requirements.
Strategic Opportunities
- India precision tooling buildout:The country's PLI scheme for advanced manufacturing is attracting carbide tool investments around Pune and Bengaluru, creating localized powder demand for automotive and aerospace machining.
- Nuclear energy shielding:Tungsten heavy alloys are expanding into spent fuel cask and reactor shielding applications as SMR developers seek high-density, corrosion-resistant materials.
- Battery recycling feedstock:Urban mining of tungsten from end-of-life carbide tools and electronics is emerging as a secondary concentrate source, with pyrometallurgical recovery routes scaling in Germany and Japan.
Industry Challenges
- Reduction furnace engineering talent:Hydrogen atmosphere reduction requires specialized metallurgical expertise that is aging out of European and North American powder plants faster than training pipelines replenish.
- APT-to-powder certification timelines:Aerospace material specifications demand 18-36 month qualification cycles for new powder lots, freezing supplier switches and locking in incumbent relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tungsten Metal Powder Market |
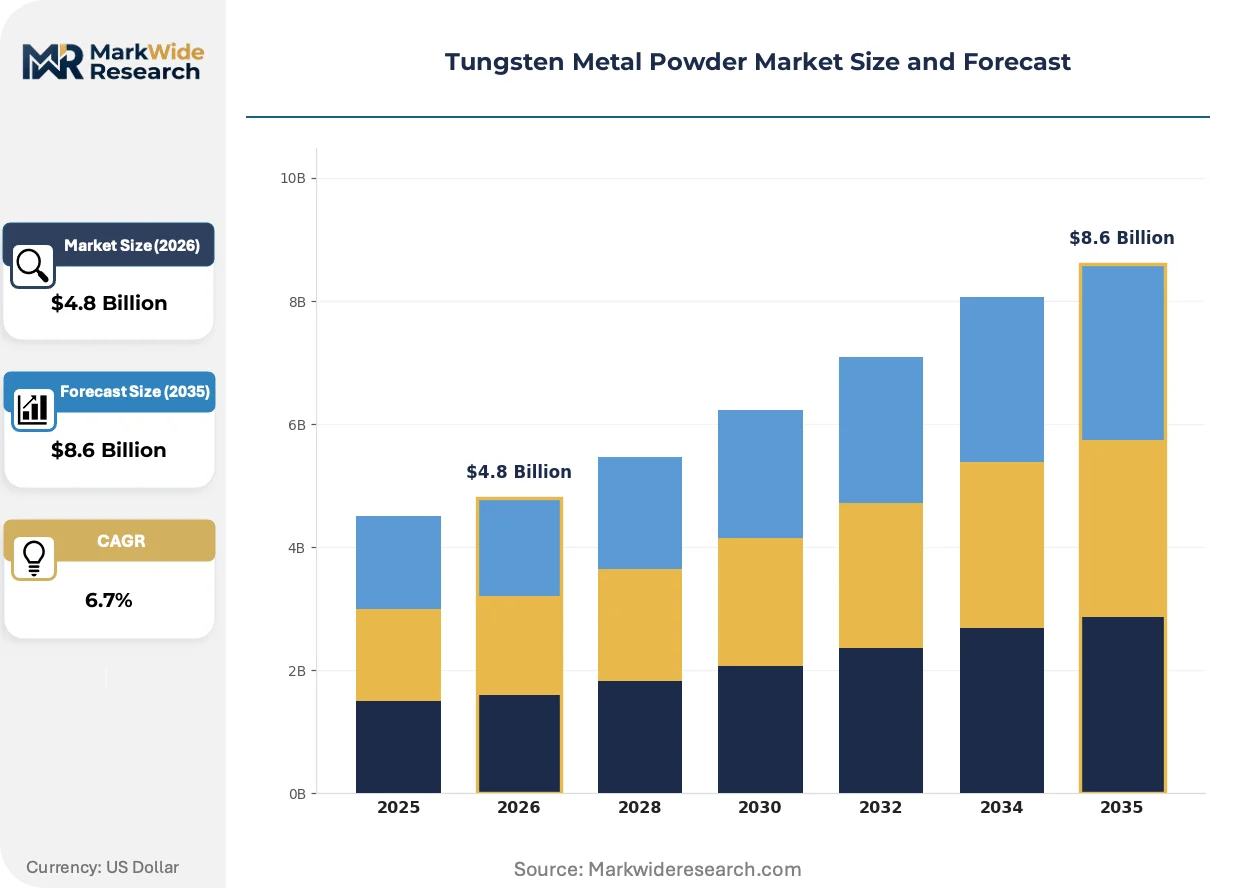
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Tungsten, Tungsten Carbide, Tungsten Heavy Alloys, Tungsten Copper Application: Aerospace, Defense, Electronics, Medical Devices End User: Manufacturers, Research Institutions, OEMs, Distributors Form: Spherical, Angular, Coarse, Fine |
| Companies Covered | China Minmetals Corporation, Xiamen Tungsten Co. Ltd., H.C. Starck GmbH, Global Tungsten & Powders Corp., Kennametal Inc., Sandvik AB, Japan New Metals Co. Ltd., Guangdong Xianglu Tungsten, Buffalo Tungsten Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tungsten Metal Powder Market Strategic Shifts
Process intensification and regulatory chemistry shifts are compressing traditional production economics while opening new performance tiers in additive and aerospace channels.
Spherical tungsten powder produced via plasma atomization is expanding into directed energy deposition systems for rocket nozzle and heat exchanger applications. SpaceX and Relativity Space are qualifying these grades for regeneratively cooled thrust chambers, driving powder producers to invest in plasma capacity. The technology is expanding into markets previously served by wrought tungsten bar stock, compressing lead times from months to days for complex geometries.
REACH Annex XVII restrictions on cobalt in consumer-contact applications are forcing reformulation of cemented carbides toward nickel-iron binder systems. ECHA's 2023 sunset date for certain cobalt classifications triggered tooling manufacturers to redesign insert grades, elevating demand for ultra-low-impurity tungsten feedstock. European cutting tool producers are responding by tightening incoming powder specifications and qualifying alternative reduction routes.
Consolidation among German automotive tool buyers is concentrating purchase volumes with fewer procurement desks, pressuring mid-tier powder distributors. Tier-1 suppliers around Dortmund and Essen are negotiating direct mill relationships, bypassing traditional trading houses. This pattern is most visible in the Rhine-Ruhr precision tooling cluster, where captive powder blending operations are displacing merchant market offtake.
Tungsten Metal Powder Market Segmentation
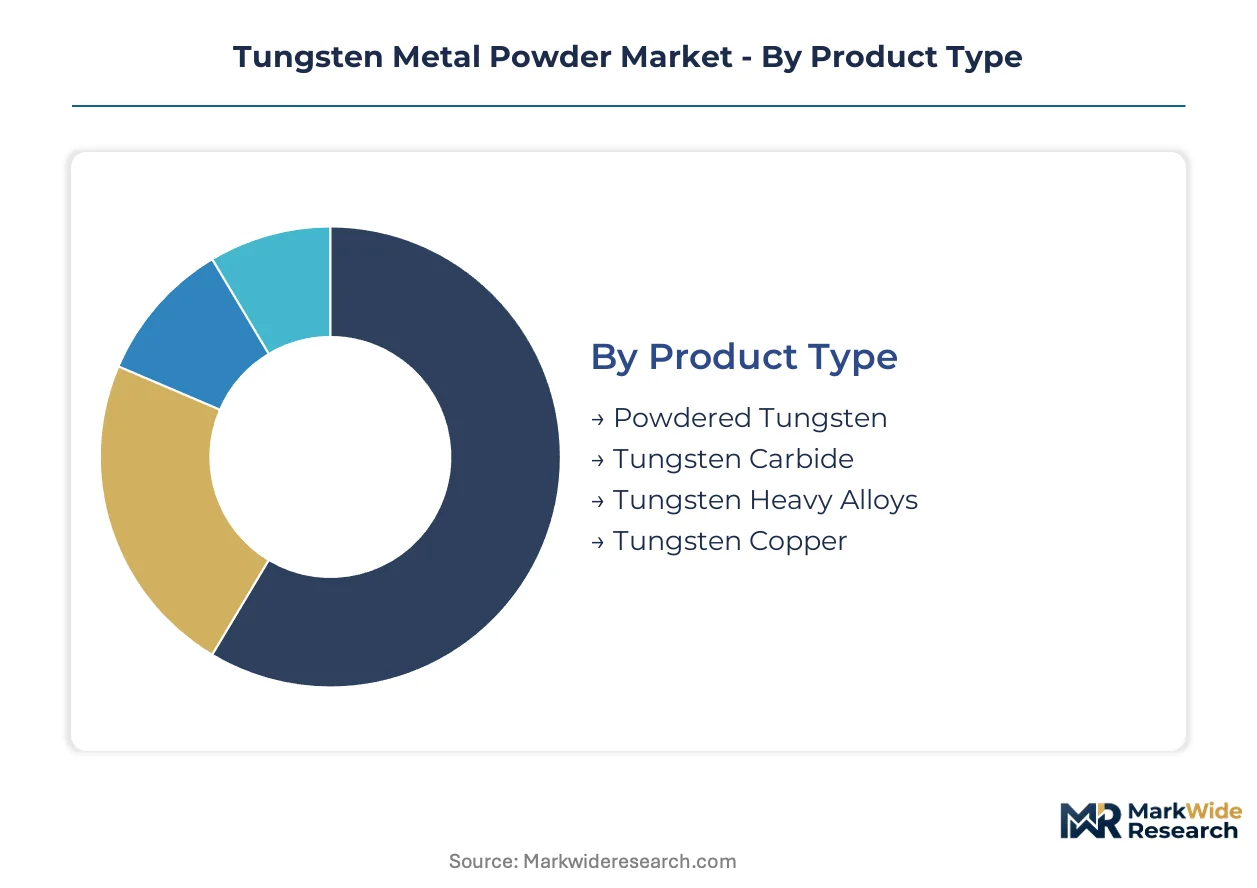
Tungsten metal powder markets fragment across purity grades, particle morphologies, and end-use specifications that dictate pricing power. Each segmentation dimension carries distinct qualification barriers and supply chain configurations that shape procurement strategies.
Product Type:
Standardization dominates at commodity grades while aerospace and medical applications demand customized purity certifications and lot traceability.
- Tungsten Carbide:Cemented carbide feedstock with cobalt, nickel, or iron binder systems. Demand concentrates in Germany's Rhine-Ruhr precision tooling cluster around Dortmund and Essen, where REACH cobalt restrictions are forcing reformulation toward nickel-iron binders that require purer tungsten feedstock.
- Powdered Tungsten:Reduced tungsten oxide exceeding 99.9% purity with particle sizes from 0.5 to 50 microns. Aerospace turbine blade manufacturers in Germany and the United States are accelerating adoption as engine OEMs qualify new superalloy compositions, pulling premium spherical powder demand through specialized supply channels.
- Tungsten Heavy Alloys:High-density compositions for radiation shielding and kinetic energy penetrators.
- Tungsten Copper:Composite material for electrical contacts and thermal management applications.
Leading the category by volume: Tungsten Carbide. Expanding most quickly: Powdered Tungsten.
Application:
Cost tiers separate qualification-intensive segments from volume-driven industrial consumption.
- Aerospace:Turbine blade superalloys and rocket nozzle applications requiring spherical powder grades. SpaceX and Relativity Space are qualifying plasma-atomized tungsten for regeneratively cooled thrust chambers, compressing lead times from months to days for complex geometries.
- Defense:Kinetic penetrators and radiation shielding for military platforms.
- Electronics:Electrical contacts and thermal management components.
- Medical Devices:Radiation shielding and implantable components where biocompatibility certification elevates specification thresholds.
Volume leadership sits with Electronics. Steepest expansion trajectory belongs to Aerospace.
End User:
Customer type determines contract structure, with OEMs demanding long-term supply agreements and research institutions driving small-lot premium pricing.
- OEMs:Engine manufacturers and tool producers with 18-36 month powder qualification cycles that freeze supplier switches and lock in incumbent relationships.
- Manufacturers:Cutting tool and carbide part producers concentrated in Germany's automotive supply chain.
- Distributors:Merchant market intermediaries facing margin pressure as Tier-1 suppliers negotiate direct mill relationships.
- Research Institutions:Universities and national laboratories qualifying next-generation additive manufacturing feedstocks.
OEMs command the largest contract values. Research Institutions are climbing the fastest as additive manufacturing qualification expands.
Form:
Maturity separates established angular grades from emerging spherical powders requiring plasma atomization investment.
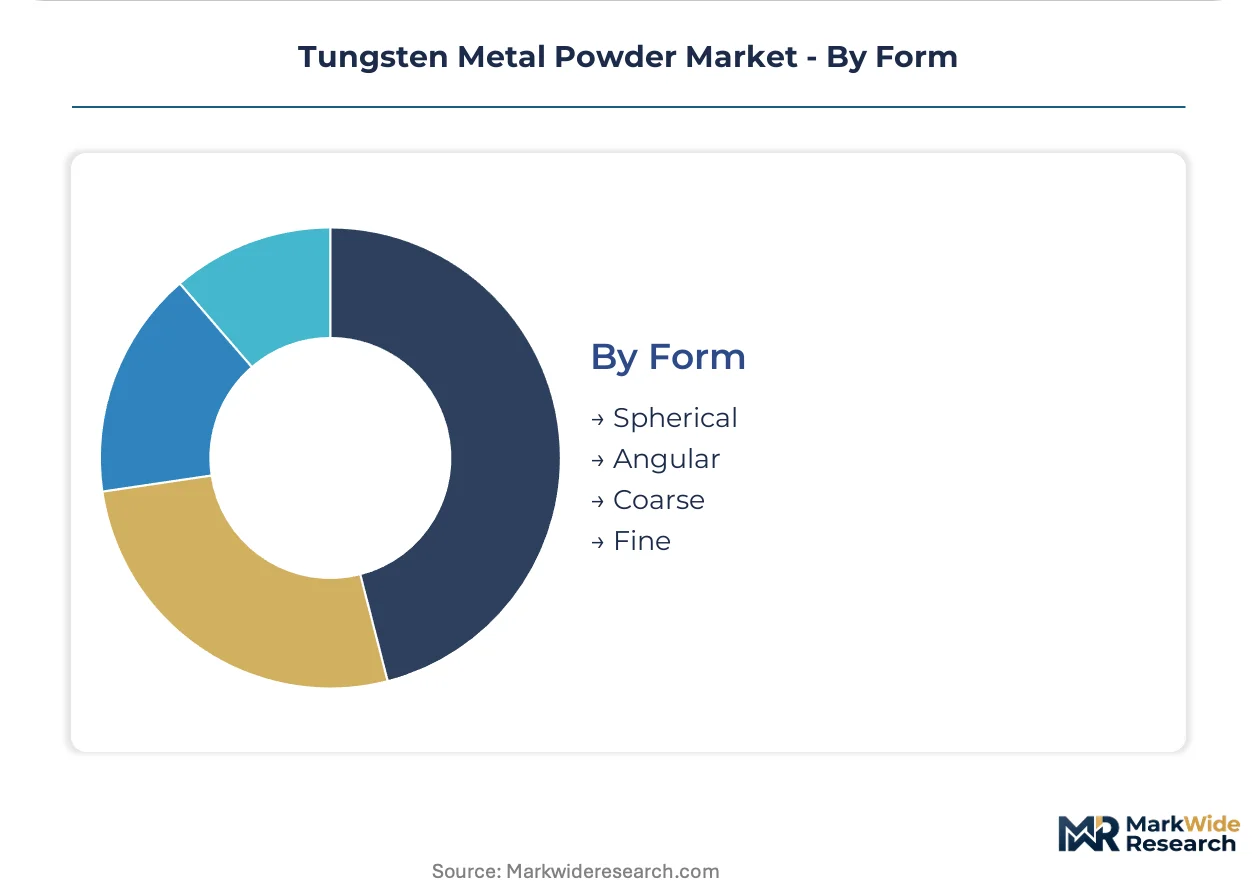
- Spherical:Plasma-atomized powder for powder bed fusion and directed energy deposition systems. Medical and defense applications for radiation shielding and thermal management components are expanding adoption.
- Angular:Conventional hydrogen-reduced powder for pressed-and-sintered hardmetal applications.
- Fine:Sub-10 micron grades for injection molding and fine-feature additive manufacturing.
- Coarse:Large particle sizes for bulk pressing operations and heavy alloy infiltration.
Angular forms retain volume leadership. Spherical grades are gaining share fastest as rocket engine manufacturers qualify new deposition systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for tungsten metal powder concentrates in Germany's precision tooling cluster around Dortmund and Essen, with aerospace qualification cycles in the United States and supply chain tightening in China reshaping procurement patterns across major consuming regions.
Germany
Aerospace turbine blade manufacturers in Bavaria and Baden-Württemberg are accelerating superalloy qualification programs. ECHA's REACH Annex XVII cobalt restrictions are forcing cemented carbide reformulation toward nickel-iron binders. The Rhine-Ruhr precision tooling cluster around Dortmund and Essen is consolidating purchase volumes with fewer procurement desks, pressuring mid-tier powder distributors.
United States
Engine OEMs in Ohio and Texas are qualifying tungsten-heavy alloys for next-generation turbine blades. FAA certification timelines for aerospace materials extend 18-36 months, freezing supplier switches. SpaceX and Relativity Space in California are qualifying plasma-atomized spherical powder for regeneratively cooled rocket thrust chambers.
China
Integrated APT-to-powder operations in Fujian and Jiangxi provinces anchor domestic supply chains. The Ministry of Ecology and Environment enforces stricter tailings and wastewater rules at concentrate plants, elevating compliance costs. Dual carbon goals are tightening mining permits and restricting feedstock availability for non-integrated producers.
Japan
Pyrometallurgical recovery routes for urban mining of tungsten from end-of-life carbide tools are scaling in Osaka and Nagoya industrial corridors. METI industrial policy supports circular economy feedstock development. Precision tool manufacturers in the Chubu region around Nagoya are tightening incoming powder specifications.
India
The PLI scheme for advanced manufacturing is attracting carbide tool investments around Pune and Bengaluru. BIS standards for cemented carbide feedstock are elevating specification thresholds. Automotive and aerospace machining clusters in Maharashtra and Karnataka are creating localized powder demand.
Tungsten Metal Powder Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with captive reduction capabilities and integrated APT-to-powder operations commanding premium positioning. The vendor base organizes around three strategic archetypes: integrated miners with downstream powder assets, independent reduction specialists with hydrogen furnace networks, and aerospace-qualified spherical powder producers with plasma atomization capacity. Capacity expansion and direct mill relationships with Tier-1 automotive tool buyers represent the dominant competitive moves.
Among German reduction specialists, H.C. Starck GmbH exemplifies captive hydrogen atmosphere capabilities serving European tooling markets. Xiamen Tungsten Co. Ltd. anchors Chinese supply through integrated upstream-to-powder operations. Kennametal Inc. occupies a position within North American aerospace channels, representing the qualification-intensive spherical grade segment.
| Leading Market Players |
|---|
| China Minmetals Corporation |
| Xiamen Tungsten Co. Ltd. |
| H.C. Starck GmbH |
| Global Tungsten & Powders Corp. |
| Kennametal Inc. |
| Sandvik AB |
| Japan New Metals Co. Ltd. |
| Guangdong Xianglu Tungsten |
| Buffalo Tungsten Inc. |
| Others |
Value Chain & Pricing Dynamics
APT concentrate costs flow from China's Jiangxi and Fujian provinces through hydrogen reduction furnaces in Germany, with purity premiums accumulating at each qualification gate before reaching aerospace OEMs in Bavaria and Texas.
Pricing Analysis
Volume concentrates in standard angular grades for cemented carbide while margins pool in spherical powder qualified for rocket engine deposition systems. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified spherical grades from industrial angular powder and commodity feedstock. Cost compression in standard grades intensifies as China's MEE enforcement elevates concentrate compliance costs. Tier-1 automotive tool buyers around Dortmund exhibit lowest price sensitivity due to captive blending operations, while merchant distributors face margin erosion from direct mill relationships.
Supply Chain Analysis
Specialized hydrogen atmosphere furnace operators in Germany's Rhine-Ruhr corridor and plasma atomization technicians in Ohio and Texas are aging out faster than training pipelines replenish, constraining capacity expansion for premium grades. Supply concentrates in China for APT-to-powder integrated operations, Germany for reduction specialists, and the United States for aerospace-qualified spherical production. The chain draws from tungsten concentrate, hydrogen feedstock, and cobalt-nickel-iron binder metals. Single-source vulnerability runs through Chinese concentrate dominance under tightening dual carbon mining permits. Distribution runs through direct mill relationships with Tier-1 automotive buyers and specialized aerospace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as players pursue captive APT supply to secure concentrate access under tightening Chinese environmental permits.
For Market Incumbents: To counter ceramic cutting tool substitution in high-speed finishing applications, cemented carbide producers should deepen backward integration into concentrate sourcing through offtake agreements with compliant Chinese miners, while investing in nickel-iron binder R&D to meet REACH reformulation mandates. For New Entrants and Emerging Players: Enter via India's PLI-driven precision tooling buildout around Pune and Bengaluru, where localized powder demand is outpacing established supply relationships. Target additive manufacturing qualification for medical radiation shielding, leveraging shorter certification cycles than aerospace to establish reference accounts. For Investors and Strategic Acquirers: Plasma atomization capacity expansion by SpaceX and Relativity Space is the leading indicator that spherical powder supply will tighten before alternative producers scale. Position for 5-10 year holding periods around mid-cap reduction specialists with hydrogen furnace networks and pending aerospace qualifications, watching for cobalt price spikes that accelerate binder metal substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Supply | Captive APT access insulates margin from China's MEE enforcement and permit tightening. |
| Plasma Atomization Capacity Buildout | Spherical powder qualification by SpaceX and Relativity Space creates supply-constrained premium tier. |
| Nickel-Iron Binder Certification Investment | REACH Annex XVII compliance opens retained European tooling market share. |
| Direct Mill Relationship with Tier-1 Automotive | Bypassing distributors captures margin from consolidated procurement desks in Rhine-Ruhr cluster. |
| Urban Mining and Pyrometallurgical Recovery | End-of-life carbide recycling in Germany and Japan diversifies concentrate sourcing. |
Study Parameters
Multi-period observation of aerospace qualification timelines, REACH enforcement patterns, and Chinese mining permit issuance anchored the trend analysis, supplemented by interviews with hydrogen reduction furnace operators, cemented carbide procurement managers at Tier-1 automotive suppliers, plasma atomization technicians, APT trading desk executives, and ECHA regulatory affairs specialists. Secondary validation drew from customs concentrate trade data, SEC filings of listed powder producers, ECHA restriction proposal dossiers, and Chinese Ministry of Ecology and Environment enforcement bulletins. Bottom-up capacity modeling triangulated against top-down end-use demand segmentation.
Segment-weighting across product type, application, end user, and form dimensions calibrated volume and value distributions throughout the forecast period. Aerospace turbine blade adoption curves, additive manufacturing deposition system installations, and cemented carbide tool production indices fed industry-specific inputs. CAGRs derived from regression against historical price-volume relationships and projected qualification cycle completions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt Chinese concentrate export restrictions or accelerated ceramic cutting tool penetration. Aerospace material specification changes or ECHA binder metal reclassifications could revise demand trajectories. Material deviation in concentrate availability, qualification timeline extensions, or plasma atomization yield rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
HSLA Steel Plate Market
Metals
Titanium Mill Products Market
Metals
Smelting Chemicals Market
Metals
Grain Oriented Electrical Steel Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
North America Iron Casting Market
Metals
Metal Coil Lamination Market
Metals
Copper and Brass Flat Products Market
Metals
Zinc Ingots Market
Metals
Aluminium Powder Market
Metals
Ferrochrome Market
Metals
Steel Salvage Drums Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Global Titanium Metal Market
Metals
High Purity Aluminium Market
Metals
Platinum Group Metals Market