
 Chrome Metal Powder Market | 2026-2036
Chrome Metal Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Chrome Metal Powder Market Analysis
Subscription-based technical support and powder specification tuning is shifting how chrome metal powder suppliers monetize long-term relationships. GfE leverages its captive ferrochrome feedstock to sustain cost visibility across the value chain. Polema Industries competes through vacuum induction melting expertise that anchors its position in aerospace-grade powder production. Delachaux Group differentiates via integrated R&D centers that specialize in particle size distribution control for thermal spray applications.
Chrome metal powder consists of refined metallic chromium particles, typically produced through aluminothermic reduction or electrolytic refining, with purity grades ranging from 98% to 99.5% chromium content and particle sizes spanning 10 to 150 microns for industrial use. The material serves primarily as a feedstock for corrosion-resistant coatings, superalloy additions, and hardfacing applications where oxidation resistance and wear protection are critical. Powdered chrome occupies the largest volume share among product types due to its direct utility in thermal spray processes, while alloyed chrome commands premium positioning where nickel-chromium matrices serve jet engine components. Aerospace applications generate the highest margin pools as OEMs enforce stringent lot traceability and chemistry certification requirements that exclude commoditized suppliers.
EPA hazardous air pollutant standards and REACH substance restrictions shape chrome metal powder formulation requirements, particularly regarding hexavalent chromium content thresholds in finished materials. OSHA permissible exposure limits for airborne chromium compounds drive investment in closed-loop powder handling systems across North American fabrication facilities. ISO 13485 and AS9100 quality frameworks govern aerospace supplier qualification, creating structural barriers for uncertified producers seeking entry into turbine engine supply chains. Stakeholders must monitor evolving EU Green Deal material passport requirements and assess whether in-house electrolytic capacity or external sourcing better serves emerging carbon footprint disclosure obligations.
Market Dynamics
Aerospace OEMs now mandate closed-loop powder traceability systems, forcing suppliers to retrofit legacy production lines with lot-tracking infrastructure that captures chemistry certification at every process node.
Growth Catalysts
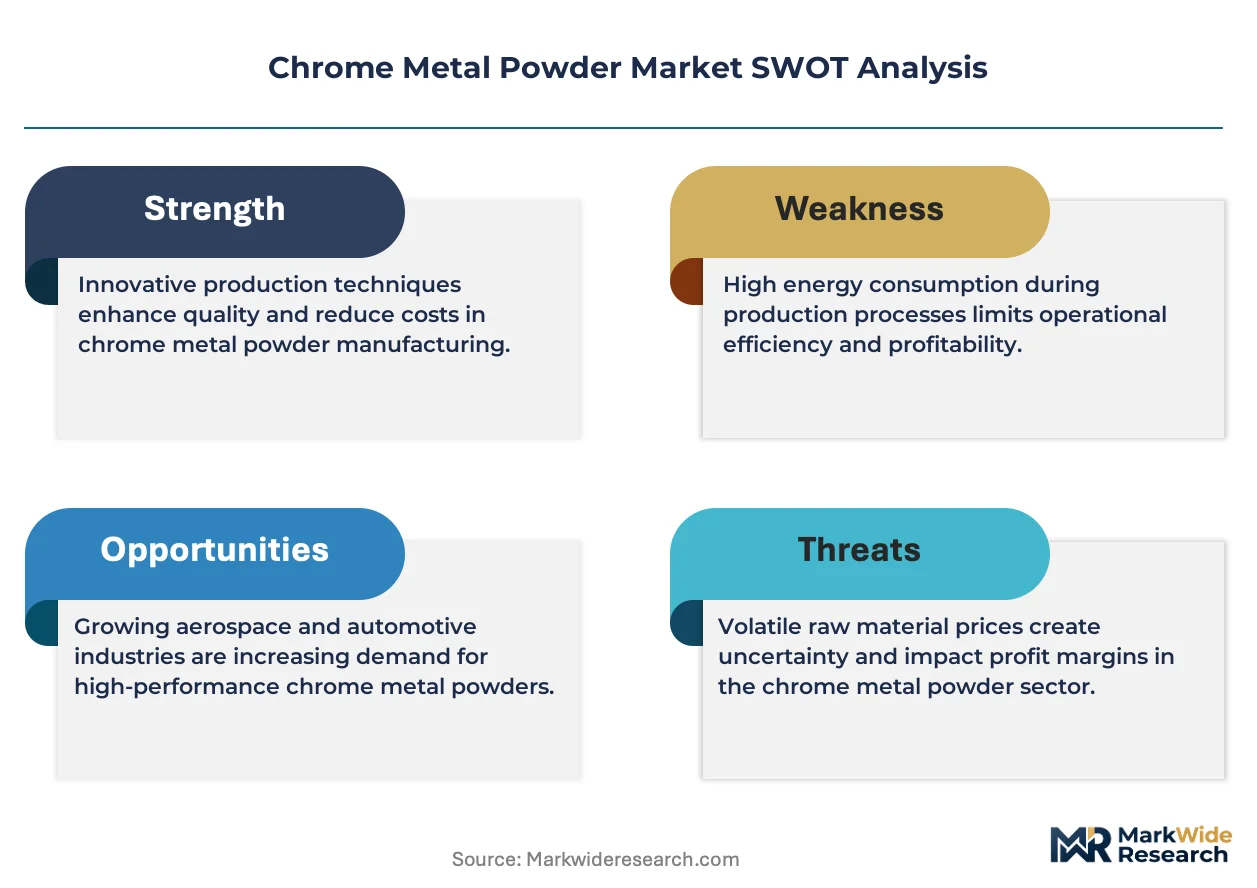
- REACH substance restrictions:European coating houses are accelerating substitution of hexavalent chromium-bearing materials with trivalent chrome powders, redirecting specification demand toward certified suppliers.
- Thermal spray automation:Robotic coating cells in turbine blade repair facilities are consuming higher volumes of tightly-sized powder fractions, tightening particle distribution tolerances.
- Ferrochrome conversion capacity:Central European metallurgical clusters sustain dedicated powder atomization lines that shorten lead times for aerospace-grade material.
Market Restraints
- Electrolytic feedstock volatility:Chrome metal powder production depends on chromium metal cathode availability, whose pricing fluctuates with South African ore export disruptions.
- Aluminothermic capacity concentration:High-purity reduction furnaces cluster in former Soviet industrial zones, creating single-source vulnerability for 99%+ purity grades.
- Plasma spray substitution:Tungsten carbide-cobalt coatings are displacing chrome-based materials in certain wear applications where hardness exceeds oxidation resistance requirements.
Strategic Opportunities
- India PLI scheme:Domestic aerospace component manufacturing incentives are attracting powder metallurgy investments for regional turbine supply chains.
- Additive manufacturing feedstock:Spherical chrome alloy powders for directed energy deposition are opening qualification pathways with rocket engine fabricators.
- EU Green Deal material passports:Carbon footprint disclosure mandates favor producers with captive renewable energy in electrolytic refining stages.
Industry Challenges
- AS9100 certification timelines:New entrants face 18-24 month qualification periods before aerospace OEMs approve lot shipments for flight-critical components.
- Closed-loop handling retrofit costs:OSHA-compliant powder containment systems require capital outlays that strain mid-scale atomization operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chrome Metal Powder Market |
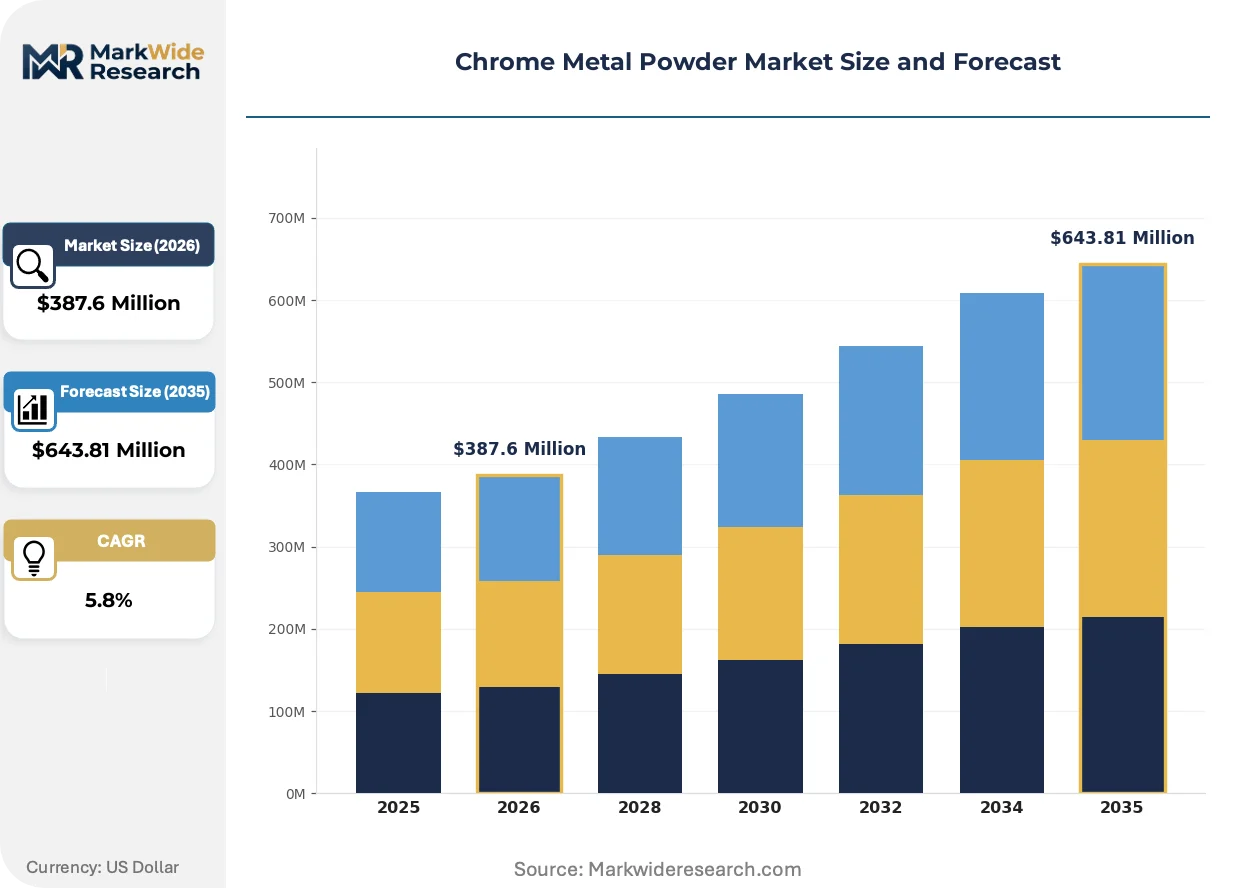
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Chrome, Coated Chrome, Alloyed Chrome, Ultra-Fine Chrome Application: Aerospace, Automotive Components, Electronic Devices, Industrial Coatings End User: Aerospace Manufacturers, Automotive Suppliers, Electronics Firms, Metal Fabricators Distribution Channel: Direct Sales, Online Marketplaces, Distributors, Resellers |
| Companies Covered | GfE (Gesellschaft für Elektrometallurgie), Polema Industries, Delachaux Group, MidUral Group, Global Metal Powders, EXO Tech, Hascor International Group, Kohsei Co., Ltd., Bell Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chrome Metal Powder Market Emerging Trajectories
Atomization technology advances are fragmenting the supplier base into specialized tiers, with equipment differentiation now determining which producers can access aerospace certification pathways versus commoditized industrial coating segments.
Plasma rotating electrode process (PREP) technology is expanding into spherical powder production for additive manufacturing applications. Rocket engine manufacturers in the United States are qualifying PREP-derived chrome-nickel superalloy powders for combustion chamber components. This capability expansion is compressing the addressable market for conventional gas-atomized material in premium segments.
EPA hazardous air pollutant standards for chromium compounds are forcing coating facilities to install ambient air monitoring networks. Job shops serving defense contractors face the steepest compliance costs, with some converting entirely to outsourced thermal spray services rather than maintaining in-house powder handling permits. The regulatory pressure is consolidating demand toward integrated coating houses with environmental engineering staff.
Specification tuning as a subscription service is displacing transactional powder sales in precision coating segments. German thermal spray houses now contract directly with atomization specialists for quarterly particle size distribution adjustments tied to specific robotic cell parameters. This service bundling is most visible in Central European aerospace repair networks where lot-to-lot consistency commands premium positioning over spot pricing.
Chrome Metal Powder Market Segmentation
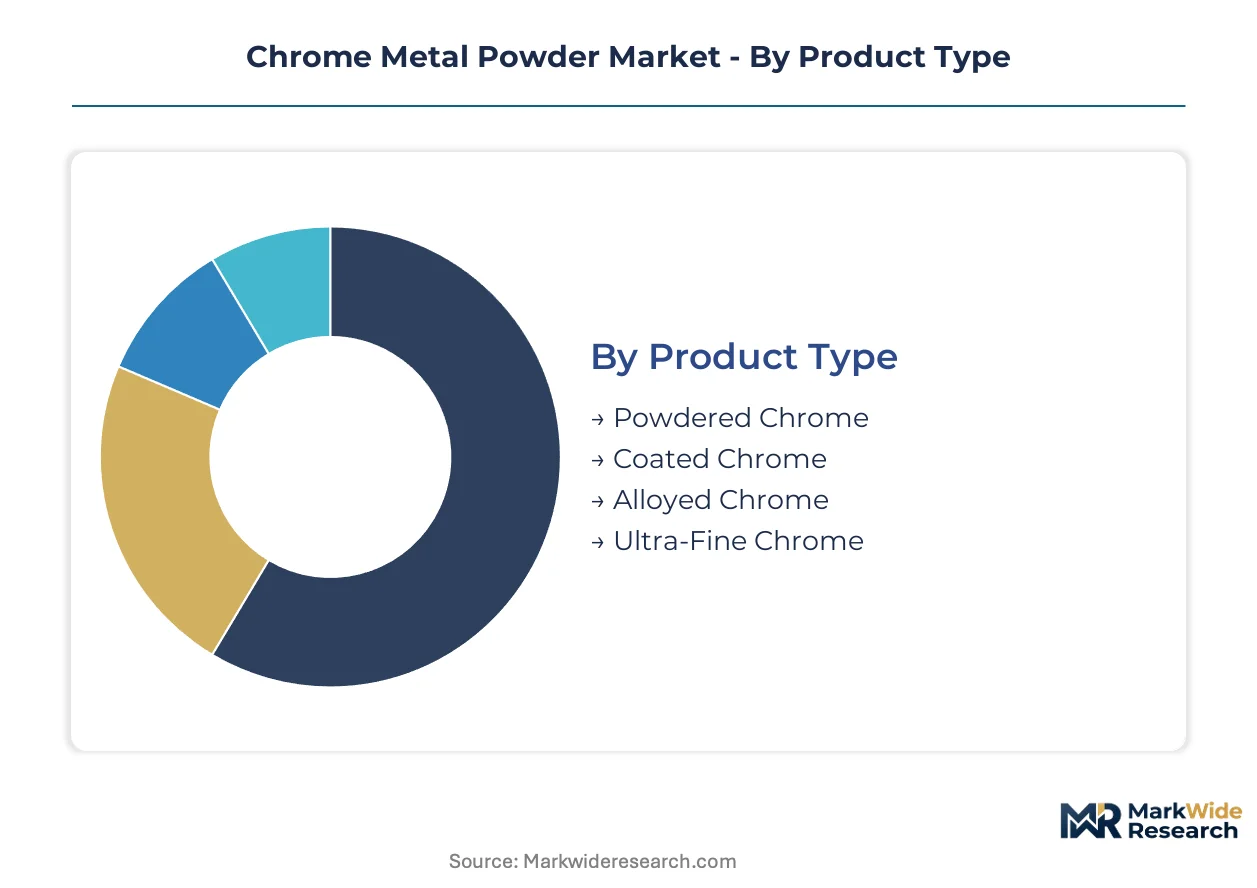
Chrome metal powder suppliers structure their operations around distinct technical specifications and certification requirements that govern pricing power. Segmentation reveals where capital deployment yields sustainable margins versus commoditized volume plays.
Product Type:
Capital intensity varies dramatically across production technologies, with electrolytic refining and advanced atomization systems demanding the heaviest upfront investment.
- Powdered Chrome:Gas-atomized particles spanning 10 to 150 microns serve thermal spray processes where oxidation resistance is paramount. Demand concentrates in German precision coating houses serving Central European turbine repair networks, driven by REACH-mandated substitution away from hexavalent chromium alternatives.
- Alloyed Chrome:Nickel-chromium matrices produced through vacuum induction melting command premium positioning for jet engine components. Aerospace OEMs in the United States enforce AS9100 lot traceability that excludes uncertified atomization operations.
- Coated Chrome:Encapsulated particles prevent oxidation during storage and transport.
- Ultra-Fine Chrome:Sub-10 micron fractions target specialized electronic applications.
Most installed capacity flows through Powdered Chrome. Expansion is steepest in Alloyed Chrome.
Application:
Margin structures diverge sharply based on certification burden and chemistry verification requirements.
- Aerospace:Turbine blade coatings and combustion chamber components require closed-loop powder traceability systems capturing chemistry certification at every process node. Thermal spray automation in repair facilities is tightening particle distribution tolerances for flight-critical applications.
- Industrial Coatings:Hardfacing and corrosion-resistant layers for oilfield equipment and power generation infrastructure consume standardized powder grades where price competition is intense.
- Automotive Components:Piston rings and valve seat coatings represent steady volume demand.
- Electronic Devices:Thin-film deposition and magnetic materials use ultra-high purity fractions.
Aerospace commands the widest margin spreads. Industrial Coatings absorbs the greatest tonnage.
End User:
Procurement sophistication determines whether suppliers can monetize technical support services or compete on spot pricing.
- Aerospace Manufacturers:OEMs and tier-1 fabricators mandate 18-24 month AS9100 qualification periods before approving lot shipments. Subscription-based specification tuning is displacing transactional sales in this segment.
- Metal Fabricators:Job shops serving defense contractors face steep OSHA compliance costs for ambient air monitoring networks, consolidating demand toward integrated coating houses with environmental engineering staff.
- Automotive Suppliers:Volume procurement of standardized grades for powertrain components.
- Electronics Firms:Specialized purity requirements for semiconductor and magnetic applications.
Aerospace Manufacturers concentrate the highest value procurement. Metal Fabricators present the steepest compliance-driven consolidation.
Distribution Channel:
Channel selection reflects customer technical sophistication and lot size requirements.
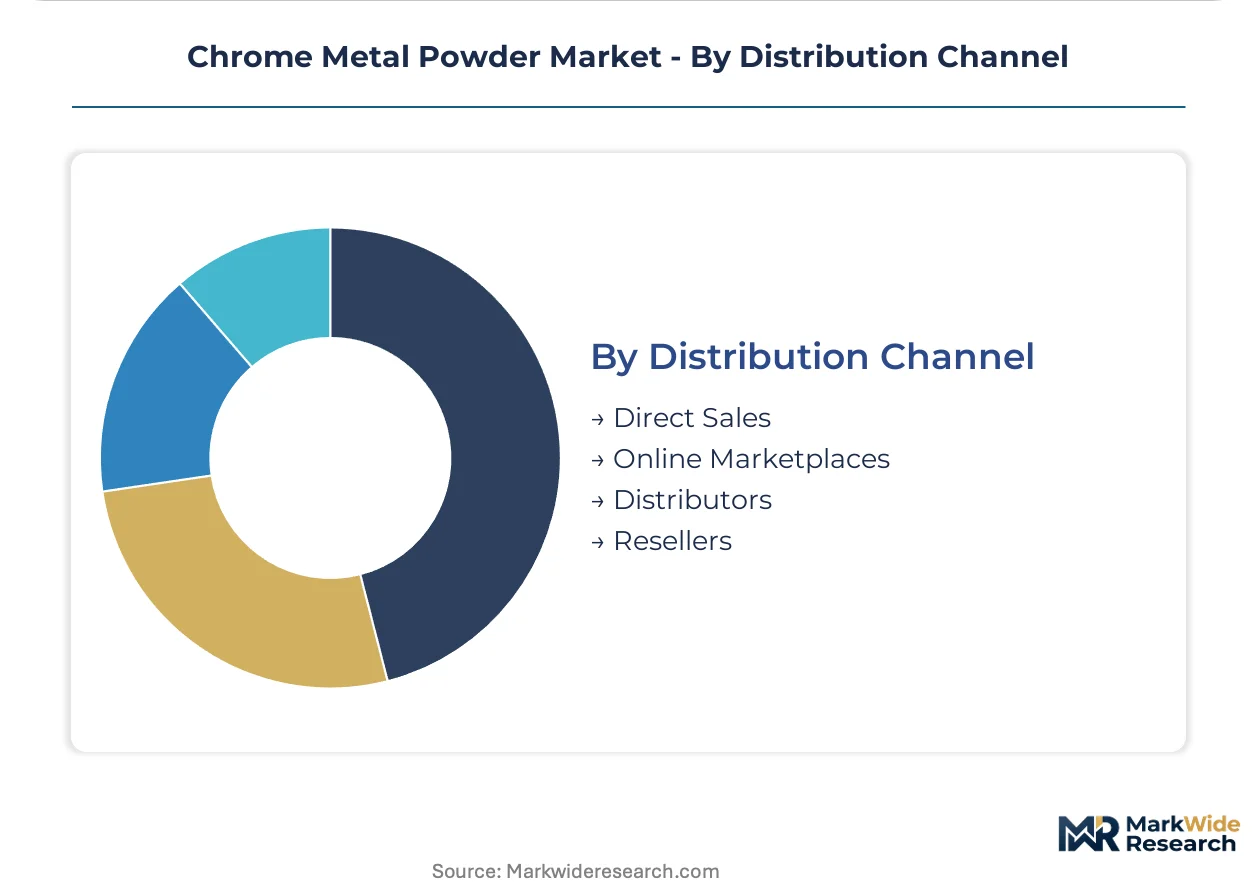
- Direct Sales:Atomization specialists contract directly with aerospace repair networks for quarterly particle size distribution adjustments tied to specific robotic cell parameters.
- Distributors:Regional stocking points serve mid-scale fabrication facilities requiring shorter lead times than transoceanic direct shipment.
- Online Marketplaces:Standardized industrial grades for research and small-batch prototyping.
- Resellers:Fragmented access to niche specifications for geographically isolated end users.
Direct Sales captures the premium service contracts. Distributors handle the broadest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting chrome metal powder production toward jurisdictions where REACH compliance costs and EPA emissions enforcement create asymmetric operating burdens. Suppliers with captive ferrochrome conversion in lower-regulation environments gain cost visibility while European coating houses absorb premium pricing for certified material.
Germany
Aerospace repair networks in North Rhine-Westphalia and Bavaria concentrate demand for AS9100-certified alloyed chrome powders. ECHA REACH substance restrictions on hexavalent chromium compounds are accelerating specification shifts toward trivalent alternatives. GfE and Delachaux Group anchor specialized ferrochrome conversion capacity serving precision coating houses across Central Europe.
United States
Rocket engine fabricators in California and Texas are qualifying spherical chrome-nickel superalloy powders for combustion chamber components. EPA hazardous air pollutant standards for chromium compounds are forcing coating facilities to install ambient air monitoring networks. Thermal spray automation in Georgia and Ohio turbine repair facilities is tightening particle distribution tolerances.
China
Domestic aerospace component manufacturing is expanding procurement of alloyed chrome powders for turbine blade coatings. MIIT industrial standards and dual carbon goals are reshaping production standards for chrome metal powder suppliers. Yangtze River Delta metallurgical clusters sustain dedicated powder atomization lines shortening lead times for aerospace-grade material.
India
The PLI scheme for domestic aerospace component manufacturing is attracting powder metallurgy investments for regional turbine supply chains. BIS quality certification requirements are creating structural barriers for uncertified producers seeking entry into defense supply chains. Maharashtra and Karnataka fabrication hubs are consolidating demand toward integrated coating houses with environmental engineering staff.
Russia
High-purity aluminothermic reduction furnaces cluster in former Soviet industrial zones, creating single-source vulnerability for 99%+ purity grades. The country's national environmental regulator is implementing stricter emissions controls on metallurgical operations. MidUral Group operations in the Ural Federal District sustain captive feedstock integration for specialized ferrochrome conversion.
Chrome Metal Powder Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace qualification requirements favoring established atomization operations over commoditized industrial suppliers. The vendor base concentrates around three tiers: integrated metallurgical groups with captive ferrochrome feedstock, specialized powder atomization houses with vacuum induction melting expertise, and regional distributors serving job shops with standardized grades. Strategic moves center on backward integration into electrolytic refining capacity and technology licensing for plasma rotating electrode process equipment.
Within the integrated metallurgical tier, GfE and Delachaux Group exemplify producers leveraging captive ferrochrome conversion to sustain cost visibility across the value chain. Polema Industries occupies a position among specialized atomization houses where vacuum induction melting expertise anchors access to aerospace certification pathways. These three entities represent distinct archetypes: feedstock-integrated European specialists, process-technology-focused precision powder producers, and diversified metallurgical groups with integrated R&D infrastructure.
| Leading Market Players |
|---|
| GfE (Gesellschaft für Elektrometallurgie) |
| Polema Industries |
| Delachaux Group |
| MidUral Group |
| Global Metal Powders |
| EXO Tech |
| Hascor International Group |
| Kohsei Co., Ltd. |
| Bell Group |
| Others |
Supply Flow & Price Mechanics
Aerospace OEM procurement mandates for closed-loop powder traceability are forcing atomization specialists to absorb capital costs for lot-tracking infrastructure, compressing margins on standardized grades while amplifying pricing power for certified suppliers with captive ferrochrome conversion.
Pricing Analysis
Distributor margins in thermal spray supply chains typically capture 15-25% markups over atomization house ex-works pricing, though direct-to-OEM contracts for aerospace-grade alloyed chrome command volume discounts tied to multi-year offtake commitments. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified nickel-chromium matrices from REACH-compliant industrial coatings and unverified commodity powders. Pricing pressure stems from South African chromium cathode supply disruptions that feed into electrolytic refining cost bases. Metal fabricators serving defense contractors exhibit the highest price sensitivity due to concurrent OSHA compliance capital burdens, while rocket engine fabricators prioritize chemistry certification over unit cost.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for aerospace component manufacturing are redirecting powder metallurgy investments toward Maharashtra and Karnataka fabrication hubs, shortening regional lead times for turbine supply chains. Production gravity centers on Germany for precision coating feedstock, Russia for high-purity aluminothermic reduction capacity, and China for Yangtze River Delta atomization clusters. Raw material flows draw from South African chromium ore, Central European ferrochrome conversion, and electrolytic cathode inventories. Single-source vulnerability pervades 99%+ purity grades concentrated in former Soviet industrial zones. Distribution runs through direct sales contracts with aerospace repair networks, regional distributors for mid-scale fabricators, and online marketplaces for research-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chrome metal powder market functions as a stable compounder anchored by irreversible regulatory substitution away from hexavalent chromium compounds, generating sustained specification upgrade cycles across European and North American coating houses.
For Market Incumbents: Cement AS9100 certification moats by accelerating backward integration into captive electrolytic refining capacity, insulating cost structures from South African ore export volatility. Expand vacuum induction melting throughput in Central European clusters to capture thermal spray automation demand from robotic coating cell deployments. Plasma spray substitution threats from tungsten carbide-cobalt coatings in wear applications necessitate R&D investment in oxidation-resistant alloy formulations that defend aerospace positioning.
For New Entrants and Emerging Players: Begin with spherical chrome-nickel superalloy powder qualification for directed energy deposition feedstock, where rocket engine fabricators in the United States and China are actively sourcing additive manufacturing materials outside established supply relationships. Target Indian domestic aerospace component manufacturing under PLI scheme incentives, where BIS certification barriers are surmountable with localized metallurgical partnerships. Pursue specification tuning service contracts as the primary go-to-market mechanism rather than transactional spot sales.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized atomization houses possessing PREP technology capabilities for spherical powder production, given additive manufacturing feedstock qualification timelines that exclude commoditized gas-atomized suppliers. Long-term viability across the analysis window favors producers with integrated ferrochrome conversion and renewable energy-tied electrolytic capacity that satisfies emerging EU Green Deal material passport requirements. Watch for EPA hazardous air pollutant enforcement intensity in Georgia and Ohio turbine repair corridors as an inflection signal for outsourced thermal spray service consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolytic Refining | GfE and Delachaux Group leverage captive ferrochrome feedstock to sustain cost visibility across chromium cathode price volatility. |
| PREP Technology Licensing | Polema Industries anchors aerospace certification pathways through vacuum induction melting expertise in spherical powder production. |
| Long-term Supply Agreement with OEMs | Direct sales contracts with German precision coating houses lock in quarterly particle size distribution adjustments for robotic cell parameters. |
| AS9100 Certification Investment | Eighteen to twenty-four month qualification periods create structural barriers excluding uncertified producers from turbine engine supply chains. |
| Green Manufacturing Transition | EU Green Deal material passport requirements favor atomization operations with captive renewable energy in electrolytic refining stages. |
Methodological Framework
Bottom-up aerospace and industrial coating demand modeling reconciled against top-down ferrochrome conversion and atomization capacity tracking forms the analytical core of this study. Primary interviews with powder metallurgy plant managers, thermal spray coating house technical directors, aerospace OEM procurement leads, and REACH compliance officers at European coating facilities combined with secondary validation from ECHA substance restriction databases, EPA hazardous air pollutant enforcement records, SEC filings of listed metallurgical groups, and customs trade data for chromium metal cathode flows. Triangulation between end-use consumption estimates and supply-side production surveys ensures convergence on volume and value outputs.
Input-output matrices map chromium ore extraction through ferrochrome conversion, electrolytic refining, and final atomization stages across the projection horizon, with segmentation dimensions spanning product type, application, and end-user procurement sophistication. CAGRs derive from elasticity-adjusted demand curves incorporating thermal spray automation penetration rates and REACH-mandated hexavalent chromium substitution timelines. Industry-specific forecast inputs include robotic coating cell deployment data from turbine repair facilities and PREP technology qualification progress with rocket engine fabricators.
Several conditions sit outside the modeled scope, including geopolitical disruption to South African ore export corridors, unanticipated breakthroughs in plasma spray coating formulations, and abrupt shifts in EPA or ECHA enforcement intensity. Forecasts reflect documented assumptions regarding regulatory compliance cost absorption and certification timeline stability. A small set of named triggers warrants ongoing watch: electrolytic cathode price volatility, AS9100 audit backlog accumulation, and EU Green Deal carbon footprint disclosure implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Casting Market
Metals
Iron Ore Market
Metals
Molybdenum Market
Metals
Copper Powder Market
Metals
High Purity Boron Market
Metals
Amorphous Metal Cores Market
Metals
Platinum Compounds Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Welding Materials Market
Metals
High Purity Pig Iron Market
Metals
Zirconium Market
Metals
Base Metals Market
Metals
Expanded Metal Foils Market
Metals
Silico Manganese Market
Metals
High Purity Lead Market
Metals
Asia-Pacific Metal Finishing Market