
 Lithium-Ion Stationary Battery Storage Market | 2026-2036
Lithium-Ion Stationary Battery Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Stationary Battery Storage Market Analysis
Aftermarket service revenue is rewriting margin allocation across the value chain. Tesla leverages its integrated software-hardware stack to capture recurring revenue from energy management services. LG Chem anchors its position through captive cell supply and long-term service contracts with Korean utilities. Siemens Energy differentiates via turnkey engineering capabilities that extend from grid connection through decades-long O&M agreements.
Lithium-ion stationary battery storage denotes electrochemical systems using lithium intercalation compounds—typically lithium iron phosphate or nickel manganese cobalt oxide cathodes paired with graphite anodes—to absorb and discharge electrical energy at grid-connected or off-grid installations. These systems employ battery management systems maintaining cell voltage within 2.5–4.2 V ranges and thermal controls sustaining 15–35°C operating windows to prevent degradation and thermal runaway. Large-scale systems dominate installed capacity owing to utility procurement cycles and economies of stackable containerized architectures, while modular systems represent the fastest-expanding configuration as commercial and industrial buyers seek phased capital deployment without full upfront commitment.
The U.S. Federal Energy Regulatory Commission Order 841 mandates storage participation in wholesale markets, reshaping revenue stack economics for developers. China's National Energy Administration enforces grid-code compliance including GB/T 36276 testing protocols that restrict market access for non-certified suppliers. The EU Battery Regulation imposes carbon footprint disclosure and recycled content thresholds that will alter cell sourcing decisions for European projects. Stakeholders must track how evolving interconnection queues and local content requirements in multiple jurisdictions affect project timelines and supplier qualification.
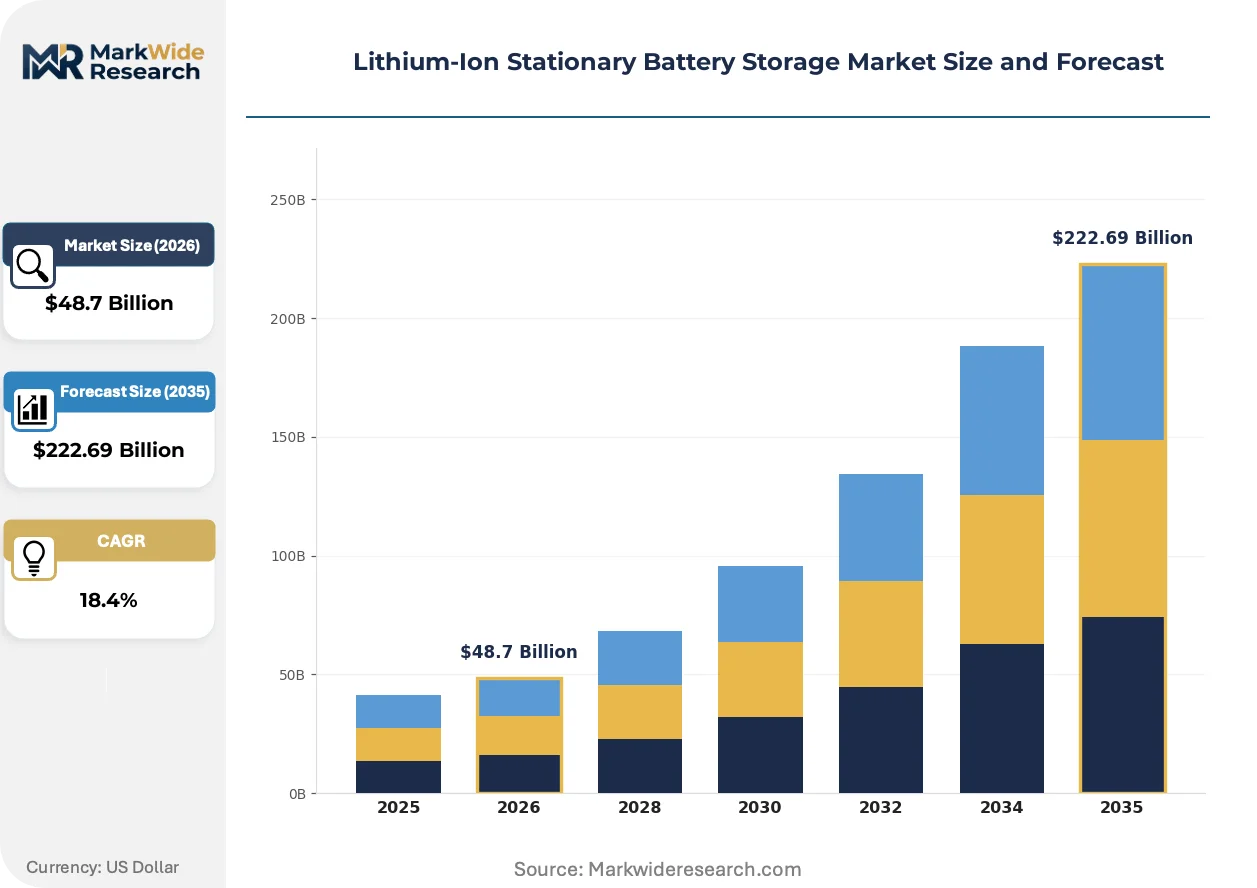
Market Dynamics
Utility procurement cycles and renewable intermittency management are compressing project development timelines while expanding containerized system deployments across high-penetration renewable zones.
Growth Catalysts
- Investment Tax Credits:The U.S. Inflation Reduction Act's energy storage incentives reduce project-levelized costs, accelerating developer commitment to multi-hundred-megawatt installations in Texas and California.
- Grid-Code Mandates:China's GB/T 36276 testing protocols create qualified supplier lists that channel procurement toward certified domestic manufacturers in Shandong and Jiangsu provinces.
- Lithium Iron Phosphate Chemistry:LFP cathode formulations displace nickel manganese cobalt in utility-scale contracts due to superior thermal stability and extended cycle life under high-utilization duty cycles.
Market Restraints
- Raw Material Concentration:Spodumene concentrate processing and cathode precursor refining concentrate in Chinese industrial clusters, exposing non-Chinese developers to supply disruption and price volatility.
- Interconnection Queues:Federal Energy Regulatory Commission jurisdiction over transmission access creates multi-year study backlogs in PJM and CAISO territories, delaying revenue commencement.
- Degradation Uncertainty:Calendar and cycle aging variability across temperature regimes complicates long-term revenue forecasting and debt structuring for merchant storage assets.
Strategic Opportunities
- Behind-the-Meter C&I:Commercial and industrial buyers in Germany and the Netherlands seek phased modular deployments to manage peak demand charges without full upfront capital commitment.
- Hybrid Renewable-Storage:Co-located solar-plus-battery configurations capture investment tax credit stacking and reduce interconnection costs through shared substation infrastructure.
- Second-Life Automotive Packs:Retired electric vehicle batteries from Nissan and BMW fleets enter stationary applications at 60-80% remaining capacity, creating circular supply streams for frequency regulation services.
Industry Challenges
- Thermal Runaway Mitigation:Battery management system firmware validation and fire suppression system integration require specialized fire engineering expertise that outstrips current training pipeline output.
- Revenue Stack Complexity:Developers must simultaneously optimize energy arbitrage, ancillary services, and capacity market participation across overlapping ISO/RTO protocols with divergent metering requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Stationary Battery Storage Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small-Scale Systems, Large-Scale Systems, Modular Systems, Standalone Systems Application: Renewable Integration, Backup Power, Frequency Regulation, Grid Stabilization End User: Utilities, Commercial, Industrial, Residential Technology: LFP, NMC, LTO, NCA |
| Companies Covered | Tesla, LG Chem, Panasonic Corporation, Johnson Controls, GS Yuasa International Ltd, BYD Company Ltd, Siemens Energy, Hitachi Energy Ltd, Exide Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Stationary Battery Storage Market Emerging Trajectories
Artificial intelligence and predictive analytics are penetrating control system architectures, compressing dispatch optimization cycles from minutes to seconds while enabling autonomous market participation.
Digital twin technology is digitizing battery degradation forecasting by creating physics-informed machine learning models that predict cell-level state-of-health trajectories. Utility asset managers in California deploy these tools to optimize warranty claims and replacement scheduling. The technology compresses operational uncertainty and enables longer-duration debt tenors for project finance.
Europe's Battery Regulation imposes carbon footprint disclosure thresholds and recycled content mandates that reshape cell sourcing decisions for projects commissioned after 2027. Developers must trace supply chain emissions from mining through manufacturing or face market exclusion. German and French utilities now require supplier sustainability certifications that exceed baseline CE marking requirements.
Merchant developers are unbundling hardware procurement from long-term service agreements, creating competitive tension between integrated manufacturers and independent O&M specialists. Texas and Australian project sponsors increasingly separate EPC contracts from 15-20 year asset management agreements, enabling vendor selection based on distinct capability criteria rather than single-source bundling.
Lithium-Ion Stationary Battery Storage Market Segmentation
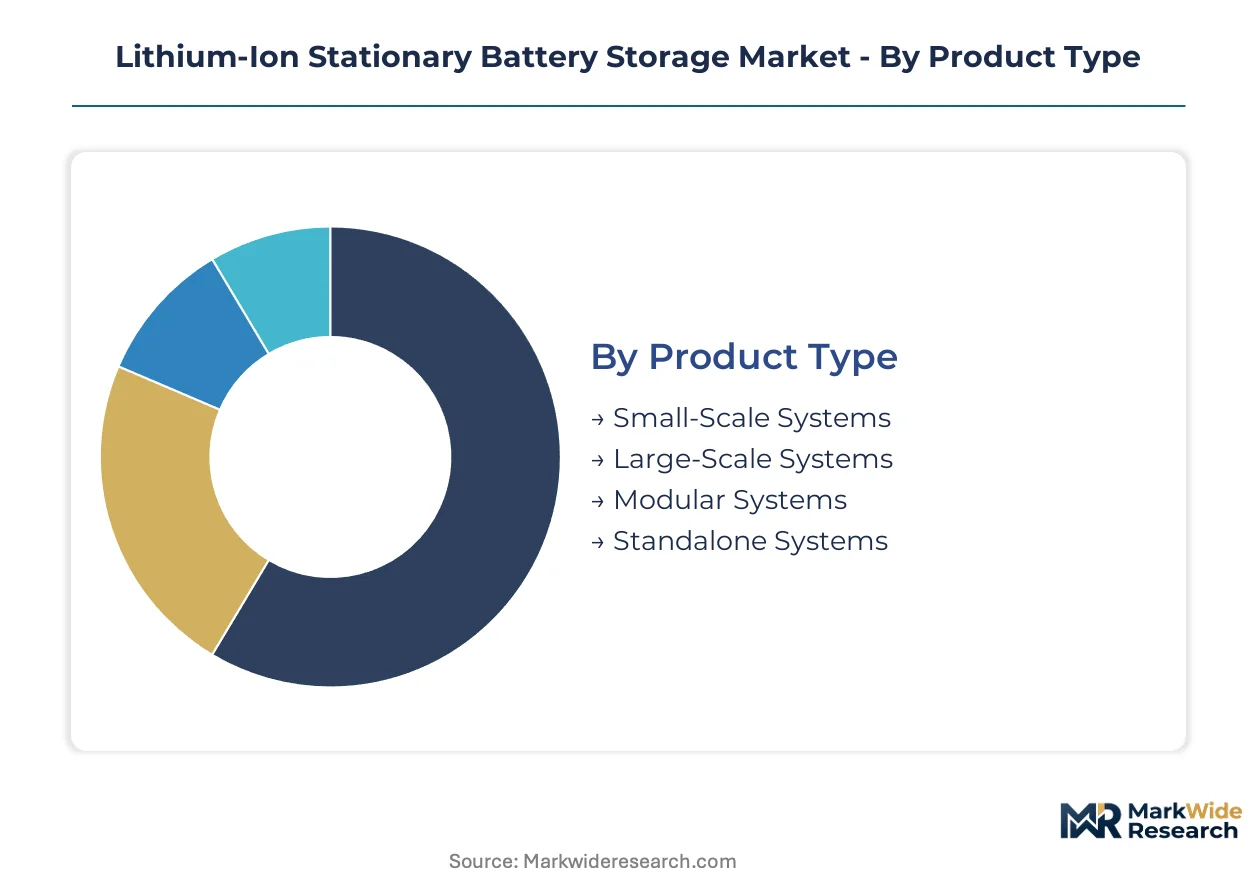
Segmentation reveals how service intensity varies across deployment scales and duty cycles. Procurement patterns diverge sharply between utility-scale tenders requiring 20-year O&M commitments and behind-the-meter installations favoring modular expansion paths.
Product Type:
After-sales service intensity escalates with system scale and integration complexity, creating divergent margin pools across the hardware-service bundle.
- Large-Scale Systems:Containerized megawatt-hour installations dominate utility procurement in California and Texas, where 15-year performance guarantees and predictive maintenance contracts anchor developer revenue models. These systems require specialized thermal management and fire suppression engineering that extends service attach rates.
- Modular Systems:Phased deployment architectures allow commercial buyers in Germany to scale capacity incrementally without full upfront capital exposure. The configuration is gaining share fastest among industrial peak-shaving applications.
- Small-Scale Systems:Residential installations in Japan and Australia rely on inverter-integrated packages with limited service differentiation.
- Standalone Systems:Purpose-built installations for off-grid mining operations in Chile and remote telecommunications infrastructure in Indonesia carry premium pricing for ruggedized enclosures.
By volume, Large-Scale Systems lead. By growth pace, Modular Systems are expanding most quickly.
Application:
Revenue stack complexity determines which applications command premium pricing and long-term service contracts versus commodity hardware sales.
- Renewable Integration:Co-located solar-plus-storage configurations in India and Brazil capture investment tax credit stacking while reducing interconnection costs through shared substation infrastructure. Developers in these markets prioritize DC-coupled architectures for efficiency gains.
- Frequency Regulation:Fast-response duty cycles in PJM and ERCOT markets favor lithium titanate chemistries with minimal degradation under high-utilization regimes. The application commands the steepest expansion trajectory among merchant storage developers.
- Grid Stabilization:Transmission-level deployments in the United Kingdom and South Korea address voltage support and inertia replacement as renewable penetration rises.
- Backup Power:Critical facility protection for data centers in Singapore and hospitals in Saudi Arabia emphasizes instantaneous response over cycling economics.
Renewable Integration captures the largest installed base. Frequency Regulation is climbing the fastest as market mechanisms mature.
End User:
Procurement sophistication and contract duration separate utility buyers from commercial and industrial segments.
- Utilities:Vertically integrated operators in China and vertically separated ISO participants in Texas negotiate multi-hundred-megawatt supply agreements with 20-year service riders. These buyers mandate GB/T 36276 or UL 9540 certification as table stakes.
- Industrial:Manufacturing facilities in the Netherlands and petrochemical complexes in Belgium seek peak demand charge reduction through behind-the-meter installations with phased expansion rights.
- Commercial:Retail chains and office portfolios in France prioritize ESG reporting alignment over pure economic returns.
- Residential:Solar-plus-storage adopters in California and Hawaii respond to net metering revisions and time-of-use rate structures.
Utilities dominate megawatt-hour procurement. Industrial buyers are gaining share fastest as retail rates rise.
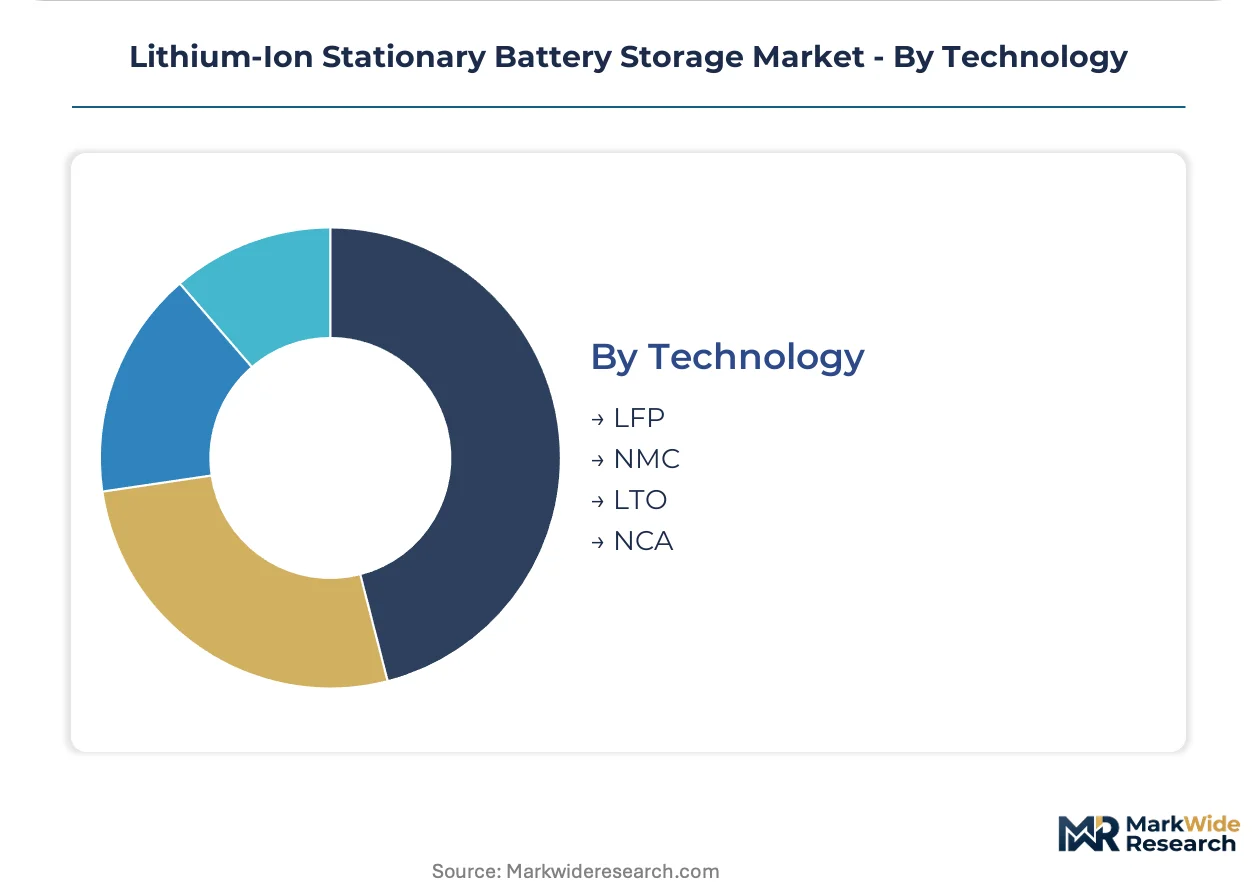
Technology:
Chemistry selection trades energy density against cycle life and thermal stability, with implications for fire safety engineering and warranty pricing.
- LFP:Lithium iron phosphate formulations displace nickel-based alternatives in utility-scale contracts due to superior thermal stability and extended calendar life under high-temperature ambient conditions in Arizona and Rajasthan.
- NMC:Nickel manganese cobalt oxide retains position in space-constrained urban installations in Seoul and Tokyo where energy density premium justifies higher material costs.
- LTO:Lithium titanate anode systems serve high-frequency cycling applications in frequency regulation markets with minimal capacity fade.
- NCA:Nickel cobalt aluminum oxide remains confined to premium residential and commercial segments requiring maximum gravimetric energy density.
LFP leads in megawatt-hour deployment. LTO is expanding most quickly in ancillary services markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developers in Germany and California exhibit the lowest price elasticity, absorbing premium pricing for certified supply chains, while Chinese buyers in Shandong and Jiangsu drive hard on procurement costs through qualified supplier list competition.
United States
ERCOT and CAISO territories dominate utility-scale deployments as merchant developers chase energy arbitrage and ancillary services revenue. FERC Order 841 mandates storage participation in wholesale markets, compressing interconnection study timelines. Texas leads installed capacity with multi-hundred-megawatt projects clustering around Houston and Dallas transmission nodes.
China
Shandong and Jiangsu provinces anchor grid-scale procurement as provincial grid operators enforce GB/T 36276 certification for market access. The National Energy Administration's dual carbon goals accelerate coastal deployment in Guangdong and Fujian. Domestic cell manufacturers in Ningde and Shenzhen capture qualified supplier list advantages.
Germany
Commercial and industrial buyers in North Rhine-Westphalia and Bavaria drive behind-the-meter modular adoption to manage peak demand charges. The EU Battery Regulation imposes carbon footprint disclosure thresholds reshaping cell sourcing after 2027. Industrial clusters around Munich and Cologne prioritize ESG-aligned supplier certification.
Australia
Frequency regulation markets in Victoria and South Australia favor lithium titanate chemistries for minimal degradation under high-utilization cycling. The national electricity market's five-minute settlement rule rewards fast-response assets. Remote mining operations in Western Australia deploy ruggedized standalone systems for off-grid power.
India
Co-located solar-plus-storage configurations in Rajasthan and Gujarat capture state-level renewable purchase obligation compliance. The Central Electricity Authority mandates storage procurement for interstate transmission-connected solar parks. Manufacturing incentives under the PLI scheme concentrate cell assembly in Tamil Nadu and Andhra Pradesh.
Lithium-Ion Stationary Battery Storage Market Vendor Landscape
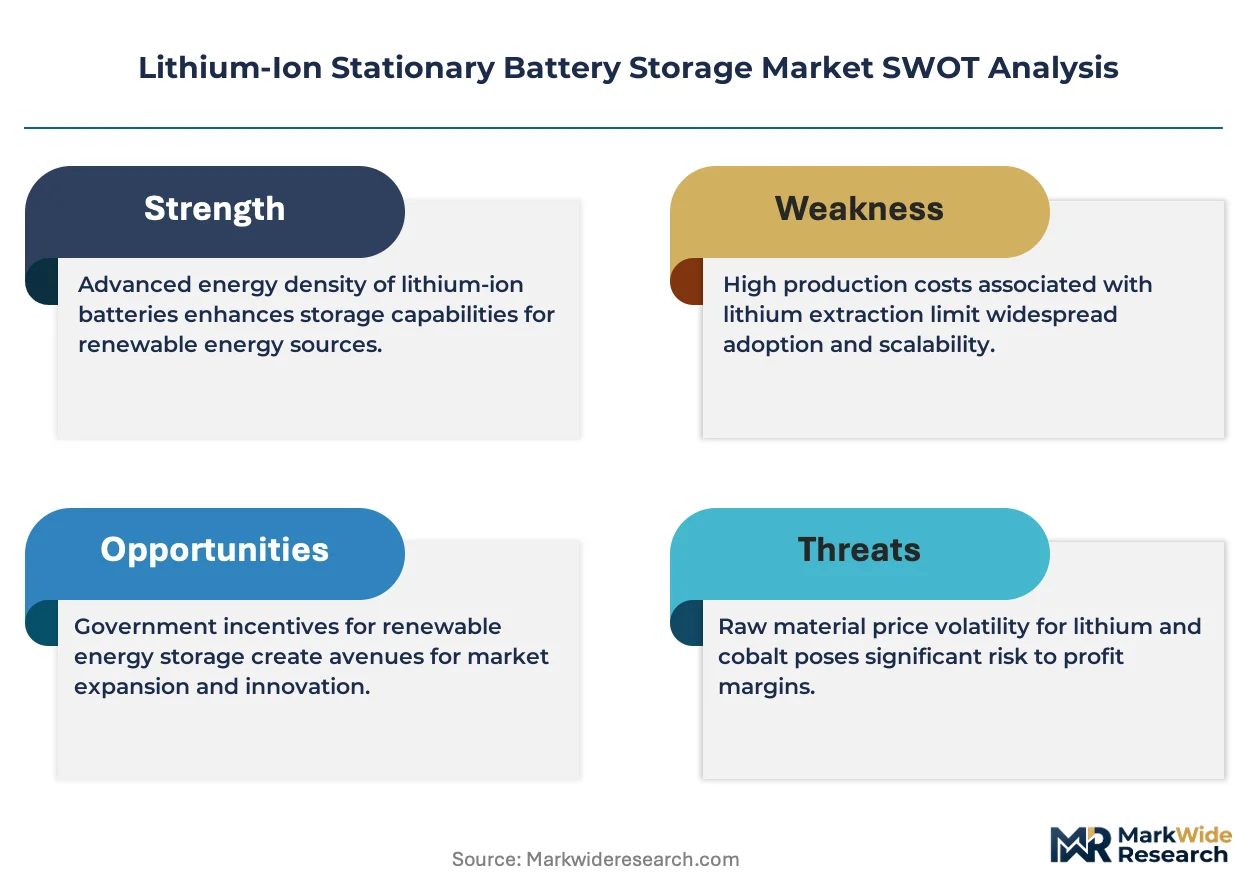
Capability concentration sits with integrated technology stacks; scale advantage sits with captive cell supply and long-term utility relationships. The vendor base organizes into three tiers: multinational conglomerates with turnkey engineering depth, specialized battery manufacturers with chemistry control, and independent system integrators with software differentiation. Dominant competitive moves include backward integration into cell production and unbundling of hardware procurement from decades-long O&M agreements.
Within the integrated technology tier, Tesla exemplifies software-hardware stack control, while LG Chem anchors the chemistry-specialist position through captive supply relationships. Siemens Energy occupies the turnkey engineering archetype, extending from grid connection through long-term asset management agreements. These three represent distinct capability configurations rather than interchangeable competitors.
| Leading Market Players |
|---|
| Tesla |
| LG Chem |
| Panasonic Corporation |
| Johnson Controls |
| GS Yuasa International Ltd |
| BYD Company Ltd |
| Siemens Energy |
| Hitachi Energy Ltd |
| Exide Technologies |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Long Beach container freight corridors transmit cost volatility from cathode precursor processing clusters directly into California project economics, compressing margins for developers without captive cell supply while amplifying price differentiation between certified and non-certified supplier tiers.
Pricing Analysis
After-sales service contracts spanning 15-to-20-year O&M agreements generate lifetime value multiples exceeding hardware-only sales by substantial margins. Three-tier pricing structure across premium, standard, and economy levels separates integrated turnkey providers from modular system vendors and commodity cell resellers, with UL 9540 and GB/T 36276 certification tiers commanding substantial premiums. Cost compression in the economy tier is intensifying because Chinese qualified supplier list competition drives procurement bidding below fully loaded service costs. Utility buyers in Texas and California exhibit the lowest price sensitivity, absorbing premiums for decades-long performance guarantees, while commercial and industrial segments in Germany negotiate hardest on upfront capital exposure.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment and advanced battery materials processing technology limit non-Chinese developers' access to next-generation cathode coating and dry electrode fabrication methods. Spodumene concentrate processing concentrates in Chinese industrial clusters around Sichuan and Hunan, with cathode precursor refining anchored in South Korean cathode plants and Japanese electrolyte formulation facilities. Raw material dependencies on Australian hard-rock lithium, Indonesian nickel, and Chilean copper expose the value chain to commodity price volatility and geopolitical sourcing disruption. Distribution runs through tier-one EPC contractors with utility relationships, who bundle hardware procurement with long-term service agreements to capture recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards participants who control scarce capabilities in thermal engineering and predictive degradation analytics, while punishing pure hardware vendors exposed to commodity cell pricing cycles.
For Market Incumbents: Build switching-cost moats through integrated software-hardware stacks that embed AI-driven dispatch optimization and autonomous market participation. Deepen backward integration into cell production to secure qualified supplier list positioning under China's GB/T 36276 protocols. Expand fire engineering training pipelines to address the capability gap in thermal runaway mitigation that outstrips current certification output. For New Entrants and Emerging Players: Establish a beachhead in behind-the-meter modular systems for commercial and industrial peak-shaving applications in Germany and the Netherlands, where phased capital deployment preferences create white-space outside utility-scale procurement cycles. Target second-life automotive pack integration for frequency regulation services, leveraging retired Nissan and BMW fleet batteries at 60-80% remaining capacity. Pursue direct sales to industrial facilities seeking ESG-aligned supplier certification under EU Battery Regulation carbon footprint thresholds. For Investors and Strategic Acquirers: Independent system integrators with software differentiation and established utility O&M relationships represent the most defensible acquisition archetype for exposure to recurring revenue expansion. Long-term viability rests on the transition from hardware-transactional to service-recurring revenue models across the projection horizon. Watch interconnection queue clearance rates in PJM and CAISO territories as the inflection signal for merchant storage asset deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cell Production Buildout | Secures GB/T 36276 qualified supplier list access for Chinese provincial utility tenders. |
| Digital Twin Platform Deployment | Enables physics-informed degradation forecasting that compresses operational uncertainty for project finance. |
| Second-Life Battery Integration | Creates circular supply streams from retired Nissan and BMW electric vehicle fleets. |
| Long-Term O&M Contract Unbundling | Separates EPC procurement from 15-20 year asset management agreements in Texas and Australia. |
| EU Battery Regulation Compliance Program | Establishes carbon footprint traceability from mining through manufacturing for post-2027 market access. |
Methodological Framework
Desk research of FERC interconnection databases, EIA project development filings, and GB/T 36276 certification registries preceded structured interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators across North America, Europe, and Asia-Pacific. Primary fieldwork captured procurement cycle dynamics, qualification protocol evolution, and revenue stack optimization strategies. Secondary validation drew from IEA stationary storage outlooks, customs trade data on lithium compound flows, and SEC 10-K disclosures from integrated manufacturers. Bottom-up project pipeline aggregation was triangulated against top-down market sizing from regulatory mandate trajectories.
Assumptions around IRA investment tax credit continuity, Chinese dual carbon goal enforcement intensity, and EU Battery Regulation implementation timing were held fixed across baseline scenarios while sensitivity bands varied interconnection queue clearance rates and raw material price trajectories. Segmentation modeling incorporated system scale tier, application duty cycle, end-user procurement sophistication, and chemistry selection as core dimensions. CAGRs were derived from project development pipeline velocity correlated with regulatory mandate schedules and renewable penetration curves. Forecast inputs included merchant storage revenue stack evolution and behind-the-meter retail rate escalation patterns.
Stress conditions across lithium carbonate price spikes, FERC Order 841 implementation delays, and thermal runaway incident frequency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about policy continuity and technology cost curves that could revise substantially with regulatory repeal or breakthrough solid-state chemistry commercialization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market