
 Europe Lithium-Ion Battery for Electric Vehicle Market | 2026-2036
Europe Lithium-Ion Battery for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lithium-Ion Battery for Electric Vehicle Market Insights
Cell sourcing from Asian suppliers toward European domestic production is consolidating as Northvolt scales its Skellefteå gigafactory and CATL establishes German manufacturing. LG Energy Solution anchors cell supply for multiple European OEM platforms through its Polish operations. Samsung SDI competes in the premium segment with high-energy-density cylindrical cells for performance electric vehicles.
The Europe lithium-ion battery for electric vehicle comprises rechargeable electrochemical cells using lithium iron phosphate, nickel manganese cobalt, or nickel cobalt aluminum cathodes paired with graphite or silicon-composite anodes, typically operating at nominal voltages of 3.2–3.7 V per cell and energy densities of 150–300 Wh/kg depending on chemistry, manufactured through electrode coating, calendering, electrolyte filling, and formation cycling to enable repeated charge-discharge cycles for automotive traction applications. Prismatic formats dominate OEM platform designs due to efficient pack-level space utilization and thermal management integration, while lithium iron phosphate chemistry extends its share in entry-level passenger vehicles and commercial vehicle segments where cycle life and cost stability outweigh energy density requirements.
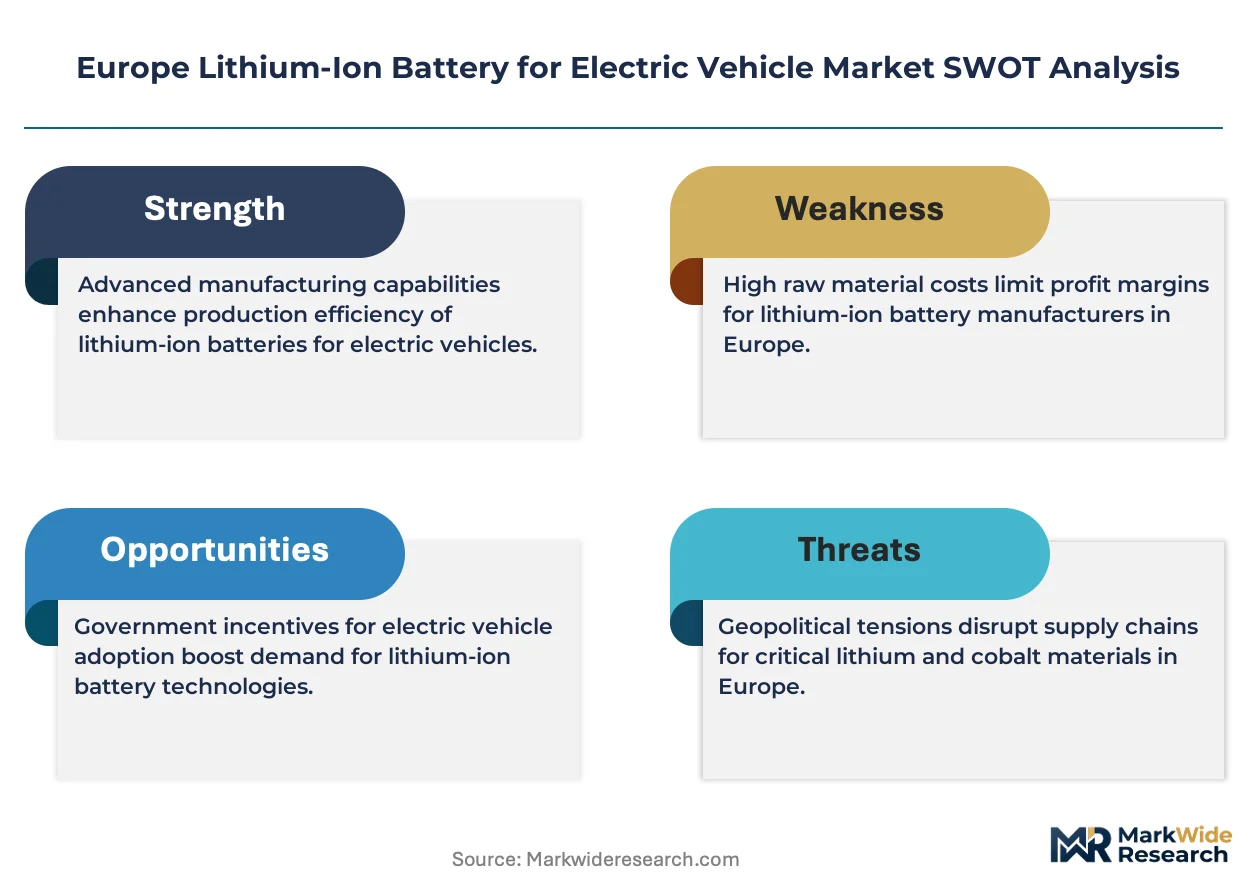
The EU Battery Regulation, CE marking requirements, and REACH chemical compliance frameworks collectively mandate carbon footprint labeling, recycled content minimums, and restricted substance controls that filter market access for non-compliant suppliers. EMA and ECHA documentation standards further shape cell material qualification timelines for European vehicle certification. Stakeholders must monitor regulatory evolution around digital battery passports and due diligence rules for raw material supply chains.
Market Dynamics
The EU Battery Regulation's recycled content mandates and carbon footprint declarations are forcing cell suppliers to requalify manufacturing processes and raw material sourcing, compressing certification timelines while elevating compliance costs across European OEM supply chains.
Growth Catalysts
- EMA material qualification pathways:Accelerated cell chemistry approval processes for nickel manganese cobalt variants are reducing time-to-market for high-energy-density automotive applications.
- Commercial vehicle electrification:Urban freight operators in Germany and the Netherlands are deploying lithium iron phosphate packs for last-mile delivery vans with demanding cycle-life requirements.
- Polish manufacturing cluster expansion:Concentrated cell production capacity in Lower Silesia is shortening logistics lead times for Central European OEM assembly plants.
Market Restraints
- Cathode active material cost volatility:Nickel and cobalt price swings from DRC and Indonesian supply corridors are destabilizing cell cost forecasts for European battery buyers.
- Graphite anode supply concentration:Synthetic and natural graphite processing capacity clusters in China create import dependency risks for European cell manufacturers.
- Energy density ceiling in lithium iron phosphate:The chemistry's theoretical limits constrain range extension for premium passenger electric vehicles beyond 400 km on single charges.
Strategic Opportunities
- Eastern European underpenetration:Romania, Bulgaria, and Poland exhibit electric vehicle adoption gaps that localized battery assembly plants could address through regional OEM partnerships.
- Silicon-composite anode convergence:Integration of silicon nanowire anodes with solid-electrolyte interphase engineering promises 20% energy density gains over conventional graphite systems.
- EU Green Deal industrial funding:Strategic battery project financing through the European Investment Bank is de-risking gigafactory construction in Sweden and Germany.
Industry Challenges
- Electrochemical engineering talent scarcity:European universities produce insufficient cell design and thermal management specialists to staff expanding R&D centers.
- Formation cycling capex intensity:Cell conditioning equipment for high-throughput manufacturing requires substantial upfront investment with extended depreciation schedules.
- REACH compliance documentation:Substance of very high concern declarations for electrolyte additives are extending material qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lithium-Ion Battery for Electric Vehicle Market |
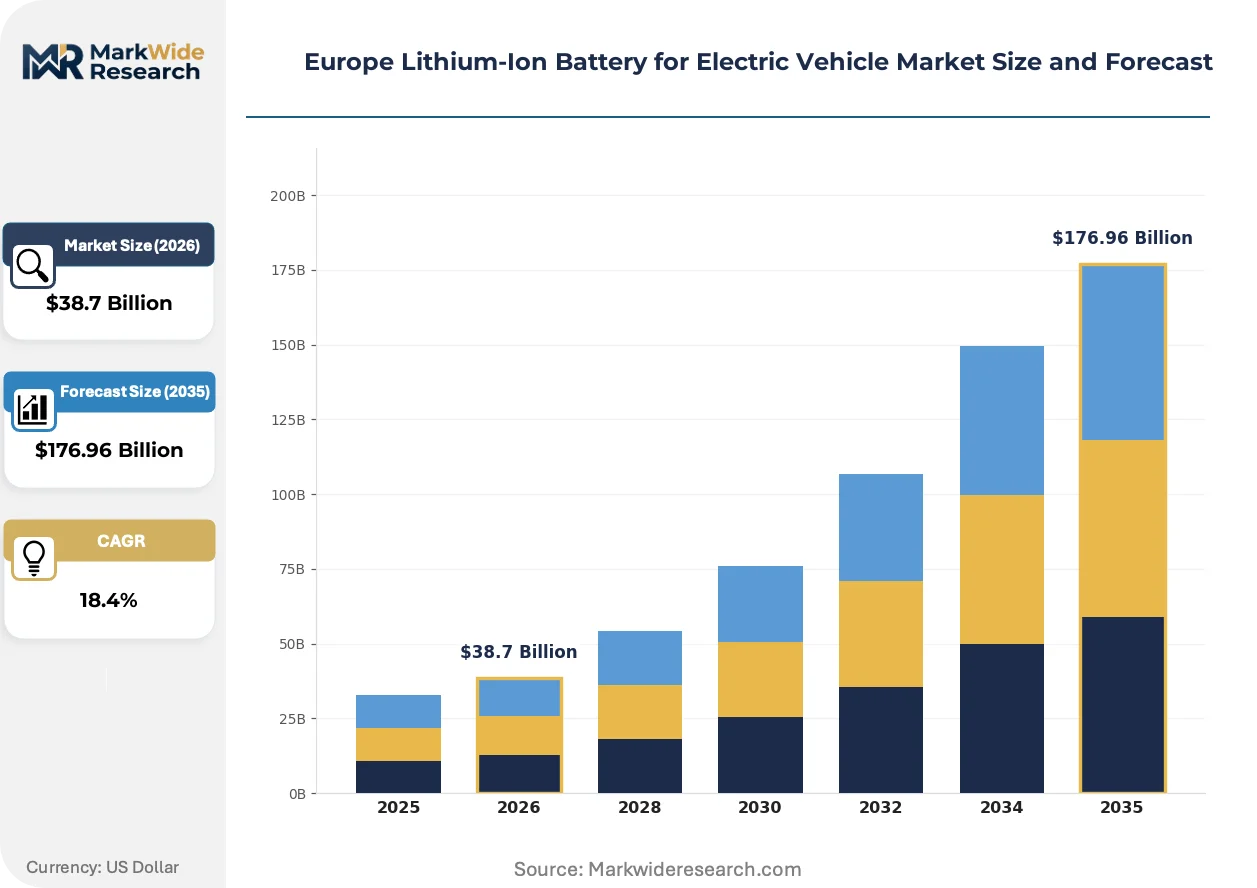
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Others Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Technology: LFP, NMC, NCA, LTO End User: OEMs, Fleet Operators, Dealerships, Aftermarket Providers |
| Companies Covered | Contemporary Amperex Technology Co. Limited (CATL), LG Energy Solution, Samsung SDI, Northvolt, Panasonic Holdings Corporation, BYD Company Limited, SK Innovation, Saft Groupe S.A., Faradion Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lithium-Ion Battery for Electric Vehicle Market Trends and Innovations
Dry electrode coating techniques and AI-driven formation optimization are compressing manufacturing energy intensity while digital battery passports are embedding traceability into cell lifecycle management.
Dry electrode manufacturing is automating solvent-free cathode and anode deposition processes that previously required energy-intensive drying ovens and toxic solvent recovery systems. European cell producers including Northvolt are piloting this technology at Skellefteå to reduce facility carbon intensity and align with EU Battery Regulation footprint thresholds. The process is automating capital allocation away from conventional wet-coating equipment while tightening environmental compliance margins for new facility approvals.
REACH chemical restriction expansions are forcing electrolyte formulators to substitute fluorinated additives with non-halogenated alternatives for CE marking eligibility. The ECHA candidate list updates are redirecting R&D expenditure toward novel lithium salts and functional electrolyte blends. High-voltage nickel-rich cathode cells for premium electric vehicles face the steepest adaptation costs due to additive-dependent cycling stability requirements.
Fleet operators are consolidating battery procurement through direct long-term supply agreements with cell manufacturers, bypassing traditional tiered distributor networks. Energy-as-a-service models for commercial vehicle batteries are replacing upfront capital purchases with per-kilometer usage contracts. This restructuring is most advanced in German logistics corridors where Deutsche Post and similar operators demand guaranteed residual value and second-life clarity in contract terms.
Europe Lithium-Ion Battery for Electric Vehicle Market Segmentation
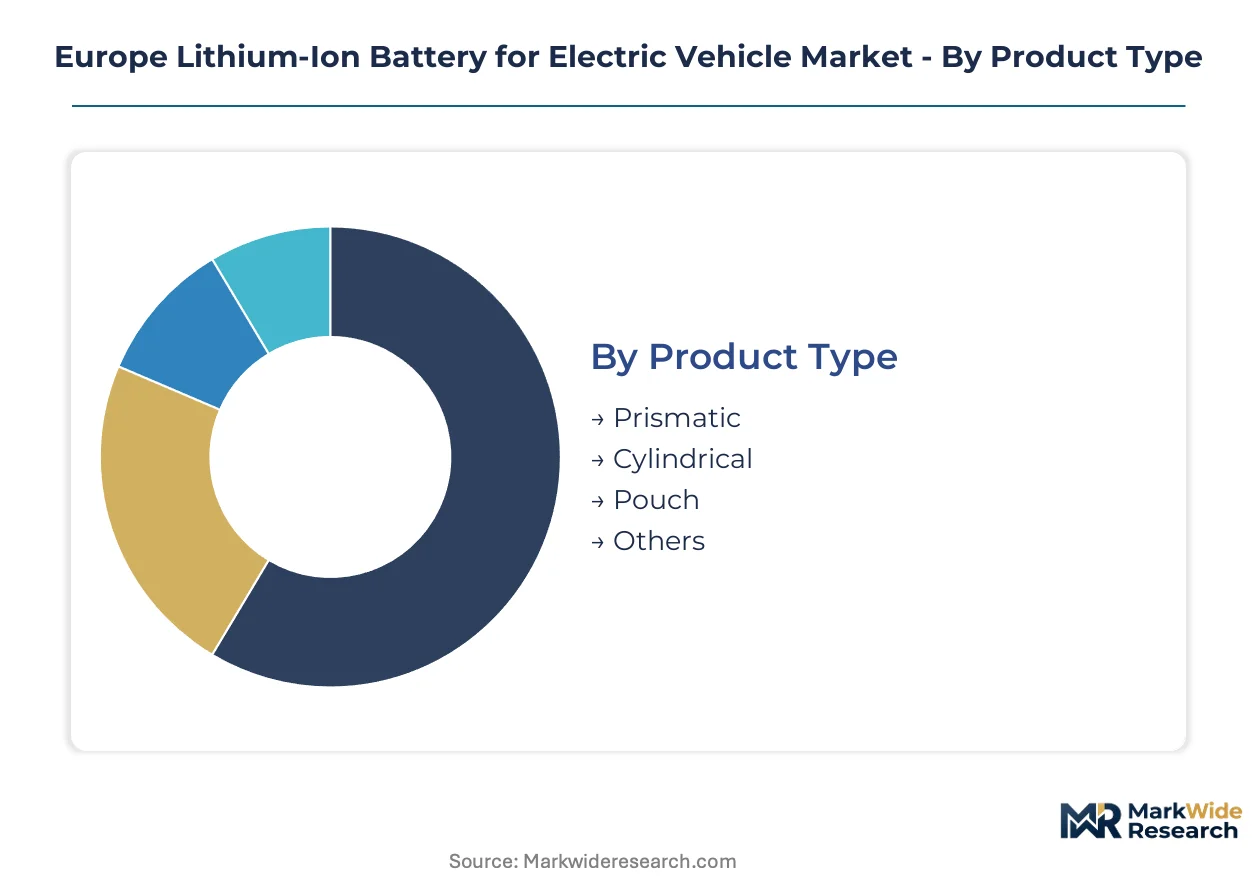
Cell format selection, chemistry trade-offs, and procurement channel preferences create distinct competitive arenas within European electric vehicle supply chains. Each segmentation dimension carries specific margin profiles and regulatory compliance burdens that reshape supplier qualification criteria.
Product Type:
Platform redesign cycles favor formats that optimize pack-level space utilization and thermal management integration.
- Prismatic:Rectangular aluminum-cased cells stack efficiently within module housings, enabling direct cooling plate attachment. Volkswagen's MEB platform and BMW's Neue Klasse architecture specify prismatic formats for their German assembly plants, driven by pack energy density targets and crash safety requirements.
- Cylindrical:Rolled electrode jellyrolls in steel cans deliver superior cycle life and manufacturing consistency. Tesla's 4680 format and Samsung SDI's supply agreements for premium performance vehicles concentrate demand in high-energy-density applications where thermal runaway containment is critical.
- Pouch:Flexible polymer-laminated cells maximize volumetric efficiency for hybrid vehicle applications with constrained packaging space.
- Others:Emerging formats including blade cells and custom geometries address niche commercial vehicle configurations.
Volume placements concentrate in prismatic formats; the faster expansion belongs to large-format cylindrical cells as OEMs pursue structural battery integration.
Application:
Duty cycle intensity and range requirements segment procurement specifications across vehicle categories.
- Passenger Vehicles:Premium sedans and SUVs specify nickel-rich chemistries for 500+ kilometer range targets, while entry-level urban vehicles adopt lithium iron phosphate for cost stability. Mercedes-Benz EQS and BMW iX platforms anchor high-nickel cell demand in German manufacturing corridors.
- Commercial Vehicles:Urban delivery vans and light trucks prioritize cycle life over energy density, with Deutsche Post and Dutch freight operators specifying LFP packs for 3,000+ cycle durability under constant fast-charging regimens.
- Two-Wheelers:Compact moped and scooter batteries emphasize weight reduction and swappable pack designs for shared mobility fleets.
- Buses:Municipal transit authorities demand megawatt-hour scale systems with 10-year operational lifespans, driving qualification of high-capacity prismatic configurations.
Passenger vehicle procurement dominates absolute cell volumes; commercial vehicle electrification is gaining share fastest as urban freight regulations tighten.
Technology:
Cathode chemistry selection determines energy density ceilings, thermal stability margins, and raw material exposure profiles.
- NMC:Nickel manganese cobalt variants from 622 to 811 ratios deliver 250-300 Wh/kg cell-level energy density for premium European OEM platforms. Northvolt's Swedish production and LG Energy Solution's Polish facilities concentrate NMC supply for German automotive assembly.
- LFP:Lithium iron phosphate chemistry eliminates cobalt sourcing risk while offering 3,000-6,000 cycle lifespans. Entry-level passenger vehicles and commercial van applications across Germany and the Netherlands specify LFP as nickel price volatility destabilizes cost forecasts.
- NCA:Nickel cobalt aluminum cathodes serve performance-oriented electric vehicles with demanding discharge rate requirements.
- LTO:Lithium titanate anode systems enable extreme fast-charging for bus and shuttle applications where 10-minute recharge cycles are operational necessities.
NMC formulations command the largest installed base; LFP is climbing fastest as OEMs diversify chemistry portfolios for cost resilience.
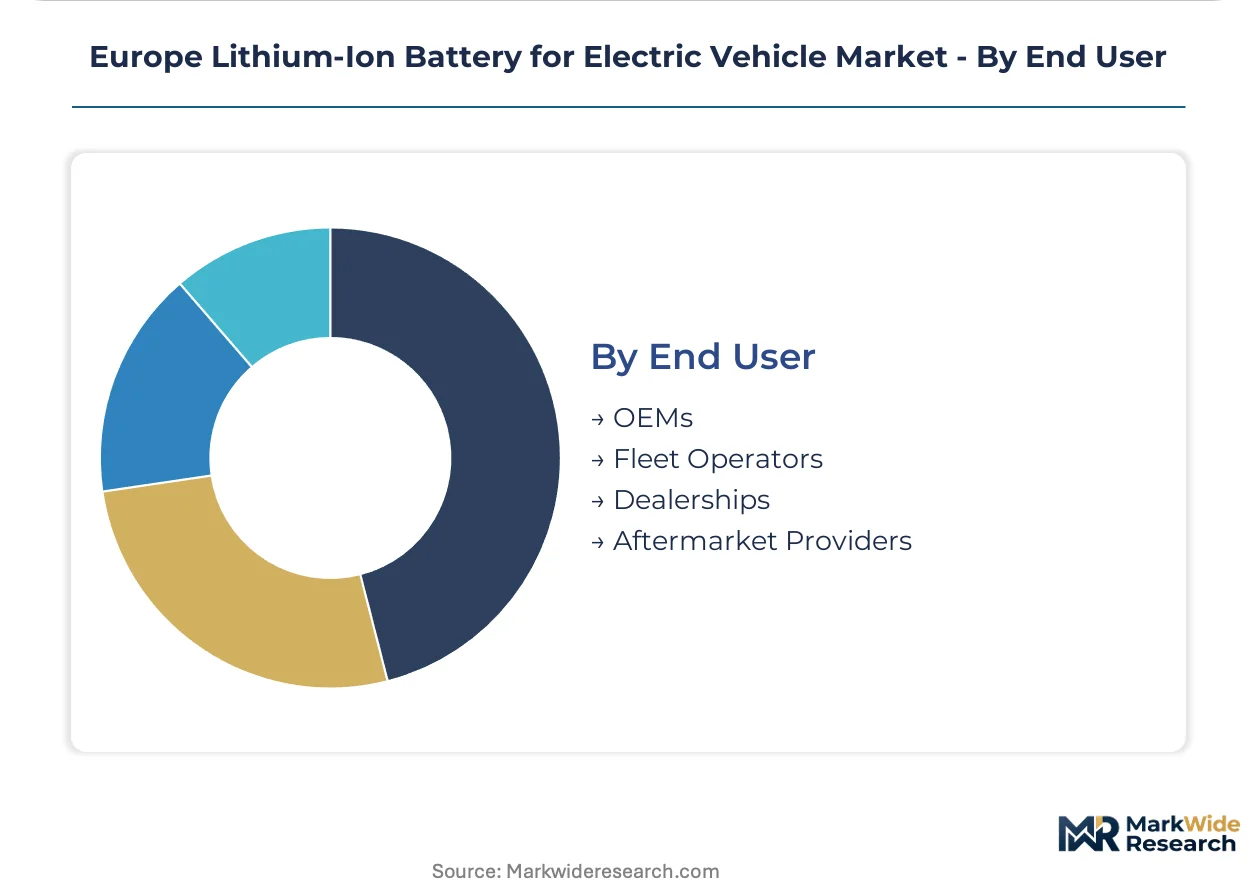
End User:
Procurement authority and contract structure preferences segment the customer landscape.
- OEMs:Volkswagen, BMW, and Mercedes-Benz operate dedicated battery assembly plants and cell manufacturing joint ventures, negotiating long-term offtake agreements with direct supplier relationships. Their purchasing power shapes cell format standardization across European platforms.
- Fleet Operators:Deutsche Post DHL and similar logistics consolidators are bypassing tiered distribution networks for direct cell manufacturer contracts, embedding residual value guarantees and second-life clarity into per-kilometer usage agreements.
- Dealerships:Authorized retail networks manage replacement battery procurement for out-of-warranty vehicles and certified pre-owned programs.
- Aftermarket Providers:Independent service specialists source compatible cell modules for vehicle refurbishment and battery repair services outside OEM warranty structures.
Direct OEM procurement accounts for dominant volume flows; fleet operator direct contracting is expanding most quickly as energy-as-a-service models displace capital purchase structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM procurement concentrates cell demand across Central European manufacturing corridors, while regulatory pressure from Brussels accelerates domestic production investments in Sweden and Poland.
Germany
Volkswagen, BMW, and Mercedes-Benz operate dedicated battery assembly plants in Lower Saxony and Bavaria, sourcing high-nickel cells for premium electric platforms. The KBA enforces UN ECE R100 battery safety certification for all automotive traction systems. Cell manufacturing joint ventures in Erfurt and Salzgitter are scaling prismatic format production for MEB and Neue Klasse architectures.
Sweden
Northvolt's Skellefteå gigafactory anchors European domestic cell production with dry electrode pilot lines reducing carbon intensity. The Swedish Environmental Protection Agency permits are conditioning expansion on renewable energy sourcing. The Västerbotten cluster is attracting electrolyte suppliers and formation equipment vendors to co-locate with Northvolt's operations.
Poland
LG Energy Solution's Wrocław facility supplies multiple German OEM platforms from Lower Silesia, shortening logistics lead times. Polish Investment and Trade Agency incentives are drawing cathode active material processors to the region. The Dolnośląskie province is consolidating as Central Europe's primary cell export hub with rail links to German assembly plants.
Netherlands
Urban freight electrification in Rotterdam and Amsterdam corridors is driving lithium iron phosphate procurement for last-mile delivery vans with demanding cycle-life requirements. The Dutch Human Environment and Transport Inspectorate enforces EU Battery Regulation compliance for commercial vehicle operators. Eindhoven's Brainport region hosts thermal management R&D centers serving Belgian and German OEM supply chains.
France
Saft Groupe's Nersac facility produces high-energy-density cells for premium European automotive applications. The French National Agency for Food, Environmental and Occupational Health Safety evaluates electrolyte additive safety for REACH compliance. The Nouvelle-Aquitaine region is positioning for second-life battery repurposing infrastructure to serve Iberian and Italian markets.
Europe Lithium-Ion Battery for Electric Vehicle Market Competitive Landscape
Capacity expansion dominates the current landscape as Asian incumbents and European challengers race to secure OEM offtake agreements. The structure tiers between established cell producers with Polish and German manufacturing footprints and emerging domestic suppliers scaling Swedish operations. Two archetypes define positioning: chemistry-agnostic volume producers and high-nickel specialists targeting premium platforms. M&A activity and strategic joint ventures are the primary competitive vectors, with OEMs seeking captive supply through equity stakes.
Among Asian-origin manufacturers, Contemporary Amperex Technology Co. Limited exemplifies the scale-driven archetype with German manufacturing commitments, while LG Energy Solution occupies a position anchoring Central European supply through Polish operations. Samsung SDI represents the premium-tier specialist archetype with cylindrical cell expertise for performance applications. Northvolt AB exemplifies the European domestic challenger model with vertically integrated recycling and renewable-powered production.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited (CATL) |
| LG Energy Solution |
| Samsung SDI |
| Northvolt |
| Panasonic Holdings Corporation |
| BYD Company Limited |
| SK Innovation |
| Saft Groupe S.A. |
| Faradion Limited |
| Others |
Pricing and Supply Chain Analysis
EMA material qualification pathways for nickel manganese cobalt variants are compressing procurement timelines for German OEMs, forcing cell suppliers to absorb certification costs upfront while negotiating long-term offtake structures that lock in volume commitments against volatile cathode active material inputs.
Pricing Analysis
Volume placements concentrate in contract-based long-term offtake agreements for prismatic and cylindrical formats, while spot procurement serves aftermarket replacement demand. Price differentiation rests on CE marking tier and volume scale, with certified high-nickel cells commanding premiums over uncertified alternatives. Cost compression in entry-level LFP segments is intensifying because Indonesian nickel supply volatility destabilizes NMC cost forecasts. Fleet operators exhibit highest price sensitivity through per-kilometer energy-as-a-service contracts, whereas premium OEM platform engineers prioritize energy density over unit cost.
Supply Chain Analysis
Graphite anode supply rests on Chinese synthetic and natural processing capacity clusters, while cathode active material production concentrates in South Korea and Japan. The European cell manufacturing base draws from DRC cobalt corridors, Indonesian nickel laterite operations, and Chinese lithium carbonate refiners. Single-source vulnerability in spherical graphite purification creates import dependency exposure for Northvolt and CATL's European operations. Distribution runs through direct OEM offtake agreements and fleet operator procurement consortia, bypassing traditional tiered battery distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry electrode manufacturing is displacing conventional wet-coating processes across European gigafactory investments, compressing energy intensity and aligning production with EU Battery Regulation carbon footprint thresholds.
For Market Incumbents: Anchor long-term supply security through backward integration into cathode active material processing in Poland and Sweden, countering Asian supplier concentration. Accelerate dry electrode pilot scale-up at Skellefteå and Erfurt to defend margin position against energy cost differentials. Prioritize REACH-compliant electrolyte formulation R&D as ECHA restriction expansions threaten existing additive portfolios. For New Entrants and Emerging Players: Capture underpenetrated commercial vehicle electrification demand in Romanian and Bulgarian logistics corridors through localized LFP pack assembly partnerships. Target urban freight operators with guaranteed residual value contracts and second-life battery clarity. Pursue energy-as-a-service go-to-market structures that displace upfront capital purchases with per-kilometer usage models. For Investors and Strategic Acquirers: The window for entry favors European domestic challengers with vertically integrated recycling capabilities and renewable energy sourcing. Long-term viability hinges on securing OEM platform qualification before incumbent Asian producers consolidate joint venture structures. Watch EIB funding allocation velocity as the inflection indicator for gigafactory construction de-risking.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Manufacturing Scale-Up | Northvolt's Skellefteå pilot reduces facility carbon intensity below EU Battery Regulation thresholds. |
| Cathode Active Material Backward Integration | Polish and Swedish processing investments shorten logistics lead times for German OEM assembly plants. |
| Energy-as-a-Service Contract Structuring | Deutsche Post's per-kilometer agreements embed residual value guarantees displacing capital purchases. |
| REACH-Compliant Electrolyte Reformulation | ECHA candidate list updates redirect R&D expenditure toward non-halogenated lithium salt alternatives. |
| Second-Life Battery Infrastructure Development | Nouvelle-Aquitaine repurposing facilities position to serve Iberian and Italian aftermarket demand. |
Research Methodology
Document review covered EU Battery Regulation implementation guidelines, ECHA substance restriction updates, and EIB strategic project financing disclosures, complemented by interviews with cell manufacturing executives, OEM platform engineers, and commercial fleet procurement directors. Secondary validation drew from KBA vehicle certification databases, Polish Investment and Trade Agency incentive records, and Northvolt environmental permit filings. Bottom-up cell production capacity modeling triangulated against top-down OEM offtake announcement aggregation.
Segmentation outputs across cell format, cathode chemistry, and end-user procurement channel were projected over the analysis window using vehicle platform electrification roadmaps and commercial vehicle duty cycle intensity assumptions. CAGRs were derived from production capacity commissioning schedules and regulatory compliance timeline constraints. Key inputs included EMA material qualification pathway durations and REACH documentation extension estimates for electrolyte additive substitutions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel price volatility from Indonesian supply corridors and ECHA restriction expansion timing for fluorinated compounds. Forecasts reflect documented assumptions around OEM joint venture completion and EIB funding disbursement velocity. A small set of triggers—cathode active material cost spikes, ECHA candidate list acceleration, and Polish manufacturing cluster labor availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
China SLI Battery Market