
 Nanobolt Lithium Tungsten Batteries Market | 2026-2036
Nanobolt Lithium Tungsten Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Nanobolt Lithium Tungsten Batteries Market Foresight
Software-defined battery management is expanding what fleet operators purchase beyond physical cells. Nyobolt leverages its proprietary anode architecture to dominate ultra-fast charging niches. LG Energy Solution sustains manufacturing scale across multiple continents. CALT anchors supply relationships with domestic automotive champions.
Nanobolt lithium tungsten batteries employ tungsten oxide nanostructured anodes paired with lithium-ion cathodes to achieve charge rates exceeding conventional graphite systems by an order of magnitude, primarily serving applications where downtime carries prohibitive costs. The rechargeable product category occupies the dominant revenue position due to cycle-life requirements in commercial transport. Solid-state technology variants attract the fastest development investment as manufacturers pursue energy density thresholds needed for aviation applications. Thin-film configurations serve emerging medical and sensor markets where form factor constraints override absolute capacity.
The EU Battery Regulation mandates carbon footprint declarations and recycled content minimums that reshape material sourcing decisions for any supplier accessing European automotive OEMs. China's SAMR enforces GB standards on thermal runaway propagation that effectively filter out lower-tier producers. The FAA in the United States maintains evolving certification pathways for lithium-based cells in aircraft auxiliary power units. Stakeholders must monitor how divergent national testing protocols fragment compliance costs without harmonized international standards.
Market Dynamics
Ultra-fast charging requirements from electric vehicle fleets are compressing development cycles for anode architectures, forcing material suppliers to prove cycle stability under 10-minute charge protocols before securing automotive qualification slots.
Growth Catalysts
- EU Battery Regulation:Carbon footprint declarations and recycled content mandates are filtering qualified suppliers into European OEM supply chains, rewarding early compliance investments with preferred vendor status.
- Aviation auxiliary power:FAA certification pathways for lithium-based aircraft cells are opening a high-margin segment where energy density premiums override cost sensitivity.
- Tungsten oxide nanostructuring:Proprietary anode fabrication techniques are unlocking charge-rate performance that graphite anodes cannot match, creating technical moats for first movers.
Market Restraints
- Tungsten concentrate supply:Over 80% of processed tungsten originates from Chinese smelters, exposing non-Chinese cell manufacturers to concentrate availability volatility and export quota risks.
- Solid-state development costs:Aviation-grade energy density targets require ceramic electrolyte integration that multiplies R&D burn rates and extends qualification timelines beyond five years.
- Graphite cost baselines:Mature synthetic graphite anodes trade at one-third the active material cost of tungsten oxide equivalents, constraining price-competitive entry into cost-sensitive consumer electronics.
Strategic Opportunities
- German automotive corridor:Stuttgart and Wolfsburg procurement offices are consolidating supplier panels around ultra-fast charging capability, creating concentrated demand pools for qualified cell vendors.
- Thin-film medical devices:Implantable sensors and disposable diagnostic equipment require sub-millimeter form factors where tungsten oxide thin-film anodes outperform conventional rolled electrodes.
- China GB standards compliance:SAMR thermal runaway propagation tests are eliminating lower-tier competitors, opening market share for producers investing in multi-layer separator and electrolyte additive portfolios.
Industry Challenges
- Electrochemist talent scarcity:Battery-grade nanostructure fabrication requires PhD-level expertise in interfacial chemistry that exceeds current university pipeline output.
- Automotive qualification timelines:OEM cell validation protocols demand 24-month abuse testing and winter validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanobolt Lithium Tungsten Batteries Market |
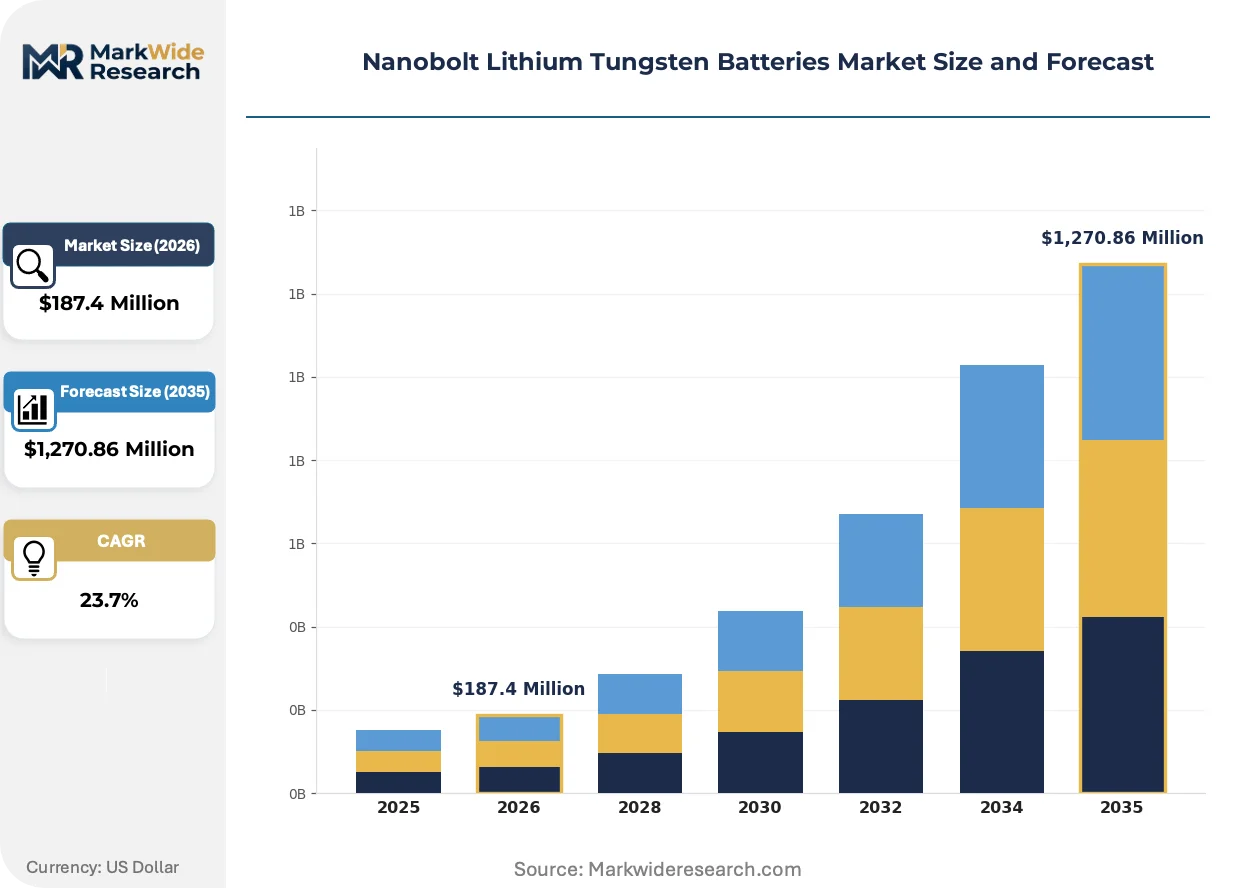
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Non-Rechargeable, Hybrid, Energy Storage Technology: Solid-State, Lithium-Ion, Supercapacitors, Thin-Film End User: Consumer Electronics, Automotive, Aerospace, Industrial Equipment Application: Energy Management, Backup Power, Power Tools, Electric Vehicles |
| Companies Covered | N1 Technologies, CALT, LG Energy Solution, Nyobolt, Niobium, BYD, Sunwoda, Aceleron, Amprius Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanobolt Lithium Tungsten Batteries Market Shifts & Advancements
Software-defined battery management systems are decoupling cell hardware from optimization algorithms, enabling fleet operators to upgrade charging protocols without physical replacement cycles.
Tungsten oxide nanostructured anodes are consolidating technical roadmaps across premium automotive and aviation segments. Mercedes-Benz and Porsche engineering teams have locked 2027 platform slots for 10-minute-to-80% charge capability. This consolidation is compressing qualification timelines for graphite-anode alternatives that cannot meet the thermal management requirements of such protocols.
REACH substance restrictions and RoHS amendments are tightening purity thresholds for heavy metal content in battery active materials. European cell importers must now document tungsten provenance through smelter audits. Aviation battery pack assemblers targeting EASA certification are absorbing the compliance costs into premium pricing structures.
Fleet procurement offices are unbundling cell supply from battery management software licenses, treating charge optimization as a separable subscription service. Logistics operators running depot-charged last-mile delivery vehicles are piloting this model most aggressively in the Netherlands and Belgium, where electricity demand charges create acute optimization incentives.
Nanobolt Lithium Tungsten Batteries Market Segmentation
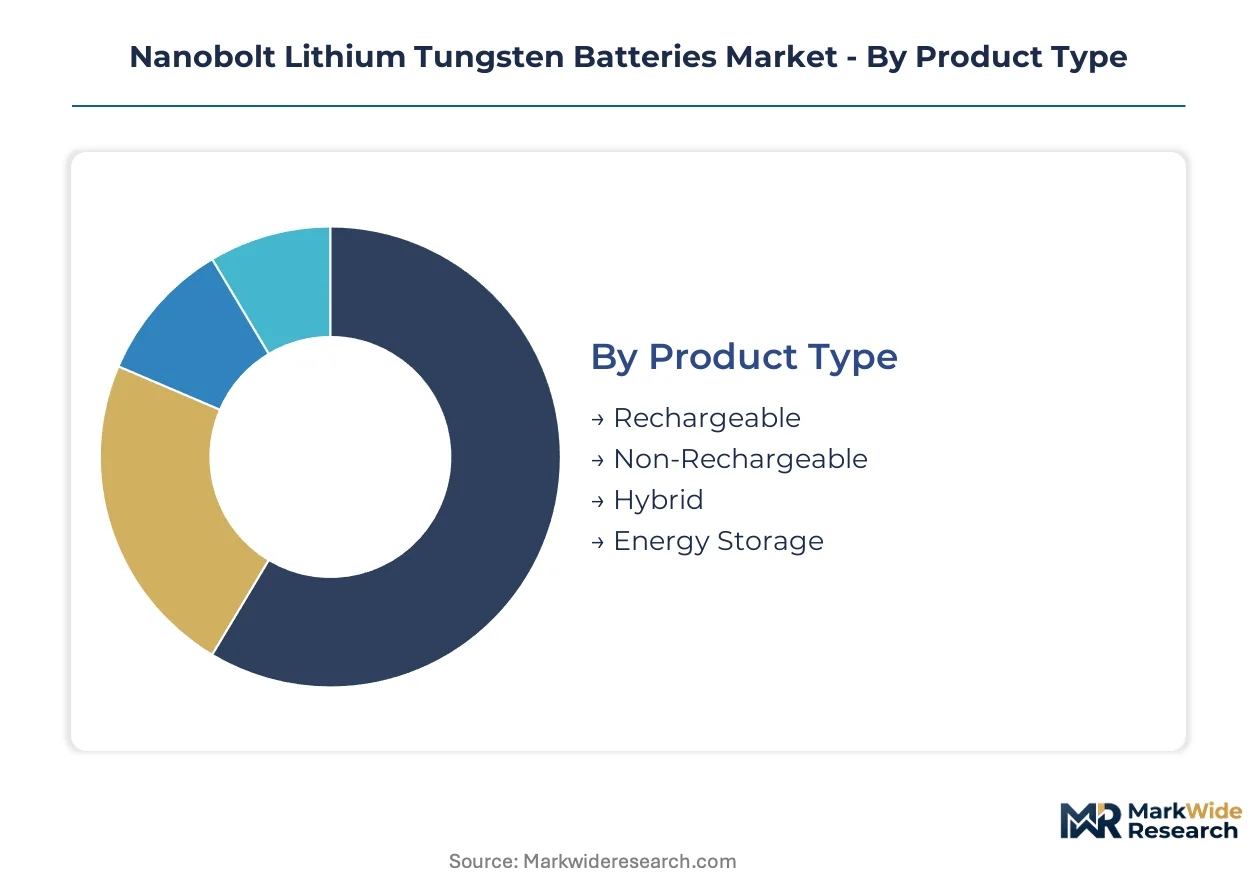
Tungsten oxide anode architectures create divergent performance profiles across product configurations, forcing buyers to trade cycle stability against charge-rate tolerance. Segmentation reveals where proprietary nanostructuring commands premium positioning versus where conventional lithium-ion chemistries retain cost advantage.
Product Type:
Standardization dominates at the commodity end where cylindrical formats prevail, while pouch and prismatic variants demand extensive customization for thermal management integration.
- Rechargeable:Lithium-ion cathodes paired with tungsten oxide nanostructured anodes deliver 10-minute-to-80% charge capability. Demand concentrates in German automotive OEM procurement offices around Stuttgart and Wolfsburg, where platform slots for 2027 ultra-fast charging models are compressing supplier qualification timelines.
- Non-Rechargeable:Primary cell configurations employ tungsten oxide cathodes with lithium metal anodes for extreme temperature tolerance. Medical implant manufacturers in Switzerland and diagnostic equipment suppliers in Belgium source thin-film variants where form factor constraints override absolute capacity requirements.
- Hybrid:Dual-chemistry architectures combine tungsten oxide anodes with supercapacitor buffers for pulse-power applications. Grid stabilization projects in Texas and California pilot these configurations for frequency regulation services.
- Energy Storage:Utility-scale systems prioritize cycle-life economics over charge-rate performance, favoring larger-format prismatic cells. Wind farm operators in Denmark and solar-plus-storage developers in Australia specify 20-year degradation warranties.
Leading the category by volume: Rechargeable. Growing fastest: Hybrid.
Technology:
Development cost tiers separate aviation-grade ceramic electrolyte integration from liquid-electrolyte systems serving commercial transport.
- Solid-State:Ceramic electrolyte matrices paired with tungsten oxide anodes target aviation auxiliary power unit specifications. FAA certification pathways in the United States and EASA protocols in Europe demand five-year qualification timelines that filter out undercapitalized developers.
- Lithium-Ion:Conventional liquid electrolyte systems with nanostructured tungsten oxide anodes dominate automotive traction battery procurement. Mercedes-Benz and Porsche engineering teams have locked platform slots requiring thermal management architectures that graphite anodes cannot satisfy.
- Supercapacitors:Tungsten oxide pseudocapacitive electrodes bridge power and energy density gaps for regenerative braking systems. Japanese rail operators and Korean bus manufacturers specify these for depot-charged fleets.
- Thin-Film:Sub-millimeter electrode stacks serve implantable sensors and disposable diagnostic equipment. Swiss medical device manufacturers and Dutch health technology firms prioritize form factor flexibility over volumetric energy density.
Commanding highest R&D investment: Solid-State. Widest deployment: Lithium-Ion.
End User:
Volume concentration in automotive procurement contrasts with margin premiums available in aerospace qualification pathways.
- Consumer Electronics:Smartphone and laptop manufacturers confront synthetic graphite cost baselines at one-third tungsten oxide equivalent pricing. Premium tier vendors in South Korea and California differentiate on 15-minute charge claims for flagship models.
- Automotive:Electric vehicle OEMs in Germany consolidate supplier panels around 10-minute charge protocols. Porsche and Mercedes-Benz procurement offices demand 24-month abuse testing and winter validation cycles before platform integration.
- Aerospace:Aircraft auxiliary power unit specifications prioritize energy density over cost sensitivity. Boeing and Airbus tier-one suppliers absorb REACH substance documentation and RoHS amendment compliance into premium pricing structures.
- Industrial Equipment:Forklift and mining vehicle fleets value cycle stability under partial state-of-charge operation. Warehouse operators in the Netherlands and Belgium unbundle cell supply from battery management software licenses, treating optimization as subscription services.
Generating largest order backlogs: Automotive. Extracting steepest price premiums: Aerospace.
Application:
Depot-charged fleet economics diverge from grid-connected stationary systems in procurement evaluation criteria.
- Energy Management:Behind-the-meter storage systems integrate tungsten oxide batteries with solar inverters for peak shaving. Commercial building operators in California and Texas face demand charge structures that reward rapid charge-discharge cycling.
- Backup Power:Uninterruptible power supply configurations prioritize instantaneous response over energy density. Data center operators in Virginia and Frankfurt specify these for ride-through capability during grid transitions.
- Power Tools:Cordless construction equipment demands high discharge rates under thermal constraints. Professional trades procurement in Germany and Japan favors swappable battery packs over integrated cells.
- Electric Vehicles:Traction battery applications drive tungsten oxide anode volume requirements. Fleet operators running last-mile delivery vehicles in Belgium and the Netherlands pilot software-defined charge optimization to minimize electricity demand charges.
Absorbing greatest production capacity: Electric Vehicles. Expanding most quickly: Energy Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates tungsten oxide anode production through smelter networks, while Germany and the United States absorb the bulk of automotive qualification demand. Regulatory divergence across these markets fragments compliance architectures without harmonized international standards.
China
Domestic automotive champions anchor procurement volumes for ultra-fast charging cells. SAMR enforces GB standards on thermal runaway propagation that filter out lower-tier producers. The Yangtze River Delta hosts concentrated tungsten processing capacity that supplies global anode manufacturers.
Germany
Mercedes-Benz and Porsche engineering teams have locked 2027 platform slots requiring 10-minute-to-80% charge capability. The EU Battery Regulation mandates carbon footprint declarations and recycled content minimums that reshape material sourcing decisions. Stuttgart and Wolfsburg procurement offices consolidate supplier panels around thermal management architectures.
United States
FAA certification pathways for lithium-based aircraft auxiliary power units attract development investment from aviation-focused cell manufacturers. The Inflation Reduction Act provisions incentivize domestic battery assembly capacity. Data center operators in Virginia specify uninterruptible power supply configurations for ride-through capability.
Japan
Rail operators and bus manufacturers specify tungsten oxide pseudocapacitive electrodes for regenerative braking systems in depot-charged fleets. METI directs industrial policy toward next-generation battery technology development. The Kansai region around Osaka maintains precision manufacturing expertise for thin-film electrode fabrication.
Belgium
Logistics operators running last-mile delivery vehicles pilot software-defined charge optimization to minimize electricity demand charges. REACH substance restrictions tighten purity thresholds for heavy metal content in active materials. Antwerp and Brussels serve as distribution nodes for European medical device manufacturers sourcing thin-film variants.
Nanobolt Lithium Tungsten Batteries Market Competitive Landscape
Top-tier vendors anchor automotive qualification slots, while mid-scale specialists occupy thin-film medical and aviation auxiliary power niches. The vendor base stratifies across three archetypes: integrated battery manufacturers with captive cathode supply, pure-play anode technology licensors, and systems integrators unbundling hardware from software-defined management platforms. Dominant competitive moves include strategic partnerships for tungsten concentrate offtake and technology licensing agreements that accelerate qualification timelines.
Within the integrated manufacturing tier, LG Energy Solution and BYD occupy positions exemplifying multi-continent production scale. CALT anchors supply relationships with domestic automotive champions in China. Nyobolt represents the pure-play anode technology archetype, leveraging proprietary nanostructuring approaches to dominate ultra-fast charging niches where graphite alternatives fail thermal management requirements.
| Leading Market Players |
|---|
| N1 Technologies |
| CALT |
| LG Energy Solution |
| Nyobolt |
| Niobium |
| BYD |
| Sunwoda |
| Aceleron |
| Amprius Technologies |
| Others |
Supply & Pricing Matrix
Tungsten oxide nanostructuring migration from laboratory-scale electrodeposition to roll-to-roll manufacturing is compressing unit economics while concentrating production know-how in the Yangtze River Delta and Germany's automotive corridor. This dual shift rewards first movers with pricing power over automotive qualification slots while exposing late entrants to concentrate cost volatility.
Pricing Analysis
Cost-down pressure on standard lithium-ion configurations accelerates because synthetic graphite anodes trade at one-third the active material cost of tungsten oxide equivalents. Three-tier pricing structure across aviation-certified, automotive-qualified, and industrial-grade tiers separates FAA-validated cells commanding premium multiples from unqualified commodity offerings. Price differentiation traces to certification tier and volume scale, with OEM procurement offices demanding 24-month abuse testing as a non-negotiable entry ticket. Fleet operators in Belgium and the Netherlands exhibit highest price sensitivity through software-defined charge optimization pilots, while Boeing and Airbus tier-one suppliers absorb compliance premiums with minimal negotiation.
Supply Chain Analysis
PhD-level electrochemist scarcity in electrodeposition engineering constrains expansion of tungsten oxide anode fabrication outside established clusters. Geographic supply concentration centers on China for tungsten concentrate processing, Germany for automotive cell qualification, and Japan for thin-film precision manufacturing. Raw material dependencies rest on Chinese smelter networks for tungsten oxide precursor, South Korean cathode active material, and Japanese separator membranes. Single-source vulnerability in Yangtze River Delta concentrate supply exposes non-Chinese assemblers to export quota disruptions. Distribution runs through Tier 1 battery pack integrators serving OEM procurement offices directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemist talent scarcity and 24-month automotive qualification timelines constrain effective capacity expansion, propping pricing power for qualified suppliers. Tungsten concentrate concentration in Chinese smelter networks amplifies supply-side leverage.
For Market Incumbents: Lock in multi-year tungsten concentrate offtake agreements with Yangtze River Delta processors before export quota tightening. Expand in-house electrodeposition capacity in Germany's automotive corridor to compress qualification timelines for 2027 platform slots. Vertical integration into tungsten oxide precursor production hedges concentrate availability volatility from SAMR regulatory shifts. For New Entrants and Emerging Players: Thin-film medical device applications in Switzerland and Belgium offer penetrable white-space where form factor constraints override absolute capacity requirements. Solid-state aviation auxiliary power development attracts premium pricing with five-year qualification barriers filtering undercapitalized competitors. Licensing proprietary nanostructuring IP to established Tier 1 integrators accelerates market entry without captive manufacturing investment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated battery manufacturers seeking anode technology differentiation. Long-term viability hinges on securing automotive qualification slots before 2027 platform locks solidify. Acquisition target archetype: pure-play anode technology licensors with locked OEM engineering relationships and pending FAA certification submissions. Watch SAMR thermal runaway propagation test enforcement as inflection indicator for Chinese market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Tungsten Concentrate Offtake Agreement | Secures precursor supply from Yangtze River Delta smelters against export quota volatility. |
| Automotive Qualification Slot Lock | Mercedes-Benz and Porsche engineering teams demand 24-month validation cycles for 2027 platforms. |
| Solid-State Aviation Certification Pathway | FAA and EASA five-year timelines filter competition in auxiliary power unit segments. |
| Software-Defined Battery Management Licensing | Fleet operators in Netherlands and Belgium unbundle optimization from hardware procurement. |
| Thin-Film Medical Device Partnership | Swiss implant manufacturers prioritize sub-millimeter form factors over volumetric energy density. |
Research Methodology
Independent corroboration across cell manufacturer executives, automotive OEM procurement directors, and aviation certification engineers underwrites the qualitative findings in this study. Primary fieldwork with tungsten oxide anode fabrication specialists, battery management software architects, and REACH compliance consultants supplied forward-looking operational intelligence. Secondary validation drew from SAMR GB standard filings, FAA certification pathway documentation, EU Battery Regulation impact assessments, and customs trade data on tungsten concentrate flows. Bottom-up segment sizing triangulated against top-down automotive production forecasts and aviation auxiliary power unit installation projections.
Comparable-period anchoring to historical qualification timeline data and tungsten price volatility patterns established forecast boundary conditions across the analysis window. Segmentation modeling incorporated product type, technology variant, end-user industry, and application use-case dimensions. CAGRs derived from installed base growth rates, replacement cycle assumptions, and penetration curve analysis for ultra-fast charging protocols. Industry-specific inputs included OEM platform slot commitments, smelter capacity expansion announcements, and electrochemist graduation pipeline data from German and Japanese technical universities.
Several conditions sit outside the modeled scope, including breakthrough solid-state ceramic electrolyte formulations achieving aviation energy density targets ahead of projected timelines, and abrupt SAMR export restrictions on tungsten concentrate. Forecasts reflect assumptions around automotive qualification protocol stability and REACH substance restriction amendment trajectories. A small set of named triggers warrants ongoing watch: FAA certification pathway acceleration, EU Battery Regulation recycled content threshold adjustments, and Yangtze River Delta environmental enforcement actions affecting smelter output.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Thin Film Battery Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market