
 North America Lithium-Ion Battery for Electric Vehicle Market | 2026-2036
North America Lithium-Ion Battery for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lithium-Ion Battery for Electric Vehicle Market Insights
Project finance tied to giga-scale cell plants is fragmenting competitive barriers across the North America Lithium-Ion Battery for Electric Vehicle Market. Tesla leverages its captive cathode production and vertical assembly in Nevada to dominate integrated cost structures. Panasonic Holdings Corporation anchors its position through exclusive supply agreements with Tesla's Gigafactory operations. LG Energy Solution competes via multi-billion-dollar joint ventures with General Motors and Honda across Ohio and Michigan.
North America Lithium-Ion Battery for Electric Vehicle refers to rechargeable electrochemical cells using lithium-ion chemistry with nickel-manganese-cobalt (NMC) or lithium-iron-phosphate (LFP) cathode formulations, typically operating at nominal voltages of 3.2–3.7 V per cell and energy densities of 150–300 Wh/kg, manufactured through electrode coating, calendering, electrolyte filling, and formation cycling processes to store and discharge electrical energy for propulsion in battery electric and plug-in hybrid vehicles. Prismatic formats now lead in structural pack integration with vehicle chassis, while cylindrical cells sustain cost advantages in high-volume production lines. LFP technology is displacing NMC in standard-range vehicles as cobalt supply constraints and thermal stability requirements reshape chemistry selection across OEM portfolios.
The US Inflation Reduction Act (IRA) and EPA vehicle emissions standards are tightening domestic content thresholds and zero-emission sales mandates, forcing cell makers to relocate cathode active material production to North America or sacrifice federal tax credit eligibility. NHTSA battery safety protocols and UL 2580 certification requirements are extending testing cycles and raising capital barriers for new entrants seeking OEM qualification. Stakeholders must monitor how Treasury Department guidance on foreign entity of concern rules reshapes joint venture structures and offtake agreements before committing to greenfield capacity.
Market Dynamics
The Inflation Reduction Act's domestic content thresholds are forcing cathode active material production to relocate to the US Midwest or forfeit federal tax credit eligibility, restructuring where cell assembly and precursor refining must occur.
Growth Catalysts
- IRA Domestic Content Rules:Treasury Department guidance on foreign entity of concern provisions is compelling joint ventures to onshore cathode precursor and active material production to Michigan and Ohio manufacturing corridors.
- Long-Range Electric Pickup Demand:OEM procurement for electric full-size trucks and SUVs with 300+ mile range is pulling high-nickel NMC cell capacity into the region.
- LFP Chemistry Maturation:Iron-phosphate cathode formulations are capturing standard-range vehicle segments as thermal stability and cobalt supply constraints reshape OEM portfolio decisions.
Market Restraints
- Cobalt and Nickel Price Volatility:Concentrated mining in the DRC and Indonesia exposes cathode cost structures to geopolitical supply disruptions and ESG compliance premiums.
- Electrolyte Salt Concentration:Lithium hexafluorophosphate production remains concentrated in Chinese chemical processing hubs, creating single-source vulnerability for North American cell plants.
- Formation Cycling Bottleneck:Extended electrochemical conditioning cycles for high-energy cells constrain effective throughput at giga-scale manufacturing lines.
Strategic Opportunities
- Mexico Nearshoring Corridor:Baja California and Sonora are attracting electrode coating and module assembly investments to access USMCA trade benefits while reducing labor costs.
- Second-Life Stationary Storage:Retired EV battery packs are finding application in grid-scale energy storage, creating circular revenue streams for OEMs and independent aggregators.
- Solid-State Interface Engineering:Silicon nanowire anodes paired with sulfide electrolyte research programs are opening pathways to 400 Wh/kg cell architectures by decade end.
Industry Challenges
- Electrochemical Engineer Scarcity:Cell plant commissioning in Michigan and Tennessee is outpacing regional university pipeline output for formation cycling and dry electrode process specialists.
- UL 2580 Certification Timelines:Extended thermal runaway propagation testing cycles are delaying OEM qualification schedules and compressing first-mover advantage windows for new cell formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lithium-Ion Battery for Electric Vehicle Market |
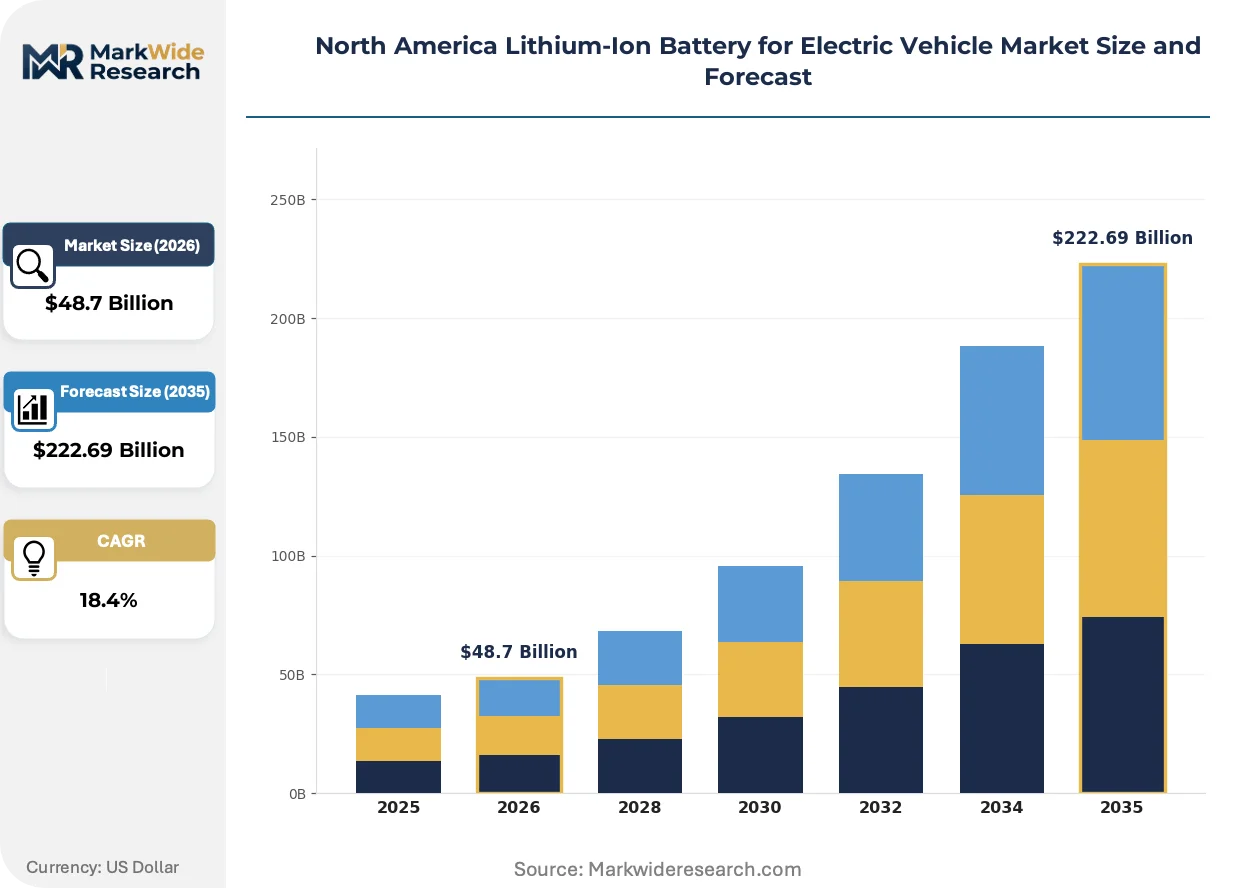
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Scale Capacity: 10-20 kWh, 21-40 kWh, 41-60 kWh, 61-80 kWh End User: OEMs, Fleet Operators, Charging Stations, Aftermarket Providers Technology: NMC, NCA, LFP, Others |
| Companies Covered | Tesla, Panasonic Holdings Corporation, LG Energy Solution, Contemporary Amperex Technology Co., Limited (CATL), BYD Company Ltd., Samsung SDI, SK Innovation, Envision AESC, EnerSys, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lithium-Ion Battery for Electric Vehicle Market Trends and Innovations
Cell-to-pack structural integration and dry electrode coating are compressing manufacturing cost curves while EPA tailpipe regulations accelerate zero-emission powertrain commitments across Detroit and foreign transplant OEMs.
Silicon-dominant anode formulations are hybridizing with graphite substrates to push energy density beyond 300 Wh/kg in premium vehicle segments. Porsche and BMW procurement teams are qualifying these cells for performance electric sedans. The technology is hybridizing cost-performance tradeoffs that previously forced OEMs to choose between range and cycle life.
EPA vehicle emissions standards and NHTSA Corporate Average Fuel Economy rules are tightening zero-emission sales mandates through 2032. These regulations are forcing legacy automakers to accelerate EV platform launches and secure dedicated cell supply through joint ventures. The compliance burden falls heaviest on full-line manufacturers with large ICE exposure in Michigan and the US Southeast.
Fleet procurement departments are consolidating battery supply agreements around total cost of ownership metrics rather than upfront cell pricing. Commercial vehicle operators in California and Texas are demanding guaranteed residual value and recycling take-back provisions in long-term contracts. This behavioral shift is most visible in Class 3-8 electric truck segments where uptime guarantees dominate supplier selection criteria.
North America Lithium-Ion Battery for Electric Vehicle Market Segmentation
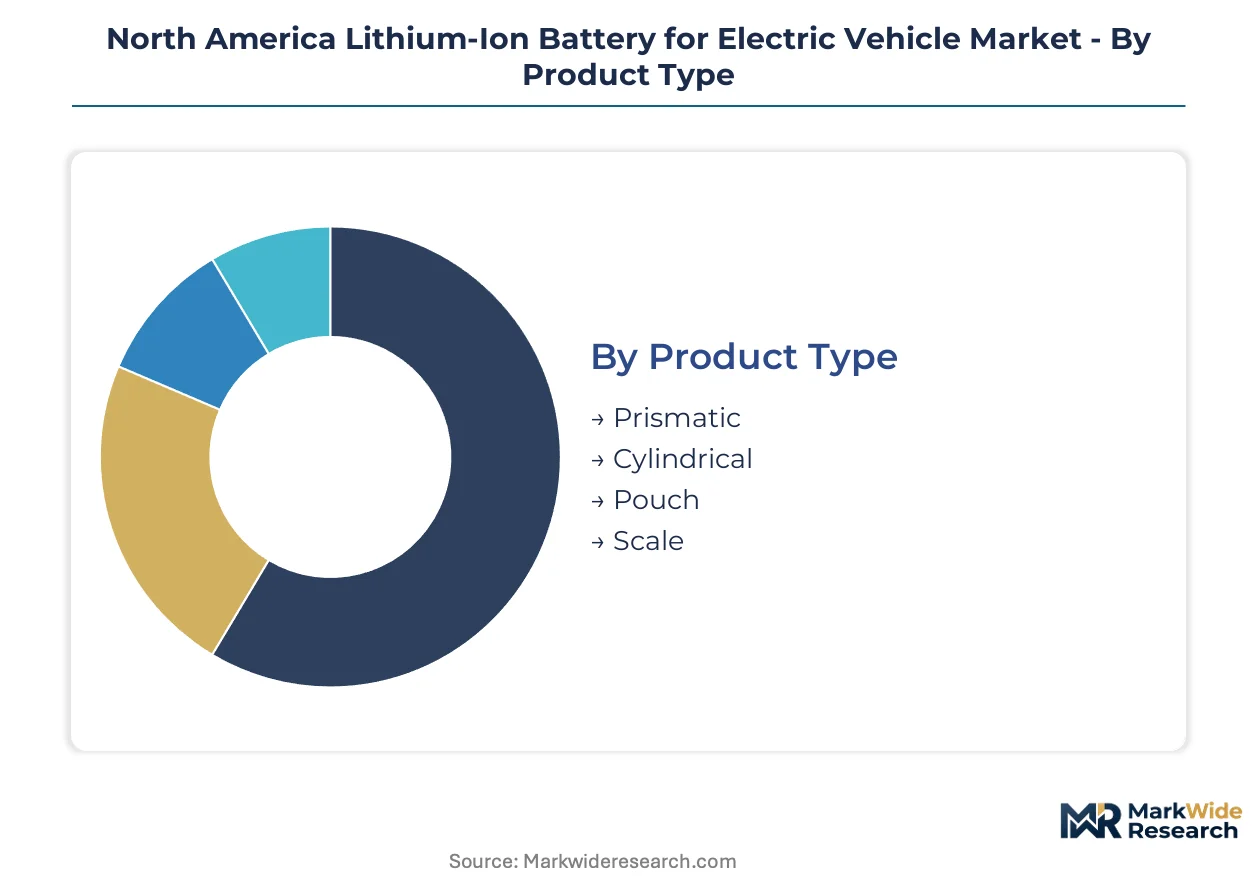
Cell format selection dictates structural pack architecture and thermal management complexity across North American EV platforms. Chemistry and capacity configurations segment procurement strategies between mass-market standard-range vehicles and premium long-range trucks requiring distinct energy density profiles.
Product Type:
Cost tier differentiation across cell geometries separates premium structural integration from commodity module assembly.
- Prismatic:Rectangular aluminum-cased cells enable direct cell-to-pack mounting with vehicle chassis, eliminating module housings. Michigan and Ohio OEM assembly lines for electric pickups and SUVs are standardizing on prismatic formats to reduce pack weight and assembly steps.
- Cylindrical:Rolled electrode jellyrolls in metal cans sustain the highest volume manufacturing throughput and automated winding speeds. Tesla's Nevada operations and Panasonic's joint venture lines exploit cylindrical formats for cost curve compression in high-output facilities.
- Pouch:Laminated polymer-foil enclosures offer packaging flexibility for hybrid transmission-integrated battery placements. South Korean suppliers dominate pouch cell qualification for Detroit OEM plug-in hybrid programs.
- Scale:Custom oversized formats for commercial vehicle and stationary storage applications. Proterra and Lion Electric bus manufacturing in California and Quebec drives scale-format demand for high-capacity depot charging cycles.
Prismatic holds installed capacity. Cylindrical is rotating up the share rankings.
Capacity:
Application requirements stratify pack sizing across passenger car, light truck, and commercial vehicle duty cycles.
- 10-20 kWh:Compact plug-in hybrid electric vehicle packs balancing electric-only range with engine-assisted cruising. Toyota and Honda procurement in Kentucky and Indiana concentrates in this band for mid-size sedan electrification.
- 21-40 kWh:Standard-range battery electric vehicle configurations using LFP chemistry for urban commuting segments. Ford and GM compact crossover production in Mexico and Tennessee targets this capacity tier for price-sensitive fleet sales.
- 41-60 kWh:Mid-range crossover and small truck packs bridging daily driving needs with occasional highway trips. Volkswagen ID.4 and Hyundai Ioniq 5 assembly in Georgia and Alabama anchors demand in this segment.
- 61-80 kWh:Extended-range configurations for full-size electric pickups and three-row SUVs requiring 300+ mile EPA ratings. Rivian Illinois plant and GM Orion Assembly in Michigan pull high-nickel cell capacity toward this upper band.
61-80 kWh dominates value concentration. 21-40 kWh is climbing the fastest on LFP cost advantages.
End User:
Customer type determines contract structure, residual value terms, and recycling obligation allocation.
- OEMs:Integrated vehicle manufacturers negotiating multi-year cell supply agreements with joint venture partners. Detroit Three and foreign transplant assemblers in Michigan, Tennessee, and Texas represent the dominant procurement volume.
- Fleet Operators:Commercial vehicle purchasers demanding guaranteed uptime and total cost of ownership warranties. Amazon Rivian van deployment and PepsiCo Tesla Semi pilots in California and Nevada establish fleet-specific performance benchmarks.
- Charging Stations:Stationary storage-integrated fast-charging hubs buffering grid demand during peak vehicle charging events. Electrify America and EVgo buffer battery installations across Texas and California interstate corridors.
- Aftermarket Providers:Independent battery replacement and remanufacturing services for out-of-warranty vehicles. Regional service networks in Florida and Arizona specialize in degraded pack diagnostics and module-level refurbishment.
OEMs hold installed capacity. Fleet Operators is rotating up the share rankings.
Technology:
Maturity and supply concentration separate established cathode chemistries from emerging alternatives.
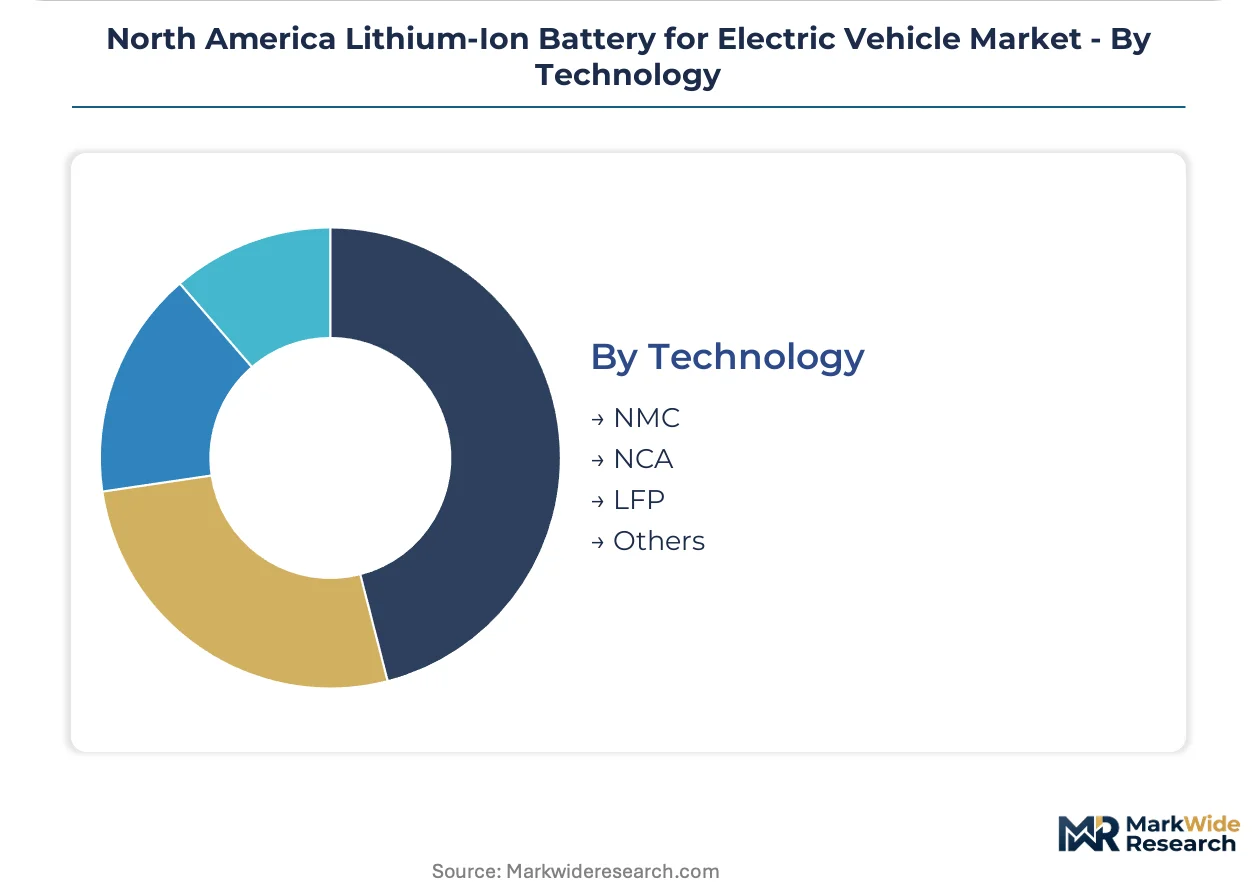
- NMC:Nickel-manganese-cobalt layered oxide cathodes delivering 250-300 Wh/kg energy density for premium long-range applications. High-nickel variants dominate GM Ultium and Ford F-150 Lightning cell specifications from Michigan and Kentucky plants.
- NCA:Nickel-cobalt-aluminum formulations optimizing volumetric energy density for performance sedans. Tesla's cylindrical cell production in Nevada remains the primary North American NCA deployment.
- LFP:Lithium-iron-phosphate chemistry eliminating cobalt content while improving thermal stability and cycle life. BYD and CATL supply agreements with Ford BlueOval SK and Tesla Lathrop facility are expanding LFP share in standard-range vehicles.
- Others:Experimental and low-volume chemistries including sodium-ion, lithium-metal, and solid-state prototypes. US Department of Energy ARPA-E funding supports solid-state research programs at Michigan and Colorado university laboratories.
NMC holds installed capacity. LFP is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North America runs a structural deficit in cathode active materials, importing precursor chemicals while exporting assembled cells and battery packs. This trade asymmetry is narrowing as IRA domestic content rules force upstream manufacturing into the US Midwest and Mexico's northern border states.
United States
Michigan and Ohio anchor cell assembly investments from Detroit Three joint ventures. EPA vehicle emissions standards and NHTSA CAFE regulations mandate escalating zero-emission sales through 2032. The Kentucky-Tennessee corridor hosts cathode precursor refining facilities qualifying for federal tax credits under Treasury Department guidance.
Canada
Ontario's automotive manufacturing belt attracts giga-scale cell plants serving Detroit assembly lines. Federal clean fuel regulations and provincial EV mandates in Quebec and British Columbia drive procurement. The Quebec lithium belt near La Corne supplies spodumene concentrate to regional hydroxide refineries.
Mexico
Baja California and Sonora host electrode coating and module assembly operations accessing USMCA trade benefits. Federal automotive manufacturing incentives and state-level industrial park development attract Korean and Japanese suppliers. The Nuevo León-Coahuila corridor concentrates battery component plants serving Texas OEM assembly.
North America Lithium-Ion Battery for Electric Vehicle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cathode materials, electrolyte salts, and separator films. The market structures around three tiers: captive cell producers owned by vehicle manufacturers, independent cell makers supplying multiple OEMs, and materials suppliers feeding both categories. Competitive moves concentrate on joint venture formation for capacity access and backward integration into precursor refining to secure IRA compliance.
Among integrated platform operators, Tesla exemplifies captive production architecture through Nevada-based cylindrical cell manufacturing. Panasonic Holdings Corporation occupies a hybrid position as both independent supplier and exclusive production partner. LG Energy Solution anchors the multi-OEM supply tier through Michigan and Ohio joint venture structures with domestic automakers.
| Leading Market Players |
|---|
| Tesla |
| Panasonic Holdings Corporation |
| LG Energy Solution |
| Contemporary Amperex Technology Co., Limited (CATL) |
| BYD Company Ltd. |
| Samsung SDI |
| SK Innovation |
| Envision AESC |
| EnerSys |
| Others |
Pricing and Supply Chain Analysis
The Port of Los Angeles-Long Beach freight corridor anchors lithium carbonate and cathode precursor movements from South American salt flats and Australian hard-rock mines into Nevada and Michigan cell plants. Its congestion-driven rate spikes feed directly into NMC cell cost curves while forcing OEM procurement teams to split between long-term offtake premiums and spot-market exposure for standard-range LFP packs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the North America Lithium-Ion Battery for Electric Vehicle Market. Pricing stratifies across premium high-nickel NMC, standard mid-range chemistries, and economy LFP tiers based on cobalt content and UL 2580 certification status. Cost compression in the LFP tier is intensifying because BYD and CATL supply agreements are eroding incumbent margin buffers. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while luxury performance OEMs remain least sensitive due to range-per-kilogram prioritization.
Supply Chain Analysis
US Treasury foreign entity of concern restrictions limit cathode active material flows from Chinese-controlled processing entities into IRA-qualified cell production. North American battery manufacturing draws from concentrated precursor refining in China, South Korea, and Japan, with lithium hydroxide feedstock anchored in Chile and Australia. Single-source vulnerability in lithium hexafluorophosphate electrolyte salts creates chokepoint exposure for Ohio and Michigan giga-factories. Distribution runs through just-in-time rail corridors from Baja California electrode coating facilities to Texas and Tennessee OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Lithium-Ion Battery for Electric Vehicle Market fragments across chemistry-specific procurement silos, as fleet electrification mandates and IRA domestic content rules create specialized supplier tiers that resist consolidation.
For Market Incumbents: Pre-empt LFP chemistry commoditization by locking spodumene concentrate offtake from Quebec's La Corne belt and accelerating dry electrode process R&D to sustain formation cycling throughput advantages. Secure joint venture structures in Mexico's Sonora corridor before USMCA rule-of-origin disputes harden, as Korean challengers are already anchoring electrode coating capacity there.
For New Entrants and Emerging Players: Canada's Quebec and Ontario manufacturing belt offers underpenetrated cathode precursor refining capacity with hydroelectric power cost advantages and proximity to Detroit Three assembly lines. Target second-life stationary storage aggregation services for retired commercial vehicle packs, where Electrify America and independent grid operators lack qualified suppliers. Pursue direct OEM qualification partnerships rather than module-tier subcontracting to escape margin compression.
For Investors and Strategic Acquirers: Specialist dry electrode coating equipment manufacturers with captive process IP represent the most defensible acquisition archetype as cell makers scramble to reduce formation cycling bottlenecks. Long-term viability hinges on IRA compliance durability through potential administrative transitions. Watch Treasury Department guidance on foreign entity of concern waivers as the critical inflection signal for joint venture restructuring valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Joint Venture | LG Energy Solution's Ohio partnership with GM secures IRA tax credit eligibility for Ultium platform cells. |
| Dry Electrode Process Scale-Up | Tesla's Nevada pilot line reduces formation cycling time and capital intensity per gigawatt-hour of output. |
| Mexico Nearshoring Footprint | Panasonic's Baja California expansion accesses USMCA benefits while hedging against US labor cost inflation. |
| Second-Life Storage Aggregation | Rivian's grid-buffer pilot with California utilities creates circular revenue streams from degraded Illinois-built packs. |
| Solid-State Interface R&D Partnership | US Department of Energy ARPA-E funding at Michigan laboratories advances silicon nanowire anode commercialization pathways. |
Research Methodology
Initial hypotheses were tested against primary input from cell plant engineering directors, OEM platform procurement managers, cathode materials R&D leads, and fleet electrification officers, then refined through secondary validation against SEC 10-K filings, US Customs and Border Protection trade data, EPA vehicle emissions compliance disclosures, and IHS Markit production databases. Bottom-up capacity buildouts across Michigan, Ohio, Tennessee, and Nevada facilities were triangulated against top-down OEM electrification commitment aggregations.
Demand-supply balance modeling across the projection horizon segmented by cell format, cathode chemistry, capacity tier, end-user archetype, and regional production cluster. CAGRs were derived from installed capacity ramp schedules, IRA domestic content compliance trajectories, and EPA zero-emission sales mandate stringency curves. Forecast inputs incorporated lithium carbonate spot price volatility bands and NHTSA battery safety protocol revision timelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting project finance terms for giga-scale plants or cobalt price shocks from DRC supply disruptions would shift the trajectory. Forecasts reflect documented assumptions around Treasury Department guidance continuity and USMCA trade framework stability. Material shifts in foreign entity of concern rule enforcement or solid-state cell commercialization breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
EV All-Solid-State Battery Market